
 Drive Mode Selector Switch and Controller Systems Market | 2026-2036
Drive Mode Selector Switch and Controller Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Drive Mode Selector Switch and Controller Systems Market Insights
A widening capital-intensity gap between integrated system suppliers and component specialists is reorganizing competitive tiers in the drive mode selector ecosystem. Robert Bosch leverages its in-house semiconductor capabilities to control electronic controller architectures from sensor to software. Denso anchors its position through deep manufacturing scale in electro-mechanical assemblies across Japanese and North American production networks. Continental differentiates by specializing in capacitive and Hall-effect touch interfaces for premium electric vehicle programs.
Drive mode selector switch and controller systems encompass human-machine interface modules that translate driver inputs into electronic signals managing powertrain calibration, suspension stiffness, and steering response, typically operating across temperature ranges of minus 40 to 85 degrees Celsius and requiring IP67 ingress protection for cabin and underhood mounting. The rotary switch category occupies the largest installed base in internal combustion and hybrid vehicle platforms where tactile feedback remains a design priority. Electronic technology segments are capturing the fastest expansion as OEMs eliminate mechanical linkages in favor of software-defined drive modes with over-the-air update capability. The electric vehicle application channel is concentrating margin pools due to higher per-unit controller complexity and integration with battery thermal management systems.
The EPA's corporate average fuel economy standards and NHTSA safety regulations in the United States, alongside the EU's CE marking and MDR-adjacent electromagnetic compatibility frameworks, are mandating stricter validation protocols for automotive switchgear reliability and fail-safe operation. Japan's METI energy efficiency directives and China's MIIT new energy vehicle technical standards are accelerating replacement of mechanical selectors with sealed electronic controllers across domestic production. Stakeholders must monitor how software-defined vehicle architectures reshape hardware procurement specifications and whether Tier-1 suppliers retain interface design authority or cede ground to platform-integrated cockpit domain controllers.
Market Dynamics
Software-defined vehicle architectures are compressing hardware procurement cycles as OEMs consolidate cockpit domain controllers and eliminate discrete switch modules from bill-of-materials specifications.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for hydrofluorocarbons are forcing thermal management redesigns that integrate drive mode controllers with battery cooling circuits.
- Capacitive touch interfaces:Hall-effect and projected capacitance technologies are capturing design wins in premium electric vehicle programs where haptic feedback and gesture recognition command price premiums.
- Electrification mandates in China:MIIT new energy vehicle technical standards are accelerating factory retooling toward sealed electronic controllers and away from mechanical rotary selectors.
Market Restraints
- Semiconductor supply concentration:Dependence on Taiwanese and South Korean foundries for automotive-grade microcontrollers creates vulnerability to geopolitical disruption and allocation constraints.
- Copper and rare earth input costs:Permanent magnet materials for Hall-effect sensors and copper wiring for harness integration face price volatility from mining concentration in Chile and the Democratic Republic of Congo.
- IP67 sealing complexity:Achieving ingress protection for underhood mounting while maintaining tactile response requires specialized gasket materials that extend qualification timelines.
Strategic Opportunities
- Aftermarket retrofit channels:Independent service networks in Germany and Japan are developing controller upgrade kits for legacy internal combustion platforms seeking drive mode customization.
- Over-the-air capability convergence:Integration of drive mode calibration with telematics platforms enables subscription-based feature activation and recurring revenue streams.
- India PLI scheme:Production-linked incentives for automotive electronics manufacturing are attracting component suppliers to establish local assembly for domestic and export-bound electric two-wheelers.
Industry Challenges
- Embedded software talent scarcity:Functional safety engineering for ISO 26262 ASIL compliance requires specialized expertise that competes with autonomous driving and battery management system development.
- Electromagnetic compatibility certification:CE marking and FCC Part 15 validation for capacitive interfaces demands anechoic chamber testing that extends product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drive Mode Selector Switch and Controller Systems Market |
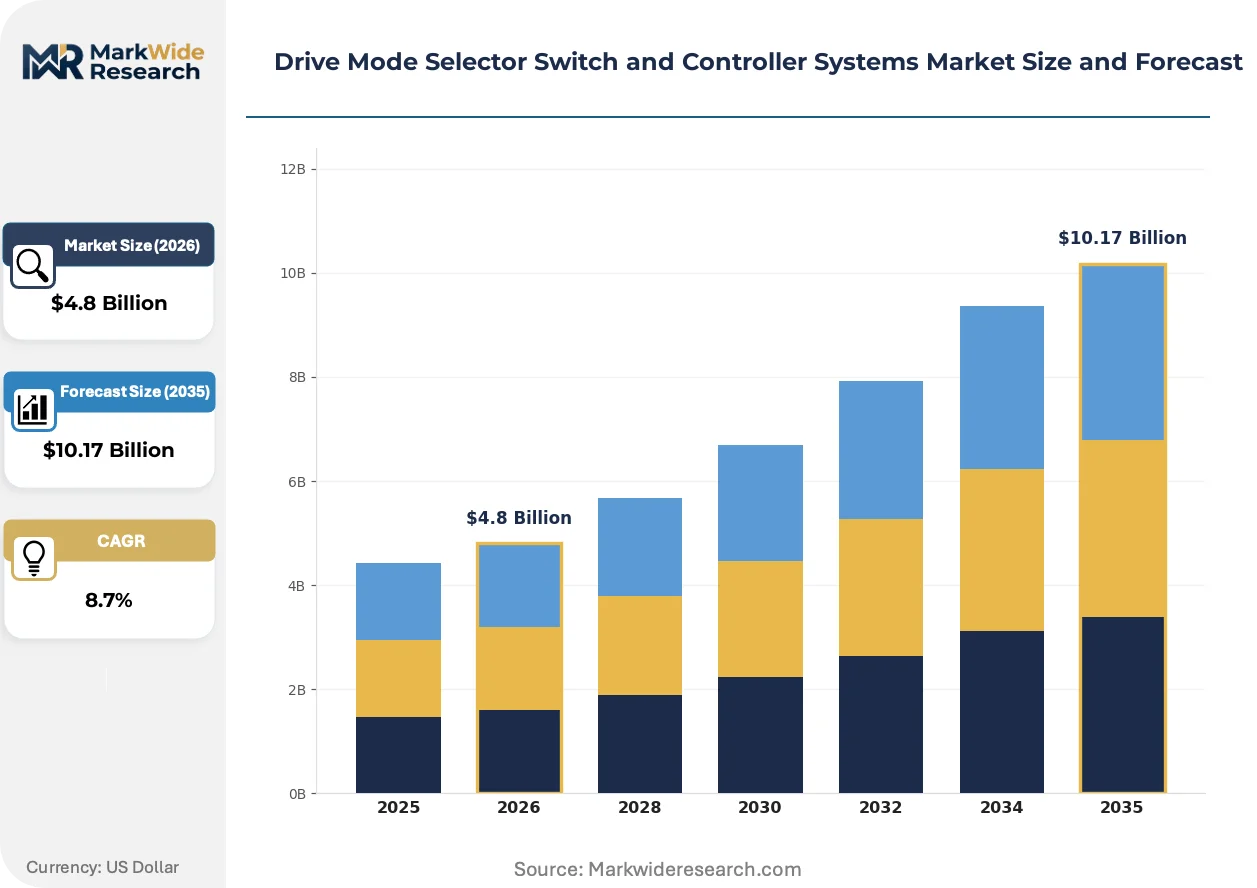
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Switch, Push Button Switch, Toggle Switch, Touchscreen Panel Technology: Mechanical, Electro-Mechanical, Electronic, Capacitive, Hall Effect Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Off-Road Equipment End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | ZF Friedrichshafen, Denso, Valeo, Robert Bosch, Continental, Tokai Rika, Alps Alpine, Hyundai Mobis, Panasonic Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drive Mode Selector Switch and Controller Systems Market Trends and Innovations
Human-machine interface technologies are migrating from tactile mechanical feedback toward software-configurable surfaces that adapt to context and driver preference without physical redesign.
Solid-state capacitive touch panels are supplanting rotary mechanical switches in volume electric vehicle programs. BMW and Mercedes-Benz have specified full-surface capacitive consoles for 2025 model year platforms. This transition is compressing supplier margins on electro-mechanical components while expanding software licensing revenue pools.
Japan's METI energy efficiency directives are mandating standby power consumption limits for electronic controllers that force semiconductor redesigns. Tier-1 suppliers must qualify new low-power microcontroller architectures. Domestic production networks are prioritizing Renesas and Renesas-partnered foundry capacity to meet compliance deadlines.
Fleet procurement departments are consolidating switch and controller specifications across multiple vehicle nameplates to capture volume pricing. General Motors and Stellantis have issued common technical standards for drive mode interfaces. North American supplier relationships are restructuring around platform-level contracts rather than program-specific awards.
Drive Mode Selector Switch and Controller Systems Market Segmentation
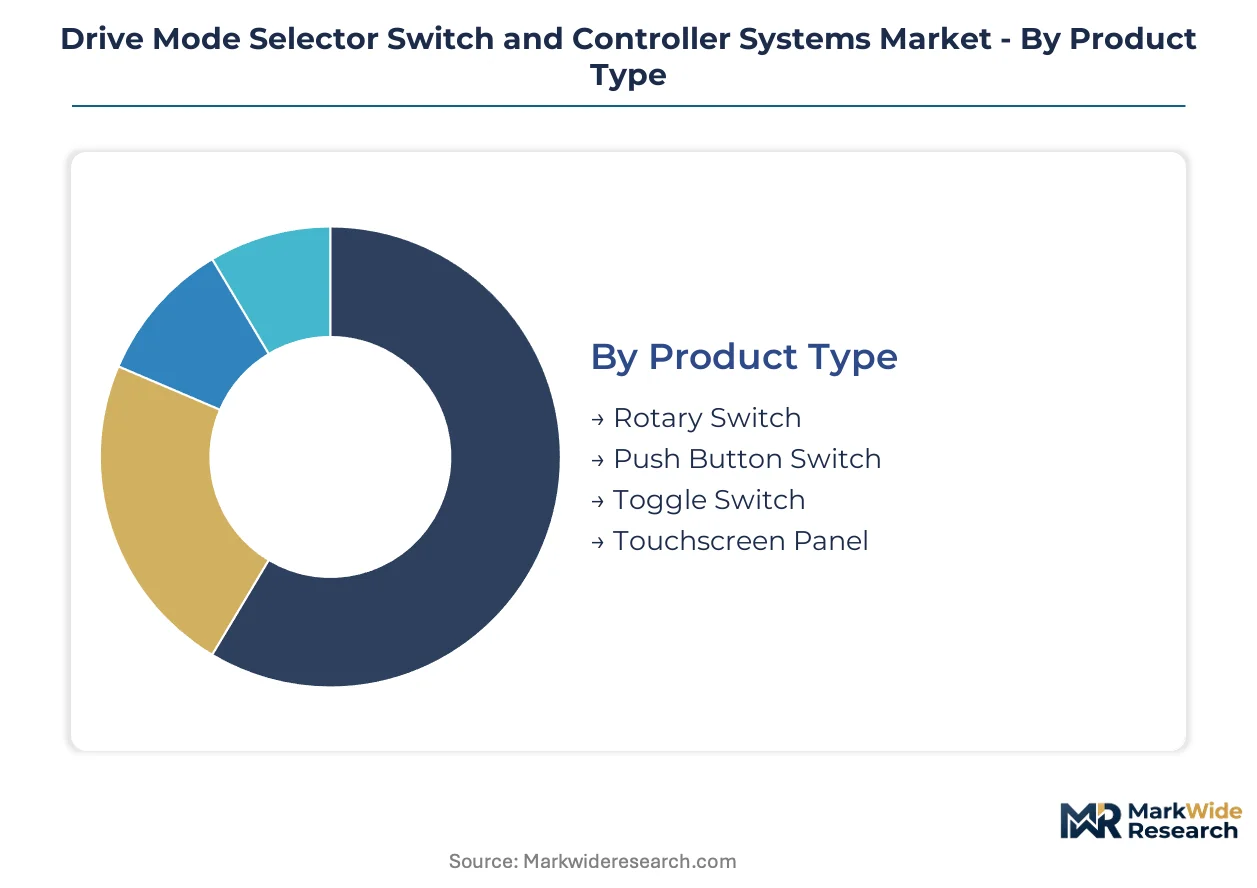
Drive mode selector architectures fragment across interface technologies, powertrain applications, and procurement channels. Each segment carries distinct certification burdens and margin structures that reshape supplier positioning.
Product Type:
Regulatory differentiation in ingress protection and electromagnetic compatibility standards separates cabin-mounted from underhood applications across switch categories.
- Rotary Switch:Mechanical detent mechanisms provide tactile feedback through indexed positions for sport, comfort, and eco calibrations. Demand concentrates in German and Japanese hybrid platforms where drivers prioritize physical feedback; the EU's F-Gas Regulation drives integration with thermal management controls.
- Push Button Switch:Momentary-contact designs enable mode toggling with LED status indication and require IP67 sealing for center console mounting. Fleets in North America specify these for commercial vehicle commonality programs; NHTSA safety regulations mandate fail-safe latching logic.
- Toggle Switch:Bistable lever mechanisms suit industrial off-road equipment with glove-operated interfaces.
- Touchscreen Panel:Full-surface capacitive arrays enable software-defined mode layouts without hardware redesign.
Rotary switch handles the majority of throughput; touchscreen panel is the fastest mover on share.
Technology:
Cost tier stratification separates commodity mechanical solutions from premium electronic architectures with over-the-air update capability.
- Mechanical:Cam-actuated contact systems operate without semiconductor dependency in legacy internal combustion platforms. Production concentrates in Chinese supply bases serving domestic commercial vehicle manufacturers; MIIT new energy vehicle standards are accelerating displacement.
- Electronic:Microcontroller-based architectures translate driver inputs through CAN bus to powertrain control modules with diagnostic feedback. German premium OEMs specify these for electric vehicle programs; ISO 26262 ASIL compliance extends development timelines.
- Electro-Mechanical:Hybrid designs combine tactile feedback with electronic signal generation for mid-range passenger vehicles.
- Capacitive:Projected field sensors enable gesture recognition and haptic feedback through piezoelectric actuators.
- Hall Effect:Magnetic position sensing eliminates mechanical wear in rotary implementations with non-contact operation.
Electronic technology commands the dominant revenue pool; capacitive interfaces are expanding most quickly in premium applications.
Application:
Customer type divergence separates fleet procurement standardization from retail consumer preference for configurable interfaces.
- Electric Vehicles:Battery thermal management integration requires drive mode controllers to coordinate cooling circuit valves and pump speeds. Demand clusters in China and Germany where electrification mandates are tightest; per-unit controller complexity sustains margin premiums.
- Passenger Vehicles:Rotary and push-button interfaces dominate internal combustion and hybrid platforms with established HMI conventions. Japanese and South Korean OEMs specify common switchgear across nameplates; METI energy efficiency directives enforce standby power limits.
- Commercial Vehicles:Fleet-specified durability requirements prioritize sealed electro-mechanical designs with million-cycle ratings.
- Off-Road Equipment:Vibration-resistant enclosures and sealed connectors address construction and agricultural duty cycles.
Passenger vehicles handle the majority of throughput; electric vehicles are climbing the fastest on revenue contribution.
End User:
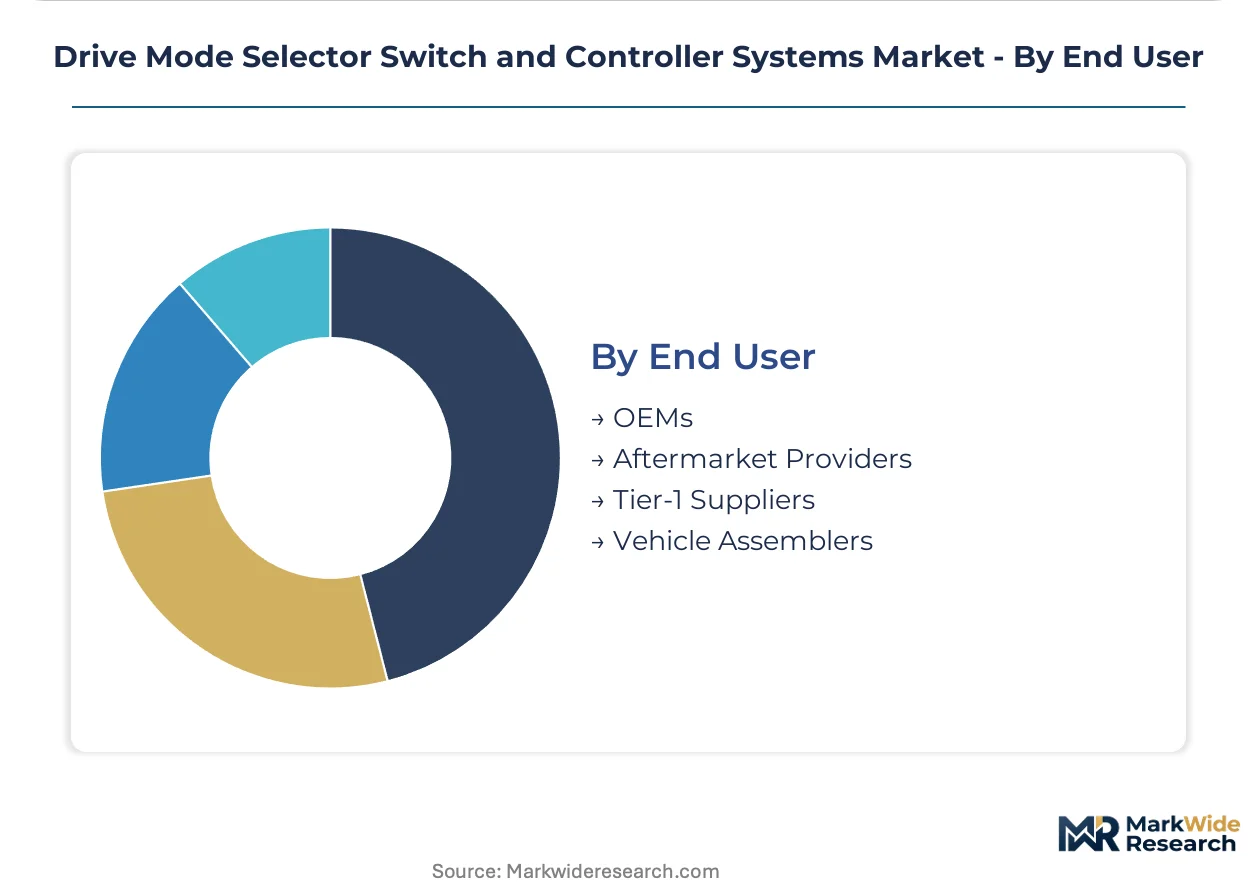
Supply concentration dynamics favor integrated system suppliers over component specialists as cockpit domain consolidation advances.
- OEMs:In-house controller development teams at BMW and Mercedes-Benz specify full-surface capacitive consoles with proprietary software stacks. Vertical integration into semiconductor sourcing is reshaping procurement relationships; Renesas and Infineon foundry allocations are contested.
- Tier-1 Suppliers:Bosch, Denso, and Continental supply integrated switch-controller modules with validation responsibility. German and Japanese production networks dominate capacity; electromagnetic compatibility certification extends qualification schedules.
- Aftermarket Providers:Independent service networks in Germany and Japan develop retrofit kits for legacy platform customization.
- Vehicle Assemblers:Contract manufacturers rely on specified supplier lists for interface module integration.
Tier-1 suppliers handle the majority of throughput; OEM captive development is gaining share fastest in premium electric vehicle programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and Germany show the least price sensitivity for premium capacitive interfaces, while fleet operators in North America and commercial vehicle assemblers in India drive hard negotiations on electro-mechanical rotary switches. This elasticity divergence is reorganizing supplier investment priorities across production networks.
China
Domestic electric vehicle OEMs are specifying sealed electronic controllers with battery thermal management integration at volumes exceeding European and Japanese markets combined. MIIT new energy vehicle technical standards mandate standby power limits and electromagnetic compatibility validation that disqualify legacy mechanical suppliers. Production concentrates in Shanghai and Shenzhen where BYD and NIO anchor Tier-1 supplier clusters for export-bound and domestic platforms.
Germany
Premium OEMs in Stuttgart and Munich are procuring full-surface capacitive consoles with proprietary software stacks, commanding per-unit prices triple those of rotary switch implementations. The EU's F-Gas Regulation forces thermal management redesigns that integrate drive mode controllers with battery cooling circuits. Supplier engineering centers in Baden-Württemberg coordinate validation with KBA type-approval protocols for CE marking compliance.
Japan
Hybrid platform demand sustains rotary switch volumes even as METI energy efficiency directives accelerate sealed electronic controller adoption across domestic production. Toyota and Honda specify common switchgear architectures across nameplates to capture manufacturing scale. Nagoya-based production networks prioritize Renesas microcontroller allocations to meet standby power compliance deadlines for 2025 model year programs.
United States
Fleet procurement departments at General Motors and Stellantis are consolidating switch specifications across multiple nameplates to extract volume pricing from Tier-1 suppliers. NHTSA safety regulations mandate fail-safe latching logic for push-button interfaces in commercial vehicle applications. Engineering activity concentrates in Michigan and California where cockpit domain controller development teams are absorbing discrete switch module functions.
India
Electric two-wheeler assemblers represent the fastest-expanding demand channel as the PLI scheme for automotive electronics manufacturing attracts component suppliers to local assembly. Domestic commercial vehicle manufacturers specify sealed electro-mechanical designs with million-cycle ratings for dust-intensive operating environments. Production gravity is shifting to Tamil Nadu and Gujarat where export-oriented supplier parks serve Southeast Asian and Middle Eastern markets.
Drive Mode Selector Switch and Controller Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated system suppliers commanding premium pricing for software-defined architectures while component specialists compete on electro-mechanical scale. The vendor base separates into three tiers: semiconductor-capable integrators with in-house controller development, manufacturing-scale electro-mechanical assemblers, and interface technology specialists focused on capacitive and Hall-effect sensing. Dominant competitive moves include backward integration into semiconductor sourcing and geographic expansion into India via PLI-scheme manufacturing partnerships.
Among the integrated system suppliers, Robert Bosch exemplifies the semiconductor-capable archetype with control over electronic controller architectures from sensor to software. Denso anchors the manufacturing-scale tier through deep production networks across Japanese and North American facilities. Continental occupies a position within the interface technology specialist tier, differentiated by capacitive and Hall-effect touch capabilities for premium electric vehicle programs. These three players represent contrasting strategic positions within a market reorganizing around software-defined vehicle architectures and cockpit domain consolidation.
| Leading Market Players |
|---|
| ZF Friedrichshafen |
| Denso |
| Valeo |
| Robert Bosch |
| Continental |
| Tokai Rika |
| Alps Alpine |
| Hyundai Mobis |
| Panasonic Automotive |
| Others |
Pricing and Supply Chain Analysis
Ninety-day microcontroller lead times from Taiwanese foundries simultaneously constrain Tier-1 supplier output and inflate electronic controller premiums, concentrating pricing power with semiconductor-capable integrators while squeezing electro-mechanical specialists. This inventory compression reinforces the capital-intensity gap between integrated system suppliers and component specialists, as OEMs prioritize suppliers with captive semiconductor access over those exposed to allocation volatility.
Pricing Analysis
After-sales service revenue from over-the-air calibration updates and subscription-based feature activation now drives lifetime value for electronic controller architectures. Three-tier pricing structure across premium capacitive interfaces, standard electro-mechanical modules, and economy rotary switches reflects certification grade differentiation, with ISO 26262 ASIL compliance commanding substantial premiums. Pricing pressure stems from fleet procurement consolidation at General Motors and Stellantis, which extracts volume discounts through platform-level contracts. Fleet operators in North America exhibit the highest price sensitivity, while German premium OEMs show minimal elasticity for full-surface capacitive consoles with proprietary software stacks.
Supply Chain Analysis
Inventory concentration in Shanghai and Shenzhen supplier parks feeds from Taiwanese and South Korean semiconductor foundries, German precision stamping equipment, and Japanese microcontroller fabrication. Copper wiring harnesses, permanent magnet materials for Hall-effect sensors, and specialized IP67 gasket compounds constitute critical input dependencies. Single-source vulnerability around automotive-grade microcontrollers creates exposure to geopolitical disruption and foundry allocation constraints. Distribution runs through Tier-1 supplier engineering centers in Baden-Württemberg, Nagoya, and Michigan that coordinate validation with OEM platform teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined vehicle architectures represent a high-growth disruption as cockpit domain consolidation eliminates discrete switch modules and redirects procurement toward integrated controller platforms. The EU's F-Gas Regulation and MIIT new energy vehicle standards constitute the regulatory inflection forcing thermal management redesigns and sealed electronic controller adoption.
For Market Incumbents: Secure Renesas and Infineon foundry allocations through long-term supply agreements to defend against semiconductor-capable competitors with in-house fabrication. Invest in ISO 26262 ASIL certification infrastructure to maintain validation authority as OEMs consolidate procurement around platform-level contracts. Capacity expansion in Tamil Nadu and Gujarat captures PLI-scheme incentives for electric two-wheeler controller assembly. For New Entrants and Emerging Players: CE marking fast-track through German KBA type-approval protocols enables entry into premium electric vehicle programs where capacitive interface demand outstrips established supplier capacity. Target India's electric two-wheeler aftermarket, where domestic assemblers lack sealed electronic controller expertise and rely on specified supplier lists. Develop retrofit upgrade kits for legacy internal combustion platforms in Germany and Japan as an initial go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized automotive electronics divisions lacking software-defined vehicle capabilities. The five-to-ten year viability window favors acquisitions of interface technology specialists with Hall-effect and capacitive sensing IP, as these capabilities become essential for premium electric vehicle programs. Monitor Renesas microcontroller allocation announcements as an inflection indicator for supplier competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Supply Agreement | Long-term foundry allocations with TSMC or Samsung secure automotive-grade microcontroller access for Tier-1 suppliers. |
| Platform Standardization | Common technical standards across multiple nameplates enable General Motors and Stellantis to extract volume pricing. |
| Software-Defined Vehicle Investment | Integration of drive mode calibration with telematics platforms enables subscription-based recurring revenue streams. |
| Geographic Manufacturing Footprint | PLI-scheme assembly in Tamil Nadu and Gujarat serves domestic Indian demand and Southeast Asian export markets. |
| Battery Thermal Management Partnership | Coordination with battery cooling circuit valve suppliers meets EU F-Gas Regulation phase-down compliance requirements. |
Research Methodology
A spread of perspectives from Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and semiconductor foundry account managers converged on the working assumptions underlying demand projections. Primary interviews with cockpit domain controller development teams in Michigan and California were cross-referenced with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and MIIT new energy vehicle technical standard disclosures. Bottom-up unit demand estimates were triangulated against top-down OEM procurement budget allocations.
Segmentation dimensions modeled include interface technology type, propulsion architecture, content per vehicle tier, and regional production cluster concentration. Volume and value outputs were derived through driver-based modeling across the projection horizon, with CAGRs calculated from year-over-year growth rate progression rather than endpoint fitting. Industry-specific forecast inputs incorporated electrification mandate timelines from the EU, China, and Japan, alongside semiconductor allocation constraints from Taiwanese and South Korean foundries.
Decision-makers should treat outputs as directional under assumptions of continued electrification mandate enforcement and stable semiconductor supply; material deviation in regulatory timelines or foundry capacity expansion would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
North America Switchgear Market
Switches
Global Smart Switch Panel Market
Switches
KVM Switch Market
Switches
Global Light Control Switches Market
Switches
Power Load Switches Market
Switches
Argentina Automotive Reed Sensors Switches Market
Switches
Contactor-based Transfer Switch Market
Switches
Touchpad Market
Switches
Smart Dimmer Switch Market
Switches
In-Wall Smart Switch Market
Switches
Transfer Switch Market
Switches
Pressure Switch Market
Switches
Global Switchgear Market
Switches
Solid State Relay Market
Switches
Zero Speed Switch Market
Switches
Rotary Limit Switches Market