
 Personal Care Ingredients Market | 2026-2036
Personal Care Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Care Ingredients Market Intelligence
ISO 16128 certification for natural and organic cosmetic ingredients is rotating supplier eligibility across the value chain. BASF SE leverages its integrated biotechnology platforms to sustain leadership in fermented active ingredients. Croda International Plc anchors its position through lipid specialty chemistry for premium skin care applications. Evonik Industries AG competes via silicone-free emollient technologies targeting clean-label brand requirements.
Personal care ingredients comprise functional and aesthetic raw materials—surfactants, emollients, humectants, preservatives, and fragrances—formulated at precise active concentrations to deliver cleansing, moisturizing, barrier protection, or sensory performance in finished consumer products. Surfactants dominate volume flows due to their ubiquity across rinse-off applications, while preservative systems face structural pressure from clean-label substitution trends. Emollients and humectants capture expanding margin pools as skin care brands prioritize barrier-repair and hydration-positioned formulations.
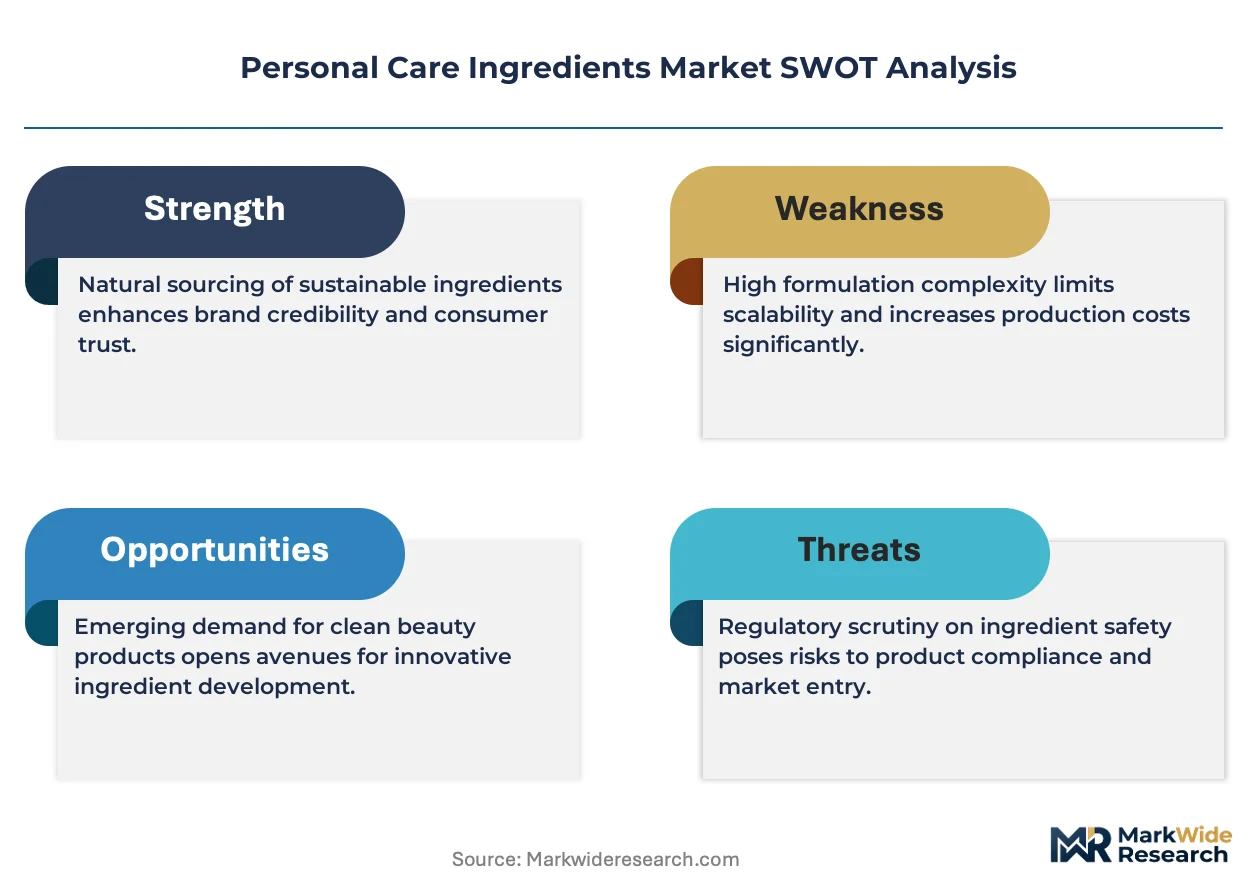
EU REACH restrictions and the FDA's color additive regulations jointly constrain permissible chemistries and documentation burdens for market entry. ECHA's ongoing microplastic restriction proposals threaten conventional exfoliant and film-forming ingredient categories. Stakeholders must monitor regulatory divergence between Brussels and Washington to anticipate reformulation mandates before compliance deadlines crystallize.
Market Dynamics
Clean-label substitution is decomposing conventional preservative systems across rinse-off and leave-on formulations, forcing suppliers to rebuild efficacy portfolios around biotech-derived actives and fermentation-based alternatives.
Growth Catalysts
- EU REACH Annex V revisions:Tightening permissible preservative chemistries accelerates demand for phenoxyethanol-free and MIT-free alternatives in skin care formulations.
- Biotechnology platforms:Fermented active ingredients derived from bacterial and yeast cultures deliver standardized bioactive concentrations with reduced batch-to-batch variation.
- Southeast Asia procurement concentration:Malaysia and Indonesia anchor surfactant and emollient volume flows through integrated oleochemical complexes serving regional contract manufacturers.
Market Restraints
- Palm oil and coconut oil price volatility:Feedstock cost swings for fatty alcohols and esters compress emollient margins unpredictably.
- Chinese surfactant supply concentration:Sodium laureth sulfate and cocamidopropyl betaine production clusters in Jiangsu and Zhejiang provinces create single-source vulnerability.
- Preservative efficacy gaps:Clean-label alternatives demonstrate shorter shelf-life stability versus parabens and formaldehyde releasers in challenge testing.
Strategic Opportunities
- India personal care manufacturing expansion:PLI scheme incentives for specialty chemicals attract ingredient suppliers to Gujarat and Maharashtra industrial corridors.
- Microbiome-targeted actives:Prebiotic oligosaccharides and postbiotic lysates open positioning in barrier-repair and sensitive-skin segments.
- Direct-to-brand digital platforms:Alibaba 1688 and specialty chemical marketplaces disintermediate traditional distributor networks for mid-scale formulators.
Industry Challenges
- ISO 16128 certification timelines:Natural origin index calculations and supplier documentation requirements extend qualification cycles by 8-14 months.
- Multifunctional ingredient integration:Combining emollient, humectant, and preservative functions in single molecules demands reformulation of legacy stability protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Care Ingredients Market |
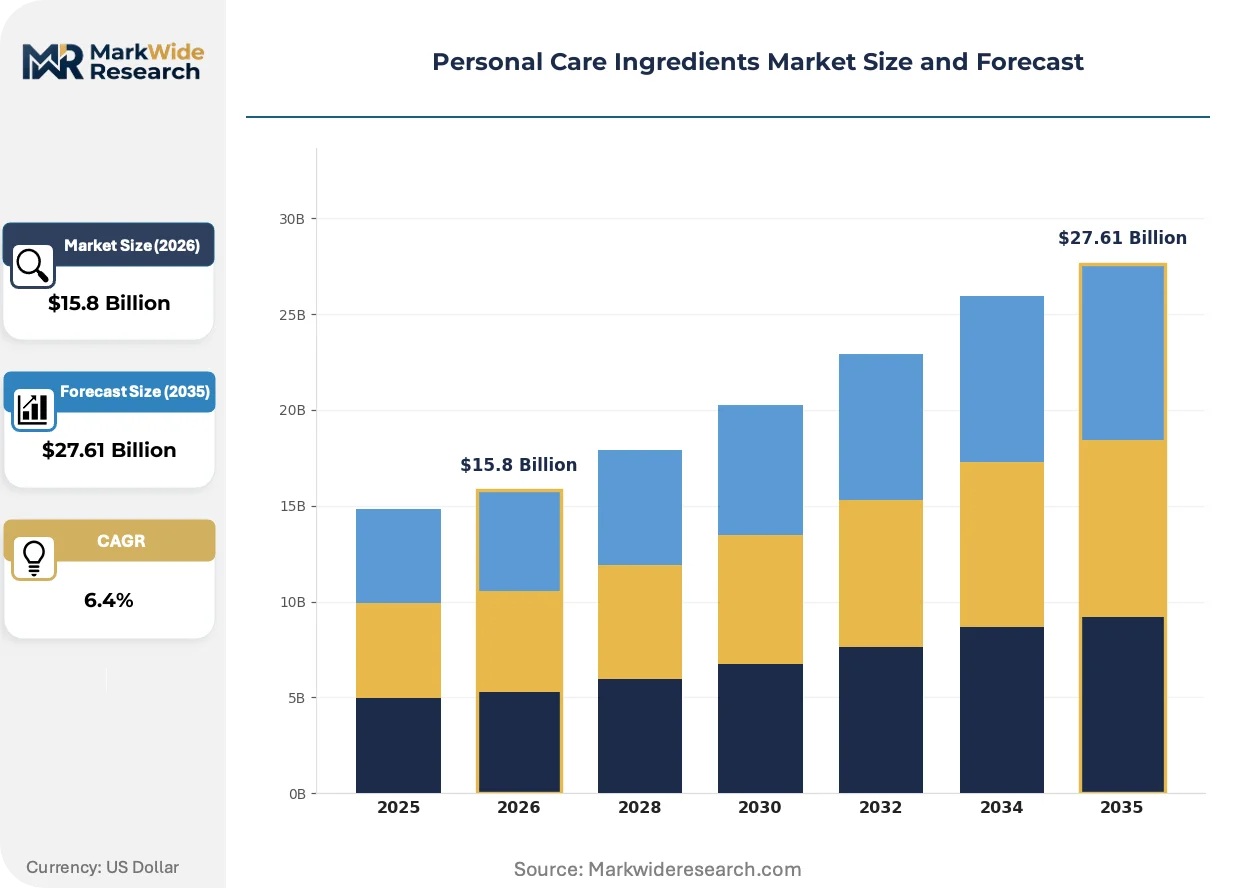
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $27.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emollients, Surfactants, Humectants, Preservatives, Thickeners, Fragrances Application: Skin Care, Hair Care, Oral Care, Sun Care, Color Cosmetics, Bath & Shower End User: Personal Grooming Brands, Dermatology Clinics, Spa Centers, Beauty Salons Form: Powder, Liquid, Paste, Gel, Emulsion, Flakes |
| Companies Covered | Dow Inc., Solvay S.A., BASF SE, Ashland Global Holdings, Givaudan, Croda International Plc, Clariant AG, DSM Firmenich AG, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Care Ingredients Market Strategic Shifts & Innovations
Biotechnology-derived actives, regulatory-driven chemistry restrictions, and procurement model digitization are simultaneously reshaping supplier R&D priorities, compliance roadmaps, and customer acquisition channels across the value chain.
Enzymatic synthesis of cosmetic peptides is decomposing traditional solid-phase synthesis economics. Premium skin care brands in South Korea and France adopt these bioengineered actives for collagen-signaling and wrinkle-reduction claims. The technology is compressing unit costs for tripeptide-1 and copper peptide complexes while enabling custom sequence development for private-label differentiation.
REACH microplastic restriction proposals from ECHA are forcing exfoliant reformulation across the European Union. Synthetic polymer beads in facial scrubs and body washes face phase-out timelines, redirecting R&D spend toward cellulose, jojoba ester, and mineral alternatives. German and French formulators lead substitution adoption, with compliance deadlines accelerating inventory destocking of legacy ingredients.
Ingredient procurement through digital marketplaces and API-connected supplier platforms is fragmenting traditional distributor relationships. Southeast Asian contract manufacturers and indie beauty brands in Brazil bypass regional distributors to source directly from specialty chemical producers. Procurement teams leverage real-time pricing data and certificate-of-analysis verification tools, compressing supplier qualification from months to weeks in high-velocity segments.
Personal Care Ingredients Market Segmentation
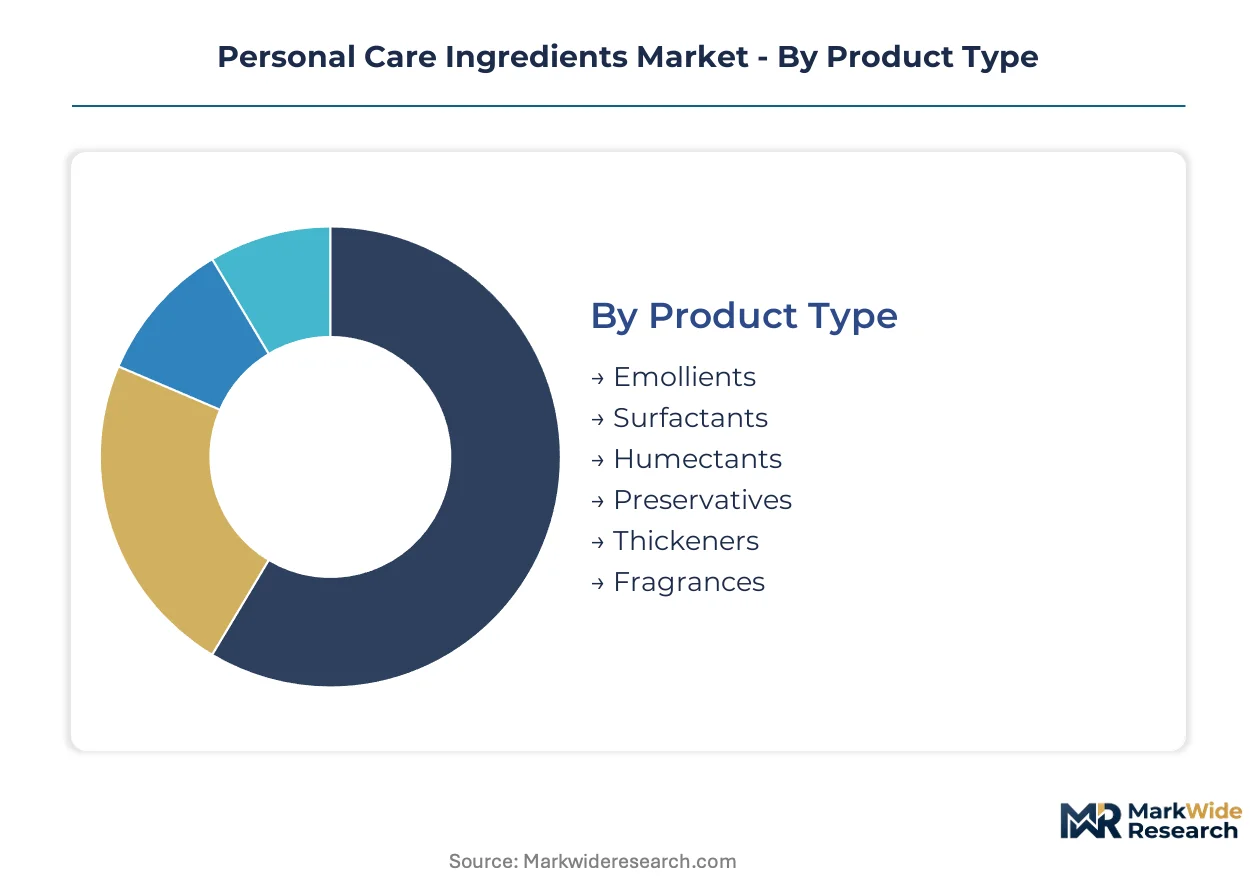
Ingredient segmentation in personal care reflects divergent regulatory thresholds across formulation types. REACH Annex V restrictions on preservatives and ECHA microplastic proposals reshape category prioritization for suppliers and brand formulators alike.
Product Type:
REACH compliance timelines and clean-label substitution pressures differentiate ingredient viability across functional categories.
- Emollients:Lipid-based barrier agents including fatty alcohols, esters, and vegetable oils deliver skin conditioning and occlusion. Demand clusters in premium skin care lines from French and South Korean brands seeking silicone-free alternatives under ECHA scrutiny.
- Surfactants:Surface-active agents reduce interfacial tension for cleansing and foaming performance. Sodium laureth sulfate and cocamidopropyl betaine volume flows concentrate in Jiangsu and Zhejiang province manufacturing clusters, exposing procurement to single-source risk.
- Humectants:Hygroscopic molecules including glycerin and sodium hyaluronate attract and retain moisture.
- Preservatives:Antimicrobial systems prevent microbial contamination in water-based formulations.
- Thickeners:Rheology modifiers control viscosity and texture across emulsion and gel formats.
- Fragrances:Aromatic compounds and essential oil blends deliver olfactory differentiation and sensory positioning.
Surfactants handle the majority of throughput; emollients are gaining share fastest as barrier-repair claims proliferate.
Application:
Formulation complexity and regulatory documentation burdens vary sharply by finished product category.
- Skin Care:Facial and body products demand multifunctional actives with documented safety profiles. EU REACH restrictions on phenoxyethanol and MIT drive reformulation toward biotech-derived preservation in German and French markets.
- Hair Care:Shampoos and conditioners require surfactant systems balancing mildness with foaming performance. Southeast Asian contract manufacturers in Malaysia and Indonesia anchor procurement volume for sulfate-free alternatives.
- Oral Care:Toothpastes and mouthwashes impose strict FDA and national pharmaceutical regulator safety thresholds.
- Sun Care:UV filter combinations face photostability testing and reef-safe positioning requirements.
- Color Cosmetics:Pigments and film-formers encounter FDA color additive regulations and microplastic substitution mandates.
- Bath & Shower:Rinse-off formulations prioritize cost-efficient surfactant systems with minimal residue.
Skin Care commands the deepest ingredient portfolios; Sun Care is expanding most quickly on regulatory-driven filter innovation.
End User:
Channel-specific documentation and certification requirements segment procurement behavior.
- Personal Grooming Brands:Mass and premium consumer product companies drive volume through contract manufacturers. ISO 16128 natural origin certification requirements from European retailers extend supplier qualification cycles.
- Dermatology Clinics:Medical-aesthetic channels demand clinical validation and hypoallergenic documentation.
- Spa Centers:Wellness-focused establishments prioritize aromatherapy positioning and natural ingredient narratives.
- Beauty Salons:Professional hair and nail services require bulk formats with rapid throughput economics.
Personal Grooming Brands absorb the dominant procurement volume; Dermatology Clinics are climbing the fastest on medical-grade ingredient premiums.
Form:
Physical state determines handling infrastructure, stability protocols, and formulation integration methods.
- Liquid:Pumpable concentrates and aqueous solutions enable automated dosing in continuous manufacturing. Surfactant and emollient bulk shipments from Indonesian oleochemical complexes favor liquid formats for regional distribution efficiency.
- Powder:Dry particulates including thickeners and active extracts require dust control and solubility management.
- Paste:Semi-solid concentrates deliver high active loading with minimal water content.
- Gel:Cross-linked polymer networks provide suspension and controlled release properties.
- Emulsion:Oil-in-water or water-in-oil dispersions combine immiscible phases for dual-function delivery.
- Flakes:Solid surfactant and fatty alcohol formats reduce shipping weight and enable on-site dilution.
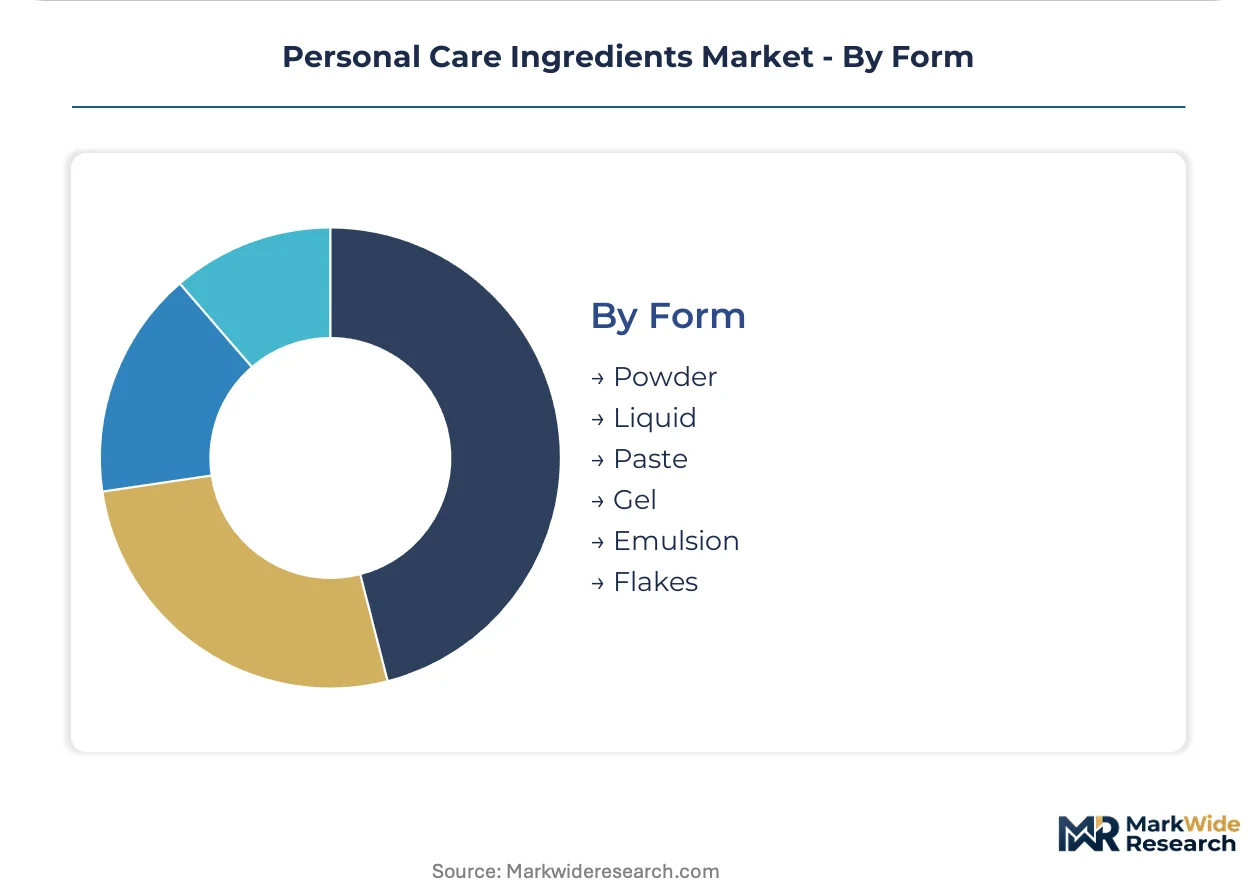
Liquid dominates manufacturing throughput; Powder is advancing fastest on waterless formulation trends and concentrated shipping economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mass-market formulators and premium skin care houses concentrate procurement decisions across four distinct demand basins, each shaped by divergent regulatory calendars and oleochemical feedstock access.
United States
Clean-label brand proliferation and indie beauty startup density drive specialty ingredient pull. FDA color additive regulations and state-level microplastic legislation in California constrain exfoliant chemistries. New Jersey and Texas chemical manufacturing corridors host preservative and emollient blending operations serving North American contract manufacturers.
Germany
Medical-aesthetic channel expansion and pharmacy-distributed skin care lines demand clinical-grade documentation. ECHA REACH Annex V revisions on isothiazolinone preservatives accelerate phenoxyethanol-free reformulation mandates. Ludwigshafen and Marl industrial complexes anchor fermentation-derived active ingredient production for European premium brands.
China
Domestic beauty brand premiumization and cross-border e-commerce export manufacturing expand surfactant throughput. NMPA cosmetic ingredient registration requirements and GB standards for preservatives extend new substance approval timelines. Jiangsu and Zhejiang province manufacturing clusters concentrate sodium laureth sulfate and cocamidopropyl betaine capacity, creating single-source procurement vulnerability.
India
Contract manufacturing export growth and domestic mass-market consumption expand emollient and surfactant demand. PLI scheme incentives for specialty chemicals attract ingredient suppliers to Gujarat and Maharashtra industrial corridors. Mumbai-Pune chemical processing belt hosts multinational emollient blending facilities serving Southeast Asian markets.
Indonesia
Integrated oleochemical complex expansion and regional halal certification requirements shape surfactant and fatty alcohol supply. BIS-equivalent national standards and ASEAN cosmetic directive harmonization govern import documentation. Sumatra and Kalimantan palm oil processing zones feed fatty alcohol and ester production for Malaysian and Thai contract manufacturers.
Personal Care Ingredients Market Key Industry Players
Player mix skews toward integrated chemical conglomerates with biotechnology platforms and lipid specialty houses with regional distribution networks. Market structure concentrates among ten to fifteen suppliers controlling critical fermentation and oleochemical process technologies. Strategic archetypes separate into biotechnology-anchored active ingredient developers, integrated surfactant and emollient producers, and fragrance-specialist houses with captive preservative portfolios. Competitive moves center on fermentation capacity expansion and direct-to-brand digital platform deployment disintermediating regional distributors.
Within the integrated chemical conglomerate tier, BASF SE and Evonik Industries AG exemplify biotechnology-anchored positioning through fermentation-derived active ingredient platforms. Croda International Plc occupies the lipid specialty archetype with emollient and surfactant chemistry focused on premium skin care applications. These three entities represent divergent strategic vectors: biotech integration, silicone-free emollient substitution, and regional procurement concentration through Southeast Asian oleochemical sourcing.
| Leading Market Players |
|---|
| Dow Inc. |
| Solvay S.A. |
| BASF SE |
| Ashland Global Holdings |
| Givaudan |
| Croda International Plc |
| Clariant AG |
| DSM Firmenich AG |
| Evonik Industries AG |
| Others |
Cost & Logistics Intelligence
EU REACH Annex V compliance gates both supplier qualification timelines and price differentiation across preservative and emollient tiers, forcing formulators to absorb certification costs or shift procurement toward pre-qualified biotech-derived alternatives.
Pricing Analysis
Cost-plus contracts with palm oil and coconut oil indexation dominate emollient and surfactant procurement from Southeast Asian oleochemical complexes. Three-tier pricing structure across premium, standard, and economy levels separates ISO 16128-certified fermented actives from conventional petrochemical-derived ingredients, with European clean-label brands showing least price sensitivity. Pricing pressure stems from feedstock volatility in Malaysian and Indonesian palm oil processing zones, compressing margins for fatty alcohol and ester suppliers serving mid-scale formulators.
Supply Chain Analysis
Strait of Malacca transit underwrites bulk surfactant and emollient flows from Indonesian oleochemical complexes to regional contract manufacturers. Supply concentrates in Jiangsu and Zhejiang provinces for sodium laureth sulfate and cocamidopropyl betaine, Malaysia and Indonesia for fatty alcohols and esters, and Germany for fermentation-derived active ingredients. Raw material dependencies span crude palm oil, coconut oil, and bacterial/yeast culture feedstocks. Single-source vulnerability in Chinese surfactant clusters creates structural risk. Distribution runs through integrated chemical conglomerates with captive blending facilities and direct-to-brand digital platforms disintermediating regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where ECHA REACH compliance timelines and ISO 16128 certification cycles create switching costs that lock formulators into pre-qualified supplier relationships.
For Market Incumbents: Consolidate fermentation capacity expansion in Ludwigshafen and Marl industrial corridors to defend against biotech-derived active ingredient entrants. Deepen backward integration into Indonesian oleochemical sourcing to offset palm oil price volatility threatening emollient margins. Lock in long-term offtake agreements with Malaysian surfactant producers before PLI scheme incentives attract new capacity to India.
For New Entrants and Emerging Players: ISO 16128 fast-track certification for natural origin index calculations opens positioning in European premium skin care supply chains underserved by incumbent documentation bottlenecks. Target microbiome-targeted actives in prebiotic oligosaccharides and postbiotic lysates, where clinical validation requirements filter out commodity suppliers. Deploy direct-to-brand digital platforms on Alibaba 1688 to bypass traditional distributor networks and compress qualification cycles for mid-scale Southeast Asian formulators.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fermentation-derived active ingredient production, favoring scaled biotech platforms over lipid specialty houses with asset-heavy oleochemical exposure. Acquisition target archetype: mid-cap fermentation specialists with validated bacterial strain libraries and existing ECHA dossier submissions. Watch ECHA microplastic restriction implementation timelines as inflection signal for exfoliant ingredient substitution demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | BASF SE and Evonik Industries AG anchor biotech-derived active ingredient supply for REACH-compliant formulators. |
| Backward Integration into Oleochemicals | Croda International Plc secures captive fatty alcohol supply from Malaysian integrated complexes. |
| ISO 16128 Certification Investment | European retailers demand natural origin documentation extending supplier qualification cycles. |
| Direct-to-Brand Digital Platform Deployment | Alibaba 1688 and specialty chemical marketplaces disintermediate traditional distributor networks. |
| Microbiome-Targeted R&D Partnership | Prebiotic oligosaccharide development opens barrier-repair positioning in sensitive-skin segments. |
Research Approach
The analysis maps emollient, surfactant, humectant, preservative, and fragrance sub-sectors, each validated through formulation chemists at contract manufacturers, procurement leads at personal grooming brands, regulatory affairs specialists navigating REACH and FDA frameworks, and plant managers at Indonesian oleochemical complexes. Primary interview insights triangulate against secondary sources including ECHA restriction proposals, FDA color additive regulations, customs trade data for fatty alcohol imports, and SEC filings from integrated chemical conglomerates. Bottom-up volume modeling and top-down value reconciliation ensure cross-validation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework segments by ingredient function, application category, end-user channel, and physical form, with regional regulatory clusters modeled separately. CAGRs derive from annualized growth trajectory fitting across the analysis window. Industry-specific inputs include REACH Annex V revision timelines, palm oil futures curves, and NMPA cosmetic ingredient registration backlogs.
Underlying assumptions cover ECHA microplastic restriction implementation schedules and ASEAN cosmetic directive harmonization progress, with deviation risk concentrated in Chinese surfactant supply disruptions and Indonesian palm oil export policy shifts. Practitioners should keep alternative scenarios live as regulatory divergence between Brussels and Washington evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Asia-Pacific Bath and Shower Products Market
Beauty & Personal Care
Body Balm Market
Beauty & Personal Care
Elastomer Gel in Personal Care Market
Beauty & Personal Care
Lip Care Market
Beauty & Personal Care
Hair Removal Wax Market
Beauty & Personal Care
Hand Soap in Retail Market
Beauty & Personal Care
Japan Beauty and Personal Care Products Market
Beauty & Personal Care
Luxury Beauty Devices Market
Beauty & Personal Care
Cosmetics Face Serum Market
Beauty & Personal Care
ASEAN Organic Cosmetics Market
Beauty & Personal Care
False Eyelashes Market
Beauty & Personal Care
Australia Skin Care Products Market
Beauty & Personal Care
Europe Hair Styling Products Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
Oil Control Shampoo Market
Beauty & Personal Care
Male Grooming Products Market