
 United Kingdom Dermocosmetics Market | 2026-2036
United Kingdom Dermocosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Dermocosmetics Market Insights
Clinical-grade formulation standards is unwinding quality tiers across the United Kingdom dermocosmetics landscape. La Roche-Posay leverages its dermatological heritage to anchor pharmacy channel dominance. CeraVe competes through ceramide-focused formulations that sustain repeat purchase rates. Beiersdorf differentiates via Eucerin's therapeutic positioning, which controls shelf space in Boots and independent chemists.
United Kingdom dermocosmetics comprise topical preparations formulated with active pharmaceutical or biologically functional ingredients, manufactured under Good Manufacturing Practice conditions with documented stability testing and dermal tolerance profiles, designed to treat or prevent skin pathologies while maintaining cosmetic acceptability. Facial Care commands the largest revenue pool within product type segments, though acne and sensitivity target concerns are capturing faster growth as NHS wait times for dermatology referrals extend patient self-treatment behavior. E-Commerce distribution channels are displacing department store counters, while serum formulations extract premium pricing relative to lotions and creams.
The UK Medicines and Healthcare products Regulatory Agency and the Cosmetic, Toiletry and Perfumery Association govern ingredient safety claims and borderline product classifications, with MHRA scrutiny intensifying for retinoid-containing formulations that straddle cosmetic-pharmaceutical boundaries. The EU Cosmetics Regulation retained in UK law post-Brexit continues shaping permissible ingredient lists and notification requirements, though divergence risk looms as the UK develops independent chemical safety frameworks. Stakeholders must monitor whether MHRA reclassification moves more active ingredients behind pharmacy-only distribution, reshaping channel economics and brand access strategies.
Market Dynamics
MHRA's intensifying scrutiny of borderline cosmetic-pharmaceutical products is forcing brands to recalibrate formulation strategies and channel positioning across England, Scotland, and Wales.
Growth Catalysts
- NHS Dermatology Wait Times:Extended referral queues exceeding 18 months in Greater Manchester and Birmingham are accelerating patient migration toward pharmacy-led self-treatment protocols.
- EU Cosmetics Regulation Retention:Post-Brexit adoption of REACH-aligned ingredient safety frameworks maintains regulatory continuity that reassures multinational manufacturers.
- Ceramide Science Maturation:Lipid barrier repair research from University of Manchester is translating into clinically validated over-the-counter formulations.
Market Restraints
- Retinoid Reclassification Risk:MHRA's 2023 consultation on vitamin A derivatives threatens to shift popular anti-aging actives behind pharmacy-only distribution.
- Active Ingredient Supply Concentration:Niacinamide and zinc oxide feedstock dependence on German and Chinese chemical manufacturers creates vulnerability.
- Clinical Trial Cost Burden:Mandatory dermal tolerance documentation under Good Manufacturing Practice standards elevates R&D expenditure for mid-tier entrants.
Strategic Opportunities
- Scotland's Underserved Highlands:Remote pharmacy networks in Aberdeen and Inverness lack dermatology-trained consultation services that southern English consumers now expect.
- Telemedicine Integration:Video-enabled skin assessments paired with prescription-strength product fulfillment are collapsing the diagnostic-to-treatment timeline.
- MHRA Innovation Office Pathway:The regulator's streamlined borderline classification pre-submission process reduces time-to-market for novel actives.
Industry Challenges
- Formulation Chemist Scarcity:Brexit-related EU talent outflow has compressed availability of professionals skilled in stability testing for biologically active compounds.
- Legacy ERP Integration:Batch traceability requirements under retained EU Cosmetics Regulation clash with outdated inventory systems at independent pharmacy chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Dermocosmetics Market |
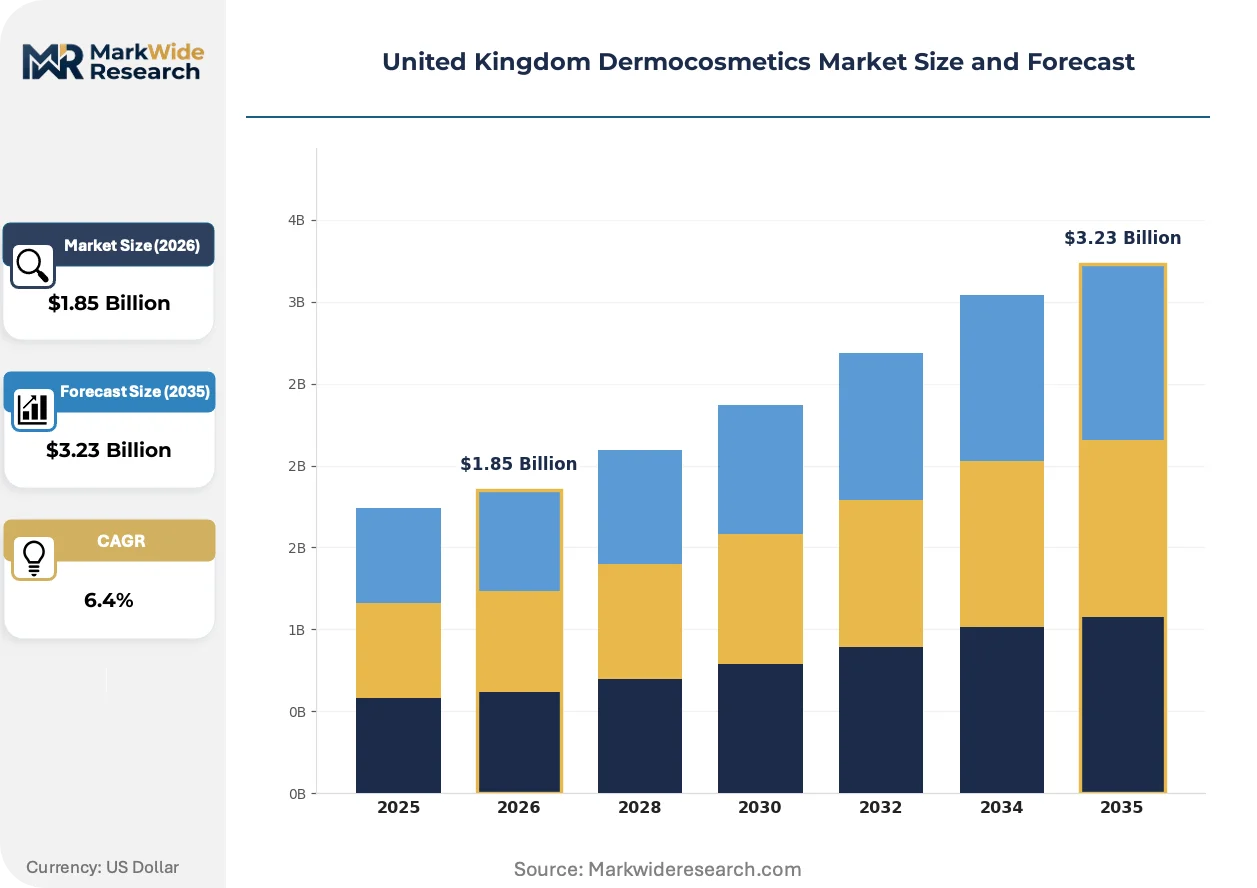
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Care, Body Care, Hair Care, Sun Protection, Lip Care Formulation: Creams, Serums, Lotions, Gels, Oils Target Concern: Anti-Aging, Acne, Hyperpigmentation, Sensitivity, Dryness Distribution Channel: Pharmacies, Beauty Salons, E-Commerce, Specialty Stores, Department Stores |
| Companies Covered | CeraVe, Bioderma, L’Oréal, Beiersdorf, Aveeno, La Roche-Posay, Vichy, Estée Lauder, Eucerin, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Dermocosmetics Market Trends and Innovations
Biotechnology-derived actives and diagnostic-adjacent product positioning are dissolving traditional boundaries between cosmetic skincare and medical dermatology across UK retail channels.
Microbiome-targeted formulations is bifurcating the facial care segment into prescriptive probiotic strains and broad-spectrum prebiotic supports. Premium clinic networks in Harley Street and Manchester's Spinningfields district are adopting strain-specific protocols faster than mass pharmacy channels. This technology is compressing the addressable market for conventional moisturizers while expanding reimbursement-adjacent revenue pools.
MHRA's 2024 guidance on software as a medical device is capturing AI-powered skin analysis applications that previously operated in unregulated cosmetic territory. The framework mandates clinical validation for algorithms recommending specific active concentrations. Mobile-enabled diagnostic tools in Boots' flagship London locations are now subject to conformity assessment procedures that delay deployment by 8-14 months.
Subscription-based replenishment models are capturing loyalty from chronic condition sufferers who previously purchased reactively. Independent pharmacy platforms and clinic-owned e-commerce portals are displacing Boots and Superdrug for repeat acne and rosacea purchases. This behavioral pivot concentrates most visibly among 25-40 year-old consumers in Bristol and Leeds who prioritize consultation continuity over retail convenience.
United Kingdom Dermocosmetics Market Segmentation
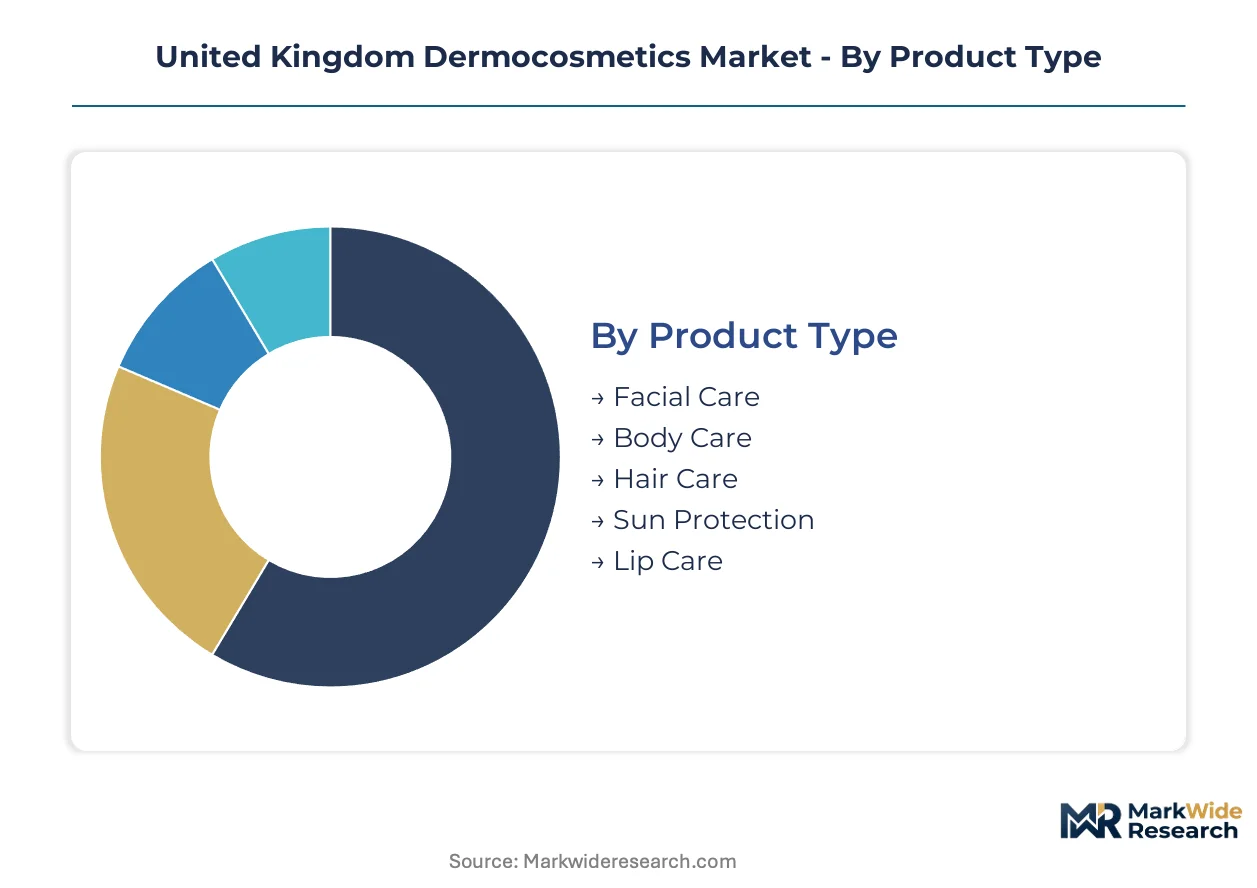
Dermocosmetics segmentation in the United Kingdom reflects divergent margin architectures across clinical validation tiers and channel access levels. Manufacturers calibrate portfolio depth against MHRA classification risk and pharmacy consultation economics.
Product Type:
Premium pricing power concentrates in facial applications where clinical efficacy claims justify repeat purchase premiums.
- Facial Care:Formulations targeting barrier repair and photoaging dominate pharmacy shelf space. Greater London clinic networks and Manchester's Spinningfields district concentrate demand for prescription-adjacent serums and ceramide-rich moisturizers as NHS dermatology wait times extend.
- Body Care:Therapeutic positioning for atopic dermatitis and keratosis pilaris drives specialist pharmacy penetration. Regional demand clusters in Scotland's Central Belt where independent chemists provide consultation continuity for chronic conditions.
- Hair Care:Scalp-focused actives addressing seborrheic dermatitis occupy a narrower clinical niche.
- Sun Protection:Mineral filter innovations respond to MHRA scrutiny of chemical UV absorbers.
- Lip Care:Barrier repair formulations command modest pharmacy presence.
The dominant share belongs to Facial Care, while Body Care is closing the gap fastest.
Formulation:
Delivery technology shapes patient compliance and clinical outcome differentiation across prescription-adjacent portfolios.
- Creams:Occlusive bases with lipid-mimetic compositions anchor chronic dryness management. Boots and independent pharmacy chains in Birmingham and Leeds prioritize dermatologist-recommended cream formats for eczema protocols.
- Serums:High-actives penetration vehicles extract maximum price per milliliter. Harley Street clinic networks and premium e-commerce portals in Bristol concentrate demand for vitamin C and niacinamide concentrates.
- Lotions:Spreadability advantages suit large-surface body applications.
- Gels:Non-comedogenic profiles capture acne-prone segments.
- Oils:Cleansing and barrier-support positioning remains niche.
Serums capture the steepest margin expansion trajectory, though Creams retain volume leadership.
Target Concern:
Condition severity determines channel routing between pharmacy self-treatment and secondary care referral.
- Anti-Aging:Retinoid and peptide formulations face MHRA reclassification risk for vitamin A derivatives. Demand concentrates among 35-50 year-old consumers in affluent London boroughs seeking clinic-grade outcomes without prescription barriers.
- Acne:Benzoyl peroxide and adapalene availability spans pharmacy and prescription channels. Extended NHS wait lists in Greater Manchester accelerate migration toward pharmacy-led management protocols.
- Hyperpigmentation:Tyrosinase inhibitor formulations serve post-inflammatory and photodamage segments.
- Sensitivity:Minimalist formulations target rosacea and reactive skin profiles.
- Dryness:Ceramide and urea-based therapies address atopic dermatitis maintenance.
Anti-Aging commands the largest revenue pool, while Acne is gaining share fastest on self-treatment behavior.
Distribution Channel:
Channel selection determines regulatory classification exposure and consultation service attachment.
- Pharmacies:Boots and independent chemists anchor MHRA-compliant borderline product distribution. Scotland's pharmacy networks in Aberdeen and Inverness deepen dermatology-trained consultation services following English pharmacy-led models.
- E-Commerce:Subscription replenishment and telemedicine integration collapse diagnostic-to-treatment timelines. Clinic-owned portals and independent pharmacy platforms displace traditional retail for chronic condition management.
- Beauty Salons:Aesthetic treatment adjacency supports premium positioning.
- Specialty Stores:Curated assortments serve ingredient-educated consumers.
- Department Stores:Counter-based consultation models face displacement pressure.
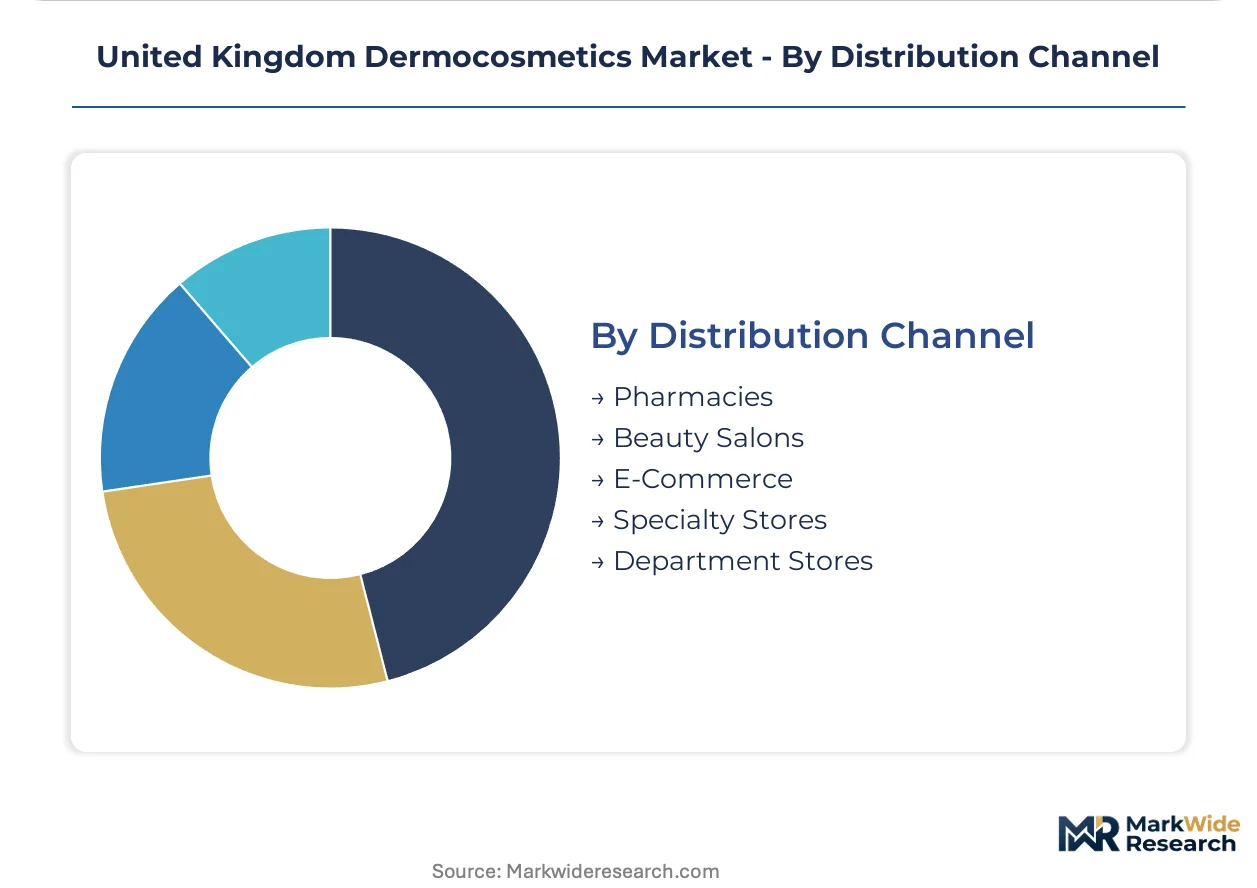
Pharmacies retain the structural advantage, while E-Commerce is expanding most quickly on subscription loyalty mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across UK sub-regions. Greater London consumers absorb premium clinic-grade pricing with minimal elasticity. Northern England and Scottish Highlands patients gravitate toward pharmacy self-treatment as NHS dermatology queues lengthen.
London and Southeast England
Harley Street clinic networks and premium pharmacy flagships in Chelsea and Kensington anchor the highest-value consumption. MHRA borderline classifications push prescription-adjacent serums into pharmacy-only distribution. Spinningfields Manchester replicates this model at reduced scale.
Midlands
Birmingham and Leicester concentrate demand for therapeutic body care addressing atopic dermatitis maintenance. Independent pharmacy chains in the West Midlands deepen dermatology-trained consultation capacity. Boots regional distribution centers route ceramide-focused formulations through Coventry logistics hubs.
North England
Greater Manchester's 18-month NHS dermatology wait times accelerate pharmacy-led acne management. Leeds and Liverpool independent chemists capture subscription replenishment loyalty from chronic condition sufferers. Telemedicine platforms collapse diagnostic-to-treatment timelines for rosacea patients.
Scotland
Aberdeen and Inverness pharmacy networks remain underserved relative to English consultation standards. The Scottish Government's pharmacy-first minor ailments strategy expands dermocosmetic access without GP referral. Edinburgh's private clinic corridor concentrates premium anti-aging demand.
Wales
Cardiff and Swansea bridge English pharmacy consultation models with NHS Wales procurement frameworks. Rural pharmacy access gaps in North Wales sustain higher e-commerce penetration for chronic skin condition management. Welsh language labeling requirements add compliance cost for mid-tier entrants.
United Kingdom Dermocosmetics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the United Kingdom dermocosmetics landscape. The market structure tiers between dermatological heritage brands with pharmacy channel dominance and mass-market portfolios competing on formulation accessibility. Three strategic archetypes define competitive positioning: heritage dermatology laboratories, mass-market skincare divisions, and clinic-exclusive premium houses. Consolidation pressure intensifies through M&A targeting microbiome research capabilities and strategic partnerships with telemedicine platforms.
Within the dermatological heritage tier, La Roche-Posay and CeraVe anchor pharmacy channel positioning through clinician endorsement protocols. Beiersdorf occupies a position exemplifying therapeutic brand architecture with Eucerin's medical-adjacent positioning. These three represent distinct approaches to MHRA compliance: prescription heritage translation, barrier repair science commercialization, and therapeutic credibility maintenance.
| Leading Market Players |
|---|
| CeraVe |
| Bioderma |
| L’Oréal |
| Beiersdorf |
| Aveeno |
| La Roche-Posay |
| Vichy |
| Estée Lauder |
| Eucerin |
| Others |
Pricing and Supply Chain Analysis
MHRA's Good Manufacturing Practice certification gates both supplier qualification and price tier differentiation across UK dermocosmetics, forcing brands to absorb compliance costs or retreat to mass-market positioning. This regulatory threshold simultaneously constrains raw material sourcing flexibility and enables prescription-adjacent premium pricing for validated formulations.
Pricing Analysis
Subscription replenishment revenue drives lifetime value concentration among chronic condition sufferers. Three-tier pricing structure across clinic-exclusive, pharmacy-validated, and mass-retail levels separates Harley Street consultation bundles from Boots dermatology-trained services from Superdrug self-selection. Pricing pressure stems from NHS wait-time-driven pharmacy volume surges that compress margin per unit. Price sensitivity concentrates among 25-40 year-old subscription adopters in Leeds and Bristol, while London clinic networks absorb premium tier increases with minimal elasticity.
Supply Chain Analysis
Container availability constraints on Rotterdam-Felixstowe lanes elevate inbound logistics costs for active ingredient shipments from German chemical manufacturers. Niacinamide and ceramide feedstock supply concentrates in Germany, China, and India, with UK formulators drawing from BASF and Evonik European production hubs. Single-source vulnerability runs through Chinese zinc oxide suppliers subject to export license unpredictability. Distribution runs through Boots' Coventry regional hub and independent pharmacy cooperative networks in Manchester and Birmingham.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK dermocosmetics represents early-cycle expansion as NHS dermatology wait times institutionalize pharmacy-led self-treatment behavior. Telemedicine integration collapses diagnostic-to-purchase timelines, accelerating adoption velocity beyond traditional retail conversion rates.
For Market Incumbents: Fortify pharmacy channel control through exclusive consultation training partnerships with Boots and independent chemist networks. Deepen vertical integration into ceramide active sourcing to offset German feedstock concentration risk. Counter emerging microbiome-specialist entrants by accelerating MHRA Innovation Office pre-submissions for novel strain formulations.
For New Entrants and Emerging Players: Lead with telemedicine-enabled subscription models targeting rosacea and acne sufferers in Scotland's underserved Highlands pharmacy networks. White-space concentration sits in Aberdeen and Inverness consultation gaps relative to English pharmacy standards. Capture loyalty through video-enabled skin assessment paired with prescription-strength product fulfillment bypassing traditional retail.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across microbiome research capabilities as platform technologies mature. Long-term viability favors acquisition targets possessing MHRA borderline classification expertise and telemedicine integration infrastructure. Signal to monitor: MHRA retinoid reclassification implementation timing and pharmacy-only distribution mandate scope.
| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Platform Integration | Video-enabled skin assessments in Boots flagship locations collapse diagnostic-to-treatment timelines. |
| MHRA Innovation Office Pre-submission | Streamlined borderline classification accelerates novel active time-to-market for microbiome formulations. |
| Pharmacy Consultation Training Partnership | Dermatology-trained staff in Scotland's Central Belt replicate English pharmacy-led engagement models. |
| Ceramide Feedstock Backward Integration | Upstream control over lipid barrier repair actives reduces German chemical manufacturer dependency. |
| Subscription Replenishment Model Launch | Chronic condition sufferers in Bristol and Leeds prioritize consultation continuity over retail convenience. |
Research Methodology
A spread of perspectives from pharmacy procurement managers, dermatology-trained consultation staff, formulation chemists, and MHRA regulatory affairs specialists converged on the working assumptions. Primary interviews with Boots category buyers and independent chemist owners in Manchester, Birmingham, and Aberdeen supplemented secondary validation through MHRA guidance documents, retained EU Cosmetics Regulation compliance databases, and NHS dermatology wait time statistics. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled include product type, formulation technology, target concern severity, and distribution channel access level. CAGRs were derived from patient volume projections tied to NHS referral queue dynamics and pharmacy consultation capacity expansion. Forecast inputs incorporated MHRA reclassification risk scenarios and telemedicine platform adoption curves without specifying implementation timelines.
The analysis sits within stated boundaries; outcomes outside MHRA regulatory continuity or sustained NHS wait-time elevation would require recalibration. Forecasts reflect assumptions regarding pharmacy-first minor ailments policy persistence and EU Cosmetics Regulation divergence trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Germany Cosmetics for Pregnancy Market
Beauty & Personal Care
United Kingdom Cosmetics Products Market
Beauty & Personal Care
US Sexual Wellness Market
Beauty & Personal Care
Saudi Arabia Body Care and Personal Hygiene Market
Beauty & Personal Care
Nail Lamps Market
Beauty & Personal Care
Organic Personal Care Market
Beauty & Personal Care
Asia-Pacific Hair Conditioner Market
Beauty & Personal Care
Global Lash Extension Market
Beauty & Personal Care
Europe Sustainable Personal Care Market
Beauty & Personal Care
Hair Gel Market
Beauty & Personal Care
Global Electric Head and Scalp Massager Market
Beauty & Personal Care
Luxury Bath and Body Products Market
Beauty & Personal Care
Nail Care Products Market
Beauty & Personal Care
Facial Care Market
Beauty & Personal Care
Facial Make-Up Market
Beauty & Personal Care
China Antibacterial Soap Market