
 GCC Male Grooming Products Market | 2026-2036
GCC Male Grooming Products Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Male Grooming Products Market Intelligence
The professional workforce segment is pivoting toward comprehensive grooming regimens that span skin care, hair care, and fragrance categories. Procter & Gamble Co. leverages its mass-market distribution networks to sustain shelf dominance across Saudi supermarkets and UAE malls. L'Oréal SA anchors its regional position through specialized men's lines that compete directly with local halal-certified alternatives. Unilever PLC differentiates via price-accessible formats that dominate volume sales in Kuwait and Oman.
GCC male grooming products encompass topical formulations, fragrances, and oral care solutions designed for men's specific dermatological needs, typically featuring oil-control agents, UV filters, and alcohol-free bases suited to arid Gulf climates. Skin care and hair care categories command the largest revenue share due to recurring purchase patterns and premiumization among millennial end users. Fragrance sales through specialty stores and salons capture the highest per-transaction values, while online retail channels represent the fastest-growing distribution pathway as digital payment infrastructure matures across the region.
SASO and ESMA standards govern product safety, ingredient disclosure, and halal compliance for all imports entering Saudi Arabia and the UAE, effectively filtering market access for non-compliant manufacturers. The UAE's Ministry of Industry and Advanced Technology enforces labeling and chemical registration rules that add compliance layers for fragrance and skin care entrants. Stakeholders must monitor evolving halal certification reciprocity agreements between Gulf states, as harmonization would reshape cross-border supply chain economics and brand localization priorities.
Market Dynamics
Halal certification reciprocity negotiations between Gulf states are compressing formulation cycles and forcing manufacturers to pre-certify products for multiple jurisdictions simultaneously.
Growth Catalysts
- ESMA Halal Framework Expansion:The UAE's Emirates Authority for Standardization and Metrology is extending halal certification requirements to cover imported skin care actives, creating compliant supply bottlenecks that reward early-adapting regional manufacturers.
- Millennial Urban Concentration:Riyadh and Jeddah host dense clusters of young professional males whose grooming expenditures now exceed three product categories per purchase occasion.
- Digital Payment Infrastructure:Mature e-wallet penetration across Saudi Arabia and Kuwait is unlocking subscription-based replenishment models for consumable grooming categories.
Market Restraints
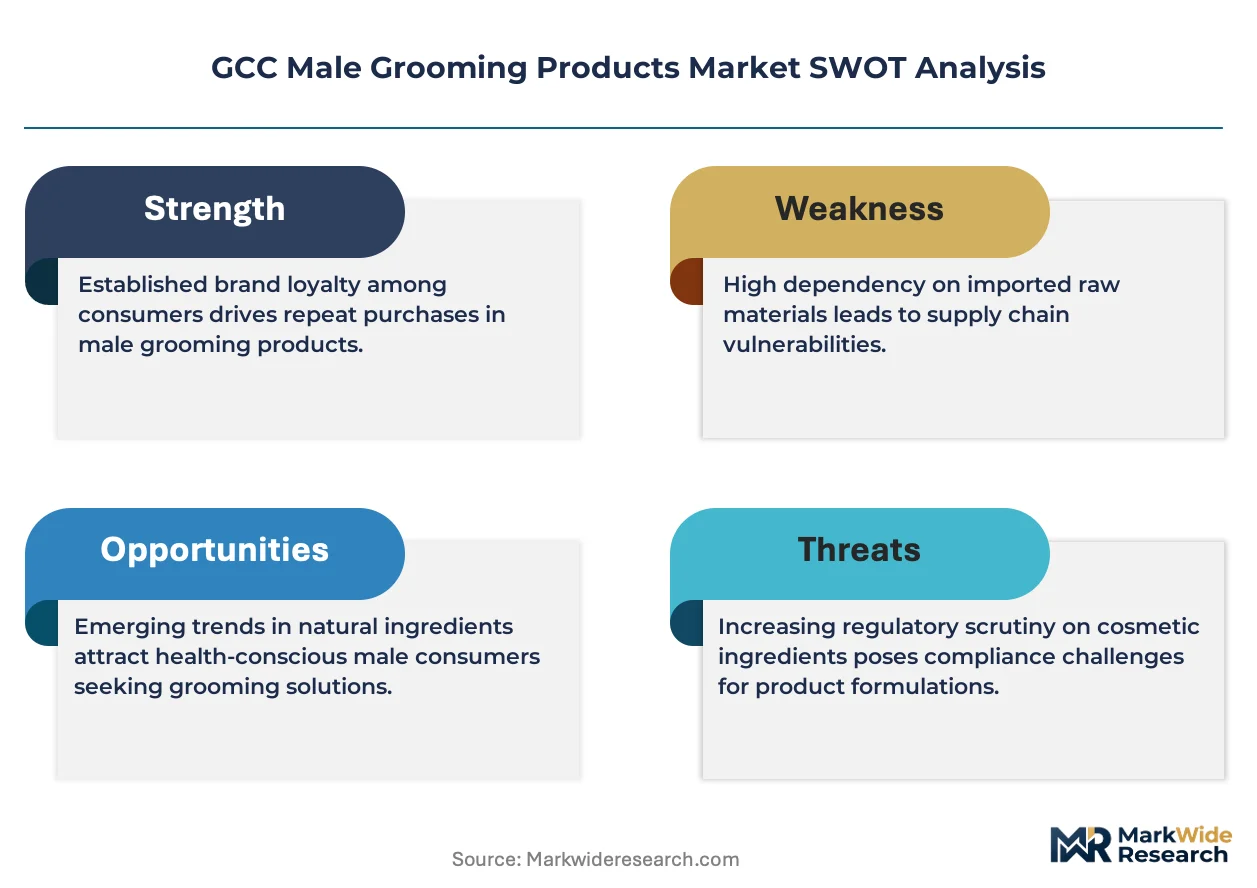
- Ingredient Import Dependency:Specialty alcohol-free solvents and halal-compliant preservatives concentrate among Malaysian and Indonesian suppliers, exposing margins to shipping cost volatility.
- SASO Testing Bottlenecks:The Saudi Standards, Metrology and Quality Organization maintains single-lab certification queues for fragrance stability testing, extending product launch timelines by four to six months.
- Waterless Formulation Constraints:Arid-climate adapted rinse-free cleansers face technical barriers in achieving comparable efficacy to water-based alternatives without alcohol content.
Strategic Opportunities
- Oman Underpenetration:Muscat and Salalah retail corridors carry limited men's skin care SKUs relative to fragrance density, creating shelf space for halal-certified entrants.
- Barbershop Channel Integration:High-service barbershops in Dubai and Doha are evolving into product recommendation nodes, bypassing traditional retail markup structures.
- SASO-ESMA Reciprocity:Pending mutual recognition agreements would eliminate duplicate certification costs for products circulating between Saudi Arabia and the UAE.
Industry Challenges
- Formulation Chemist Scarcity:Gulf universities produce limited graduates trained in halal-compliant cosmetic chemistry, forcing brands to recruit from Southeast Asian talent pools.
- Climate Stability Testing:Products must demonstrate shelf integrity across 50°C storage conditions and rapid temperature cycling, requiring accelerated aging protocols that extend R&D cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Male Grooming Products Market |
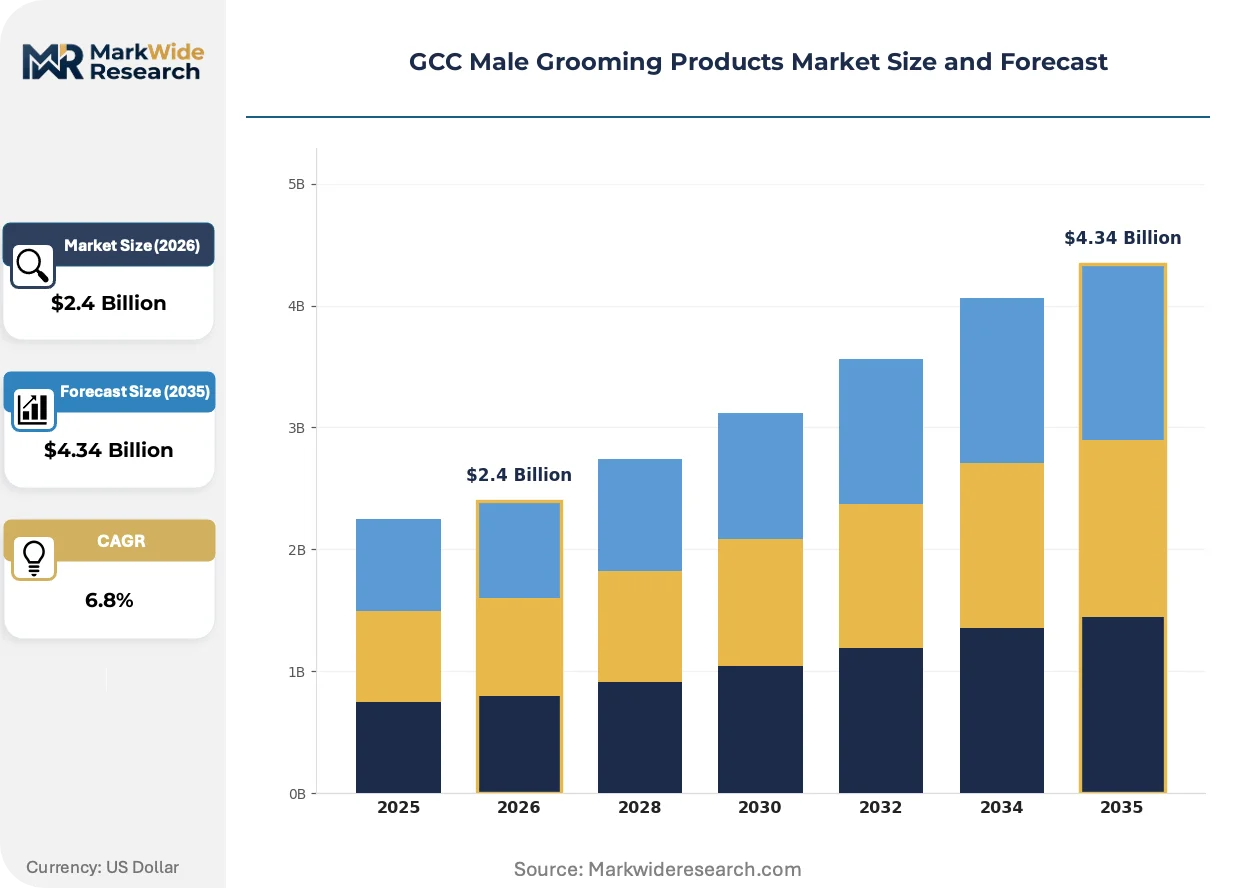
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shaving Cream, Beard Oil, Aftershave Balm, Hair Styling Gel Category: Skin Care, Hair Care, Fragrance, Oral Care End User: Millennials, Generation X, Professionals, Students Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Salons |
| Companies Covered | Beiersdorf AG, Colgate-Palmolive Company, Procter & Gamble Co., Estée Lauder Companies, Inc., Kao Corporation, Unilever PLC, Shiseido Co., Ltd., Coty, Inc., L'Oréal SA, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Male Grooming Products Market Strategic Shifts & Innovations
Water-conscious formulation science and AI-driven personalization engines are rewriting product development timelines and retail interaction models across Gulf grooming categories.
Biotechnology-derived halal actives are decentralizing sourcing patterns for premium skin care lines. Saudi and UAE-based labs now cultivate plant stem cell extracts and fermentation-based peptides locally, reducing dependency on European and East Asian ingredient houses. Regional brands are adopting these inputs faster than multinationals, compressing the innovation gap between local and imported offerings.
SASO's 2024 ingredient disclosure mandates are forcing reformulation of legacy fragrance and skin care portfolios. The regulation requires granular labeling of all components exceeding 0.01% concentration, including complex fragrance accords previously protected as trade secrets. Premium fragrance houses are responding by simplifying compositions and patenting novel delivery systems rather than ingredient combinations.
Subscription replenishment models are displacing supermarket bulk purchasing among urban professionals in Kuwait City and Manama. Younger buyers prioritize convenience and curated discovery over unit cost savings, accepting 15-20% per-ounce premiums for automated delivery. Specialty e-commerce platforms are capturing this cohort through algorithmic matching of skin type data to product rotations, bypassing the diagnostic limitations of physical retail.
GCC Male Grooming Products Market Segmentation
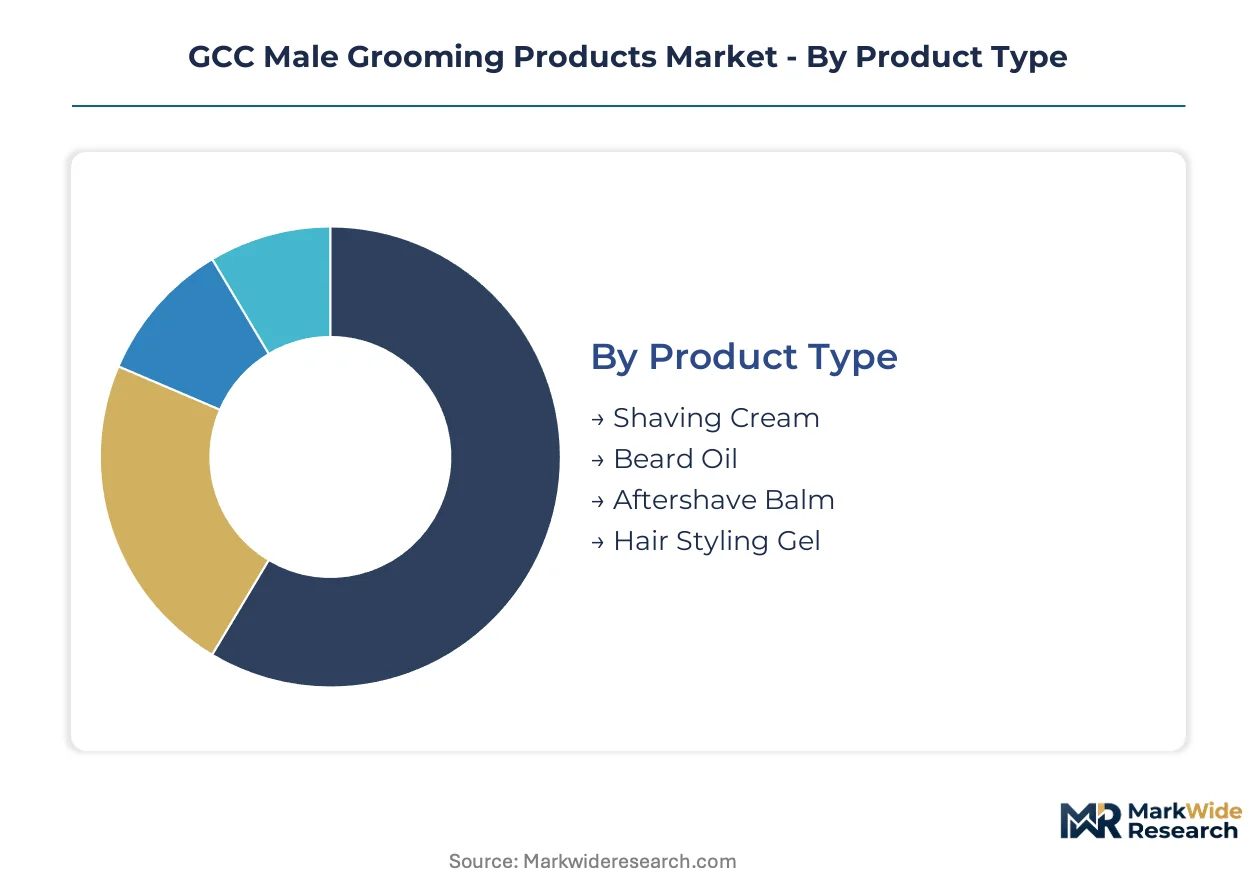
GCC male grooming markets fragment across product physics, consumer life-stage, and channel economics. Certification requirements from SASO and ESMA apply unevenly across these divides, concentrating compliance costs in fragrance and skin care while exempting certain oral care formulations.
Product Type:
Shaving Cream and Beard Oil carry mandatory SASO stability testing for alcohol-free solvent systems, while Hair Styling Gel faces lighter ESMA disclosure thresholds in the UAE.
- Shaving Cream:Emulsion-based formulations combining glycerin, stearic acid, and halal-certified surfactants designed for hard-water compatibility across Gulf municipal supplies. Demand clusters in Riyadh and Jeddah among professionals seeking irritation-mitigating properties for daily use. SASO's fragrance stability queues extend launch timelines by four to six months for new entrants.
- Beard Oil:Carrier oil blends featuring argan, jojoba, and halal-compliant vitamin E derivatives targeting length maintenance and follicle conditioning. Kuwait City and Dubai barbershops drive premium positioning through recommendation-based sales, bypassing retail markup structures. ESMA's expanded halal framework now covers imported active botanicals, creating supply bottlenecks.
- Aftershave Balm:Alcohol-free moisturizing formulations with aloe vera and allantoin for post-irritation recovery.
- Hair Styling Gel:Polymer-based hold systems adapted to high-humidity coastal climates in Doha and Manama.
Leading the category by volume: Shaving Cream. Growing fastest: Beard Oil.
Category:
Margin structures diverge sharply — Fragrance captures highest per-transaction values through specialty retail, while Oral Care operates on supermarket volume economics with minimal certification overhead.
- Skin Care:Oil-control cleansers, UV-filter moisturizers, and anti-aging serums formulated for sebum-rich male dermatology in arid climates. Riyadh's young professional males now purchase across three product subcategories per occasion, driving premiumization. Biotechnology-derived halal actives from Saudi-based labs are compressing innovation cycles versus imported alternatives.
- Hair Care:Shampoos, conditioners, and scalp treatments addressing hard-water mineral buildup and heat-stress damage. Subscription replenishment models in Kuwait City displace bulk purchasing among millennials accepting per-ounce premiums for convenience. Algorithmic skin-type matching platforms bypass diagnostic limitations of physical retail.
- Fragrance:Concentrated perfume oils and eau de parfum compositions requiring granular SASO ingredient disclosure above 0.01% concentration.
- Oral Care:Toothpastes and mouthwashes with halal-compliant flavor systems, generally exempt from fragrance stability testing protocols.
Skin Care generates the highest absolute margin per SKU. Fragrance exhibits the steepest expansion trajectory through digital channels.
End User:
Life-stage segmentation determines category penetration depth — Professionals cross-purchase across skin, hair, and fragrance, while Students concentrate in single-category entry points.
- Millennials:Urban males aged 25-40 in Jeddah and Dubai driving comprehensive grooming regimen adoption beyond basic hygiene. Digital payment maturity enables subscription-based replenishment with 15-20% per-ounce premiums accepted for automated delivery.
- Generation X:Established professionals prioritizing fragrance and skin care over hair styling categories.
- Professionals:White-collar workforce segments across Saudi Arabia, the UAE, and Kuwait expanding routines into three-plus product categories per purchase occasion.
- Students:Price-sensitive entrants concentrated in volume hair care and oral care with limited skin care penetration.
Professionals dominate absolute spending. Millennials are gaining share fastest through digital channel migration.
Distribution Channel:
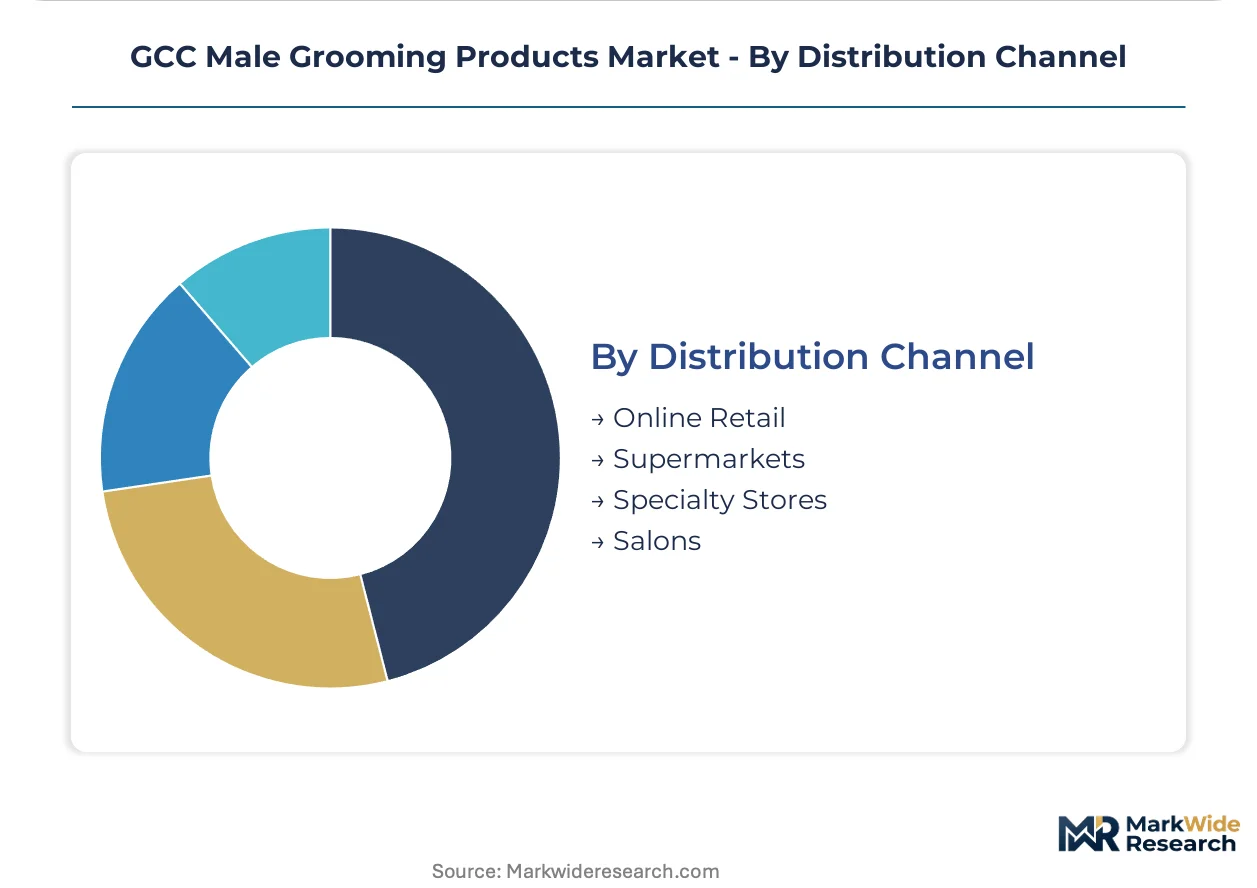
Channel selection dictates margin capture and certification documentation requirements — Salons and specialty stores demand full SASO/ESMA traceability, while Online Retail operates under deferred compliance verification.
- Online Retail:E-commerce platforms and brand-direct sites leveraging mature e-wallet infrastructure across Saudi Arabia and Kuwait. Algorithmic personalization engines match skin-type data to product rotations, capturing younger buyers prioritizing curated discovery over unit cost savings.
- Supermarkets:Mass-market shelf dominance by Procter & Gamble and Unilever across Saudi hypermarkets and UAE malls.
- Specialty Stores:Fragrance-focused retail capturing highest per-transaction values through assisted selling environments.
- Salons:High-service barbershops in Dubai and Doha evolving into product recommendation nodes with bypassed retail markups.
Supermarkets retain volume leadership. Online Retail climbs the fastest as digital payment infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity for halal-compliant formulations concentrates in Saudi Arabia and the UAE, while consumption intensity peaks in urban centers across all six Gulf states. Manufacturing investments lag behind retail expansion, creating import dependency for specialty actives and alcohol-free solvents.
Saudi Arabia
Riyadh and Jeddah host dense clusters of young professional males whose grooming expenditures now span three product categories per purchase occasion. SASO's fragrance stability testing queues extend product launch timelines by four to six months, filtering market access for non-compliant manufacturers. Local biotechnology labs in the Eastern Province now cultivate plant stem cell extracts, reducing dependency on Southeast Asian ingredient houses.
United Arab Emirates
Dubai's high-service barbershops are evolving into product recommendation nodes that bypass traditional retail markup structures. ESMA's expanded halal framework now covers imported skin care actives, creating compliant supply bottlenecks that reward early-adapting regional manufacturers. Abu Dhabi's Ministry of Industry and Advanced Technology enforces labeling and chemical registration rules that add compliance layers for fragrance entrants.
Kuwait
Kuwait City's millennial professionals have displaced supermarket bulk purchasing with subscription replenishment models that accept 15-20% per-ounce premiums for automated delivery. Mature e-wallet penetration is unlocking algorithmic personalization engines that match skin-type data to product rotations. The concentration of price-accessible formats dominates volume sales relative to premium positioning.
Qatar
Doha's high-service barbershops are integrating retail functions alongside grooming services, creating hybrid distribution channels. Local regulations align with ESMA frameworks for halal certification, though testing infrastructure remains less developed than in the UAE. The professional workforce segment drives comprehensive regimen adoption across skin, hair, and fragrance categories.
Oman
Muscat and Salalah retail corridors carry limited men's skin care SKUs relative to fragrance density, creating shelf space for halal-certified entrants. Import dependency for specialty alcohol-free solvents exposes margins to shipping cost volatility from Malaysian and Indonesian suppliers. Young urban consumers are beginning to mirror Saudi and UAE purchasing patterns for premium grooming categories.
GCC Male Grooming Products Market Key Industry Players
Top-tier vendors anchor mass-market shelf dominance, while regional specialists and premium fragrance houses occupy narrower competitive positions. The vendor base stratifies across three tiers: multinational conglomerates with distribution scale, halal-certified regional manufacturers with formulation agility, and luxury fragrance specialists with assisted-selling expertise. Strategic moves concentrate on barbershop channel integration and biotechnology-derived ingredient sourcing. Competitive differentiation increasingly depends on pre-certification for multiple Gulf jurisdictions simultaneously.
Within the multinational tier, Procter & Gamble Co., L'Oréal SA, and Unilever PLC exemplify divergent positioning archetypes. Procter & Gamble Co. occupies a position anchored in mass-market distribution networks across Saudi hypermarkets and UAE malls. L'Oréal SA represents the specialized men's line approach that competes directly with local halal-certified alternatives. Unilever PLC exemplifies price-accessible format dominance that captures volume sales in Kuwait and Oman. These three entities collectively illustrate how scale, specialization, and pricing strategy segment competitive space without requiring exclusive territorial claims.
| Leading Market Players |
|---|
| Beiersdorf AG |
| Colgate-Palmolive Company |
| Procter & Gamble Co. |
| Estée Lauder Companies, Inc. |
| Kao Corporation |
| Unilever PLC |
| Shiseido Co., Ltd. |
| Coty, Inc. |
| L'Oréal SA |
| Others |
Cost & Logistics Intelligence
Halal certification grade divergence between SASO-compliant premium formulations and ESMA-registered standard alternatives manifests in both pricing power and sourcing configurations across the GCC. Premium tiers command lead-time premiums through dedicated Malaysian and Indonesian ingredient channels, while standard formats compete on spot inventory economics from regional distributors.
Pricing Analysis
Short lead-time premiums for SASO-certified fragrance and skin care formulations run 15-20% above spot inventory pricing for comparable ESMA-registered alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, brand heritage, and barbershop channel integration. Pricing pressure stems from shipping cost volatility affecting alcohol-free solvent imports. Students exhibit highest price sensitivity, while Riyadh professionals accept per-ounce premiums for subscription convenience.
Supply Chain Analysis
Direct-to-barbershop channels handle premium buyer demand across Dubai and Doha, bypassing traditional retail markups. Manufacturing concentrates in Saudi Arabia and the UAE, with specialty actives drawn from Malaysia and Indonesia. Raw material dependencies span argan oil, halal-compliant vitamin E derivatives, and plant stem cell extracts. Single-source vulnerability concentrates in Southeast Asian preservative suppliers. Distribution runs through supermarket chains for volume, specialty stores for fragrance, and algorithmic e-commerce platforms for millennial replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SASO's fragrance stability testing queues function as a cost-of-compliance moat, filtering market access for manufacturers unwilling to absorb four-to-six-month certification timelines. This regulatory barrier rewards early-certifying incumbents while forcing new entrants into alternative positioning.
For Market Incumbents: Anticipate ESMA-SASO reciprocity negotiations by pre-certifying formulations for both jurisdictions simultaneously. Consolidate barbershop channel relationships in Dubai and Doha before regional competitors replicate the recommendation-based sales model. Biotechnology-derived ingredient sourcing from Saudi-based labs offers a defensible cost position against Southeast Asian supply volatility.
For New Entrants and Emerging Players: Enter via Oman's underpenetrated skin care corridors in Muscat and Salalah, where fragrance density far exceeds grooming SKU availability. Target millennial professionals in Kuwait City with subscription-first positioning leveraging mature e-wallet infrastructure. Algorithmic skin-type matching platforms provide a go-to-market angle that bypasses physical retail's diagnostic limitations.
For Investors and Strategic Acquirers: Re-rating potential sits with halal-certified regional manufacturers given pending reciprocity agreements between Gulf states. Long-term viability across the analysis window favors entities with captive biotechnology labs and multi-jurisdiction certification pipelines. Monitor ESMA-SASO mutual recognition announcements as the inflection signal for cross-border supply chain economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Pre-Positioning | Dual SASO-ESMA registration eliminates duplicate testing costs for Saudi-UAE circulation. |
| Biotechnology Lab Investment | Saudi-based plant stem cell cultivation reduces dependency on Southeast Asian ingredient houses. |
| Barbershop Channel Integration | Dubai high-service grooming venues bypass retail markups through recommendation-based sales. |
| Subscription Platform Launch | Kuwait City millennial professionals accept per-ounce premiums for automated replenishment convenience. |
| Waterless Formulation R&D | Arid-climate rinse-free cleansers address technical barriers without alcohol content. |
Research Approach
Regulatory filings from SASO and ESMA, customs trade records, and Nielsen retail audit data formed the secondary backbone for this analysis. Primary interviews with brand managers at multinational conglomerates, category buyers at Saudi hypermarkets, halal certification officers, and barbershop operators in Dubai and Doha provided demand-side validation. Bottom-up SKU-level modeling and top-down category sizing were triangulated to anchor volume and value estimates.
Bottom-up unit economics were stress-tested against top-down macro indicators across the projection horizon. Segmentation dimensions modeled include product physics, consumer life-stage, certification tier, and distribution channel complexity. CAGRs were derived from trend extrapolation of millennial purchasing pattern shifts and digital payment infrastructure maturity. Climate stability testing protocols and halal certification reciprocity timelines served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under shipping cost volatility from Southeast Asian suppliers and accelerated ESMA framework expansion. Periodic stress-testing of base assumptions is recommended, particularly regarding SASO testing queue durations and biotechnology lab scale-up timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Underarm Antiperspirant and Deodorant Market
Beauty & Personal Care
UV Nail Gel Market
Beauty & Personal Care
Europe Hair Styling Products Market
Beauty & Personal Care
Netherlands Sustainable Personal Care Market
Beauty & Personal Care
Online Beauty and Personal Care Products Market
Beauty & Personal Care
Switzerland Haircare Market
Beauty & Personal Care
Global Hot Air Brushes Market
Beauty & Personal Care
Global Organic Hair Color Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
Shower Gel Market
Beauty & Personal Care
Rice Shampoo Bar Market
Beauty & Personal Care
China Electric Face Cleanser Market
Beauty & Personal Care
France Dermocosmetics Market
Beauty & Personal Care
Colombia Hair Care Market
Beauty & Personal Care
Magnetic Eyelashes Market
Beauty & Personal Care
Cosmetic Serum Market