
 North America Beauty and Personal Care Products Market | 2026-2036
North America Beauty and Personal Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America Beauty and Personal Care Products Market Analytics
Gen Z consumers is redrawing demand patterns across North America, shifting volume from traditional mass-market cosmetics toward ingredient-transparent skincare and personalized beauty routines. The Estée Lauder Companies Inc. leverages its prestige brand architecture to command premium positioning in specialty retail channels. Procter & Gamble Co. sustains mass-market dominance through manufacturing scale and drugstore distribution density. Glossier, Inc. differentiates via direct-to-consumer digital engagement and community-driven product development.
Beauty and personal care products encompass topical formulations designed for skin health, hair maintenance, color enhancement, and personal hygiene, typically comprising active ingredients such as retinoids, hyaluronic acid, and botanical extracts delivered through emulsion-based or anhydrous systems. These products serve commercial purposes ranging from therapeutic dermatological support to aesthetic self-expression and daily grooming rituals. Skincare leads absolute value contribution as consumers prioritize preventive aging and barrier-repair regimens, while fragrance experiences the fastest trajectory among discretionary categories as experiential retail rebounds. Online Retail captures expanding margin pools through subscription models and algorithmic personalization, though Specialty Stores retain defensible positions in premium makeup and professional-grade haircare.
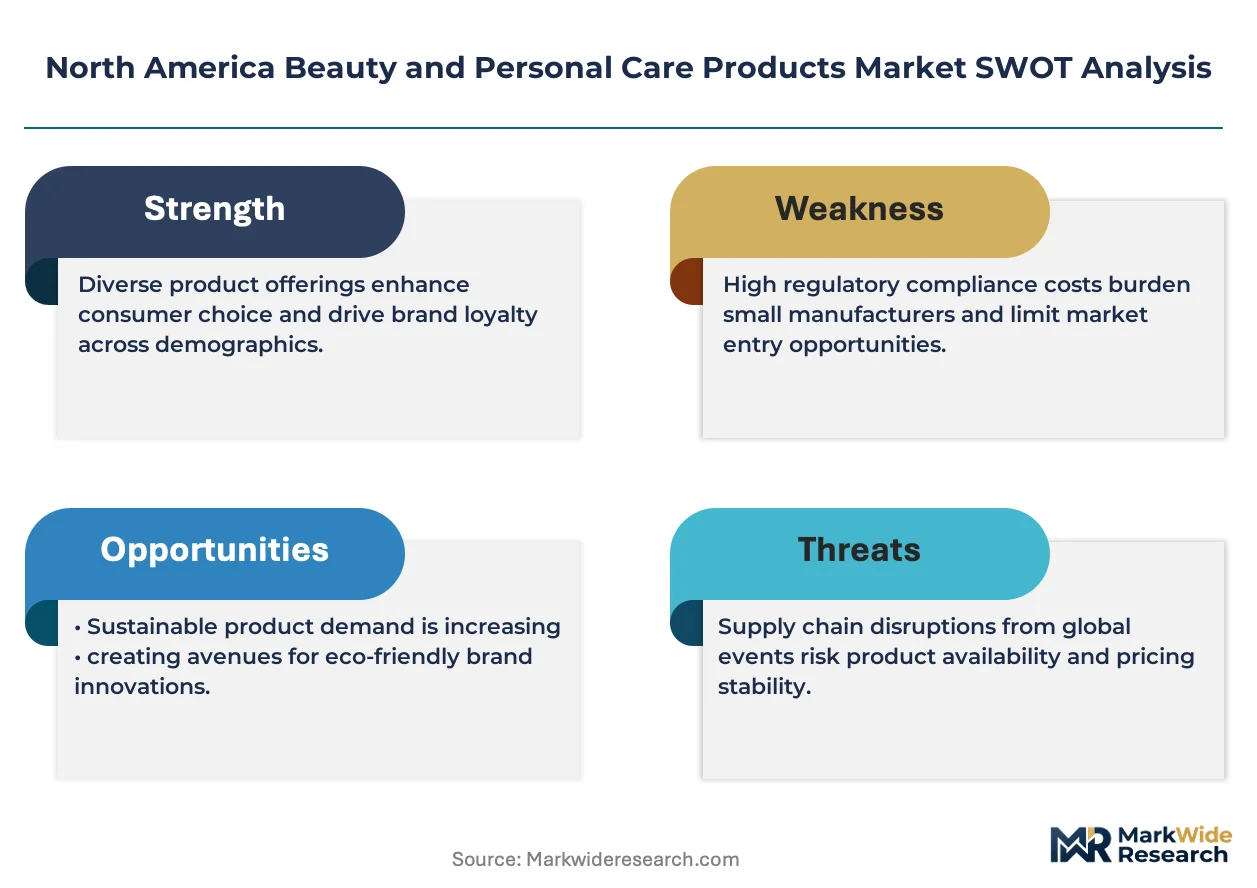
The FDA governs cosmetic safety through the Federal Food, Drug, and Cosmetic Act, while Health Canada administers the Cosmetic Regulations under the Food and Drugs Act, and California's Proposition 65 imposes additional ingredient disclosure burdens that ripple across North American supply chains. These frameworks elevate compliance costs for imported formulations while creating competitive shelter for domestic manufacturers with established regulatory infrastructure. Stakeholders must monitor pending federal fragrance allergen labeling rules and state-level per- and polyfluoroalkyl substance restrictions that threaten reformulation cycles across waterproof and long-wear categories.
Market Dynamics
Clean-label ingredient transparency is compressing formulation cycles across North American beauty supply chains, forcing manufacturers to rebuild R&D pipelines around biotech-derived actives and eliminate legacy preservative systems.
Growth Catalysts
- FDA Modernization Act 2.0:Federal mandate accelerates alternative testing method validation, reducing time-to-market for novel cosmetic actives and eliminating animal testing bottlenecks in California and New York state jurisdictions.
- Biotechnology fermentation platforms:Lab-grown squalane and collagen production is decoupling supply from agricultural commodity volatility, stabilizing input costs for premium skincare manufacturers.
- Urban corridor density:Toronto, Los Angeles, and New York City concentrate disposable income and specialty retail infrastructure, concentrating early adoption of personalized beauty diagnostics.
Market Restraints
- Per- and polyfluoroalkyl substance restrictions:California and New York state-level bans on PFAS in waterproof cosmetics force reformulation of long-wear foundations and mascaras, compressing margin pools in color cosmetics.
- Fragrance allergen disclosure mandates:Pending federal labeling rules from the FDA elevate compliance documentation burdens, particularly threatening small-batch indie brands lacking regulatory infrastructure.
- Glass and aluminum packaging shortages:Premium sustainable packaging material constraints limit capacity expansion for clean beauty brands targeting plastic-free positioning.
Strategic Opportunities
- Men's grooming underpenetration:Canadian and U.S. male consumers show lagging adoption of preventive skincare relative to female counterparts, presenting white space for barrier-repair and sun protection formulations.
- Subscription algorithmic personalization:Direct-to-consumer platforms leverage skin microbiome testing data to lock in recurring revenue through customized serum regimens.
- Health Canada cosmetic notification alignment:Harmonized North American regulatory pathways reduce dual-track compliance costs for cross-border brand expansion.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise in natural preservation systems and emulsion stability lags demand, elongating product development timelines for clean-label launches.
- Legacy ERP integration friction:Batch-level traceability requirements for ingredient transparency clash with decades-old manufacturing software, forcing costly system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Beauty and Personal Care Products Market |
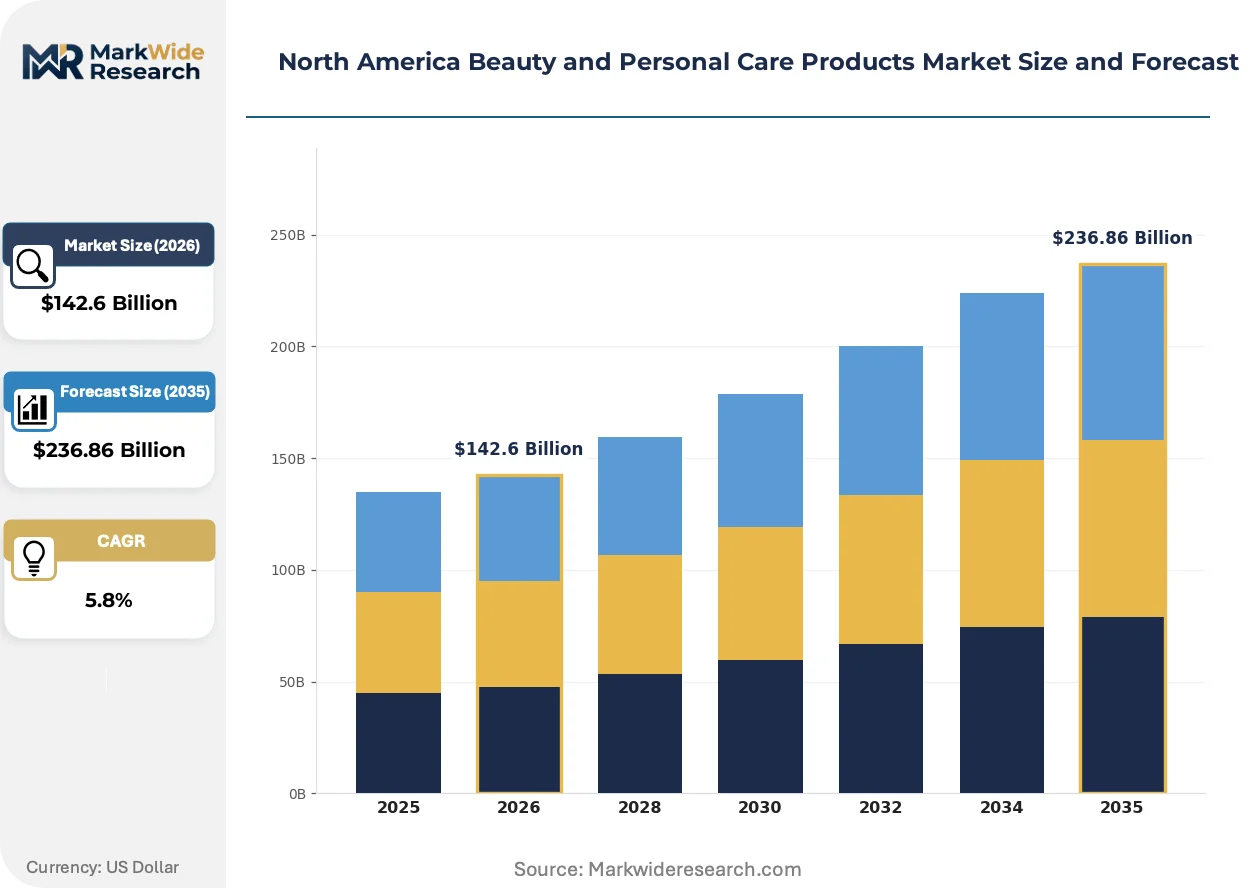
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $236.86 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Distribution Channel: Online Retail, Department Stores, Drugstores, Specialty Stores Customer Type: Women, Men, Teens, Professionals Formulation: Cream, Serum, Gel, Liquid |
| Companies Covered | Revlon, Colgate-Palmolive, The Estée Lauder Companies Inc., Glossier, Inc., Hims & Hers, Procter & Gamble Co., Coty Inc., ILIA Beauty, Johnson & Johnson Consumer Health, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Beauty and Personal Care Products Market Evolving Landscape
Biotechnology-derived ingredients and AI-powered skin diagnostics are collapsing traditional boundaries between cosmetics and therapeutics, while regulatory pressure on chemical transparency accelerates ingredient list simplification.
Lab-grown collagen and elastin produced through precision fermentation is supplanting marine and bovine-sourced alternatives in premium anti-aging formulations. Prestige skincare brands in Los Angeles and New York City are adopting these bioidentical proteins at 18-month replacement cycles. This shift is compressing supply chains previously dependent on Japanese and Brazilian agricultural inputs.
California's Proposition 65 enforcement expansion is mandating ingredient disclosure beyond federal FDA baseline requirements for cosmetic products sold in the state. The regulation cascades across North American supply chains as manufacturers standardize to the strictest common denominator. Waterproof and long-wear color cosmetics face the steepest compliance burdens due to historical reliance on undisclosed fluorinated compounds.
Algorithmic skin analysis through smartphone imaging is redirecting consumer purchasing from retail associate recommendations to data-driven regimen curation. Specialty store traffic in Toronto and Vancouver is declining as direct-to-consumer platforms capture diagnostic and fulfillment functions simultaneously. This behavioral pivot concentrates margin capture with platforms owning both data infrastructure and manufacturing relationships.
North America Beauty and Personal Care Products Market Segmentation
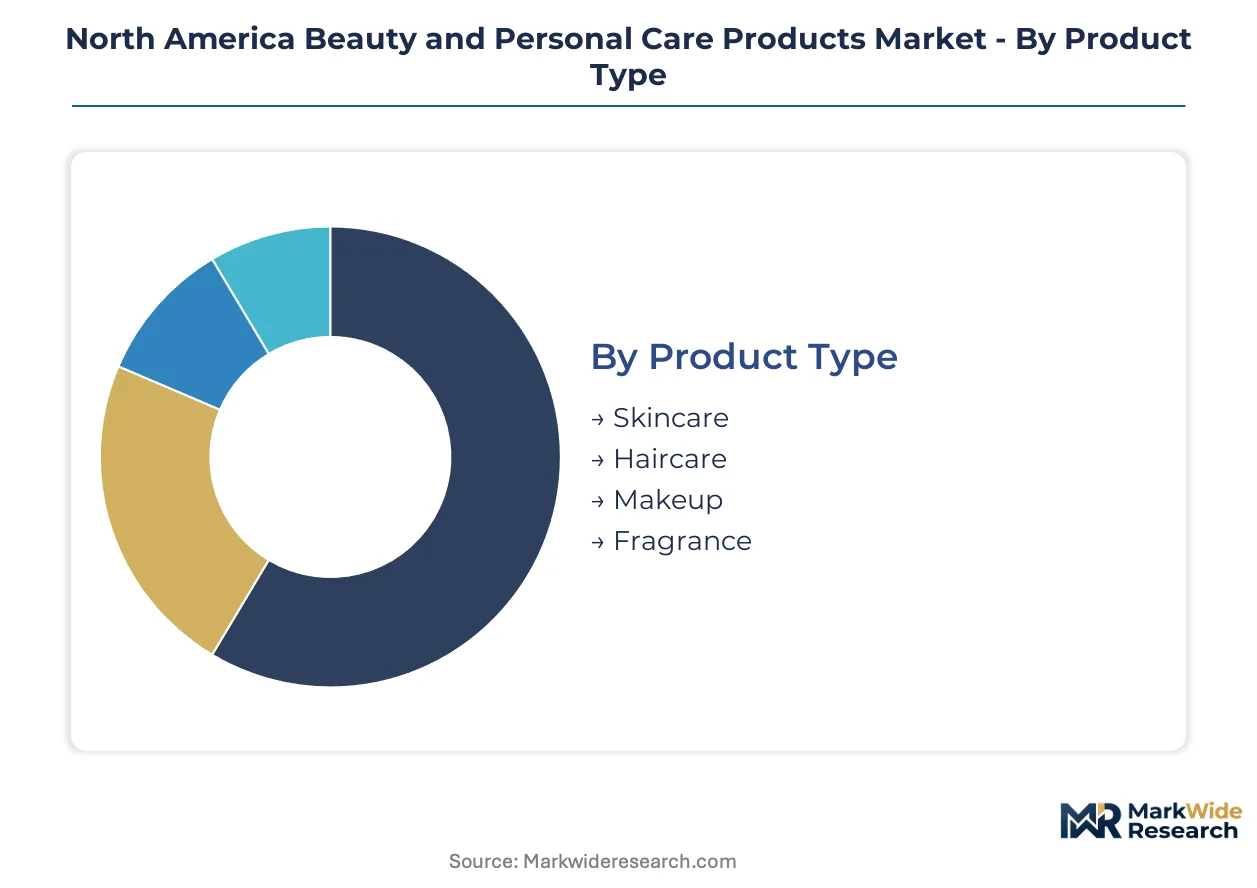
Segmentation in North American beauty markets reveals distinct margin architectures across product categories and channel strategies. Understanding substitution dynamics between mass and prestige tiers enables targeted resource allocation for formulation R&D and retail partnerships.
Product Type:
Substitution pressure intensifies as skincare serums displace traditional color cosmetics in discretionary spending baskets across urban Canadian and U.S. markets.
- Skincare:Emulsion-based and anhydrous formulations deliver retinoids, hyaluronic acid, and botanical actives for barrier repair and preventive aging regimens. Demand concentrates in premium serum and gel formulations across Los Angeles, New York City, and Toronto urban corridors as Gen Z consumers prioritize ingredient transparency over mass-market cosmetics.
- Haircare:Professional-grade shampoos, conditioners, and styling products target scalp health and damage repair through keratin and peptide delivery systems. Specialty Stores in Canadian and U.S. metropolitan areas retain defensible positions for salon-exclusive lines despite Online Retail expansion.
- Makeup:Color cosmetics face reformulation pressure from California and New York PFAS restrictions affecting waterproof foundations and mascaras.
- Fragrance:Discretionary category experiences experiential retail rebound as consumers return to in-person sampling.
Skincare retains volume leadership; Fragrance holds the steepest expansion curve.
Distribution Channel:
Cost tier stratification separates premium experiential retail from algorithmic direct-to-consumer platforms competing on personalization infrastructure.
- Online Retail:Subscription models and AI-powered skin diagnostics capture expanding margin pools through recurring revenue lock-in. Algorithmic personalization leverages skin microbiome testing data to customize serum regimens, redirecting purchasing from retail associate recommendations to data-driven curation.
- Specialty Stores:Sephora and Ulta Beauty maintain defensible positions in premium makeup and professional-grade haircare through in-store diagnostics and exclusive brand partnerships. Toronto and Vancouver traffic faces pressure as direct-to-consumer platforms consolidate diagnostic and fulfillment functions.
- Department Stores:Prestige brand architecture relies on counter-based consultation for high-consideration purchases.
- Drugstores:Mass-market dominance through manufacturing scale and convenience positioning serves routine replenishment shopping.
Online Retail captures margin expansion fastest; Specialty Stores defend premium positioning.
Customer Type:
Volume concentration varies sharply by demographic, with male underpenetration presenting white space against saturated female skincare adoption.
- Women:Core customer base drives preventive aging and personalized beauty routine adoption across all distribution channels.
- Men:Canadian and U.S. male consumers show lagging adoption of preventive skincare relative to female counterparts, creating opportunity for barrier-repair and sun protection formulations targeting simplified regimen positioning.
- Teens:Gen Z consumers redraw purchasing patterns toward clean-label formulations and community-driven product development.
- Professionals:Time-constrained urban workers favor multi-functional products combining treatment and cosmetic benefits.
Women anchor absolute volume contribution; Men represent the most underpenetrated expansion opportunity.
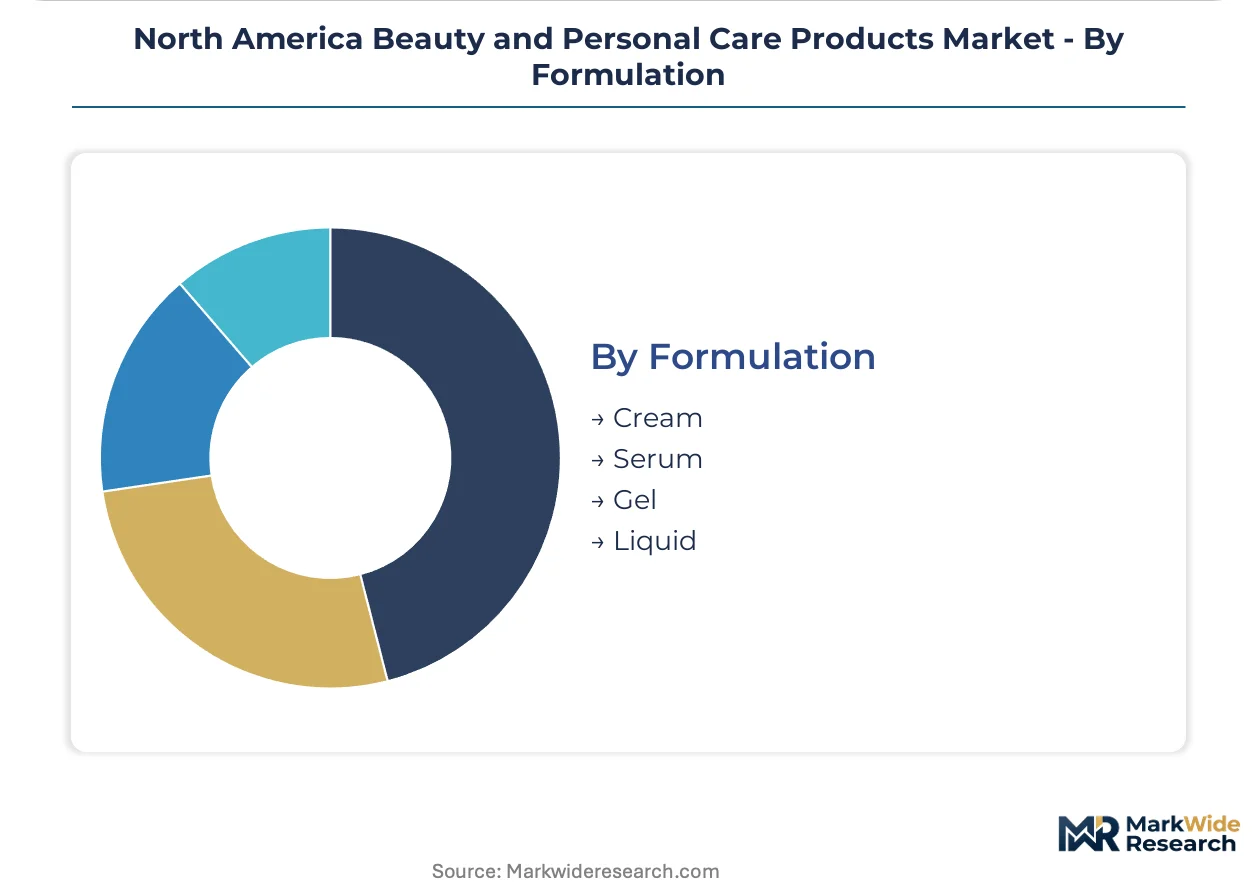
Formulation:
Supply concentration in biotechnology-derived actives favors serum and gel formats over legacy cream bases dependent on established preservative systems.
- Serum:High-concentration active delivery systems feature lab-grown collagen and elastin from precision fermentation platforms. Prestige brands in Los Angeles and New York City adopt bioidentical proteins at accelerated replacement cycles, compressing supply chains previously dependent on Japanese and Brazilian agricultural inputs.
- Gel:Lightweight, fast-absorbing vehicles suit humid climates and male consumer preferences for non-greasy textures. Water-based formulations align with clean-label ingredient transparency mandates spreading from California across North American supply chains.
- Cream:Traditional emulsion systems face reformulation pressure to eliminate legacy preservatives.
- Liquid:Spray and fluid formats serve haircare and fragrance applications with convenience positioning.
Serum commands premium pricing power; Gel gains share fastest among male and younger demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation expertise concentrates in coastal urban corridors where biotechnology fermentation platforms and specialty retail infrastructure overlap. Canada and the United States anchor regional supply, while Mexico emerges as a manufacturing alternative for mass-market production.
United States
California and New York state-level bans on PFAS in cosmetics are forcing reformulation of waterproof color cosmetics, while the FDA Modernization Act 2.0 accelerates alternative testing validation. Los Angeles and New York City concentrate premium serum adoption and direct-to-consumer platform headquarters, with Gen Z consumers driving clean-label ingredient transparency mandates.
Canada
Health Canada's Cosmetic Regulations impose notification requirements that ripple across North American supply chains as manufacturers standardize to stricter standards. Toronto and Vancouver urban corridors concentrate specialty retail traffic and early adoption of personalized beauty diagnostics, though direct-to-consumer platforms are compressing in-store footfall.
Mexico
Manufacturing cost advantages attract mass-market production for brands serving price-sensitive segments across North America. Mexico City anchors domestic demand for personal care essentials, while northern border states concentrate contract manufacturing facilities serving cross-border distribution networks.
North America Beauty and Personal Care Products Market Competitive Landscape
Concentration sits with prestige conglomerates and mass-market multinationals, with indie digital-native brands occupying fragmented niches. The competitive structure tiers across three archetypes: heritage prestige houses with specialty retail dominance, scale-driven mass-market manufacturers with drugstore density, and direct-to-consumer platforms leveraging algorithmic personalization. Dominant competitive moves include portfolio diversification into men's grooming and biotech-derived ingredient partnerships, alongside geographic expansion through cross-border regulatory harmonization.
Within the heritage prestige tier, The Estée Lauder Companies Inc. and Coty Inc. exemplify brand-architecture strategies built on counter-based consultation and exclusive retail partnerships. Revlon occupies a position in the mass-market tier alongside Colgate-Palmolive and Johnson & Johnson Consumer Health, representing manufacturing scale and pharmacy channel penetration. Glossier, Inc. anchors the digital-native archetype, while ILIA Beauty and Hims & Hers exemplify clean-label positioning and telehealth-integrated personalization respectively. Procter & Gamble Co. sits at the scale-driven end with unmatched distribution density across routine replenishment channels.
| Leading Market Players |
|---|
| Revlon |
| Colgate-Palmolive |
| The Estée Lauder Companies Inc. |
| Glossier, Inc. |
| Hims & Hers |
| Procter & Gamble Co. |
| Coty Inc. |
| ILIA Beauty |
| Johnson & Johnson Consumer Health |
| Others |
Value Network & Pricing Analysis
Ninety-day formulation cycles from concept to shelf placement concentrate pricing power with manufacturers commanding biotech fermentation capacity, while compressing margins for brands dependent on legacy preservative supply chains. This lead-time compression reshapes procurement priorities across clean-label and conventional product tiers.
Pricing Analysis
California's Proposition 65 dictates the pricing tier structure across North American beauty markets by imposing compliance cost differentials that stratify brands by regulatory infrastructure depth. Three-tier pricing structure across premium, standard, and economy levels separates biotech-enabled prestige formulations from mass-market alternatives, with certification-grade ingredient transparency commanding measurable premiums. Price erosion runs through waterproof color cosmetics as PFAS reformulation costs cascade through manufacturing. Indie brands exhibit highest price sensitivity due to fragmented regulatory compliance investments, while prestige conglomerates absorb documentation burdens within existing legal frameworks.
Supply Chain Analysis
Ninety-day formulation cycles expose vulnerability in glass and aluminum packaging procurement, where sustainable material shortages constrain capacity expansion for plastic-free positioning. Biotechnology fermentation platforms in the United States, South Korea, and Japan anchor supply for lab-grown squalane and collagen, drawing from precision fermentation infrastructure previously serving pharmaceutical applications. Single-source vulnerability concentrates in Japanese and Brazilian agricultural inputs for marine and bovine-derived alternatives. Distribution runs through specialty retail corridors in Los Angeles, New York City, and Toronto, with direct-to-consumer platforms capturing diagnostic and fulfillment integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Men's grooming underpenetration signals early-cycle expansion potential, with Canadian and U.S. male consumers showing lagging preventive skincare adoption relative to saturated female segments.
For Market Incumbents: Fortify regulatory infrastructure investments to absorb pending FDA fragrance allergen disclosure mandates that threaten small-batch competitors lacking compliance scale. Deepen backward integration into biotech fermentation partnerships securing captive supply of lab-grown actives. Expand capacity in Toronto and Vancouver urban corridors where specialty retail retains defensible positioning against direct-to-consumer platform consolidation. For New Entrants and Emerging Players: Health Canada cosmetic notification alignment offers accelerated cross-border market access relative to dual-track FDA compliance pathways. Target men's barrier-repair and sun protection formulations as the most penetrable white space against female-skewed incumbent portfolios. Deploy telehealth-integrated personalization as the primary go-to-market angle, mirroring Hims & Hers architecture without replicating their specific execution. For Investors and Strategic Acquirers: Carve-out targets emerge from mass-market conglomerates divesting non-core color cosmetics exposed to PFAS reformulation headwinds. Position portfolio construction around five-to-ten year biotechnology ingredient transitions, favoring platforms with fermentation partnerships over legacy agricultural supply chains. Monitor FDA fragrance allergen rule finalization as the critical inflection signal for compliance cost reallocation across tier structures.| Strategic Initiative | Industry Significance |
|---|---|
| Biotech Ingredient Partnership | Precision fermentation secures supply of lab-grown collagen independent of Japanese and Brazilian agricultural volatility. |
| Direct-to-Consumer Platform Launch | Algorithmic skin diagnostics capture recurring revenue through subscription serum regimens displacing retail associate recommendations. |
| Men's Grooming Line Extension | Simplified regimen positioning addresses underpenetration in Canadian and U.S. male preventive skincare adoption. |
| Cross-Border Regulatory Harmonization | Health Canada alignment reduces dual-track compliance costs for U.S. brands expanding into Toronto and Vancouver corridors. |
| Sustainable Packaging Transition | Glass and aluminum sourcing investments defend plastic-free positioning against material shortage constraints. |
Research Methodology
The analysis maps skincare, haircare, makeup, and fragrance sub-sectors, each validated through formulation chemists, specialty retail category buyers, direct-to-consumer platform operators, and regulatory affairs specialists. Primary interviews with cosmetic brand managers, biotechnology fermentation facility directors, and Health Canada notification officers combine with secondary validation against FDA Modernization Act 2.0 legislative text, California Proposition 65 enforcement records, Nielsen retail audit data, and SEC filings from publicly traded beauty conglomerates. Bottom-up volume builds from urban corridor demand clusters triangulate against top-down market sizing from trade association production estimates.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon, with segmentation modeling spanning product type, distribution channel, customer demographic, and formulation technology dimensions. CAGRs derive from regression analysis of historical adoption curves adjusted for regulatory inflection points and biotechnology cost reduction trajectories. Forecast inputs incorporate PFAS restriction implementation timelines, precision fermentation capacity expansion announcements, and urban disposable income concentration patterns.
Underlying assumptions cover regulatory enforcement intensity, biotechnology scale-up timelines, and male consumer adoption elasticity, with deviation risk concentrated in FDA fragrance allergen rule finalization timing and sustainable packaging material availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Emea Beauty Devices Market
Beauty & Personal Care
Personal Care Products Market
Beauty & Personal Care
Oil Control Lotion Market
Beauty & Personal Care
Electric Nail Files Market
Beauty & Personal Care
Makeup Setting Spray Market
Beauty & Personal Care
Online Beauty and Personal Care Products Market
Beauty & Personal Care
LAMEA Hair Removal Wax Market
Beauty & Personal Care
Facial Wipes Market
Beauty & Personal Care
Skin Care Luxury Cosmetic Market
Beauty & Personal Care
North America Hair Removal Wax Market
Beauty & Personal Care
Europe Professional Beauty Services Market
Beauty & Personal Care
Nail Care Market
Beauty & Personal Care
Australia Beauty and Personal Care Products Market
Beauty & Personal Care
Home Use Anti-Aging Beauty Device Market
Beauty & Personal Care
Asia-Pacific Perms and Relaxants Market
Beauty & Personal Care
Shaving Foam Market