
 United Kingdom Luxury Goods Market | 2026-2036
United Kingdom Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Luxury Goods Market Outlook
Aftermarket service revenue is fragmenting across authentication, resale certification, and repair networks as circular economy models penetrate luxury ownership. Burberry Group plc extends its vertical control through in-house trench coat manufacturing at its Castleford facility. LVMH Moet Hennessy Louis Vuitton anchors its UK position with dedicated atelier services and bespoke clienteling at its London flagship. Kering SA differentiates through intensified leather goods R&D and sustainability traceability investments across its British operations.
Luxury goods encompass premium apparel, accessories, leather goods, timepieces, and jewelry characterized by superior materials, artisanal construction, and price positioning that insulates demand from mass-market cyclicality. British heritage manufacturing traditions, including hand-stitched leatherwork and bespoke tailoring, define product authenticity and justify persistent price premiums. Jewelry and handbags command the deepest margin pools within product type segmentation, while online retail and private sales channels capture the fastest growth trajectories as digital authentication technologies reduce perceived purchase risk. Heritage and craftsmanship dimensions of brand perception sustain pricing power among established houses, though innovation signals increasingly influence millennial acquisition decisions.
UK Trading Standards enforces Consumer Rights Act protections and anti-counterfeiting measures that elevate compliance costs for import-dependent brands. The UK's Modern Slavery Act and forthcoming extended producer responsibility frameworks pressure supply chain restructuring toward verifiable ethical sourcing. Stakeholders must monitor evolving post-Brexit customs arrangements and their impact on EU-UK goods circulation before committing to fixed distribution infrastructure.
Market Dynamics
Digital-native millennials maturing into core buyers are compressing purchase cycles while demanding authentication transparency, forcing heritage houses to reconfigure clienteling infrastructure around blockchain-verified provenance and immersive retail environments.
Growth Catalysts
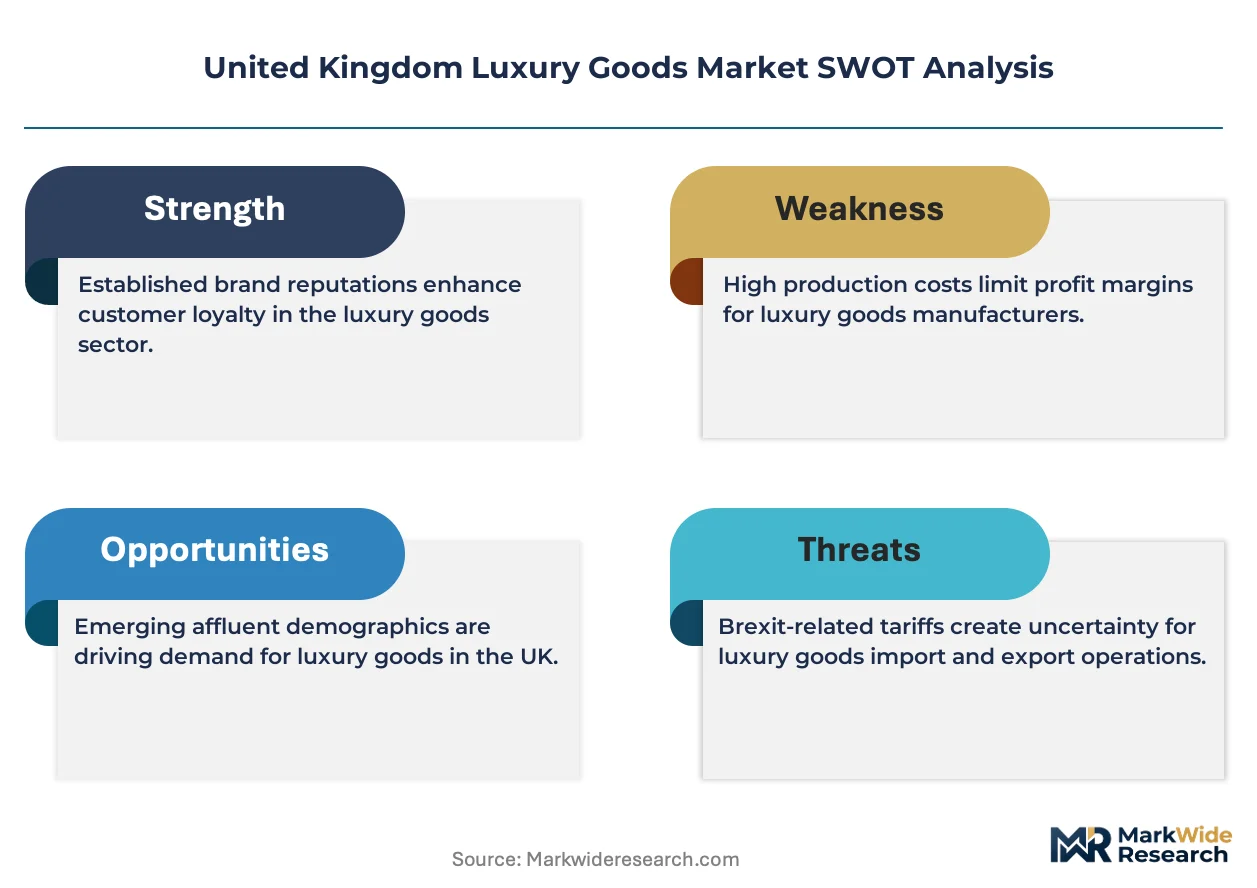
- Modern Slavery Act compliance:Mandatory supply chain disclosure obligations for precious metals and gemstones sourcing are accelerating investment in ethical extraction partnerships and third-party auditing infrastructure.
- Millennial wealth accumulation:Maturing digital-native cohorts are expanding their share of high-value purchases, prioritizing brands with demonstrable sustainability credentials and immersive digital experiences.
- London flagship concentration:Bond Street and Mayfair retail corridors concentrate demand gravity, where physical presence signals brand legitimacy and anchors omnichannel client acquisition.
Market Restraints
- Precious metal price volatility:Gold and platinum input cost fluctuations compress margin predictability for jewelry and watch manufacturers dependent on fixed-price heritage collections.
- Artisan labor scarcity:Hand-stitched leatherwork and bespoke tailoring skill pools are contracting as British craft apprenticeship pipelines fail to replenish retiring master craftspeople.
- Post-Brexit customs friction:Evolving EU-UK goods circulation arrangements create inventory positioning uncertainty for import-dependent brands with continental European supply nodes.
Strategic Opportunities
- Scottish and Northern English secondary cities:Manchester, Edinburgh, and Glasgow present underpenetrated wealth concentrations where localized flagship formats can capture dispersed affluent demand.
- Circular economy certification:Resale authentication and repair network investments unlock recurring revenue streams as secondary market legitimacy reduces perceived purchase risk.
- Extended producer responsibility frameworks:Forthcoming UK regulations mandating end-of-life product stewardship create first-mover advantage for brands with established take-back and refurbishment infrastructure.
Industry Challenges
- Digital authentication integration:Embedding NFC and blockchain verification into legacy product lines demands substantial retooling of manufacturing workflows without disrupting heritage craftsmanship positioning.
- Atelier talent retention:Competing compensation packages from technology and financial services sectors drain specialized leatherwork and horology expertise from established British houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Luxury Goods Market |
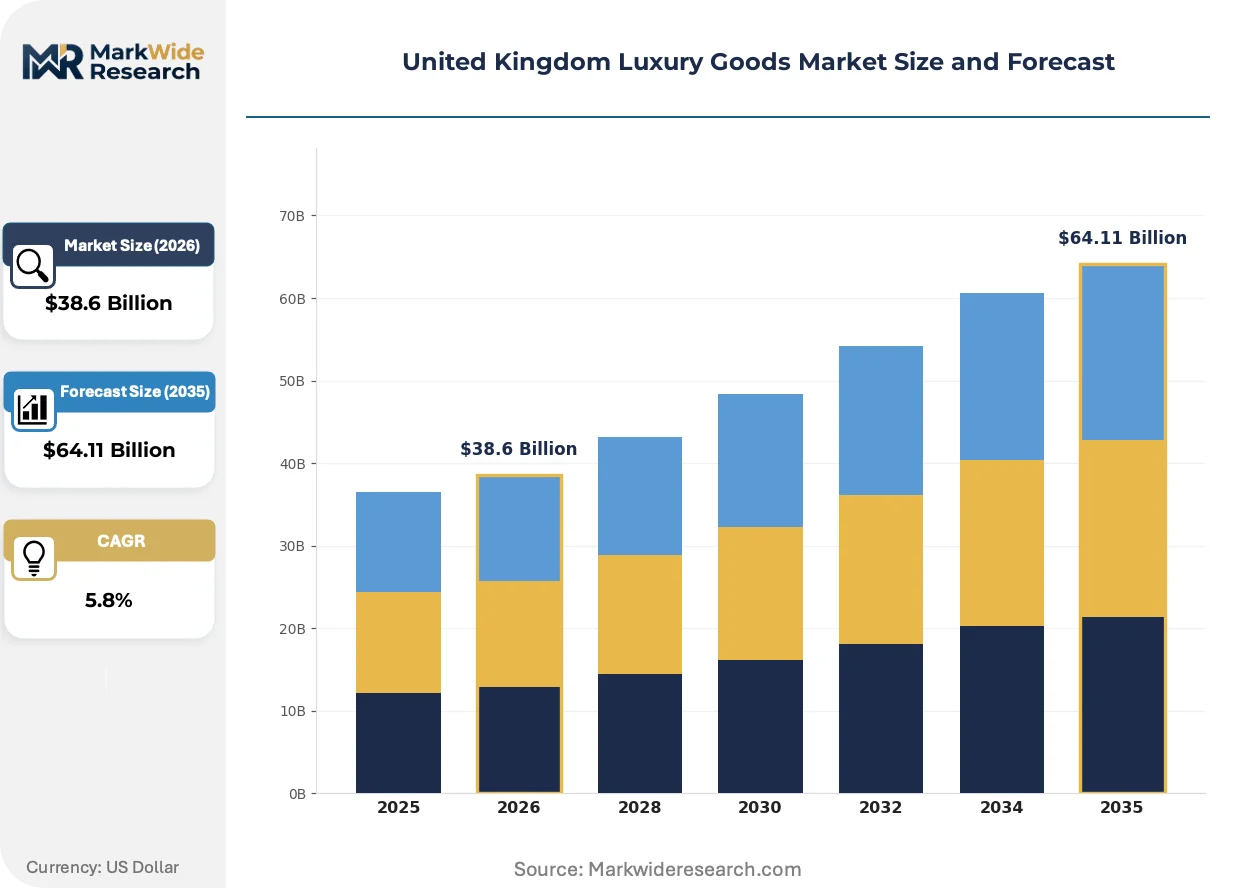
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jewelry, Handbags, Apparel, Footwear Customer Type: Affluent Consumers, Millennials, Baby Boomers, Celebrities Sales Channel: Online Retail, Department Stores, Specialty Shops, Private Sales Brand Perception: Heritage, Exclusivity, Craftsmanship, Innovation |
| Companies Covered | Kering SA, Mulberry Group plc, LVMH Moet Hennessy Louis Vuitton, Harrods, Jimmy Choo, Compagnie Financière Richemont S.A., Chanel Limited, Selfridges, Burberry Group plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Luxury Goods Market Strategic Shifts
Immersive technologies and regulatory transparency mandates are compressing the distance between craftsmanship narrative and verifiable product provenance, reshaping how heritage authenticity is constructed and communicated.
Blockchain-based provenance tracking is virtualizing the authentication function that physical certificates and dealer relationships previously monopolized. Younger collectors now expect immutable ownership records accessible via smartphone, pressuring established houses to retrofit digital infrastructure onto archival inventory systems. This shift is virtualizing trust mechanisms and fragmenting authentication revenue across technology vendors and certification platforms.
The UK's Modern Slavery Act transparency requirements are mandating granular supply chain disclosure for precious metals and gemstone sourcing. Trading Standards enforcement of Consumer Rights Act protections elevates compliance costs while creating competitive differentiation for early ethical sourcing adopters. Jewelry and watch segments with complex multi-tier supplier networks face the steepest restructuring burdens.
Secondary market legitimacy is displacing stigma around pre-owned luxury acquisition. Digital-native buyers now treat authenticated resale platforms as primary discovery channels, compressing traditional retail's role in customer education. This behavioral pivot is most visible in London, where consignment boutiques and digital resale interfaces capture growing share of handbag and timepiece transactions among under-40 purchasers.
United Kingdom Luxury Goods Market Segmentation
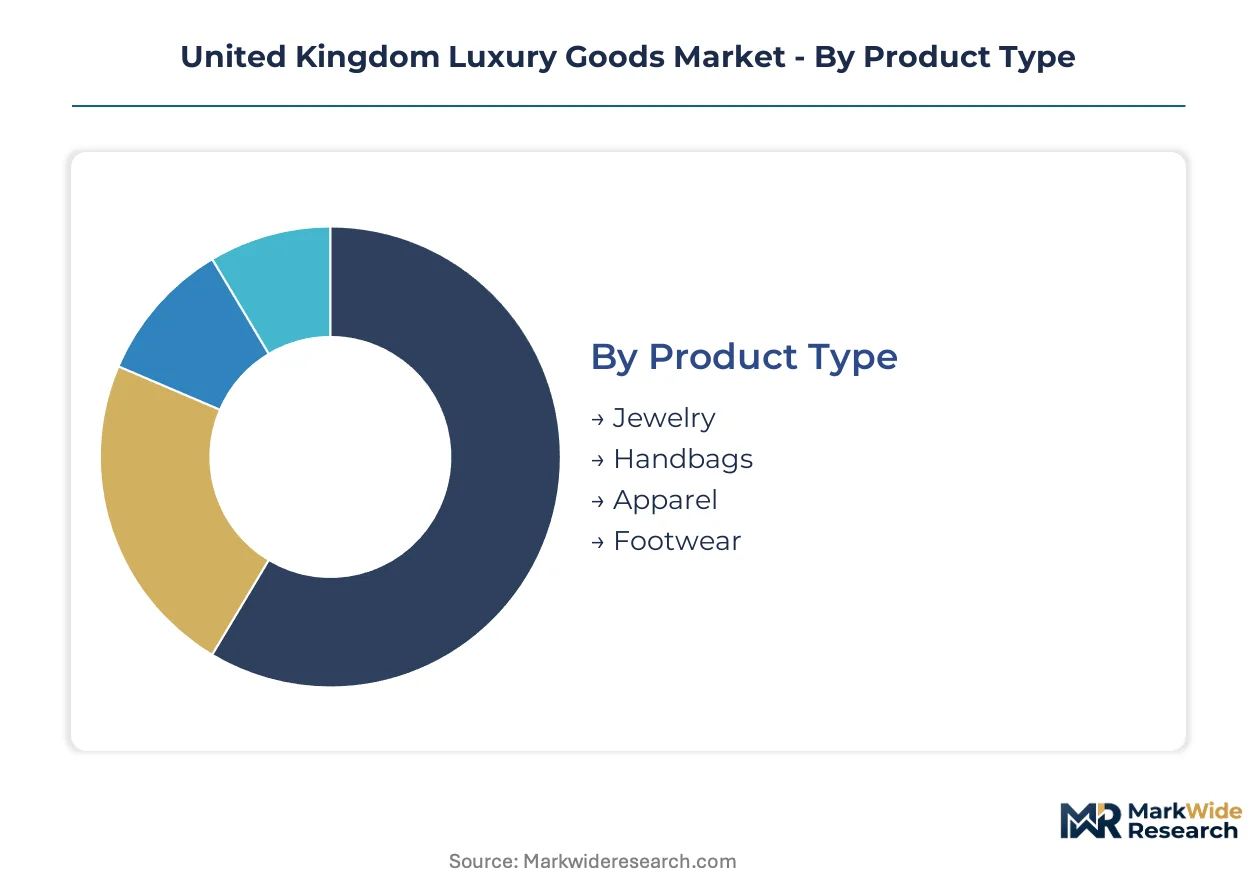
Segmentation in the UK luxury goods market reveals how purchasing power, channel preference, and brand meaning fragment across distinct buyer psychographies. Understanding these divides allows houses to allocate atelier capacity, flagship investment, and digital infrastructure against the highest-yield combinations.
Product Type:
Demand intensity varies sharply across use-case spectrum from ceremonial acquisition to daily utility, with margin structure and authentication complexity diverging accordingly.
- Jewelry:Precious metal and gemstone compositions command the deepest margin pools within luxury, with platinum and ethically sourced sapphire concentrations anchoring price premiums. Bond Street boutiques concentrate high-value transactions where Modern Slavery Act disclosure requirements now shape sourcing partnerships.
- Handbags:Artisanal leather construction with hand-stitched detailing defines authenticity markers for British heritage houses. Manchester and Edinburgh present underpenetrated demand where localized flagship formats can capture dispersed affluent buyers seeking exclusivity signals.
- Apparel:Bespoke tailoring traditions sustain pricing power through Savile Row and Mayfair atelier networks.
- Footwear:Hand-finished leather soles and bench-made construction differentiate premium positioning from mass-market alternatives.
Established volume favors jewelry; emerging adoption favors handbags.
Customer Type:
Wealth accumulation timelines and digital nativity create divergent service expectations across generational cohorts.
- Affluent Consumers:High-net-worth individuals with established collection practices prioritize provenance documentation and atelier access over price sensitivity. London's private sales channels capture this segment through invitation-only presentations and bespoke commissioning relationships.
- Millennials:Maturing digital-native cohorts compress purchase cycles while demanding blockchain-verified sustainability credentials. Glasgow and secondary city flagships gain traction as this group disperses beyond traditional London concentration.
- Baby Boomers:Long-tenured brand relationships anchor loyalty through heritage recognition and craftsmanship appreciation.
- Celebrities:Visibility-driven acquisition patterns create amplification effects for emerging designer visibility.
Affluent consumers anchor current revenue; millennials drive channel transformation.
Sales Channel:
Authentication technology maturity is redistributing purchase risk perception across physical and digital touchpoints.
- Online Retail:Digital authentication interfaces with NFC verification and blockchain provenance tracking reduce perceived purchase risk for remote buyers. This channel is climbing the fastest as younger collectors treat authenticated resale platforms as primary discovery channels.
- Department Stores:Curated concessions within Harrods and Selfridges maintain relevance through experiential service layers that pure digital cannot replicate.
- Specialty Shops:Independent boutiques in Mayfair and Knightsbridge sustain clienteling depth for ultra-high-net-worth relationship management.
- Private Sales:Invitation-only presentations capture ceremonial and investment-grade acquisitions outside public retail visibility.
Physical presence dominates transaction value; digital infrastructure captures acquisition frequency.
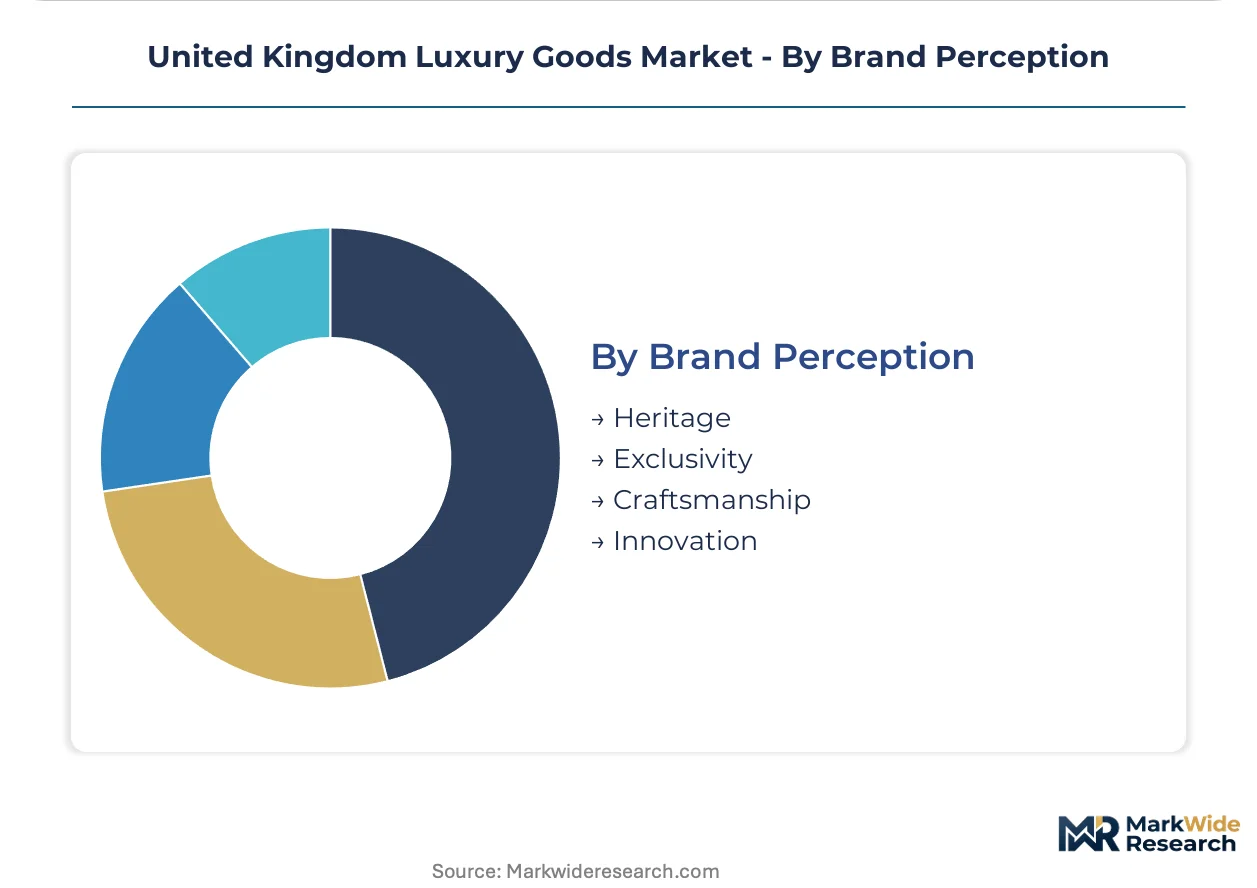
Brand Perception:
Competitive positioning hinges on dimensional emphasis across authenticity markers and forward signals.
- Heritage:British manufacturing lineage and archival design codes justify persistent price premiums through narrative authority. Castleford trench coat production and Savile Row bench traditions exemplify this positioning.
- Exclusivity:Controlled distribution and limited production runs create scarcity value that insulates demand from mass-market cyclicality.
- Craftsmanship:Visible handwork and master artisan attribution sustain authenticity perception against mechanized alternatives.
- Innovation:Materials science advancement and digital integration signals increasingly influence millennial acquisition decisions alongside traditional markers.
Craftsmanship anchors established houses; innovation differentiates emerging challengers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across UK sub-regions. London buyers exhibit the lowest sensitivity to premium positioning, while Northern England and Welsh consumers demand stronger value justification for heritage pricing.
London and Southeast
Bond Street and Mayfair flagships concentrate ultra-high-net-worth transactions where provenance documentation commands decisive weight. The UK's Modern Slavery Act enforcement pressures jewelry houses to disclose ethical sourcing credentials. Knightsbridge ateliers anchor bespoke commissioning relationships for international collectors.
Midlands
Birmingham's jewelry quarter sustains artisan metalworking traditions that feed heritage brand supply chains. Trading Standards enforcement of Consumer Rights Act protections elevates compliance costs for regional manufacturers. Leicester's leatherworking clusters face artisan labor scarcity as apprenticeship pipelines contract.
North England
Manchester and Liverpool present underpenetrated wealth concentrations where localized flagship formats capture dispersed affluent demand. Post-Brexit customs friction creates inventory uncertainty for brands routing continental European supply through northern distribution nodes. Yorkshire's textile heritage informs emerging sustainable manufacturing partnerships.
Scotland
Edinburgh and Glasgow millennial cohorts compress purchase cycles while demanding blockchain-verified sustainability credentials. The Scottish Government's circular economy strategy pressures brands to establish take-back infrastructure. Aberdeen's energy wealth sustains private sales channel activity outside London visibility.
Wales
Cardiff's emerging affluent segment exhibits stronger price elasticity than English counterparts, demanding innovation signals alongside heritage positioning. Extended producer responsibility frameworks forthcoming from Westminster pressure supply chain restructuring. Welsh wool and textile traditions offer niche authenticity markers for specialized collections.
United Kingdom Luxury Goods Market Competitive Environment
Capability concentration sits with heritage atelier networks; scale advantage sits with diversified luxury conglomerates. The market structures around three tiers: integrated fashion houses with captive manufacturing, multi-brand retail platforms with experiential service layers, and independent leather goods specialists with regional craft anchoring. Dominant competitive moves include vertical integration into in-house production and circular economy certification investments that lock in secondary market legitimacy.
Within the heritage house tier, Burberry Group plc and Mulberry Group plc represent British manufacturing lineage archetypes, while LVMH Moet Hennessy Louis Vuitton anchors the scale-driven conglomerate position. Kering SA and Compagnie Financière Richemont S.A. occupy diversified portfolio positions across leather goods and hard luxury segments. Chanel Limited exemplifies the controlled distribution scarcity model, with Jimmy Choo representing specialist footwear positioning. Retail platform archetypes include Harrods and Selfridges, which sustain relevance through curated concessions and experiential service layers that pure digital channels cannot replicate.
| Leading Market Players |
|---|
| Kering SA |
| Mulberry Group plc |
| LVMH Moet Hennessy Louis Vuitton |
| Harrods |
| Jimmy Choo |
| Compagnie Financière Richemont S.A. |
| Chanel Limited |
| Selfridges |
| Burberry Group plc |
| Others |
Value Chain & Pricing Dynamics
Castleford's in-house trench coat manufacturing capacity anchors Burberry's pricing autonomy against import-dependent competitors, converting captive production into sustained margin premiums across heritage outerwear lines. This geographic concentration of artisan skill directly shapes downstream pricing power for British houses competing with continental conglomerates.
Pricing Analysis
Aftermarket service revenue from authentication, resale certification, and repair networks now drives lifetime value capture as circular economy models mature. Three-tier pricing structure across heritage, contemporary, and entry-level collections stratifies access points while preserving exclusivity signaling. Pricing pressure stems from artisan labor scarcity as apprenticeship pipelines fail to replenish retiring master craftspeople. Affluent collectors exhibit lowest price sensitivity, while aspirational millennials demand stronger value justification for entry-tier acquisitions.
Supply Chain Analysis
Tariff exposure between the European Union and United Kingdom dominates supply chain risk calculus for import-dependent brands routing continental components through British distribution nodes. Manufacturing concentration rests on Italy for leather tanning, Switzerland for horology movements, and India for precious gemstone cutting. Raw material dependencies include ethically sourced platinum, full-grain vegetable-tanned leather, and conflict-free sapphires. Distribution runs through London flagship anchoring with secondary city satellite formats capturing dispersed northern demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom luxury goods market sits in cyclical recovery as millennial wealth accumulation normalizes post-volatility spending patterns. This demographic maturation provides the cyclical driver justifying strategic repositioning across stakeholder archetypes.
For Market Incumbents: Insulate heritage positioning against digital-native challengers by embedding NFC authentication into archival product lines and expanding Castleford-style captive manufacturing to leather goods categories. Channel control through private sales networks in Mayfair and Knightsbridge preserves ultra-high-net-worth relationships from platform disintermediation. Certification investment in Modern Slavery Act compliance creates competitive moats against slower-adapting rivals.
For New Entrants and Emerging Players: Manchester and Edinburgh present underpenetrated wealth concentrations where localized flagship formats can capture dispersed affluent demand outside London saturation. Glasgow's millennial cohort compresses purchase cycles while demanding blockchain-verified sustainability credentials, creating entry wedge for digitally native positioning. Go-to-market angle should emphasize authenticated resale platform partnerships as primary discovery channels rather than traditional retail buildout.
For Investors and Strategic Acquirers: Long-term, this sits as a brand-arbitrage play because heritage manufacturing lineage commands persistent valuation premiums against pure digital-native challengers. Acquisition target archetype includes independent leather goods specialists with regional craft anchoring in Yorkshire or Scottish textile traditions. Signal to watch is Modern Slavery Act enforcement intensity as inflection indicator for compliance-cost winners versus losers.
| Strategic Initiative | Industry Significance |
|---|---|
| Circular Economy Certification | Establishes secondary market legitimacy through authenticated resale platform partnerships. |
| Atelier Talent Retention Programs | Counteracts technology sector compensation drains on specialized leatherwork expertise. |
| Blockchain Provenance Integration | Virtualizes trust mechanisms for digital-native collectors demanding smartphone-accessible ownership records. |
| Scottish Flagship Expansion | Captures Edinburgh and Glasgow millennial demand dispersing beyond traditional London concentration. |
| Extended Producer Responsibility Infrastructure | Creates first-mover advantage as Westminster mandates end-of-life product stewardship frameworks. |
Study Parameters
The analysis maps jewelry, leather goods, apparel, and timepiece segments, each validated through atelier directors, heritage brand supply chain managers, luxury retail buyers, and circular economy platform operators. Primary interviews combined with secondary validation from UK Trading Standards enforcement records, Modern Slavery Act disclosure filings, and customs trade data. Bottom-up demand modeling and top-down market sizing triangulate volume estimates.
Assumptions held fixed include regulatory enforcement intensity of existing disclosure frameworks and millennial wealth trajectory normalization, while precious metal price volatility and post-Brexit customs arrangements were treated as scenario variables. Segmentation dimensions span product type, customer generation cohort, sales channel authentication maturity, and brand perception archetype. CAGRs derived from trend extrapolation against historical cyclical patterns, with artisan labor supply elasticity and digital authentication adoption curves as key forecast inputs.
Practitioners should monitor Modern Slavery Act enforcement actions and secondary market platform transaction volumes for early signals of forecast deviation. Forecasts reflect assumptions about regulatory stability and generational spending normalization, with precious metal cost spikes or customs disruption presenting specific revision risks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Luxury Mechanical Watches Market
Luxury Goods
Hard Luxury Goods Market
Luxury Goods
Secondhand Luxury Goods Market
Luxury Goods
GCC Secondhand Luxury Goods Market
Luxury Goods
Wooden Watch Market
Luxury Goods
Russia Luxury Goods Market
Luxury Goods
Global Gold and Diamond Jewellery Market
Luxury Goods
Luxury Pen Market
Luxury Goods
Personal Luxury Goods Market
Luxury Goods
China Luxury Goods Market
Luxury Goods
Luxury Products for Kids Market
Luxury Goods
Luxury Piano Market
Luxury Goods
Thailand Luxury Goods Market
Luxury Goods
Brazil Luxury Jewelry Market
Luxury Goods
GCC Luxury Goods Market
Luxury Goods
Luxury Goods Market