
 Asia-Pacific Luxury Goods Market | 2026-2036
Asia-Pacific Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Luxury Goods Market Analysis
China is fragmenting as luxury brands expand domestic manufacturing and localized design studios to reduce import dependency and accelerate product-to-market cycles. LVMH Moet Hennessy Louis Vuitton SE anchors its regional footprint through vertically integrated leather workshops in Guangzhou and Hangzhou. Chanel SA differentiates via exclusive métiers d'art partnerships that preserve artisanal craft clusters across the Pearl River Delta. Kering SA competes through aggressive digital integration, linking mainland e-commerce platforms directly with Italian and French ateliers for made-to-order services.
Asia-Pacific luxury goods encompass premium apparel, leather accessories, fine jewelry, watches, and beauty products characterized by superior craftsmanship, rare material provenance, and heritage brand equity, typically retailing through controlled distribution to maintain scarcity value and price integrity. The primary commercial purpose centers on signaling social status while delivering durable, collectible assets with residual resale value. Accessories and handbags lead absolute revenue contribution due to lower production complexity and higher margin retention versus ready-to-wear. Online distribution channels represent the fastest-growing segment as live-stream commerce and WeChat mini-programs convert younger demographics. Super luxury positioning occupies the deepest profit pool, where Hermès International SA and Rolex SA sustain waiting-list mechanisms that insulate pricing power from cyclical volatility.
China's SAMR enforces anti-counterfeiting protocols and cross-border e-commerce standards that dictate authentication technology investments for market entry. Japan's METI and Consumer Affairs Agency coordinate luxury resale regulations and import duty structures that shape parallel market dynamics across East Asia. India's BIS certification requirements for precious metal jewelry create compliance thresholds that filter unauthorized entrants. Stakeholders must monitor regulatory divergence between ASEAN member states as harmonized customs frameworks remain incomplete, fragmenting logistics strategies across Southeast Asian expansion plans.

Market Dynamics
Live-stream commerce infrastructure is compressing purchase cycles across the Asia-Pacific luxury goods sector, forcing heritage houses to rebuild fulfillment networks around same-day delivery expectations in Shanghai, Seoul, and Tokyo.
Growth Catalysts
- China's dual carbon goals:MEE emissions standards accelerate sustainable material substitution in leather tanning and precious metal refining, opening certified supply pools for compliant brands.
- Japan's METI circular economy framework:Formalized luxury resale channels legitimize secondary markets, extending product lifecycles and reducing new-unit production pressure.
- Live-stream commerce penetration:Douyin and Kuaishou algorithmic targeting converts Gen-Z browsers in tier-two Chinese cities at conversion rates multiples above traditional e-commerce.
Market Restraints
- Raw material concentration:Italian and French tanneries control premium calfskin supply, exposing brands to euro-denominated input volatility and six-month order backlogs.
- Cross-border authentication friction:China's SAMR e-commerce standards mandate blockchain traceability investments that filter smaller entrants lacking capital reserves.
- Artisan labor scarcity:Pearl River Delta embroidery and métiers d'art clusters face generational attrition as younger workers migrate to tech manufacturing.
Strategic Opportunities
- India's BIS precious metal certification:Formalized compliance pathways create first-mover advantage for jewelry houses establishing local hallmarking infrastructure ahead of market maturation.
- WeChat mini-program ecosystems:Closed-loop social commerce enables direct clienteling without platform commission structures, preserving margin in mainland China.
- Vietnam and Indonesia manufacturing:ASEAN tariff differentials and emerging craft training centers support regional production diversification beyond China-centric supply.
Industry Challenges
- Blockchain implementation complexity:SAMR anti-counterfeiting mandates require interoperable traceability systems that conflict with legacy ERP architectures and multi-brand retail partnerships.
- Atelier-to-warehouse reconfiguration:Made-to-order service promises strain Italian and French production schedules, creating fulfillment bottlenecks during peak gifting seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Luxury Goods Market |
| Market Size in 2026 | $287.6 Billion |
| Market Size in 2035 | $519.91 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Footwear, Accessories, Handbags Distribution Channel: Online, Department Stores, Specialty Stores, Luxury Boutiques Customer Type: Affluent Consumers, High-Net-Worth Individuals, Millennials, Gen Z Brand Positioning: Premium, Super Luxury, Contemporary, Emerging |
| Companies Covered | Chanel SA, Rolex SA, LVMH Moet Hennessy Louis Vuitton SE, Burberry Group Plc, Prada SpA, Kering SA, Compagnie Financiere Richemont SA, Moncler SpA, Hermès International SA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Luxury Goods Market Emerging Trajectories
Digital authentication layers and circular service models are restructuring how Asia-Pacific consumers acquire, verify, and resell luxury assets, collapsing traditional ownership cycles into fluid access patterns.
Blockchain-based provenance tracking is virtualizing authenticity verification for high-value watches and leather goods. Affluent buyers in China and Japan now expect immutable ownership records transferable across secondary platforms. This compression of trust infrastructure eliminates intermediary appraisal costs and accelerates peer-to-peer transaction velocity.
Japan's METI guidelines on sustainable sourcing now mandate recycled content thresholds for leather goods sold through domestic retail channels. The regulation forces procurement teams to certify tannery water usage and chemical discharge profiles. Premium accessories lines face the steepest compliance burden as they balance heritage craft narratives with documented environmental accountability.
Younger demographics across South Korea and mainland China treat luxury acquisition as content creation rather than private consumption. Social media visibility drives purchase timing, with buyers selecting pieces optimized for algorithmic performance. This behavior concentrates demand on limited-edition drops and artist collaborations that generate shareable scarcity signals.
Asia-Pacific Luxury Goods Market Segmentation
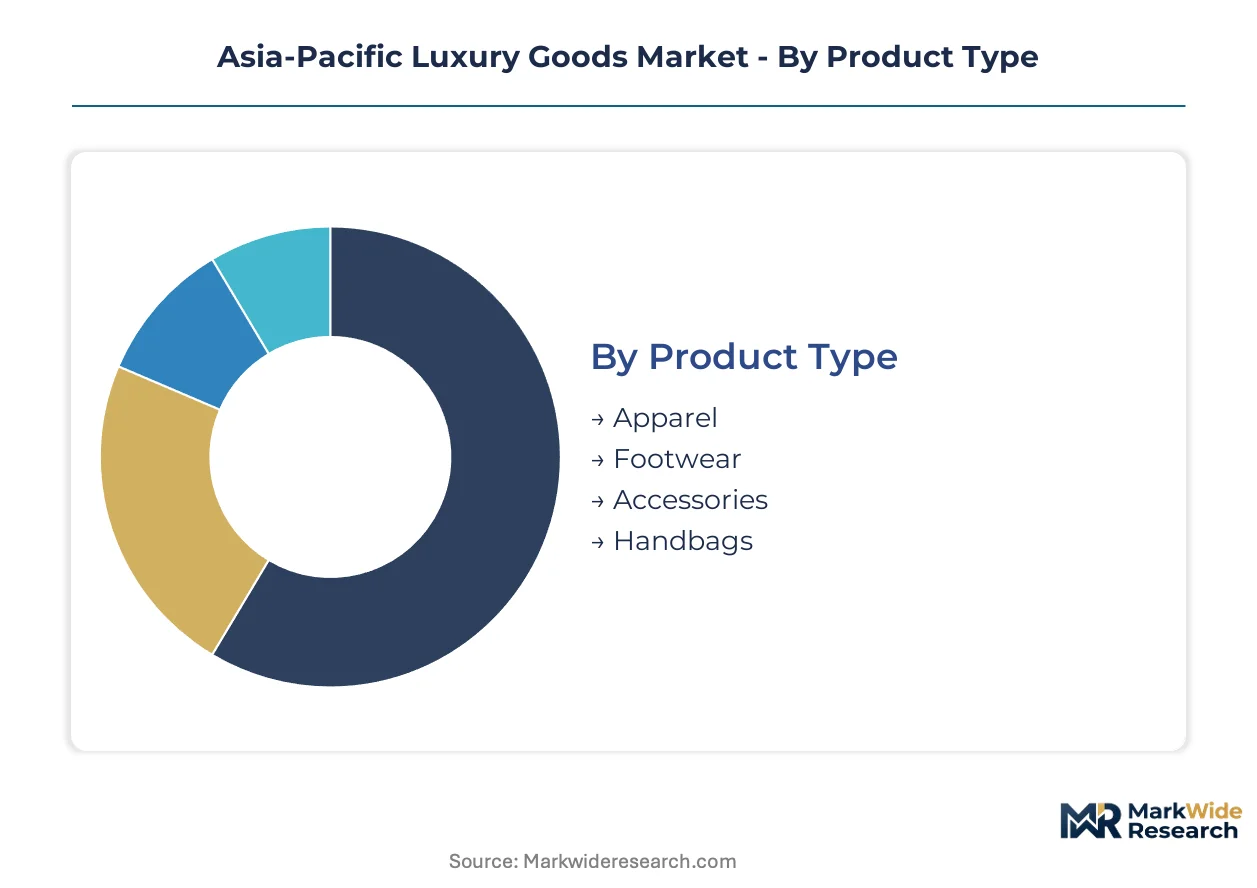
Segmentation in Asia-Pacific luxury goods reveals how purchasing power, distribution infrastructure, and generational values split demand across incompatible commercial models. Price anchoring, channel preference, and digital nativity create distinct profit pools that resist unified treatment.
Product Type:
Cost tier separates manufacturing complexity from margin retention across finished goods categories.
- Apparel:Ready-to-wear collections demand seasonal inventory turns and size-run optimization. Shanghai and Beijing concentrate demand for runway-aligned drops where WeChat mini-program pre-orders reduce markdown exposure.
- Footwear:Leather-soled dress shoes and limited sneaker collaborations occupy opposite ends of the craftsmanship spectrum. Seoul's streetwear collectors drive wait-list mechanics for artist partnerships that compress release-to-resale cycles.
- Accessories:Silk scarves, leather belts, and small leather goods generate recurring purchase frequency with lower decision friction than core categories.
- Handbags:Structured silhouettes in exotic skins command the deepest profit pools where Hermès and Chanel sustain multi-year allocation queues.
Handbags command the established base. The steepest expansion runs through footwear.
Distribution Channel:
Customer type and purchase occasion dictate channel selection across the region's fragmented retail landscape.
- Online:Live-stream commerce and algorithmic recommendation engines compress discovery-to-purchase intervals. Douyin and Kuaishou convert tier-two Chinese cities at rates multiples above traditional e-commerce, forcing heritage houses to rebuild fulfillment around same-day delivery.
- Department Stores:Isetan in Tokyo and Lane Crawford in Hong Kong anchor brand visibility with curated edit authority. These venues concentrate gifting demand during Lunar New Year and year-end seasons.
- Specialty Stores:Multi-brand accessories retailers in Singapore and Bangkok filter emerging labels for regional buyers seeking differentiation from flagship house codes.
- Luxury Boutiques:Controlled environments preserve scarcity signaling through appointment-only access and clienteling depth.
Luxury boutiques command the established base. Online channels are climbing the fastest.
Customer Type:
Generational cohort and wealth source determine responsiveness to heritage narrative versus digital-native engagement models.
- Affluent Consumers:Salary-derived purchasing power concentrates in tier-one Chinese cities where entry-level leather goods serve as professional milestone markers. This segment responds to credit-linked installment schemes that reduce lump-sum payment friction.
- High-Net-Worth Individuals:Asset-backed collectors acquire rare pieces as portable wealth storage. Tokyo and Singapore private salons cultivate multi-year relationships through bespoke commissioning and early access protocols.
- Millennials:First-generation luxury buyers in Jakarta and Bangkok prioritize logo visibility and social media performance over craft provenance.
- Gen Z:Digital natives treat acquisition as content creation, selecting pieces optimized for algorithmic reach and resale liquidity.
Affluent consumers command the established base. Gen Z buyers show the steepest expansion trajectory.
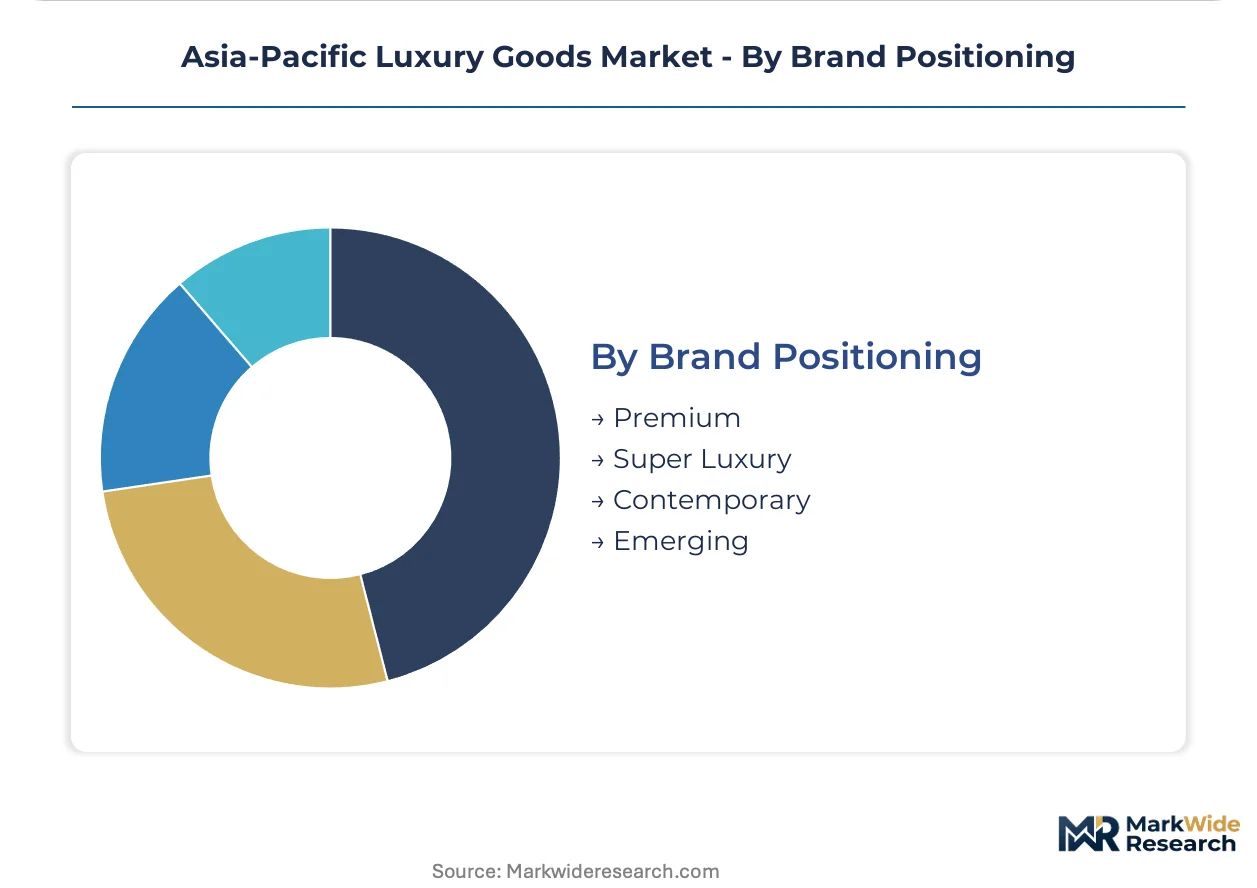
Brand Positioning:
Price architecture and scarcity mechanics segment competitive territory across accessible entry points and unattainable apex positioning.
- Premium:Diffusion lines and accessible leather goods target frequency-driven purchasers. This tier faces the steepest margin pressure as Chinese domestic manufacturing narrows cost gaps with heritage European production.
- Super Luxury:Waiting-list mechanisms and artisan-limited output insulate pricing power from cyclical volatility. Hermès and Rolex sustain multi-year allocation queues that convert scarcity into resale premium.
- Contemporary:Designer-led houses balance craft credibility with fashion-cycle relevance. Seoul and Shanghai buyers gravitate toward these labels for differentiation from omnipresent heritage logos.
- Emerging:Local Asian designers leverage regional craft techniques and digital-native marketing to capture share before international expansion.
Super luxury commands the established base. Contemporary positioning gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Pudong International Airport cargo terminals and Hong Kong-Zhuhai-Macau Bridge logistics corridor anchor Asia-Pacific luxury goods distribution, enabling same-day replenishment to flagship boutiques across the Pearl River Delta and Yangtze River Delta corridors.
China
Shanghai and Beijing concentrate tier-one demand for leather goods and timepieces, with Douyin live-stream commerce converting Gen-Z buyers in Chengdu and Hangzhou at conversion rates multiples above traditional retail. SAMR enforces blockchain traceability mandates for cross-border e-commerce authentication. LVMH and Kering operate vertically integrated leather workshops in Guangzhou and Hangzhou to compress production cycles.
Japan
Tokyo's Ginza and Omotesando districts sustain appointment-only boutique cultures where Hermès and Chanel cultivate multi-year client relationships through bespoke commissioning. METI circular economy guidelines formalize luxury resale channels, legitimizing secondary markets for watches and handbags. Osaka's Umeda district hosts concentrated consignment infrastructure for authenticated pre-owned goods.
South Korea
Seoul's Gangnam district drives demand for limited sneaker collaborations and streetwear-adjacent luxury, with collectors compressing release-to-resale cycles through dedicated trading platforms. MFDS cosmetic safety regulations shape beauty product import protocols for fragrance and skincare lines. The Dongdaemun Design Plaza cluster supports emerging local designers leveraging regional craft techniques.
India
Mumbai and Delhi-NCR concentrate HNI wealth for fine jewelry acquisition, with BIS precious metal certification requirements creating compliance thresholds that filter unauthorized entrants. The country's national jewelry regulator mandates hallmarking infrastructure that jewelry houses must establish ahead of market maturation. Surat's diamond cutting cluster feeds upstream gemstone supply for domestic atelier production.
Singapore
Marina Bay and Orchard Road anchor Southeast Asian tourism-dependent retail, with Changi Airport's Jewel complex functioning as a duty-free luxury goods distribution node. The city-state's customs authority coordinates ASEAN tariff frameworks that remain incomplete, fragmenting logistics strategies for brands expanding into Indonesia and Vietnam. Multi-brand accessories retailers in the Bugis district filter emerging labels for regional buyers.
Asia-Pacific Luxury Goods Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in métiers d'art and exotic material supply. The Asia-Pacific luxury goods sector consolidates around heritage European houses with century-old brand equity, while emerging Asian designers fragment the contemporary tier through digital-native marketing. Three archetypes dominate: vertically integrated leather goods producers, digitally aggressive multi-brand platforms, and artisan-limited super-luxury houses. Competitive moves center on backward integration into tannery supply and WeChat mini-program ecosystem development.
Within the vertically integrated tier, LVMH Moet Hennessy Louis Vuitton SE and Kering SA exemplify divergent digital strategies—LVMH through captive Guangzhou workshops, Kering through direct atelier-to-consumer platform linkage. Hermès International SA anchors the super-luxury archetype with allocation queue mechanics that insulate pricing power from cyclical volatility.
| Leading Market Players |
|---|
| Chanel SA |
| Rolex SA |
| LVMH Moet Hennessy Louis Vuitton SE |
| Burberry Group Plc |
| Prada SpA |
| Kering SA |
| Compagnie Financiere Richemont SA |
| Moncler SpA |
| Hermès International SA |
| Others |
Supply Flow & Price Mechanics
Italian and French tannery concentration in premium calfskin supply anchors margin capture at the super-luxury tier, where six-month order backlogs and euro-denominated input volatility insulate Hermès and Chanel pricing power from mid-market compression. This upstream scarcity forces heritage houses to absorb currency risk or pass through to waiting-list clientele, while domestic Chinese manufacturers narrow cost gaps in accessible leather goods.
Pricing Analysis
SAMR blockchain traceability mandates dictate the pricing tier structure across Asia-Pacific luxury goods, segmenting compliant heritage houses from filtered smaller entrants lacking capital reserves for authentication infrastructure. Three-tier pricing structure across super-luxury, contemporary, and premium levels reflects scarcity mechanics, brand equity depth, and certification investment intensity. Cost compression in accessible leather goods intensifies because Chinese domestic manufacturing narrows production cost differentials with European ateliers. Affluent consumers in tier-one cities show highest price sensitivity to entry-level goods, while high-net-worth individuals demonstrate inelastic demand for allocation-queue products.
Supply Chain Analysis
Vertically integrated leather workshops in Guangzhou, Hangzhou, and Dongguan hold concentrated production capacity for LVMH and Kering, feeding captive supply networks that compress atelier-to-boutique cycles. Pearl River Delta métiers d'art clusters and Italian tanning districts anchor raw material dependencies, alongside Swiss movement manufacturers for timepiece assembly. Single-source vulnerability runs through generational attrition in embroidery craft clusters as younger workers migrate to tech manufacturing. Distribution runs through Shanghai Pudong cargo terminals and Hong Kong-Zhuhai-Macau Bridge logistics corridors enabling same-day replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific luxury goods reward players who control scarce artisan capacity and authentication infrastructure, with generational craft attrition and regulatory compliance investments creating widening capability gaps between capital-rich heritage houses and resource-constrained challengers.
For Market Incumbents: Harden defensibility by deepening captive supply of Pearl River Delta métiers d'art clusters through apprenticeship endowments and atelier acquisitions, insulating against generational craft attrition that threatens production continuity. Accelerate SAMR-compliant blockchain traceability deployment ahead of smaller competitors, converting regulatory burden into authentication-based pricing power that filters unauthorized resale channels. For New Entrants and Emerging Players: Tier-two Chinese cities with live-stream commerce infrastructure represent the most penetrable entry point for digital-native brands lacking heritage equity, where Douyin algorithmic targeting converts Gen-Z browsers at conversion rates multiples above traditional retail. India's BIS precious metal certification pathway offers first-mover advantage for jewelry houses establishing local hallmarking infrastructure ahead of market maturation. WeChat mini-program ecosystems enable direct clienteling without platform commission structures. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated leather goods producers with captive Guangzhou or Hangzhou workshop capacity and established SAMR compliance infrastructure, positioning for sustained margin retention as regulatory thresholds rise. Long-term viability hinges on scarcity mechanics that convert waiting-list psychology into resale liquidity. The signal to watch is blockchain traceability mandate expansion beyond cross-border e-commerce into domestic retail channels.| Strategic Initiative | Industry Significance |
|---|---|
| Métiers d'Art Apprenticeship Endowment | Pearl River Delta craft clusters secure generational talent pipelines against tech-sector migration. |
| SAMR Blockchain Traceability Deployment | Cross-border e-commerce authentication mandates convert compliance investment into pricing power. |
| WeChat Mini-Program Ecosystem Development | Closed-loop social commerce eliminates platform commission structures in mainland China. |
| India BIS Hallmarking Infrastructure | Precious metal certification creates first-mover positioning ahead of jewelry market maturation. |
| Vietnam Manufacturing Footprint Expansion | ASEAN tariff differentials diversify production beyond China-centric supply concentration. |
Methodological Framework
The analysis maps leather goods, timepieces, fine jewelry, and beauty product sub-sectors, each validated through brand executives, supply chain directors, regulatory affairs leads, and multi-brand retail buyers. Primary interviews with heritage house atelier managers and Pearl River Delta workshop operators combined with secondary validation from SAMR filings, METI circular economy guidelines, BIS certification records, and customs trade data. Bottom-up production capacity modeling and top-down consumer expenditure triangulation anchored volume estimates.
Assumptions held SAMR blockchain mandates, METI resale channel formalization, and BIS precious metal thresholds fixed at current enforcement intensity while varying live-stream commerce penetration rates and generational craft attrition scenarios across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, customer cohort, and brand positioning tier alongside regional regulatory cluster differentiation. CAGRs derived from historical luxury goods expenditure elasticity and affluent consumer wealth accumulation patterns, with inputs from atelier capacity utilization and exotic skin allocation queue dynamics.
Practitioners should monitor SAMR mandate expansion scope, METI recycled content threshold adjustments, and Pearl River Delta craft cluster enrollment rates for early signals of forecast revision. Quarterly review of blockchain traceability compliance costs, waiting-list duration trends, and live-stream commerce conversion rate shifts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Qatar Luxury Good Market
Luxury Goods
South Korea Luxury Goods Market
Luxury Goods
Thailand Luxury Goods Market
Luxury Goods
Brazil Luxury Jewelry Market
Luxury Goods
Global Gold Jewelry Market
Luxury Goods
Luxury Apparels Market
Luxury Goods
Luxury Appraisal Service Market
Luxury Goods
France Luxury Goods Market
Luxury Goods
Mexico Luxury Goods Market
Luxury Goods
North America Luxury Goods Market
Luxury Goods
Watch Winder Market
Luxury Goods
Spain Luxury Jewelry Market
Luxury Goods
Mens Watch Market
Luxury Goods
Used Luxury Bags Trading Service Market
Luxury Goods
GCC Personal Luxury Goods Market
Luxury Goods
UAE Luxury Jewelry Market