
 Designer Bags and Luxury Handbags Market | 2026-2036
Designer Bags and Luxury Handbags Market Size, Share, and Industry Trends Forecast 2026-2036
Designer Bags and Luxury Handbags Market Insights
Affluent professional women is consolidating as the dominant end-use vertical, displacing traditional occasion-based purchasing as daily luxury integration becomes standard. Hermès leverages its vertically controlled leather sourcing and artisan apprenticeship model to sustain unmatched price authority. Chanel differentiates through proprietary hardware ateliers and controlled scarcity mechanics. Prada navigates material innovation by anchoring its Re-Nylon initiative within heritage nylon codes.
Designer bags and luxury handbags denote precision-crafted portable accessories constructed from full-grain leather, exotic skins, technical canvas, or regenerated nylon, employing saddle-stitching, edge-painting, and metal hardware finishing to achieve durability and aesthetic distinction. Their primary commercial purpose centers on personal goods transport combined with social signaling and wealth display. Tote bags and crossbody bags occupy the volume core, while clutches concentrate margin pools in evening and event segments. Leather commands the material hierarchy by value, though canvas and regenerated nylon are accelerating fastest among younger demographics seeking entry-point access with sustainability credentials.
REACH chemical restrictions and the EU Green Deal carbon-border adjustments are reshaping European tannery sourcing and forcing brands to document supply-chain provenance. The US Federal Trade Commission's Green Guides constrain environmental marketing claims, tightening how brands communicate leather alternatives and recycled content. Stakeholders must monitor evolving material certification standards and decide whether to pursue captive tannery investments or multi-source compliance partnerships.
Market Dynamics
REACH chemical restrictions and the EU Green Deal carbon-border adjustments are forcing tanneries to document supply-chain provenance or lose access to the European market. This regulatory pressure is compressing supplier bases and accelerating captive leather sourcing investments among heritage houses.
Growth Catalysts
- EU Green Deal carbon-border adjustments:The framework pressures brands toward certified sustainable tanning, creating competitive advantage for early compliance adopters in European markets.
- High-net-worth millennial collectors:This demographic segment is expanding acquisition of limited-edition pieces, shifting volume concentration toward scarcity-driven release mechanics.
- Regenerated nylon innovation:Technical advances in Re-Nylon and similar materials are opening entry-point access with sustainability credentials for younger demographics.
Market Restraints
- Exotic skin supply concentration:CITES-regulated python and crocodile sourcing concentrates in Southeast Asian tanneries, exposing brands to quota volatility and trade restriction risk.
- REACH chemical compliance costs:The ECHA framework mandates extensive substance testing, elevating fixed compliance burdens for small and mid-sized leather goods manufacturers.
- Secondhand platform substitution:Certified pre-owned channels are capturing price-sensitive collectors, compressing primary market entry-tier volume.
Strategic Opportunities
- Domestic Chinese luxury consumption:Mainland demand continues to outpace cross-border purchasing, rewarding localized retail footprint expansion and region-specific product development.
- Blockchain provenance integration:Distributed ledger technology converging with physical authentication is enabling tamper-evident supply-chain documentation for resale value protection.
- Artisan apprenticeship pipeline expansion:Controlled scarcity of saddle-stitching craftspersons creates white space for accredited training programs that lock in future production capacity.
Industry Challenges
- Saddle-stitching craftsperson scarcity:The 18-24 month training timeline for edge-painting and hand-stitching excellence constrains volume scaling for heritage production models.
- Multi-source compliance partnership complexity:Brands without captive tannery investments must orchestrate documentation across fragmented European and Asian supplier networks.
- Hardware atelier capacity bottlenecks:Proprietary metal finishing requires specialized equipment and skilled labor, creating lead time compression risks during demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Designer Bags and Luxury Handbags Market |
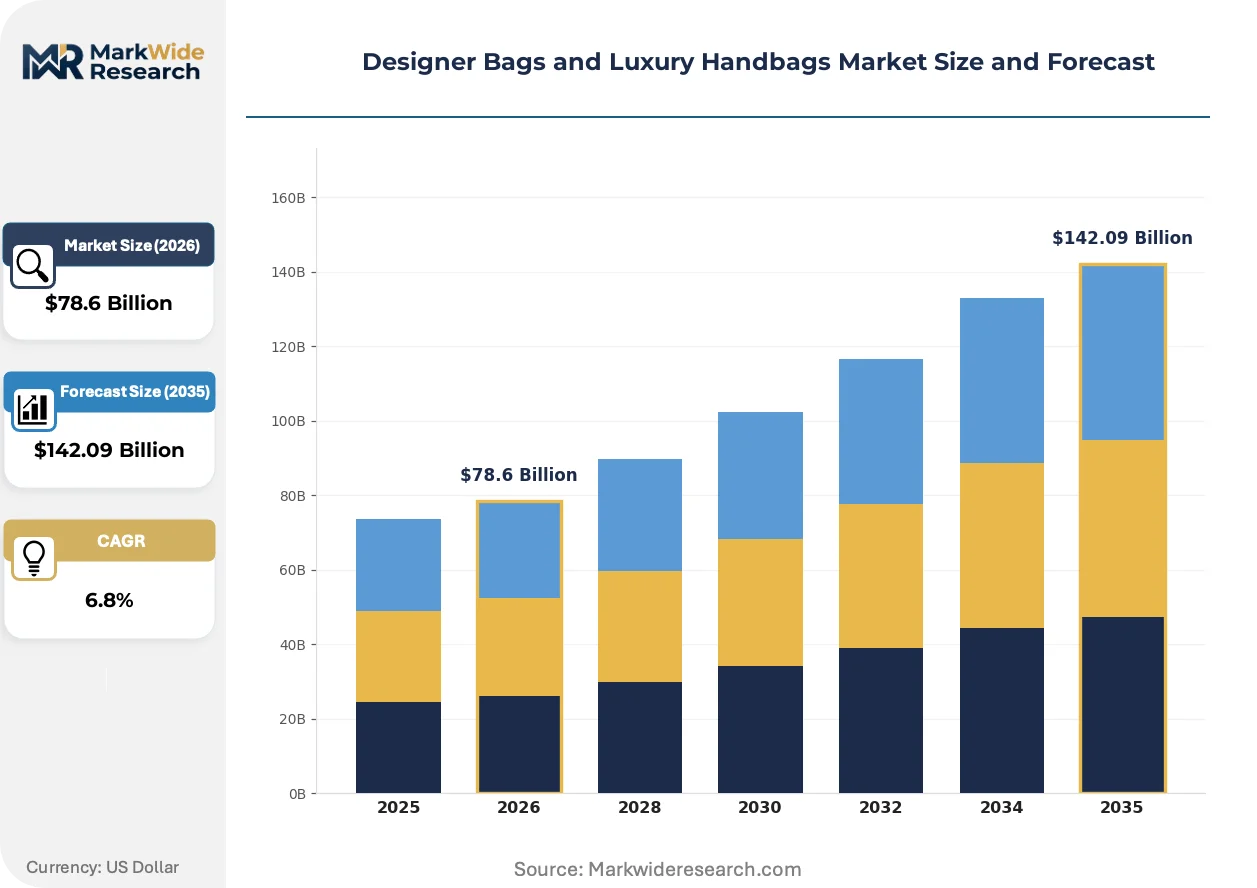
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $142.09 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tote Bags, Crossbody Bags, Clutches, Satchels Material: Leather, Canvas, Nylon, Suede End User: Women, Men, Youth, Professionals Price Tier: Luxury, Premium, Mid-Range, Affordable |
| Companies Covered | Gucci, Hermès, Chanel, Fendi, Celine, Louis Vuitton, Prada, Bottega Veneta, Dior, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Designer Bags and Luxury Handbags Market Trends and Innovations
Material science advances and regulatory documentation requirements are converging to reshape how luxury houses source, authenticate, and distribute precision-crafted accessories. These forces are compressing traditional supply timelines while elevating transparency as a competitive differentiator.
Regenerated nylon formulations are modularizing heritage material codes into scalable, traceable production systems. Prada's Re-Nylon initiative demonstrates how technical canvas can anchor sustainability credentials without sacrificing brand recognition. Younger collectors are adopting these entry-point pieces at accelerating velocity, enabling volume expansion without diluting core leather price architecture.
REACH chemical restrictions are eliminating chromium-tanned leather from European supply chains unless tanneries achieve ZDHC certification. The ECHA framework requires substance-level documentation across wet-blue processing stages, forcing brands to consolidate supplier relationships or invest in captive finishing capacity. Italian and French tanneries are responding by specializing in vegetable-tanned certification tiers.
Collector behavior is fragmenting across primary and secondary channels based on authentication certainty. Chinese HNWIs are rotating toward domestic boutique experiences over cross-border daigou purchasing, while resale platforms are capturing occasion-based buyers seeking discontinued heritage pieces. This channel bifurcation is most visible in Shanghai and Beijing, where mono-brand flagship expansion coincides with certified pre-owned authentication service growth.
Designer Bags and Luxury Handbags Market Segmentation
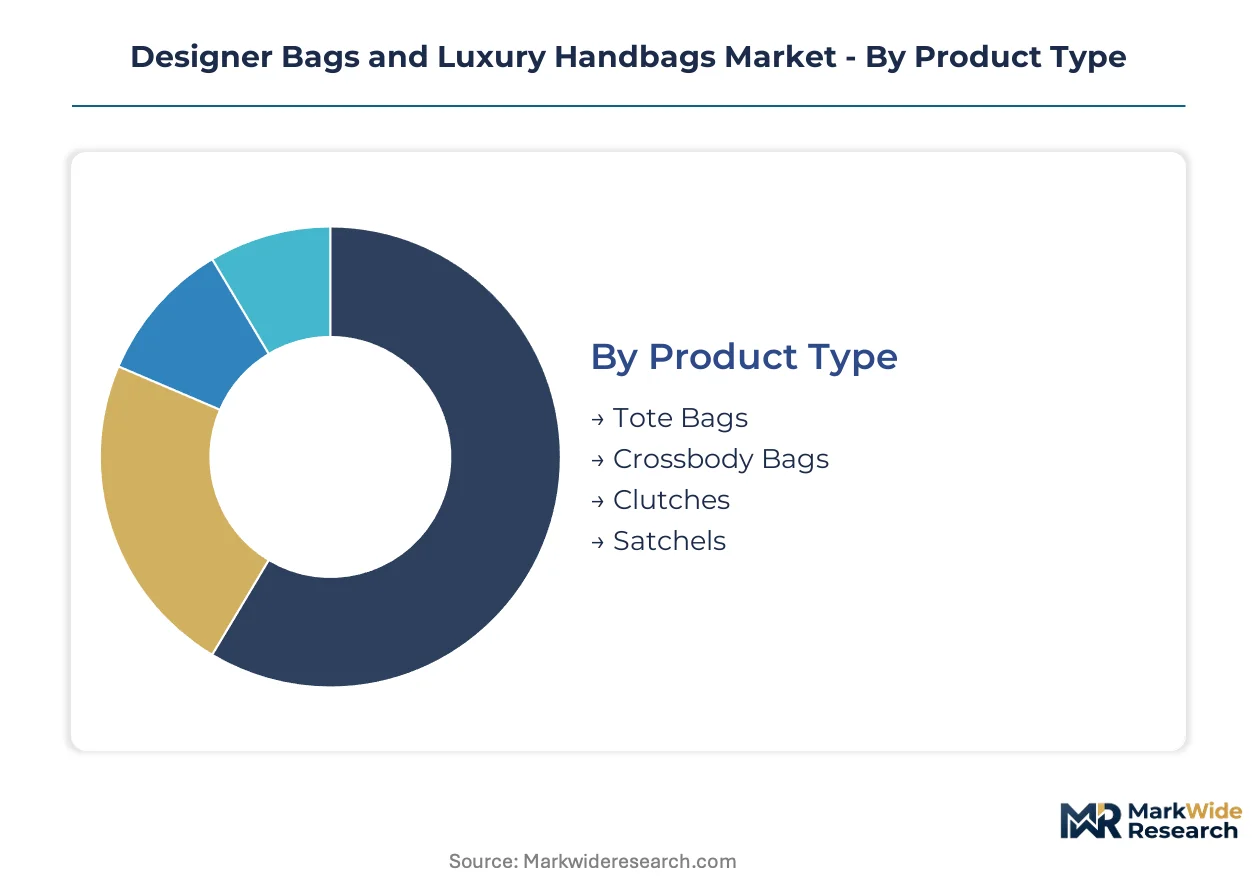
Segmentation in the designer bags and luxury handbags market reveals how supply concentration, craft scarcity, and regulatory pressure concentrate value across distinct product configurations. Understanding these divides exposes where margin pools form and where volume expansion remains structurally constrained.
Product Type:
Supply concentration for saddle-stitching artisans and hardware ateliers favors specific silhouettes that optimize production throughput against skill scarcity.
- Tote Bags:Large-volume silhouettes requiring extensive leather yardage and reinforced base construction dominate daily-use purchasing among affluent professional women. Demand concentrates in domestic Chinese boutiques where localized flagship expansion captures rotation away from cross-border channels.
- Crossbody Bags:Compact form factors with adjustable strap hardware balance accessibility with craft intensity, attracting high-net-worth millennial collectors seeking limited-edition releases. This segment gains share fastest among younger demographics prioritizing versatility across occasion types.
- Clutches:Evening-focused minimal structures with precision edge-painting concentrate margin pools in event-driven purchasing.
- Satchels:Structured academic-heritage silhouettes with top-handle and shoulder-strap dual configurations serve professional end-uses with archival design references.
Today's leader: Tote Bags. Tomorrow's challenger: Crossbody Bags.
Material:
REACH chemical restrictions and EU Green Deal carbon-border adjustments are fragmenting supplier bases across certification tiers, elevating material provenance as a competitive differentiator.
- Leather:Full-grain and exotic skin constructions command the material hierarchy by value, with vegetable-tanned certification tiers displacing chromium-processed alternatives in European supply chains. Italian and French tanneries specializing in ZDHC-compliant finishing capture preferential sourcing from heritage houses.
- Nylon:Regenerated formulations such as Prada's Re-Nylon anchor sustainability credentials within technical canvas codes, accelerating adoption among entry-point collectors seeking traceable production systems. This material climbs the fastest among demographics prioritizing environmental documentation.
- Canvas:Woven cotton and coated technical substrates serve heritage house monogram programs with scalable manufacturing.
- Suede:Napped leather finishes requiring specialized tannery equipment occupy niche luxury positioning with higher care requirements.
Current margin concentration: Leather. Steepest expansion trajectory: Nylon.
End User:
Purchasing behavior fragments across demographic cohorts based on integration of daily luxury versus occasion-based acquisition patterns.
- Women:Affluent professional women consolidate as the dominant vertical, displacing traditional occasion-based purchasing through seamless integration of precision-crafted accessories into daily wardrobe architecture. This segment concentrates volume in mainland China where domestic consumption outpaces cross-border daigou activity.
- Professionals:Gender-neutral workwear-adjacent purchasing prioritizes functional organization and subdued hardware, expanding as corporate dress codes relax while status signaling persists through material quality.
- Men:Masculine-coded briefcase and messenger silhouettes with minimal branding serve evolving professional accessory norms.
- Youth:Entry-point collectors drive regenerated material adoption and secondary platform engagement for discontinued heritage pieces.
Volume anchor: Women. Emerging intensity: Professionals.
Price Tier:
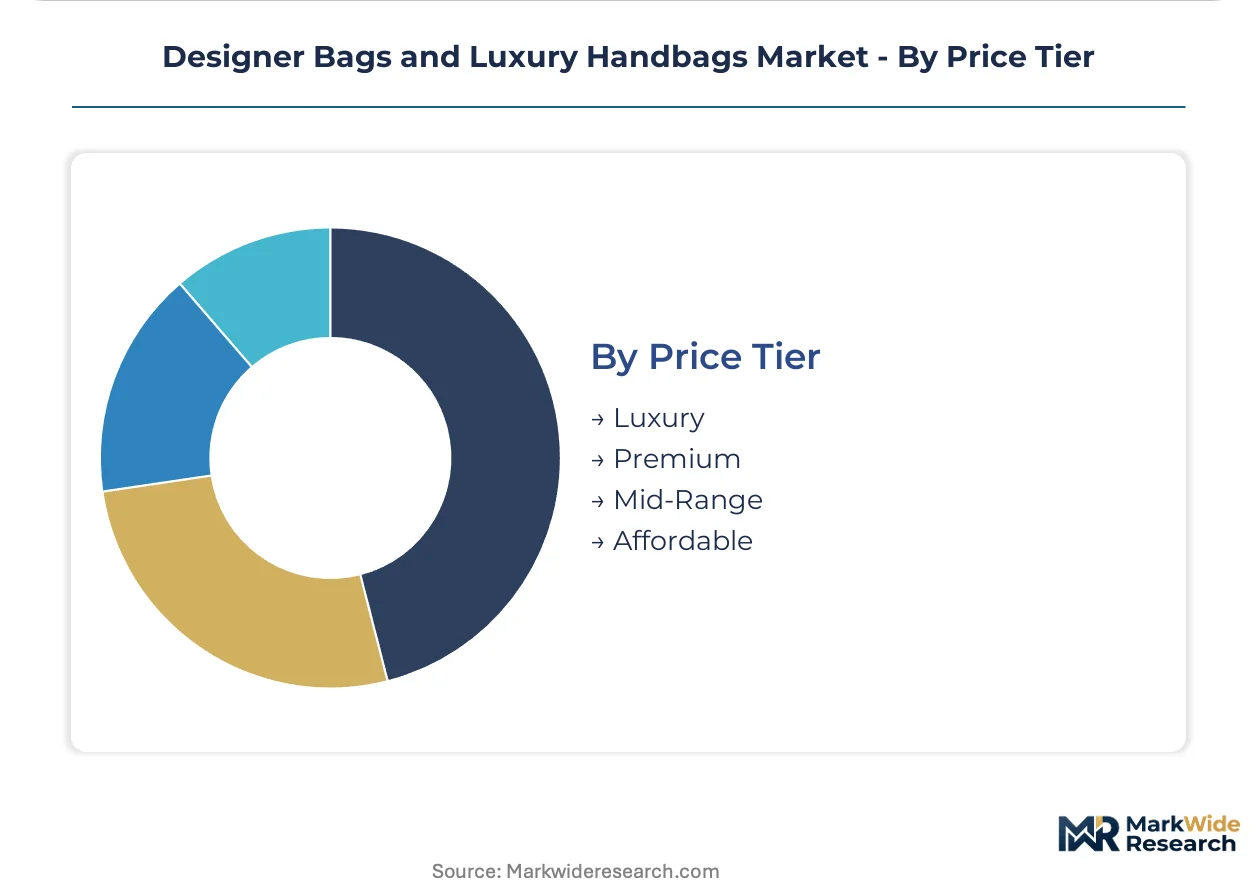
Three-tier pricing structure across luxury, premium, and accessible levels reflects supply chain configuration from captive tannery investments to multi-source compliance partnerships.
- Luxury:Vertically controlled leather sourcing and artisan apprenticeship models sustain unmatched price authority through controlled scarcity mechanics and proprietary hardware ateliers. Hermès and Chanel occupy this tier with documented supply-chain provenance justifying substantial markups.
- Premium:Heritage house diffusion lines and established contemporary brands balance craft credibility with scaled manufacturing, capturing collectors between entry-point experimentation and trophy acquisition.
- Mid-Range:Accessible contemporary labels with outsourced production serve trend-responsive purchasing with compressed lead times.
- Affordable:Fast-fashion interpretations and certified pre-owned channels capture price-sensitive collectors through authentication service integration.
Margin dominance: Luxury. Volume expansion zone: Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are fragmenting production geography as REACH compliance costs in Europe push finishing capacity toward Italian tanneries with ZDHC certification while Asian manufacturing clusters absorb assembly stages. This divergence concentrates premium leather sourcing in Mediterranean supply corridors and regenerates technical material production in East Asian chemical parks.
France
Paris-based heritage houses anchor demand for vegetable-tanned certification tiers, with Île-de-France boutiques capturing rotating Chinese HNWI collectors. The EU Green Deal carbon-border adjustment mechanism pressures domestic tanneries to document wet-blue processing provenance. Lyon and Auvergne-Rhône-Alpes clusters specialize in edge-painting and hardware finishing for controlled-scarcity release mechanics.
Italy
Tuscan tanneries in Santa Croce sull'Arno dominate ZDHC-compliant full-grain finishing, supplying captive leather to vertically integrated maisons. ECHA substance testing mandates compress supplier bases toward certified finishing houses. Milan and Florence concentrate flagship retail expansion targeting domestic Chinese luxury consumption rotation away from cross-border channels.
China
Shanghai and Beijing mono-brand flagships capture accelerating domestic luxury consumption as HNWIs abandon daigou purchasing. SAMR enforcement of advertising standards constrains environmental marketing claims for leather alternatives. Pearl River Delta manufacturing clusters scale regenerated nylon production with blockchain traceability integration for entry-point collector segments.
United States
New York and Los Angeles concentrate consignment platform authentication services capturing price-sensitive collectors from primary market entry tiers. FTC Green Guides tighten substantiation requirements for recycled content claims in leather goods marketing. Miami and Dallas retail footprints expand to capture professional women integrating daily luxury accessories into workwear architecture.
Japan
Tokyo and Osaka department store salons sustain demand for archival heritage silhouettes with artisan craft documentation. METI circular economy guidelines encourage take-back programs for end-of-life leather goods. Kansai manufacturing clusters specialize in precision hardware finishing for limited-edition collaborative releases targeting millennial collectors.
Designer Bags and Luxury Handbags Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage houses controlling proprietary supply chains and contemporary labels outsourcing to Italian and Asian fabrication networks. Market structure concentrates margin authority among vertically integrated players with captive tannery investments, while volume expansion flows through multi-source compliance partnerships. Three archetypes dominate: vertically integrated heritage maisons, heritage-diffusion contemporary brands, and certified pre-owned authentication platforms. Competitive moves center on artisan apprenticeship pipeline expansion and blockchain provenance integration for resale value protection.
Within the vertically integrated archetype, Hermès and Chanel occupy positions defined by controlled scarcity mechanics and proprietary hardware ateliers. Prada sits within the material innovation tier, anchoring sustainability credentials through regenerated nylon initiatives without diluting core leather price architecture. These three exemplify how supply-chain documentation and craft scarcity sustain price authority across divergent material strategies.
| Leading Market Players |
|---|
| Gucci |
| Hermès |
| Chanel |
| Fendi |
| Celine |
| Louis Vuitton |
| Prada |
| Bottega Veneta |
| Dior |
| Others |
Pricing and Supply Chain Analysis
Luxury-mid-accessible tier divergence in designer handbags manifests through captive tannery investments at the apex and multi-source compliance partnerships at volume tiers, with REACH certification costs in Europe compressing supplier bases and elevating price authority for documented provenance. This bifurcation concentrates margin pools where vertically integrated houses control leather sourcing while entry-point competitors absorb elevated compliance burdens across fragmented Asian supplier networks.
Pricing Analysis
Retailer markup layers in mono-brand boutiques sustain substantial premiums over wholesale-dependent contemporary labels, with three-tier pricing structure across luxury, premium, and accessible levels reflecting supply chain configuration from proprietary hardware ateliers to outsourced fabrication. Price differentiation rests on vegetable-tanned certification tiers and artisan craft documentation, with pricing pressure intensifying in entry segments as certified pre-owned platforms capture occasion-based collectors. Affluent professional women exhibit lowest price sensitivity, while younger entry-point collectors demonstrate highest elasticity.
Supply Chain Analysis
Regional distribution centers in Milan and Florence anchor European leather finishing, with hub-and-spoke patterns radiating toward Paris and Lyon for hardware assembly and edge-painting specialization. Geographic supply concentrates in Italy, France, and China, with full-grain leather and exotic skins drawing from Tuscan tanneries while regenerated nylon feeds from Pearl River Delta chemical parks. Single-source vulnerability in CITES-regulated python and crocodile sourcing from Southeast Asian tanneries exposes brands to quota volatility. Distribution runs through mono-brand flagship networks in Shanghai, Beijing, and domestic Chinese boutiques.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The designer bags and luxury handbags market compounds steadily as daily luxury integration among affluent professional women sustains replacement-cycle demand regardless of macroeconomic volatility. This structural demand driver insulates premium tiers from cyclical compression.
For Market Incumbents: Anticipate secondhand platform substitution by accelerating blockchain provenance integration for resale value protection and expanding artisan apprenticeship pipelines to lock in saddle-stitching capacity. Controlled scarcity mechanics remain the priority lever against emerging authentication-service entrants capturing price-sensitive collectors. For New Entrants and Emerging Players: EU Green Deal carbon-border adjustments in Europe open a window for ZDHC-certified tannery partnerships that incumbent heritage houses have not fully locked. White-space targets include regenerated nylon entry-point positioning for younger demographics and domestic Chinese boutique formats bypassing cross-border daigou channels. A direct-to-consumer launch with embedded traceability technology offers the cleanest go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-source compliance partnership complexity exceeds small and mid-sized manufacturer capabilities. The five-to-ten year viability window favors vertically integrated specialists with captive leather sourcing or proprietary hardware ateliers. Acquisition target archetypes include Italian tanneries with ZDHC certification and authentication-technology platforms. The signal to watch is CITES quota tightening on exotic skins, which would accelerate captive sourcing premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Tannery Investment | REACH compliance in Europe forces consolidation toward ZDHC-certified finishing houses with documented provenance. |
| Blockchain Provenance Integration | Distributed ledger technology from Pearl River Delta manufacturers enables tamper-evident supply-chain documentation for resale protection. |
| Artisan Apprenticeship Expansion | Accredited training programs in Lyon and Auvergne-Rhône-Alpes lock in future saddle-stitching capacity against craftsperson scarcity. |
| Domestic Chinese Flagship Expansion | Shanghai and Beijing mono-brand boutiques capture rotation away from cross-border daigou purchasing among HNWIs. |
| Regenerated Nylon Scale-Up | Technical material innovation in Prada's Re-Nylon mold opens entry-point access without diluting core leather price architecture. |
Research Methodology
Coverage spans Western Europe, North America, and Asia-Pacific, with primary inputs from each region combining structured interviews with brand executives, tannery procurement directors, luxury retail buyers, and sustainability compliance officers with secondary validation. Trade data from Italian leather goods associations, ECHA substance registration databases, SAMR advertising enforcement records, and FTC Green Guide adjudications anchored supply-side and regulatory dimensions. Bottom-up SKU-level modeling triangulated against top-down category spend estimates.
Granularity-level framing applied separate elasticity assumptions by price tier, material certification grade, and regional channel structure across the projection horizon. Segmentation dimensions modeled include product silhouette, material type, end-user demographic, and price tier, with additional disaggregation by domestic versus cross-border purchasing patterns in China. CAGRs derived from fitted growth curves incorporating replacement-cycle frequencies and collector acquisition velocity. Forecast inputs captured REACH compliance cost pass-through rates and CITES quota allocation volatility.
Revisions become necessary when regulatory enforcement intensifies beyond modeled thresholds or when exotic skin trade restrictions materialize unexpectedly. Forecasts reflect documented assumptions regarding artisan training pipeline throughput and Chinese domestic consumption rotation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Singapore Luxury Goods Market
Luxury Goods
China Luxury Market
Luxury Goods
Asia-Pacific Luxury Goods Market
Luxury Goods
Europe Secondhand Luxury Goods Market
Luxury Goods
South Korea Luxury Goods Market
Luxury Goods
Watch Winder Market
Luxury Goods
Luxury Handbag Market
Luxury Goods
Accessible Luxury Goods Market
Luxury Goods
Russia Luxury Goods Market
Luxury Goods
Luxury Products for Kids Market
Luxury Goods
Middle East and Africa Luxury Goods Market
Luxury Goods
Used Luxury Bags Trading Service Market
Luxury Goods
Personal Luxury Goods Market
Luxury Goods
Mexico Luxury Goods Market
Luxury Goods
Brazil Luxury Goods Market
Luxury Goods
UAE Luxury Jewelry Market