
 Hard Luxury Goods Market | 2026-2036
Hard Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Hard Luxury Goods Market Intelligence
The substitution of natural diamonds with lab-grown alternatives is hardening the value proposition for entry-level fine jewelry. LVMH leverages its diverse portfolio of brands, from jewelry to watches, to capture a wide consumer base. Kering specializes in high-fashion-linked luxury goods, emphasizing unique design aesthetics. Compagnie Financière Richemont dominates the high-end watch and jewelry segments through brands like Cartier.
Hard luxury goods encompass durable items crafted from precious materials, such as metals and gemstones, intended for long-term ownership. These products, including mechanical watches with complex movements or jewelry featuring specific carat weights and clarity grades, serve as status symbols and investment assets. Luxury Watches and Fine Jewelry continue to constitute the largest product segments by value. Meanwhile, Online Luxury Platforms are experiencing rapid expansion, challenging the traditional dominance of Flagship Stores and Authorized Retailers in distribution.
Market access and material sourcing are governed by international frameworks like the Kimberley Process Certification Scheme for diamonds and CITES for exotic materials. In addition, national hallmarking standards in countries like the United Kingdom and Switzerland, alongside FTC guidelines in the United States, ensure material purity and protect consumers. Stakeholder decisions will center on balancing brand heritage with the adoption of digital sales channels and sustainable material innovations.
Market Dynamics
The hard luxury market's structure is defined by a fundamental tension between preserving brand heritage and adapting to new consumer demands for sustainability and digital accessibility. This dynamic forces incumbents to innovate material sourcing while carefully managing their exclusive distribution models.
Growth Catalysts
- Collector and Investor Demand:A growing cohort of high-net-worth individuals seeks hard luxury goods, particularly limited edition watches and rare gemstones, as tangible assets and a hedge against economic volatility, concentrating demand in major wealth centers.
- Material Science Innovation:The commercialization of lab-grown diamonds and the use of certified recycled precious metals are expanding the market, making entry-level fine jewelry more accessible and appealing to sustainability-conscious consumers.
- Wealth Concentration in New Markets:Rising disposable incomes and an affinity for status symbols in China and Middle Eastern hubs like Dubai are creating significant new consumer bases for established European luxury houses.
Market Restraints
- Raw Material Price Volatility:The market is exposed to fluctuations in the prices of core commodities like gold, platinum, and high-quality diamonds, which can compress margins for manufacturers and create pricing uncertainty for consumers.
- Complex Sourcing Regulations:Compliance with frameworks such as the Kimberley Process for conflict diamonds and CITES for exotic skins adds layers of administrative burden and cost, restricting the agility of supply chains.
- Threat from Adjacent Categories:High-end smartwatches with advanced health-tracking features and designer fashion jewelry offer compelling alternatives for consumers at the entry-level and mid-tier segments, diverting discretionary spending from traditional hard luxury items.
Strategic Opportunities
- Digital Channel Expansion:Developing sophisticated, branded e-commerce platforms and curated online marketplaces offers a direct channel to engage with a global audience, bypassing the limitations of physical retail footprints.
- Blockchain for Provenance:Implementing blockchain technology provides an immutable record of an item's history, from raw material sourcing to ownership, enhancing authenticity and value for secondary market trading and collectibles.
- Targeting Next-Wave Wealth:Focusing on emerging luxury consumer clusters in Southeast Asian nations like Vietnam and Indonesia presents an opportunity to establish brand presence ahead of competitors in markets with nascent but rapidly growing demand.
Industry Challenges
- Scarcity of Artisanal Skills:The industry faces a shortage of master craftspeople, particularly in specialized fields like mechanical watchmaking (horology) and high-jewelry gem-setting, threatening the ability to produce top-tier items and execute repairs.
- Balancing Exclusivity and Accessibility:Brands struggle to maintain an aura of exclusivity and heritage while using mass-market digital platforms for marketing and sales, creating a risk of brand dilution and devaluing their core proposition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hard Luxury Goods Market |
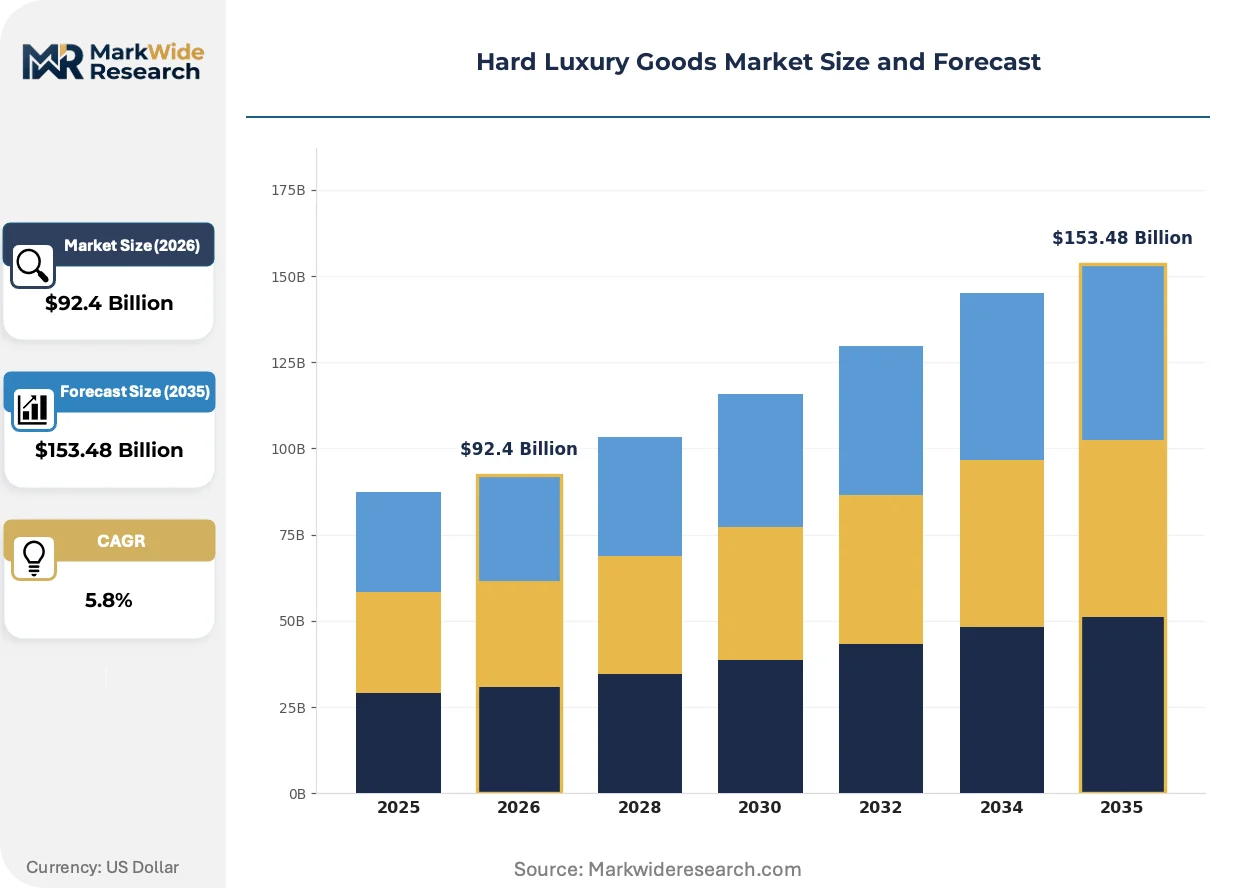
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $153.48 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Watches, Fine Jewelry, Precious Metals, Designer Handbags, High-End Eyewear, Luxury Writing Instruments Distribution Channel: Flagship Stores, High-End Department Stores, Authorized Retailers, Online Luxury Platforms, Exclusive Boutiques, Luxury Auctions Customer Type: Affluent Individuals, Collectors, Professionals, Celebrities, Investors, Luxury Enthusiasts Pricing Tier: Entry-Level Luxury, Mid-Tier Luxury, Ultra-Luxury, Limited Edition, Customized Pieces |
| Companies Covered | Compagnie Financière Richemont, Chanel, LVMH, Cartier, Prada, Hermès, Kering, Rolex, EssilorLuxottica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hard Luxury Goods Market Strategic Shifts & Innovations
The convergence of material science and digital verification technologies is redefining benchmarks for quality, authenticity, and value. This shift impacts everything from gemstone assessment to consumer engagement, forcing brands to adopt new tools to prove their product's worth beyond aesthetics.
Advanced imaging and artificial intelligence are being applied to gemstone analysis. These systems use machine learning algorithms to evaluate the clarity, color, and cut of diamonds and other precious stones with high precision. Gemological institutes and large-scale manufacturers are the primary adopters, seeking greater consistency. The technology is automating the historically subjective and labor-intensive grading process, reducing human error and accelerating supply chain throughput.
New regulations emphasize supply chain transparency. The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates that large companies provide extensive disclosures on their environmental and social impact, including raw material origins. This directly affects luxury conglomerates operating in Europe, which must now invest heavily in traceability systems. The fine jewelry and watch segments are most impacted, re-engineering procurement to meet these stringent new standards.
Consumer purchasing decisions are increasingly influenced by an item's provenance and the narrative behind it. The traditional sales model focused purely on material specifications, such as carat weight or metal purity, is being augmented by demand for rich storytelling. This is most visible among younger consumers in North America and Europe, who prioritize brands that can demonstrate ethical sourcing, artisanal heritage, or a unique design history.
Hard Luxury Goods Market Segmentation
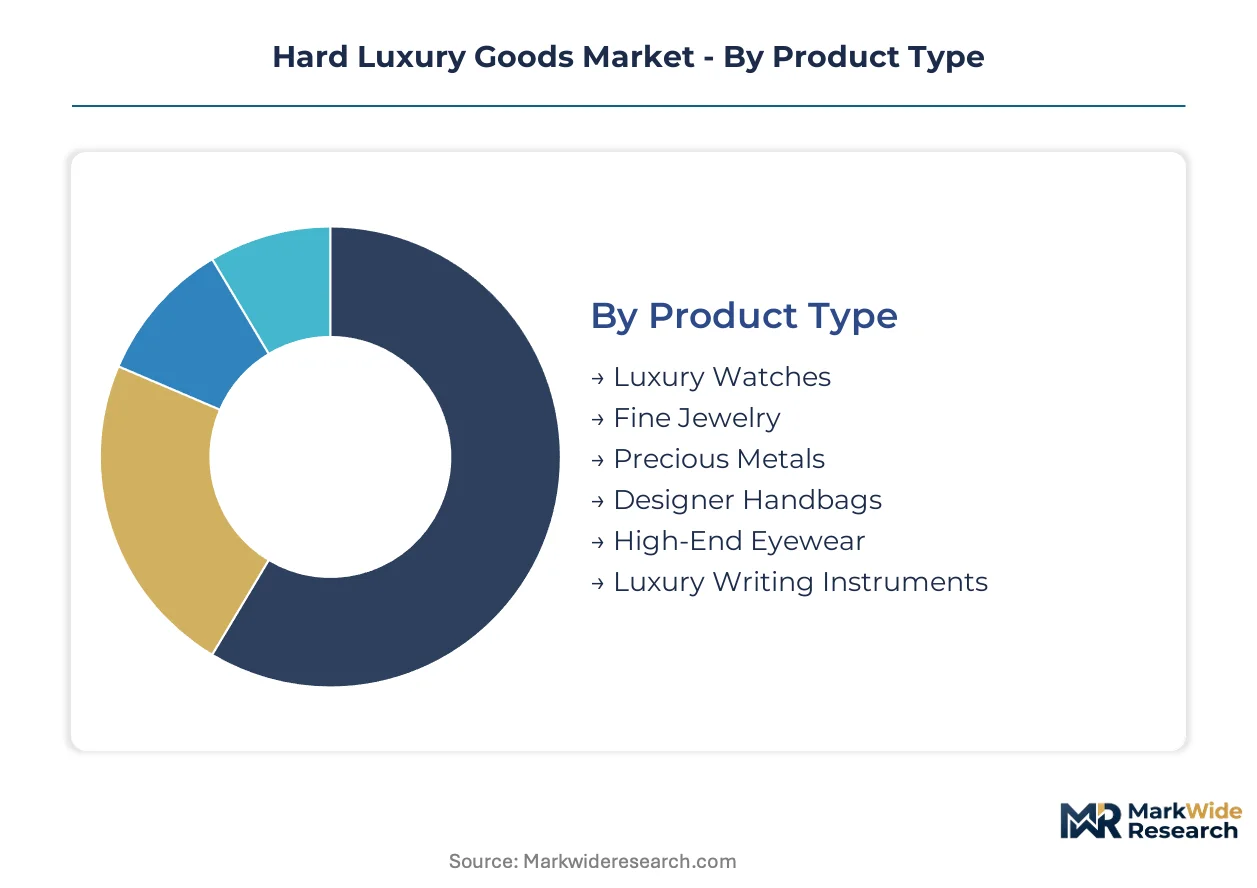
The hard luxury goods market stratifies across distinct product categories, distribution channels, customer profiles, and pricing tiers. Understanding these segments enables brands to tailor product development, marketing strategies, and distribution networks effectively. Market dynamics vary significantly within each segment, influencing competitive approaches and growth trajectories.
Product Type:
The hard luxury goods market is primarily defined by the craftsmanship and material specifications inherent in its diverse product offerings.
- Luxury Watches:These items feature intricate mechanical movements, often incorporating complex complications like perpetual calendars or tourbillons. Demand from collectors in Switzerland and Japan drives continuous innovation in high-end horology.
- Fine Jewelry:This segment includes pieces crafted from precious metals such as gold or platinum, adorned with specific carat weights and clarity grades of gemstones. Younger consumers in North America and Europe increasingly prioritize ethically sourced and traceable pieces.
- Precious Metals:This category encompasses investment-grade gold, silver, and platinum bullion or bars. Investors in China seek these tangible assets for wealth preservation and portfolio diversification.
- Designer Handbags:High-end fashion accessories are meticulously crafted from exotic materials like crocodile or rare calfskin. Fashion-conscious consumers in France often drive demand for exclusive designs and limited production runs.
- High-End Eyewear:Premium frames incorporate advanced lens technology and luxury materials such as titanium or buffalo horn. Professionals in Germany value sophisticated aesthetics combined with exceptional durability.
- Luxury Writing Instruments:This segment includes meticulously crafted pens from rare materials, often featuring intricate engraving or precious metal accents. Executives in the United Kingdom purchase these items as refined status symbols.
Luxury Watches lead on scale; Fine Jewelry leads on momentum.
Distribution Channel:
Access to hard luxury goods varies significantly across different distribution channels, each catering to specific consumer preferences and purchasing behaviors.
- Online Luxury Platforms:These digital marketplaces offer global reach, curated collections, and convenient purchasing options for a wide array of luxury items. Younger consumers in the United States increasingly prefer the accessibility and transparency of online purchasing.
- Flagship Stores:These immersive brand environments provide exclusive client experiences, showcasing the full breadth of a brand's heritage and craftsmanship. High-net-worth individuals in Dubai seek personalized service and an elevated in-store atmosphere.
- High-End Department Stores:Multi-brand retail spaces within established commercial centers offer a diverse selection of luxury goods under one roof. Shoppers in Japan value the convenience of exploring various luxury offerings simultaneously.
- Authorized Retailers:Independent jewelers and watch dealers operate with official brand partnerships, providing local expertise and after-sales support. Consumers in Canada often rely on these trusted local establishments for authenticity.
- Exclusive Boutiques:Niche outlets focus on limited-edition releases and highly specialized collections, often providing a more intimate shopping experience. Collectors in London frequent these locations for unique, rare pieces not widely available.
- Luxury Auctions:Public sales platforms facilitate the acquisition of rare, vintage, and collectible items, often achieving premium prices. Investors globally participate in these events for high-value acquisitions and secondary market opportunities.
Online Luxury Platforms exhibits the steepest expansion trajectory, while Flagship Stores maintain a substantial market presence.
Customer Type:
The hard luxury market segments by distinct customer types, each driven by unique motivations for acquisition and ownership.
- Collectors:These individuals acquire items for their historical significance, rarity, artistic merit, or potential for future appreciation. These individuals in Hong Kong actively pursue limited edition watches and rare gemstones.
- Investors:Buyers in this segment view hard luxury items as tangible assets for wealth preservation, diversification, and potential appreciation over time. High-net-worth individuals in Singapore purchase rare diamonds and precious metals.
- Affluent Individuals:This broad category includes high-income consumers seeking status symbols, personal adornment, and expressions of personal style. This significant group in the United States drives consistent demand for established luxury brands.
- Professionals:Individuals acquiring luxury items to signify professional success, sophistication, and attention to detail. Executives in Germany often select high-quality watches and writing instruments as part of their professional image.
- Celebrities:Public figures significantly influence trends through their visible consumption and endorsement of luxury goods. Their choices in Los Angeles impact brand desirability and product visibility among a wider audience.
- Luxury Enthusiasts:Passionate consumers possess a deep appreciation for craftsmanship, brand heritage, and the intricate details of luxury products. These individuals in Italy often attend industry events and exhibitions to deepen their knowledge.
Collectors and Investors collectively drive the market's high-value transactions, while Affluent Individuals represent the broadest consumer base.
Pricing Tier:
Hard luxury goods are differentiated across various pricing tiers, reflecting material quality, brand prestige, and exclusivity.
- Ultra-Luxury:This tier comprises items characterized by exceptional rarity, bespoke craftsmanship, and the highest possible material quality. Buyers in Switzerland often commission unique pieces for unparalleled exclusivity and personal expression.
- Limited Edition:Scarce products produced in restricted quantities, often featuring unique design elements, collaborations, or historical significance. Collectors in Japan highly value these pieces for their investment potential and distinctiveness.
- Entry-Level Luxury:More accessible luxury items serve as an introduction to high-end brands, often featuring simpler designs or alternative materials. Lab-grown diamonds are expanding this segment in the United States, making fine jewelry more attainable.
- Mid-Tier Luxury:Products in this segment balance brand recognition with premium materials and design, offering a compelling value proposition. Consumers in China seek quality and status at a more attainable price point than ultra-luxury items.
- Customized Pieces:Bespoke items are tailored precisely to individual client specifications, including unique designs, materials, and engravings. Wealthy patrons in the Middle East frequently commission unique jewelry designs or personalized watches.
Ultra-Luxury items command the highest unit prices, while Entry-Level Luxury is expanding most quickly due to material innovations.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland's specialized horology cluster drives significant innovation in mechanical watches. Major wealth centers in China and the Middle East further concentrate demand for high-value hard luxury items. This global market landscape shapes brand strategies for distribution and material sourcing.
Switzerland
Collectors in Switzerland drive continuous innovation in high-end horology. Buyers frequently commission unique pieces for unparalleled exclusivity and personal expression. National hallmarking standards ensure material purity and protect consumers. The Jura Arc region remains a global hub for intricate watchmaking, attracting master craftspeople and specialized suppliers.
China
Rising disposable incomes and an affinity for status symbols in China create a significant consumer base. Investors increasingly seek precious metals like gold for wealth preservation. China's GB standards for product quality influence luxury goods imports. Major cities like Shanghai and Beijing serve as key retail hubs, attracting established European luxury houses.
United States
Affluent individuals in the United States drive consistent demand for established luxury brands. Younger consumers increasingly prefer accessible entry-level fine jewelry. FTC guidelines protect consumers by ensuring material purity and accurate product descriptions. New York City's Diamond District remains a crucial center for gemstone trading and jewelry manufacturing.
United Arab Emirates
High-net-worth individuals in Dubai seek personalized service and an elevated in-store atmosphere. Wealthy patrons frequently commission unique jewelry designs or personalized watches. MOHAP regulations govern the import and sale of precious goods. Dubai's Gold Souk and luxury malls function as major retail and trading centers for precious metals and bespoke pieces.
Japan
Japanese collectors highly value these pieces for their investment potential and distinctiveness. Shoppers value the convenience of exploring various luxury offerings simultaneously. METI oversees industry standards for manufacturing and trade. Tokyo's Ginza district is a renowned luxury shopping destination, showcasing exclusive boutiques and flagship stores.
Hard Luxury Goods Market Key Industry Players
Portfolio diversification dominates the current landscape, as major players strategically expand their brand offerings. The market exhibits a tiered structure, with a few large conglomerates dominating the ultra-luxury and high-end segments. These global entities coexist with specialized independent artisans and digitally native brands targeting niche markets. Strategic acquisitions, brand portfolio expansion, and the adoption of advanced digital sales channels are common competitive moves to secure market share and consumer loyalty.
Within the conglomerate archetype, LVMH exemplifies a strategy of extensive brand portfolio management across diverse luxury categories. Compagnie Financière Richemont occupies a position as a dominant force in high-end watch and jewelry segments. Kering, another significant player, anchors its strategy on high-fashion-linked luxury goods, emphasizing unique design aesthetics. These entities leverage their established heritage and global reach to maintain premium pricing and exclusive distribution networks, adapting their strategies to integrate digital channels and sustainable material sourcing.
| Leading Market Players |
|---|
| Compagnie Financière Richemont |
| Chanel |
| LVMH |
| Cartier |
| Prada |
| Hermès |
| Kering |
| Rolex |
| EssilorLuxottica |
| Others |
Cost & Logistics Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD) gates qualified supply within the hard luxury market, ensuring only ethically sourced materials access premium-tier pricing and consumer segments.
Pricing Analysis
Raw material price volatility in gold and platinum directly impacts manufacturing costs, which are typically passed through to consumers in the ultra-luxury and limited-edition segments. Pricing stratifies across premium, standard, and economy tiers, driven by brand prestige and intricate craftsmanship. Pricing softness runs through the entry-level luxury segment due to the increasing accessibility of lab-grown diamonds. Collectors and investors demonstrate the lowest price sensitivity, prioritizing rarity and provenance, while affluent individuals in the mid-tier are more sensitive to price fluctuations.
Supply Chain Analysis
Precious metal supply for hard luxury goods largely hinges on mining operations in South Africa and Australia, with diamond sourcing drawing from Russia and Botswana. Key raw material dependencies include high-carat diamonds, gold, and CITES-regulated exotic materials. Regulatory restrictions, such as the Kimberley Process for conflict diamonds, pose a structural risk to supply chain agility. Distribution runs through a hybrid model, combining exclusive flagship stores and authorized retailers with expanding online luxury platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hard luxury market presents a significant margin-expansion story, driven by the shift towards premium-tier offerings and enhanced brand storytelling.
For Market Incumbents: Extend brand heritage through immersive digital experiences, directly counteracting the threat from adjacent categories like high-end smartwatches. Invest in blockchain technology for immutable provenance tracking, reinforcing authenticity and value for collectors. Diversify material sourcing to mitigate raw material price volatility and comply with evolving sustainability mandates.
For New Entrants and Emerging Players: The European Union's Corporate Sustainability Reporting Directive (CSRD) in Europe opens a window for new entrants focused on fully traceable, sustainably sourced luxury. Target younger consumers in North America and Europe with entry-level fine jewelry featuring lab-grown diamonds and compelling ethical narratives. An online-first model with strong digital provenance storytelling offers a cost-effective go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for luxury brand conglomerates because the market's high barriers to entry and strong brand loyalty create enduring value. Long-term viability rests on the asset-like nature of hard luxury items, offering wealth preservation and diversification over a 5-10 year horizon. Target specialized artisanal workshops or innovative digital luxury platforms for acquisition, with consumer adoption rates for blockchain-verified provenance serving as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Channel Expansion | Broadens consumer reach and enhances direct engagement for luxury brands globally. |
| Blockchain Provenance Integration | Enhances authenticity and trust, critical for secondary market valuation and collector confidence. |
| Sustainable Material Sourcing | Addresses evolving consumer preferences and regulatory mandates from the European Union. |
| Artisanal Skill Development | Preserves traditional craftsmanship, crucial for high-end watchmaking and fine jewelry production. |
| Emerging Market Entry | Captures demand from rising wealth centers in Southeast Asian nations like Vietnam. |
Research Approach
Bottom-up fine jewelry modeling reconciled against top-down precious metal supply tracking forms the analytical core of this study. The approach combines insights from primary interviews with luxury brand executives, authorized retailers, master craftspeople, and gemstone traders. Secondary validation draws from national hallmarking standards, CITES trade data, corporate sustainability reports, and established luxury market analyses.
An input-output matrix underpins the forecast framework, mapping material flows and consumer demand across the analysis window. Segmentation dimensions modeled include product type, distribution channel, customer type, pricing tier, and material origin. Compound Annual Growth Rates (CAGRs) were derived from historical trend analysis and projected market dynamics, incorporating raw material price forecasts and disposable income growth rates as key inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of extreme raw material price volatility or major trade disruptions. Forecasts reflect assumptions concerning economic stability and regulatory continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
UAE Luxury Jewelry Market
Luxury Goods
Thailand Luxury Goods Market
Luxury Goods
Spain Luxury Jewelry Market
Luxury Goods
Global Gold and Diamond Jewellery Market
Luxury Goods
GCC Secondhand Luxury Goods Market
Luxury Goods
United States Secondhand Luxury Goods Market
Luxury Goods
Asia-Pacific Luxury Goods Market
Luxury Goods
China Luxury Goods Market
Luxury Goods
Mens Watch Market
Luxury Goods
Luxury Piano Market
Luxury Goods
Italy Luxury Goods Market
Luxury Goods
Luxury Goods Market
Luxury Goods
Accessible Luxury Goods Market
Luxury Goods
Germany Luxury Goods Market
Luxury Goods
Mexico Luxury Goods Market
Luxury Goods
Luxury Handbag Market