
 China Luxury Market | 2026-2036
China Luxury Market Size, Share, and Industry Trends Forecast 2026-2036
China Luxury Market Intelligence
Shanghai-based flagship retail expansion is recalibrating how international maisons allocate floor space and inventory depth. LVMH Moët Hennessy Louis Vuitton leverages its multi-brand architecture to dominate high-visibility mall placements in first-tier cities. Hermès International sustains scarcity-driven distribution, limiting boutique access to reinforce exclusivity. Chow Tai Fook Jewellery Group anchors domestic jewelry demand through localized design studios and heritage gold craftsmanship.
China luxury goods encompass high-value fashion, timepieces, jewelry, and leather accessories distinguished by superior materials, artisanal construction, and brand heritage pricing power. These products serve status signaling, wealth preservation, and personal identity functions for affluent buyers. Fashion and jewelry segments command the deepest margin pools due to material markups and limited-edition scarcity mechanics. Gen Z and millennial customer types represent the fastest-expanding cohort, with digital-native purchasing habits reshaping online and exclusive boutique channel strategies.
SAMR enforces anti-counterfeiting and consumer protection standards that constrain gray-market circulation and mandate transparent pricing disclosures. China's dual carbon goals and evolving GB standards on textile sustainability are forcing reformulations of material sourcing and packaging protocols. Stakeholders must monitor how NMPA cosmetics regulations and emerging data privacy frameworks reshape cross-border e-commerce operations and client data deployment in luxury CRM systems.
Market Dynamics
China's dual carbon goals are forcing luxury brands to restructure material sourcing and manufacturing footprints, while Gen Z purchasing power concentrates demand in Shanghai and Greater Bay Area flagship locations.
Growth Catalysts
- Dual carbon policy framework:China's national climate commitments are accelerating sustainable material adoption across leather and textile supply chains, creating first-mover advantages for compliant brands.
- Gen Z digital-native purchasing:Younger consumers are driving experiential retail investments and social commerce integration, reshaping how maisons allocate boutique floor space.
- Greater Bay Area wealth concentration:Shenzhen and Guangzhou are emerging as secondary luxury hubs with dedicated flagship development, diversifying demand beyond Shanghai.
Market Restraints
- Gold price volatility:Chow Tai Fook and domestic jewelry houses face margin compression when raw material costs spike, limiting pricing flexibility in heritage craftsmanship segments.
- SAMR anti-counterfeiting enforcement:Stricter gray-market crackdowns are constraining parallel import channels that previously served price-sensitive buyers in lower-tier cities.
- Scarcity distribution limits:Hermès-style boutique access restrictions create artificial supply ceilings that cap volume growth despite unmet demand.
Strategic Opportunities
- Hainan duty-free expansion:The island's retail zone is capturing offshore purchasing that previously flowed to Hong Kong or overseas, with customs policies favoring domestic consumption.
- GB textile sustainability standards:Evolving national technical regulations on recycled content and chemical disclosure are creating certification-based differentiation for early adopters.
- Virtual try-on convergence:AR-powered jewelry and timepiece visualization is merging with WeChat mini-program commerce, reducing return rates in online channels.
Industry Challenges
- Artisan talent scarcity:Master craftspeople capable of heritage gold work and leather marquetry are retiring faster than training pipelines replenish, threatening production continuity.
- Cross-border data compliance:CRM systems must reconfigure client data architectures to satisfy emerging personal information protection frameworks without disrupting loyalty programs.
- Packaging reform timelines:GB standards on single-use reduction are forcing rapid redesign of unboxing experiences that previously reinforced brand ritual.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Luxury Market |
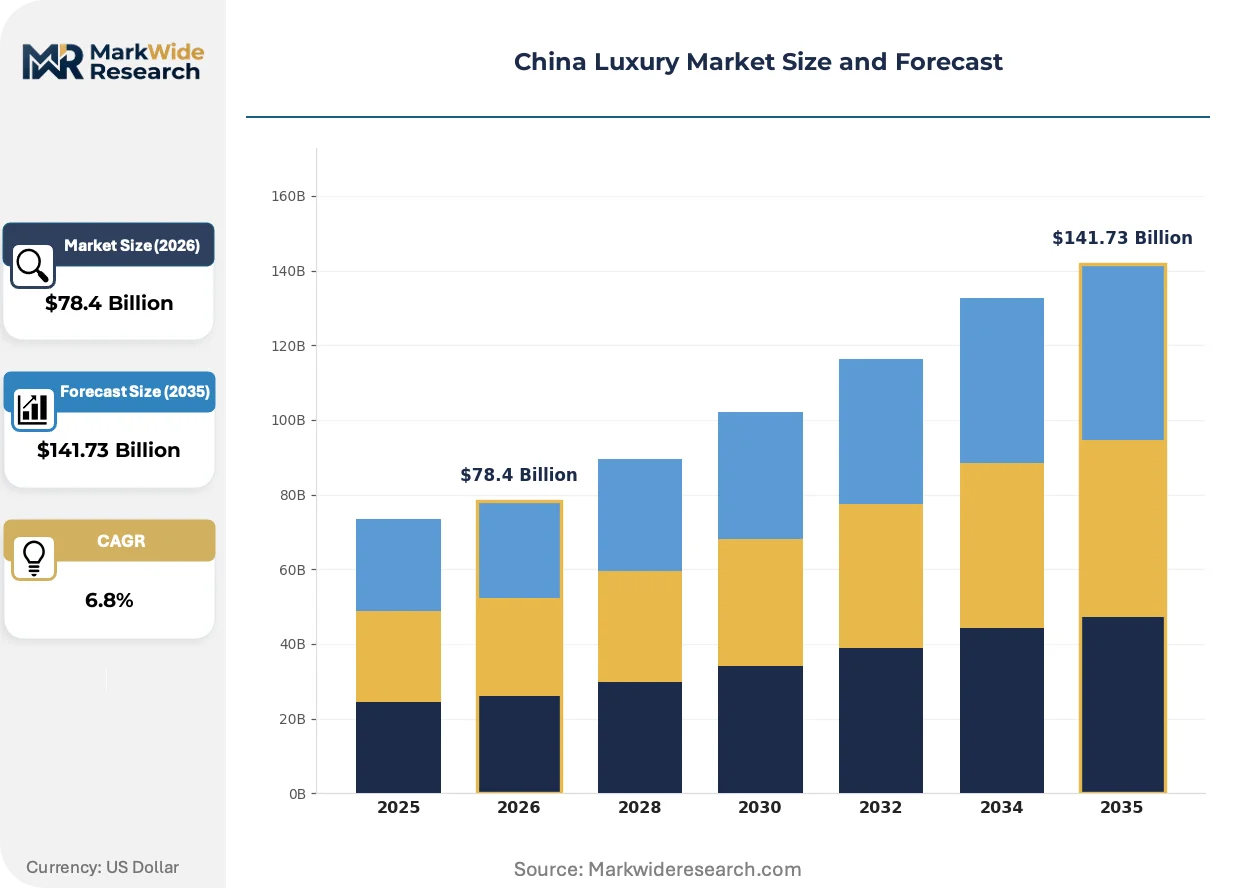
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Fashion, Watches, Jewelry, Accessories Customer Type: High Net Worth Individuals, Affluent Consumers, Millennials, Gen Z Sales Channel: Online, Brick-and-Mortar, Luxury Department Stores, Exclusive Boutiques Brand Positioning: Premium, Affordable Luxury, High-End, Exclusive |
| Companies Covered | LVMH Moët Hennessy Louis Vuitton, Kering, Hermès International, Chanel, Prada, Richemont, Estée Lauder Companies, Chow Tai Fook Jewellery Group, Li-Ning, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Luxury Market Strategic Shifts & Innovations
Digital infrastructure and sustainability mandates are converging to reshape how Chinese luxury consumers discover, validate, and purchase high-value goods across physical and virtual touchpoints.
Blockchain-based provenance authentication is automating supply chain transparency for diamond and gemstone sourcing. High-net-worth buyers in Shanghai and Beijing are demanding verifiable origin documentation at accelerating rates. This technology is automating trust-building that previously required human sales associate mediation, compressing the consideration phase for major purchases.
GB standards on textile chemical safety and recycled content are tightening disclosure requirements for imported leather goods and apparel. Brands must now submit material composition data to customs authorities before clearance. Fashion and accessories segments with complex multi-country sourcing are restructuring supplier contracts to pre-certify compliance, adding lead time but reducing seizure risk.
Private clienteling through WeChat enterprise accounts is displacing traditional email and phone outreach for millennial and Gen Z collectors. Sales associates at LVMH and Kering houses are building closed-group communities for early access drops and event invitations. This shift is most visible in Shanghai, where flagship staff maintain thousands of active one-to-one chat relationships driving repeat purchase frequency.
China Luxury Market Segmentation
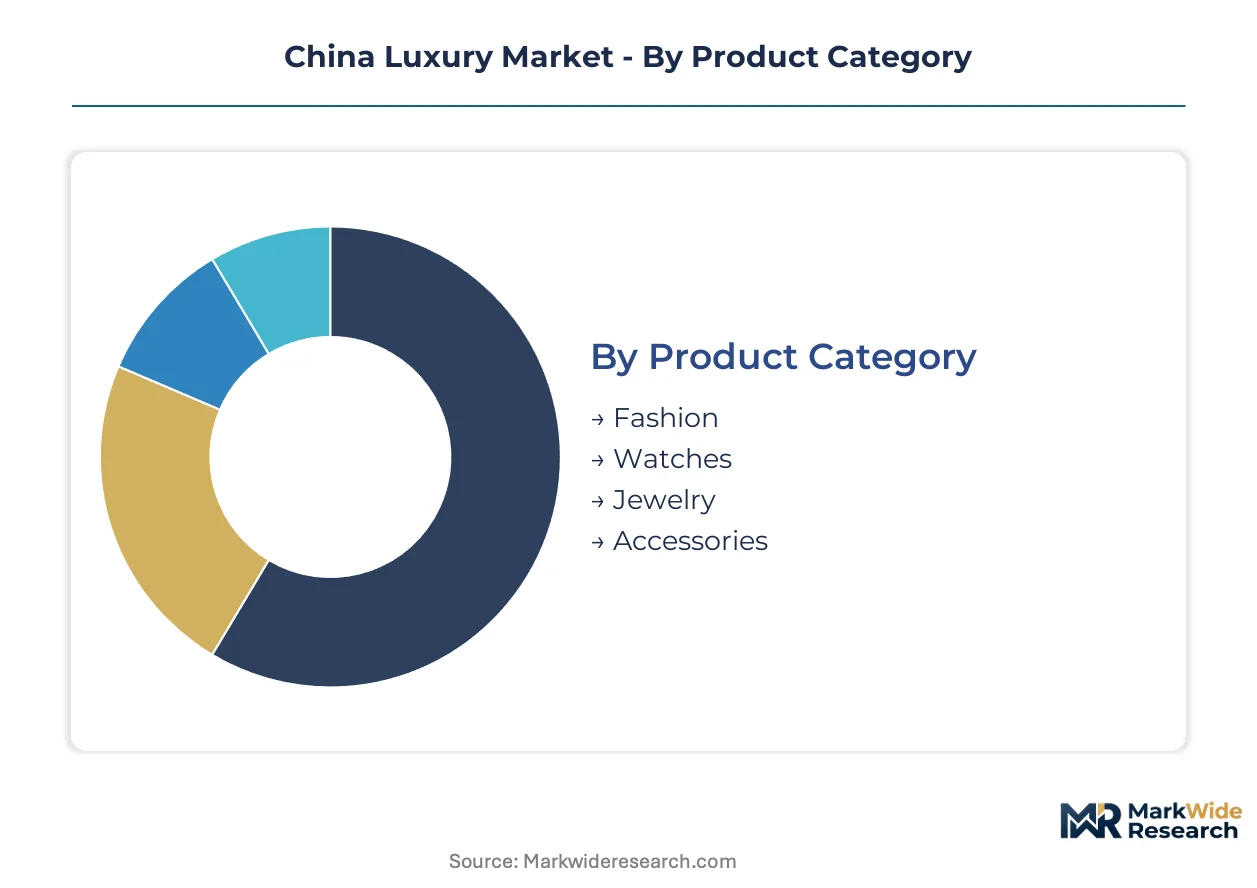
Segmentation in the China luxury market reveals how purchasing power, channel preferences, and brand positioning stratify across distinct consumer cohorts. Understanding these divides enables precise inventory allocation and boutique network planning for maisons operating in Shanghai and the Greater Bay Area.
Product Category:
Fashion and jewelry buyers prioritize material provenance and craftsmanship heritage, while timepiece collectors emphasize mechanical complication and resale value preservation.
- Fashion:Apparel and leather goods incorporating artisanal construction techniques and limited-edition drops. Shanghai flagship locations command the deepest inventory for ready-to-wear collections as experiential retail investments concentrate in first-tier cities.
- Watches:Mechanical timepieces distinguished by horological complexity and Swiss heritage manufacturing. Demand clusters among male collectors in Beijing and Shenzhen where wealth preservation motives drive repeat purchases.
- Jewelry:Gold, diamond, and gemstone pieces anchored by heritage craftsmanship.
- Accessories:Leather goods, silk goods, and small leather articles completing luxury wardrobes.
Volume sits with Fashion; growth tilts toward Jewelry as Gen Z buyers enter the market.
Customer Type:
Wealth thresholds and digital fluency create divergent purchasing rhythms across age and asset brackets.
- High Net Worth Individuals:Buyers with investable assets exceeding established thresholds who purchase bespoke and made-to-order pieces. Private clienteling through WeChat enterprise accounts dominates their discovery and transaction pathways in Shanghai.
- Affluent Consumers:Upper-middle-class buyers making occasional luxury purchases for milestone events. They respond to duty-free pricing at Hainan retail zones where customs policies favor domestic consumption.
- Millennials:Digital-native buyers aged 28-43 reshaping online channel strategies.
- Gen Z:The youngest cohort expanding most quickly with social commerce integration preferences.
Affluent Consumers provide the revenue base; Gen Z is gaining share fastest through experiential retail engagement.
Sales Channel:
Channel selection reflects convenience-versus-experience tradeoffs that vary by purchase occasion and product category.
- Online:E-commerce platforms and brand-owned digital storefronts with AR-powered visualization tools. Return rate reduction through virtual try-on convergence is reshaping inventory planning for jewelry and timepiece categories.
- Brick-and-Mortar:Standalone flagship boutiques in Shanghai and Shenzhen offering full-service clienteling. These locations capture the highest transaction values as sales associates build one-to-one relationships.
- Luxury Department Stores:Multi-brand retail environments in first-tier city commercial districts.
- Exclusive Boutiques:Scarcity-driven distribution points limiting access to reinforce brand exclusivity.
Brick-and-Mortar commands transaction value; Online is climbing the fastest on mini-program commerce adoption.
Brand Positioning:
Price architecture and distribution scarcity define competitive territory across the positioning spectrum.
- Premium:Established maisons with heritage pricing power and recognized logo equity. These brands dominate high-visibility mall placements through multi-brand architecture advantages in first-tier cities.
- High-End:Ultra-luxury houses with scarcity-driven distribution and artisanal production limits. Boutique access restrictions create artificial supply ceilings that reinforce exclusivity despite unmet demand.
- Affordable Luxury:Accessible price points democratizing brand entry for younger buyers.
- Exclusive:Invitation-only or waitlist-controlled product access for top-tier clientele.
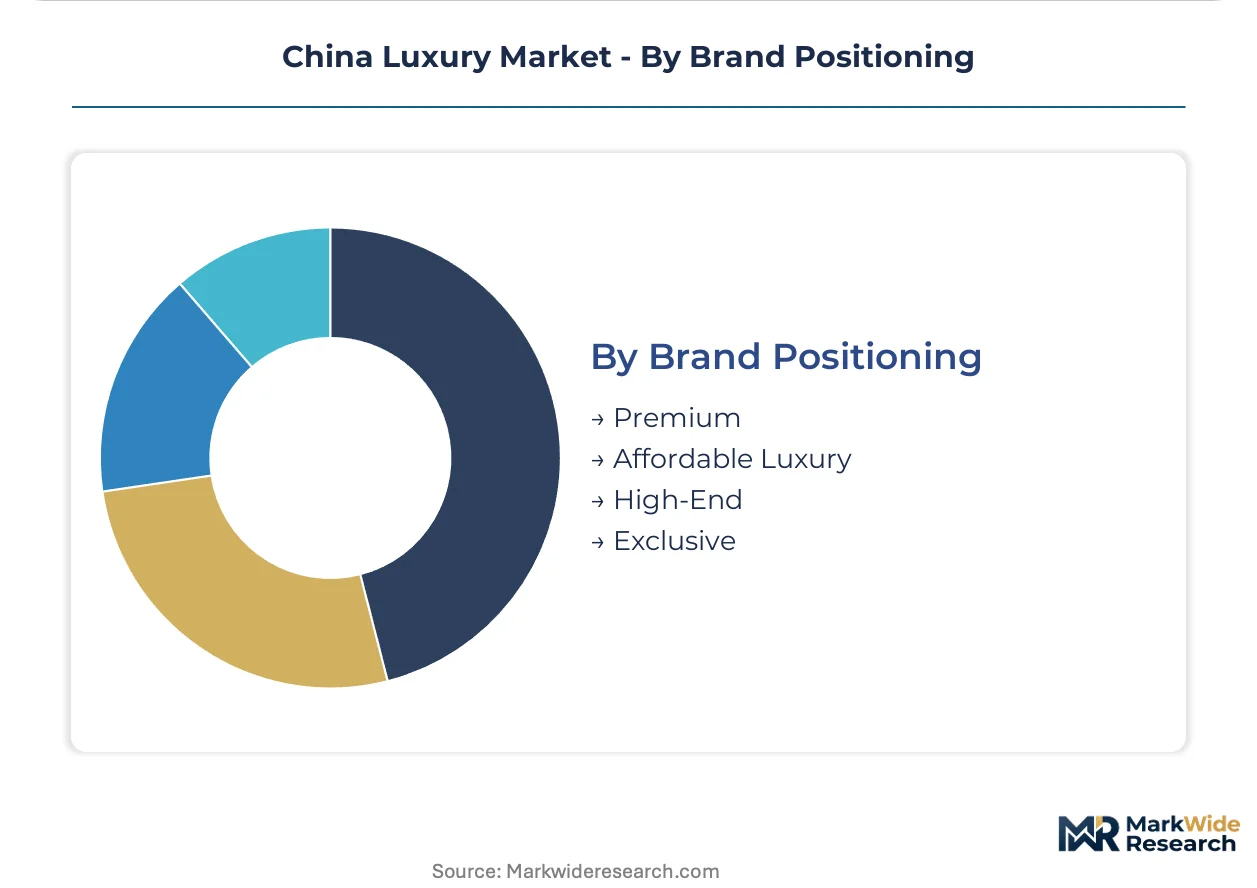
Premium positioning holds volume concentration; Exclusive tiers show the steepest expansion trajectory as brands cultivate rarity narratives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian leather tanning districts and Swiss watchmaking valleys anchor the upstream material flows feeding China's luxury consumption engine. These European supply nodes connect through Shanghai's bonded warehousing infrastructure to domestic retail endpoints. The analysis window tracks how regional sourcing patterns adapt to China's dual carbon compliance timelines.
France
Paris-based maisons command heritage pricing power through controlled scarcity distribution. The country's national climate framework pressures leather goods houses to reformulate tanning processes and reduce chemical discharge. Lyon textile clusters are piloting recycled silk programs that pre-certify GB standards compliance for China-bound shipments.
Italy
Milan and Florence anchor artisanal leather and jewelry production serving Chinese HNWI demand for made-to-order pieces. REACH chemical disclosure protocols are tightening material traceability requirements that now extend to customs pre-clearance documentation. The Tuscan tanning district is consolidating around water-recycling investments to maintain access to Shanghai flagship retail channels.
Switzerland
Geneva and Le Locle horology valleys supply mechanical timepieces prized by Beijing and Shenzhen collectors for wealth preservation. Swissmedic-equivalent watch industry self-regulation on origin labeling is converging with SAMR anti-counterfeiting enforcement demands. The Jura arc is expanding training pipelines for complication specialists as master watchmakers retire faster than apprentices qualify.
Japan
Tokyo and Osaka luxury precincts capture Chinese tourist purchasing that shifted from Hong Kong during travel restriction periods. METI circular economy guidelines on precious metal recycling are reshaping how Japanese jewelry houses source gold for China-bound collections. Ginza flagship investments are converging with WeChat mini-program integration to serve digitally native travelers.
United States
New York and Los Angeles anchor marketing and celebrity endorsement pipelines that shape Chinese Gen Z brand perception. FTC guidelines on environmental marketing claims are tightening how American houses advertise sustainability credentials to SAMR-scrutinized audiences. Manhattan showroom investments are pivoting toward virtual clienteling infrastructure that feeds Shanghai sales associate networks.
China Luxury Market Key Industry Players
Global majors compete with regional champions across distribution scarcity and digital clienteling capabilities. The vendor base stratifies into three tiers: ultra-luxury houses with waitlist-controlled access, premium maisons with multi-brand architecture advantages, and domestic jewelry specialists with heritage craftsmanship positioning. Consolidation pressure concentrates among the premium tier where scale determines mall placement leverage. Competitive moves center on experiential retail buildouts and strategic partnerships with Hainan duty-free operators.
Within the ultra-luxury scarcity tier, Hermès International exemplifies distribution-limiting strategies that reinforce exclusivity despite unmet demand. Among French-based conglomerates, LVMH Moët Hennessy Louis Vuitton and Kering occupy positions defined by multi-brand portfolio breadth and flagship retail density in Shanghai. Chow Tai Fook Jewellery Group anchors the domestic specialist archetype, leveraging heritage gold craftsmanship and localized design studios to capture jewelry demand outside foreign house dominance.
| Leading Market Players |
|---|
| LVMH Moët Hennessy Louis Vuitton |
| Kering |
| Hermès International |
| Chanel |
| Prada |
| Richemont |
| Estée Lauder Companies |
| Chow Tai Fook Jewellery Group |
| Li-Ning |
| Others |
Cost & Logistics Intelligence
Gold price volatility cascades through jewelry supply chains into three-tier pricing structure across premium, standard, and economy levels, with heritage craftsmanship segments absorbing raw material spikes through limited-edition scarcity mechanics rather than transparent pass-through.
Pricing Analysis
Warranty and authentication service bundling separates ultra-luxury waitlist tiers from premium ready-to-wear, with blockchain provenance documentation now standard at scarcity-driven houses while mass-market jewelry remains unbundled. Price differentiation hinges on artisan certification tier and geographic flagship density, with Shanghai boutique placements commanding significant premiums over Greater Bay Area equivalents. Cost compression in gold-dependent jewelry segments is intensifying because raw material hedging coverage has thinned; affluent consumers in Hainan duty-free zones show highest price sensitivity while HNWI bespoke buyers remain elasticity-proof.
Supply Chain Analysis
GB textile sustainability certification gates access to Shanghai flagship retail channels, forcing European tanneries and silk weavers to pre-submit chemical disclosure documentation before customs clearance. Manufacturing gravity centers on France for leather goods, Italy for artisanal jewelry, and Switzerland for mechanical timepieces, with each node drawing from distinct raw material pools: Tuscan vegetable-tanned hides, Jura watch movement components, Lyon silk filament. Single-source vulnerability concentrates in master craftspeople pipelines as heritage gold workers and leather marquetry specialists retire faster than apprentices qualify. Distribution runs through Shanghai bonded warehousing into flagship boutique networks, with Hainan duty-free zones capturing offshore purchasing previously routed through Hong Kong.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artisan talent scarcity props pricing power across heritage craftsmanship segments, with master goldsmith and leather marquetry pipelines constraining volume expansion regardless of unmet demand signals.
For Market Incumbents: Acquire distressed atelier capabilities in Italian tanning districts and Swiss watchmaking valleys before training pipeline gaps widen further. Secure multi-year apprenticeship contracts with École Boulle and similar craft institutions to lock emerging talent flows. Defend against digital-native entrants by embedding AR visualization tools into WeChat enterprise clienteling workflows before Gen Z buyers fully migrate to virtual-first discovery. For New Entrants and Emerging Players: Second-tier city affluent consumers outside Shanghai-Shenzhen flagship density represent the most penetrable white-space target, with price-sensitive jewelry demand underserved by scarcity-distribution houses. Hainan duty-free zone presence offers lower capital entry than mainland flagship buildouts, with customs policies favoring domestic consumption. Go-to-market through WeChat mini-program commerce with virtual try-on convergence reduces return rate risk in online jewelry categories. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-size Italian leather goods houses with GB standards compliance already certified but lacking China distribution scale. Long-term viability in the 5-10 year window rests on dual carbon alignment and digital clienteling infrastructure deployment. The signal to watch is SAMR enforcement intensity on gray-market crackdowns, which would accelerate formal channel consolidation and reward compliant operators.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Atelier Acquisition | Captures retiring master craftspeople pipelines before training gaps widen in Tuscan and Jura production clusters. |
| GB Standards Pre-Certification | Locks customs clearance priority for Lyon textile and Florence leather shipments into Shanghai bonded warehousing. |
| WeChat Enterprise Clienteling Scale-Up | Mirrors LVMH and Kering closed-group community models driving repeat purchase frequency among millennial collectors. |
| Hainan Duty-Free Zone Partnership | Captures offshore purchasing flow previously routed through Hong Kong with favorable customs consumption policies. |
| AR Virtual Try-On Deployment | Reduces return rates in online jewelry and timepiece channels through WeChat mini-program integration. |
Research Approach
Document review covered SAMR regulatory filings, GB standards technical documentation, and European tannery REACH compliance records, complemented by interviews with Shanghai flagship retail directors, Milan atelier production heads, and Shenzhen duty-free zone operators. Secondary validation drew from customs trade data, LVMH and Kering annual disclosures, and Chow Tai Fook jewelry segment reports. Bottom-up channel volume estimates triangulated against top-down wealth concentration data from Greater Bay Area and Shanghai metropolitan statistical sources.
Cross-referencing historical pricing elasticity patterns against expert panel input on Gen Z purchasing behavior shifts shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product category, customer wealth tier, sales channel format, and brand positioning scarcity level. CAGRs derived from trend-line extrapolation adjusted for dual carbon policy implementation pace and SAMR enforcement intensity variations. Industry-specific inputs incorporated gold price volatility scenarios and master craftsperson retirement rate projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to dual carbon compliance timeline acceleration and cross-border data privacy framework evolution. Forecasts reflect documented assumptions on wealth concentration persistence in Shanghai and Greater Bay Area nodes. A model refresh is warranted upon material change in SAMR gray-market enforcement intensity or Hainan duty-free customs policy adjustment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Brazil Luxury Goods Market
Luxury Goods
France Luxury Goods Market
Luxury Goods
Europe Secondhand Luxury Goods Market
Luxury Goods
Luxury Products for Kids Market
Luxury Goods
Russia Luxury Goods Market
Luxury Goods
Hard Luxury Goods Market
Luxury Goods
Mexico Luxury Goods Market
Luxury Goods
China Luxury Goods Market
Luxury Goods
Spain Luxury Jewelry Market
Luxury Goods
UAE Luxury Jewelry Market
Luxury Goods
Secondhand Luxury Goods Market
Luxury Goods
Qatar Luxury Good Market
Luxury Goods
Global Gold and Diamond Jewellery Market
Luxury Goods
Luxury Pen Market
Luxury Goods
Personal Luxury Goods Market
Luxury Goods
Luxury Apparels Market