
 Luxury Piano Market | 2026-2036
Luxury Piano Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Piano Market Insights
The gap between artisan-built luxury pianos and mass-produced instruments is consolidating around hand-voiced soundboards and bespoke cabinetry. Steinway & Sons anchors its position through vertical integration into Alaskan spruce sourcing and proprietary rim-bending processes. Bösendorfer differentiates via its extended keyboard range and Viennese tonal character. Yamaha leverages hybrid manufacturing precision to compete across both concert-grand and aspirational-consumer tiers.
A luxury piano denotes an acoustically engineered stringed instrument constructed from resonant tonewoods such as Sitka spruce soundboards and hard-rock maple rims, designed for concert-grade sustain and dynamic response in professional performance environments. Grand pianos occupy the dominant margin pool due to institutional procurement cycles and heirloom investment profiles, while hybrid pianos attract technology-integrated buyers seeking acoustic action with digital silence. Individual buyers and professional musicians channel premium pricing through direct sales and specialty music stores rather than online retailers.
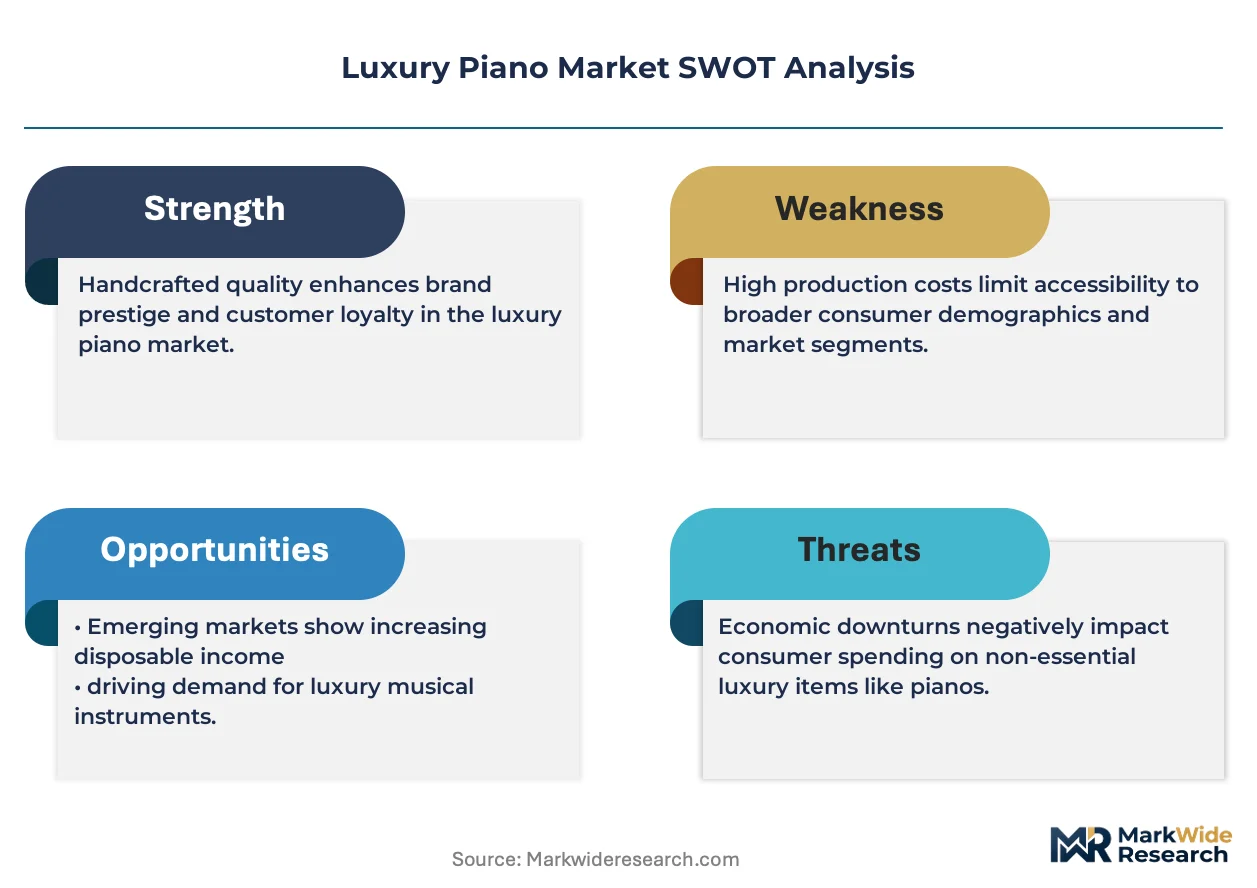
The US EPA regulates volatile organic compound emissions from piano lacquers and finishes, compelling manufacturers to reformulate coatings or absorb compliance costs. Japan's METI standards for musical instrument safety shape export requirements for Asian manufacturers serving domestic conservatories. The EU Timber Regulation mandates chain-of-custody documentation for tropical hardwoods, restricting material sourcing for mahogany and walnut components. Stakeholders must weigh climate-control infrastructure investments against evolving acoustic-purity certifications as collection and performance use cases diverge.
Market Dynamics
Hand-voiced soundboard craftsmanship is compressing production timelines while EU F-Gas Regulation mandates force retooling of climate-controlled storage infrastructure across European collections.
Growth Catalysts
- EU F-Gas Regulation Phase-Down:Climate-controlled conservatory storage facilities must replace hydrofluorocarbon-based humidity systems with sustainable alternatives, creating replacement demand for precision environmental equipment.
- Tokyo and Osaka Metropolitan Procurement:Japan's METI-certified institutional buyers channel concentrated demand through direct manufacturer relationships for concert-grade instruments.
- Alaskan Spruce Sourcing Control:Captive timber supply agreements for resonant tonewood are securing acoustic consistency for heirloom-grade production runs.
Market Restraints
- Tropical Hardwood Documentation Burden:EU Timber Regulation chain-of-custody requirements restrict mahogany and walnut component sourcing to certified suppliers, extending procurement cycles.
- Artisan Capacity Bottleneck:Master voicer and rim-bending specialist availability concentrates in Vienna and Hamburg, limiting scalable hand-finishing throughput.
- Hybrid Digital Substitution:Silent-capable hybrid pianos with acoustic action are capturing technology-integrated buyer segments previously committed to pure acoustic instruments.
Strategic Opportunities
- Acoustic-Purity Certification Divergence:Separate collection-grade and performance-grade certification pathways allow manufacturers to segment heirloom investment buyers from working professional users.
- Sustainable Humidity System Integration:Climate-control infrastructure investments align with evolving acoustic-purity storage standards for institutional collections.
- Specialty Music Store Channel Reinforcement:Direct sales relationships through curated retail networks bypass online price transparency for premium buyer segments.
Industry Challenges
- Master Craftsman Succession Planning:Multi-decade apprenticeship requirements for soundboard voicing and rim-bending specializations face generational transfer gaps.
- Reformulated Coating Compliance Timelines:US EPA volatile organic compound emission limits for piano lacquers require accelerated finish chemistry redevelopment without tonal property degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Piano Market |
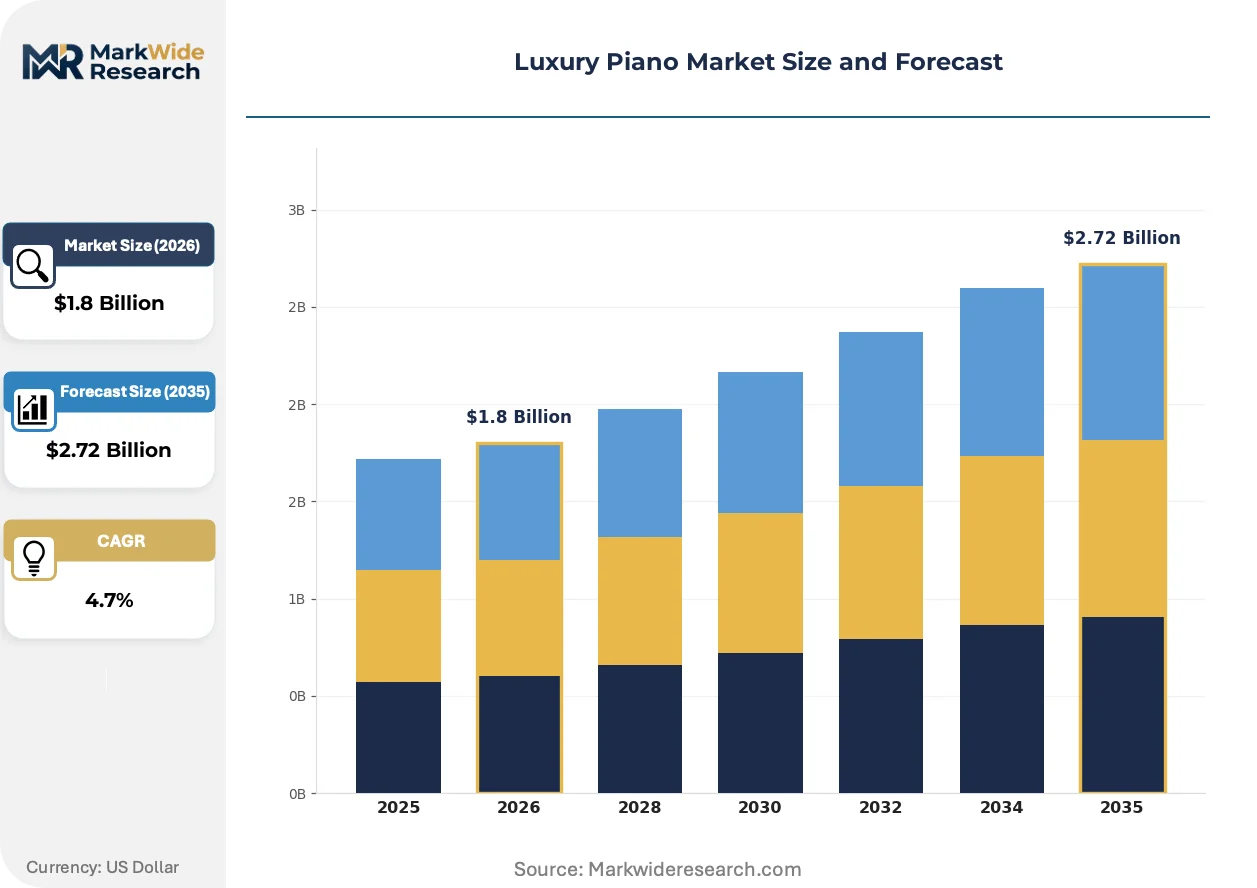
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grand Pianos, Upright Pianos, Digital Pianos, Hybrid Pianos Material: Mahogany, Spruce, Maple, Walnut Customer Type: Individual Buyers, Educational Institutions, Professional Musicians, Event Venues Distribution Channel: Online Retailers, Specialty Music Stores, Direct Sales, Auctions |
| Companies Covered | Fazioli, Steinway & Sons, Yamaha, Bösendorfer, Kawai, C. Bechstein, Blüthner, Schimmel, Sauter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Piano Market Trends and Innovations
Precision manufacturing convergence with acoustic heritage is redefining competitive differentiation across handcrafted and technology-integrated instrument tiers.
Active soundboard sensor arrays are consolidating real-time tonal feedback capabilities into performance instruments. Concert hall technical directors in Vienna and Berlin are piloting these systems for venue-specific voicing calibration. The technology is consolidating previously separate acoustic adjustment and digital monitoring workflows into unified instrument management platforms.
EU F-Gas Regulation refrigerant phase-down mandates are compelling storage facility operators to retrofit humidity control infrastructure. Climate-controlled warehouse operators serving private collections must absorb compliance costs or pass through to collectors. German and Austrian conservatory storage facilities are responding fastest due to proximity to regulatory enforcement capacity.
Heirloom investment buyers are rotating procurement toward direct manufacturer relationships with documented provenance chains. Specialty music stores in Japan and Germany are capturing this shift through white-glove consultation services that online channels cannot replicate. Tokyo metropolitan conservatories exemplify the preference for verified craftsmanship documentation over price-optimized transactions.
Luxury Piano Market Segmentation
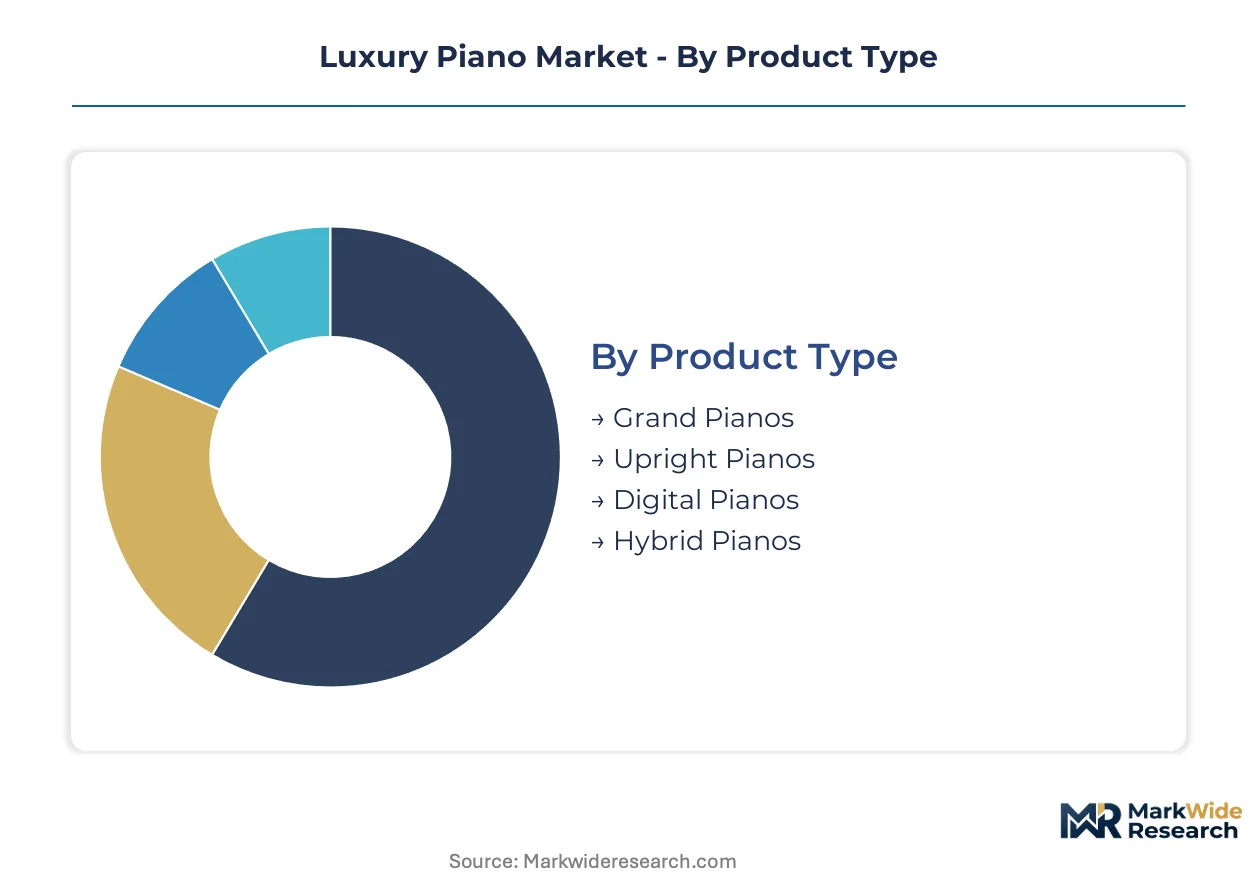
Segmentation in the luxury piano market tracks how buyer priorities diverge between acoustic heritage and technology integration. Procurement patterns split across institutional volume buyers and individual collectors seeking provenance documentation.
Product Type:
Buyers choose between acoustic purity and silent-capable flexibility based on performance environment constraints.
- Grand Pianos:Concert-grade instruments with horizontal soundboard orientation deliver maximum sustain and dynamic range. Institutional procurement in Japan's metropolitan conservatories concentrates demand for nine-foot concert grands with documented hand-voicing.
- Hybrid Pianos:Acoustic key action pairs with digital sound generation for silent practice capability. Technology-integrated buyers in residential settings are shifting procurement toward these instruments as apartment living restricts acoustic playing hours.
- Upright Pianos:Vertical string arrangement suits space-constrained professional studios and smaller educational facilities.
- Digital Pianos:Sampled sound reproduction targets entry-level aspirational buyers and secondary practice instruments.
Volume sits with Grand Pianos; growth tilts toward Hybrid Pianos.
Material:
Tonewood selection determines acoustic signature and regulatory compliance burden simultaneously.
- Spruce:Sitka and Alaskan spruce varieties provide resonant soundboard cores with optimal stiffness-to-weight ratios. Captive sourcing agreements in North American timber regions are securing supply consistency for heirloom-grade production.
- Mahogany:Dense hardwood for rim and case construction offers tonal warmth and aesthetic depth. EU Timber Regulation chain-of-custody requirements restrict procurement to certified tropical suppliers, extending lead times.
- Maple:Hard-rock maple rims deliver structural stability and bright tonal character for concert instruments.
- Walnut:Premium cabinetry material for bespoke finishes commands collector premiums in German and Austrian markets.
Procurement volume clusters around Spruce; Mahogany faces the steepest compliance-driven supply constraints.
Customer Type:
Purchasing authority and decision criteria fragment across use-case requirements.
- Educational Institutions:METI-certified conservatories in Tokyo and Osaka drive concentrated demand through direct manufacturer relationships. Procurement cycles align with fiscal-year budgeting and acoustic-purity certification requirements.
- Individual Buyers:Heirloom investment collectors prioritize documented provenance and master craftsman attribution. White-glove consultation through specialty music stores in Germany and Japan captures this segment away from price-transparent channels.
- Professional Musicians:Working performers balance instrument portability against venue-specific voicing requirements.
- Event Venues:Concert halls and recital spaces maintain fleet inventories with active sensor arrays for real-time tonal calibration.
Revenue concentration rests with Educational Institutions; Individual Buyers are expanding most quickly as Asian high-net-worth collectors deepen market participation.
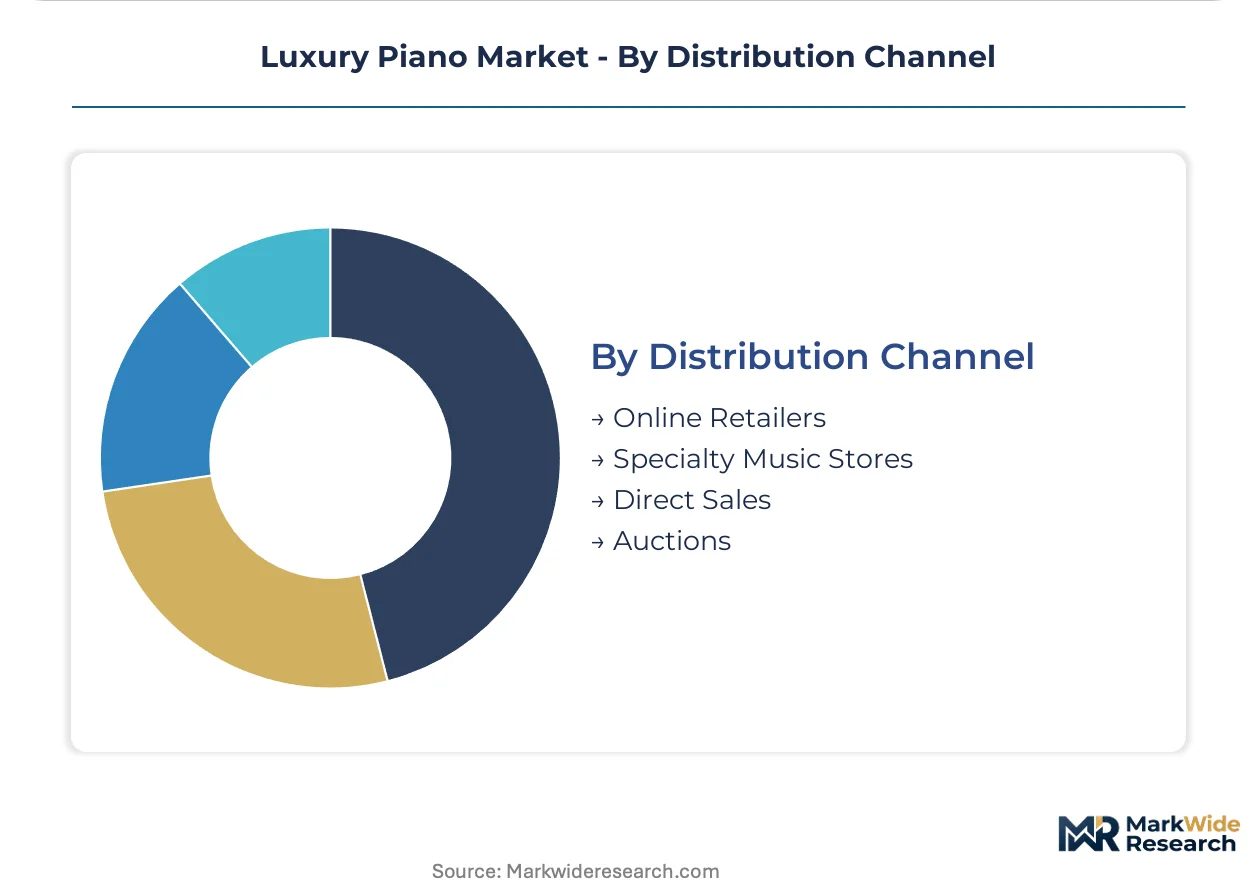
Distribution Channel:
Channel selection determines price transparency and service bundling available to buyer segments.
- Specialty Music Stores:Curated retail networks in Vienna, Hamburg, and Tokyo provide consultation, voicing adjustment, and maintenance bundling. These stores capture premium buyer segments seeking verified craftsmanship documentation.
- Direct Sales:Manufacturer relationships enable bespoke specification and provenance documentation for heirloom investment buyers. Steinway and Bösendorfer leverage this channel for institutional and collector segments.
- Auctions:Secondary market transactions for vintage instruments with historical performance attribution.
- Online Retailers:Price-transparent platforms serve entry-level digital and hybrid piano segments.
Transaction value concentrates in Specialty Music Stores; Direct Sales channels are gaining share fastest among institutional and collector segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo and Osaka metropolitan conservatories channel concentrated procurement through direct manufacturer relationships, anchoring institutional demand patterns across the Pacific Rim. Vienna and Hamburg production clusters supply hand-voiced instruments to collectors worldwide. New York and London serve as secondary market liquidity centers for heirloom-grade transactions.
Japan
Tokyo metropolitan conservatories and Osaka concert halls drive institutional procurement cycles aligned with METI-certified safety standards. The Ministry of Economy, Trade and Industry shapes export requirements for domestic manufacturers serving conservatory networks. Kanto and Kansai regions concentrate high-net-worth collector demand for documented provenance instruments.
United States
New York auction houses and Los Angeles recording studios sustain secondary market liquidity for vintage instruments with performance attribution. EPA volatile organic compound emission limits for piano lacquers compel coating reformulation without tonal degradation. Steinway & Sons' Queens manufacturing facility exemplifies captive Alaskan spruce sourcing for resonant soundboard production.
Germany
Hamburg and Berlin production clusters anchor European hand-finishing capacity for concert-grade instruments. EU F-Gas Regulation mandates force retooling of climate-controlled storage infrastructure across conservatory collections. Bavarian specialty music stores capture collector segments through white-glove consultation services unavailable through price-transparent channels.
Austria
Vienna's rim-bending and soundboard voicing specialists concentrate multi-decade apprenticeship expertise for heirloom-grade production. EU Timber Regulation chain-of-custody documentation restricts tropical hardwood sourcing for mahogany and walnut components. Austrian conservatory storage facilities respond fastest to sustainable humidity system mandates due to regulatory enforcement proximity.
United Kingdom
London dealer networks and Edinburgh recital halls maintain fleet inventories for performance-grade instrument circulation. REACH chemical safety standards influence finish chemistry redevelopment timelines across European manufacturing. British specialty retailers emphasize provenance documentation for Asian collector segments seeking verified craftsmanship attribution.
Luxury Piano Market Competitive Landscape
Capital-heavy producers with captive timber agreements compete with design-focused ateliers outsourcing component fabrication. Market structure consolidates around three to five heritage houses controlling hand-voicing expertise and institutional procurement relationships. Strategic archetypes separate vertical integrators securing Alaskan spruce supply, Viennese tonal specialists extending keyboard range, and precision manufacturers bridging acoustic and hybrid tiers. Dominant competitive moves include direct sales channel expansion for collector segments and sustainable humidity system integration for institutional storage contracts.
Among heritage European houses, Steinway & Sons, Bösendorfer, and Fazioli exemplify distinct competitive positioning archetypes. Steinway & Sons represents the vertically integrated model with upstream timber control. Bösendorfer occupies the extended-range tonal specialist position within Viennese production traditions. Fazioli anchors the ultra-premium concert grand segment with limited production scale. Yamaha and Kawai sit within the precision manufacturing tier competing across acoustic and hybrid instrument categories. C. Bechstein, Blüthner, and Schimmel represent German-speaking regional specialists with concentrated domestic and adjacent European market presence.
| Leading Market Players |
|---|
| Fazioli |
| Steinway & Sons |
| Yamaha |
| Bösendorfer |
| Kawai |
| C. Bechstein |
| Blüthner |
| Schimmel |
| Sauter |
| Others |
Pricing and Supply Chain Analysis
Alaskan spruce soundboard material costs cascade through three distinct pricing tiers based on hand-voicing certification levels and provenance documentation depth. Master craftsman attribution and METI-certified safety compliance separate heirloom-grade instruments from working professional tiers, with EU Timber Regulation documentation burdens compressing margins on mahogany and walnut components.
Pricing Analysis
Acoustic-purity certification anchors value-based pricing across collection-grade and performance-grade pathways. Price differentiation separates instruments with documented rim-bending specialist attribution from precision-manufactured alternatives, while sustainable humidity system integration commands premium positioning for institutional storage contracts. Cost compression in mid-tier hybrid pianos intensifies due to digital substitution pressure, with technology-integrated residential buyers exhibiting highest price sensitivity and Tokyo metropolitan conservatories showing least.
Supply Chain Analysis
EU Timber Regulation chain-of-custody certification gates tropical hardwood sourcing for mahogany and walnut components. Geographic supply concentration clusters in Austria, Germany, and Japan for hand-finishing expertise, with raw material dependencies on Alaskan spruce, hard-rock maple, and certified tropical hardwoods. Single-source vulnerability concentrates in Vienna and Hamburg for master voicer availability. Distribution runs through specialty music stores in Tokyo, Vienna, and Hamburg for premium buyer segments, with direct manufacturer relationships capturing institutional and collector demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive timber agreements and climate-control infrastructure investments determine competitive durability. Players securing upstream Alaskan spruce sourcing and downstream storage facility contracts capture margin pools unavailable to component-assemblers.
For Market Incumbents: Anchor market position through captive Alaskan spruce supply agreements and proprietary rim-bending process documentation. Hybrid digital substitution threatens pure acoustic tier volume; respond with acoustic-purity certification divergence that segments heirloom investment buyers from working professionals. Master craftsman succession planning represents the critical defensive lever. For New Entrants and Emerging Players: Begin with sustainable humidity system integration for EU F-Gas Regulation compliance contracts in German and Austrian conservatory storage facilities. White-glove consultation services through specialty music stores in Japan offer the most penetrable channel angle, as online price transparency cannot replicate provenance documentation capabilities. For Investors and Strategic Acquirers: Master voicer apprenticeship program expansion is the leading indicator that hand-finishing capacity will sustain across generational transfer gaps. Long-term viability centers on heritage houses with documented craftsmanship lineage and institutional procurement relationships. Watch for accelerated EU F-Gas Regulation enforcement triggering climate-control infrastructure replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Timber Supply Agreement | Alaskan spruce sourcing control secures acoustic consistency for heirloom-grade production runs. |
| Sustainable Humidity System Integration | EU F-Gas Regulation compliance creates replacement demand for precision environmental equipment. |
| Master Craftsman Apprenticeship Program | Multi-decade training pipelines address generational transfer gaps in soundboard voicing expertise. |
| Direct Sales Channel Expansion | Manufacturer relationships enable bespoke specification for METI-certified institutional buyers. |
| Acoustic-Purity Certification Divergence | Separate collection-grade and performance-grade pathways segment heirloom investment from working professional users. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with master voicers, conservatory procurement directors, specialty music store owners, and climate-control equipment manufacturers combined with bottom-up and top-down triangulation. Secondary sources included EU Timber Regulation chain-of-custody databases, METI safety standard documentation, EPA volatile organic compound emission filings, and piano manufacturer production disclosures.
Data-stream reconciliation across shipment volumes, institutional procurement cycles, and collector transaction records informed the analytical framework. Segmentation dimensions modeled encompass product type, material certification tier, customer category, and distribution channel across the projection horizon. CAGRs derived from fitted growth curves incorporating Alaskan spruce supply constraints, EU F-Gas Regulation compliance timelines, and Asian high-net-worth collector penetration patterns.
Underlying measurement precision varies by segment; grand piano institutional procurement carries tighter precision than individual collector transactions. Forecasts reflect assumptions regarding master craftsman availability, regulatory enforcement intensity, and hybrid technology substitution rates. A model refresh is warranted upon material change in EU F-Gas Regulation implementation pace or Alaskan spruce harvest quota adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
North America Luxury Goods Market
Luxury Goods
Used Luxury Bags Trading Service Market
Luxury Goods
United Arab Emirates Luxury Goods Market
Luxury Goods
GCC Luxury Goods Market
Luxury Goods
India Watch Market
Luxury Goods
Wooden Watch Market
Luxury Goods
Luxury Products for Kids Market
Luxury Goods
United States Luxury Goods Market
Luxury Goods
United States Secondhand Luxury Goods Market
Luxury Goods
Spain Luxury Goods Market
Luxury Goods
Thailand Luxury Goods Market
Luxury Goods
China Luxury Goods Market
Luxury Goods
Russia Luxury Goods Market
Luxury Goods
Mens Watch Market
Luxury Goods
Pre-Owned Luxury Watches Market
Luxury Goods
Luxury Apparels Market