
 Ultrasonic Pulse Velocity Tester Market | 2026-2036
Ultrasonic Pulse Velocity Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Pulse Velocity Tester Market Outlook
A shortage of certified non-destructive testing technicians is redrawing competitive dynamics across the supply base. Proceq Group leverages its Swiss engineering heritage to sustain premium positioning in digital portable units. Controls S.p.A. anchors Southern European demand through deep relationships with Italian infrastructure agencies. James Instruments Inc. competes on price-accessible analog systems for mid-tier contractors.
Ultrasonic pulse velocity testers emit high-frequency mechanical waves through concrete, masonry, or rock, measuring transit time to infer material uniformity, crack depth, and compressive strength; typical operating frequencies range from 24 kHz to 250 kHz depending on aggregate size and member thickness. Portable digital units command the largest revenue share due to field versatility, while wireless technology represents the fastest-expanding configuration as site connectivity standards mature. Desktop systems retain stable demand within research institutions where laboratory calibration protocols require stationary precision.
ASTM C597 and EN 12504-4 establish pulse velocity measurement standards that manufacturers must satisfy for North American and European market access, while ISO 1920-7 provides international reference methodology. The US Federal Highway Administration and Germany's Federal Institute for Research on Building, Urban Affairs and Spatial Development both incorporate ultrasonic testing into bridge condition assessment guidelines. Stakeholders must weigh capital deployment between established analog reliability and digital platform ecosystems that promise workflow integration but demand recurring software commitments.
Market Dynamics
The shortage of certified non-destructive testing technicians is compressing equipment utilization rates and forcing manufacturers toward automated waveform interpretation. Digital signal processing capabilities now determine competitive positioning more than hardware durability.
Growth Catalysts
- ASTM C597 and EN 12504-4 compliance mandates:Federal highway administrations in the United States and Germany require periodic structural assessments, creating recurring equipment procurement cycles for bridge and tunnel networks.
- Wireless connectivity integration:Site-wide IoT infrastructure on major infrastructure projects enables real-time data transmission from field units to central monitoring systems.
- Aging concrete stock:Post-war infrastructure across North America and Western Europe exceeds design life thresholds, expanding assessment frequency requirements.
Market Restraints
- Piezoelectric transducer supply concentration:Specialty ceramic manufacturing clusters in Japan and Germany create single-source vulnerability for critical sensor components.
- High aggregate variability in field concrete:Non-uniform material composition produces inconsistent pulse velocity readings, limiting standardized strength correlation accuracy.
- ISO 1920-7 calibration complexity:Laboratory reference block requirements impose capital burdens on smaller testing contractors seeking accreditation.
Strategic Opportunities
- India's Smart Cities Mission:Urban infrastructure monitoring protocols create first-mover advantage for digital portable unit suppliers establishing service networks.
- Cloud-based waveform analytics:Machine learning pattern recognition for crack classification converges with edge computing hardware to differentiate premium offerings.
- Subscription software ecosystems:Recurring revenue models for interpretation algorithms offset hardware margin compression in mature European markets.
Industry Challenges
- ASNT Level II certification scarcity:Training pipeline constraints limit field deployment capacity, extending project timelines for structural assessment contractors.
- Legacy analog system integration:Mixed fleet environments complicate data standardization when contractors upgrade equipment incrementally rather than replacing entire inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Pulse Velocity Tester Market |
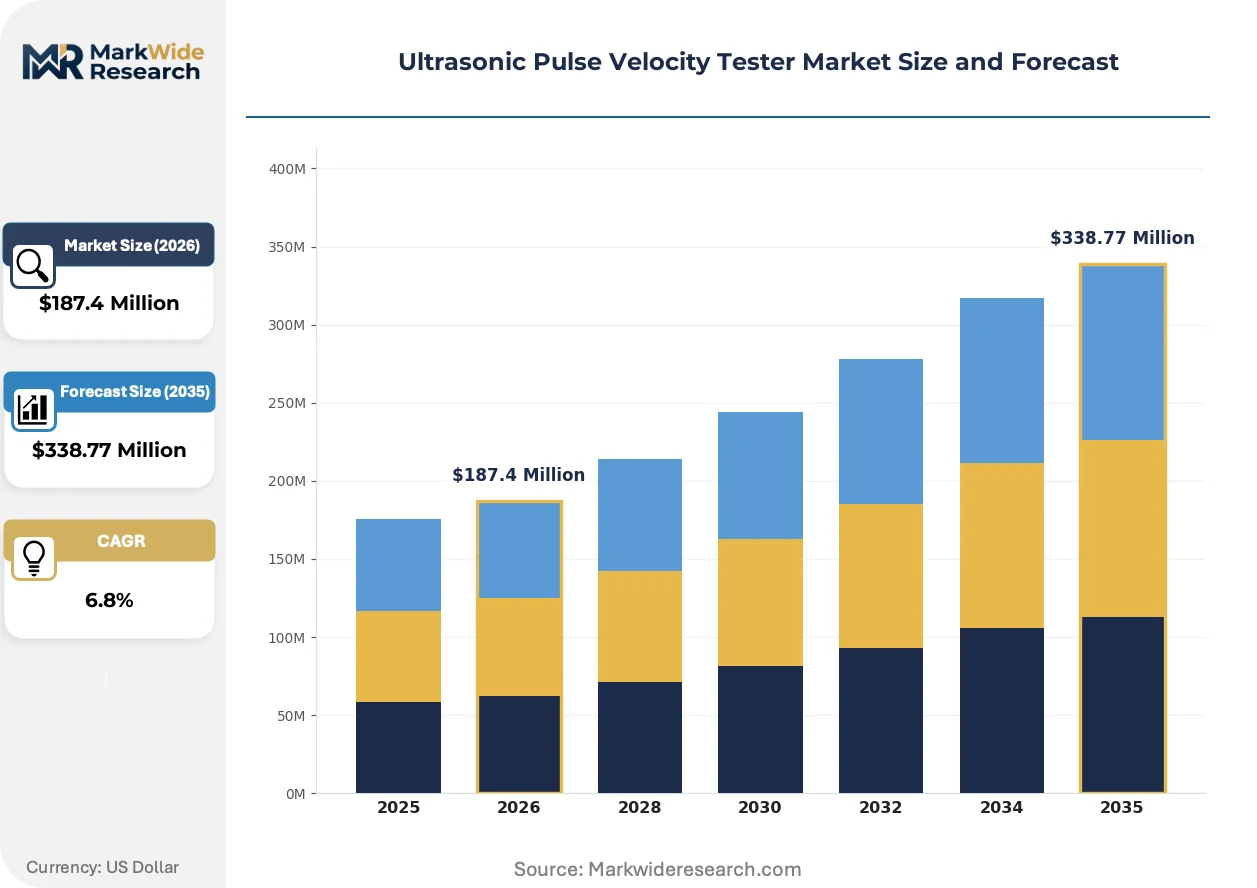
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Desktop, Handheld, Fixed Technology: Digital, Analog, Hybrid, Wireless End User: Construction, Civil Engineering, Material Testing, Research Institutions Application: Concrete Testing, Soil Analysis, Structural Integrity, Non-Destructive Testing |
| Companies Covered | Proceq Group, Controls S.p.A., Roop Telsonic Ultrasonix, Stanlay, Canopus Instruments, James Instruments Inc., Aimil Ltd., Humboldt Mfg. Co., Impact Test Equipment Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Pulse Velocity Tester Market Strategic Shifts
Signal processing automation is compressing the technician-to-output ratio, while connectivity standards reshape how field data flows into asset management systems. Equipment differentiation increasingly hinges on software interpretation depth rather than transducer sensitivity.
Artificial intelligence-driven crack classification is supplanting manual waveform interpretation in high-volume inspection environments. Large infrastructure asset managers in Germany and the United States are deploying AI-augmented units on major bridge rehabilitation contracts. This compression of interpretation labor is reshaping staffing models for regional testing contractors.
REACH substance restrictions on lead-based piezoelectric materials are accelerating ceramic formulation transitions across European supply chains. Manufacturers must recalibrate transducer production lines to maintain CE marking eligibility. The regulatory pressure falls most heavily on mid-tier analog system producers with limited R&D bandwidth.
Equipment-as-a-service arrangements are displacing outright purchase models among municipal infrastructure agencies with constrained capital budgets. Leasing providers bundle calibration maintenance and software updates into multi-year contracts. This shift is most pronounced in United States state transportation departments managing distributed bridge inventories.
Ultrasonic Pulse Velocity Tester Market Segmentation
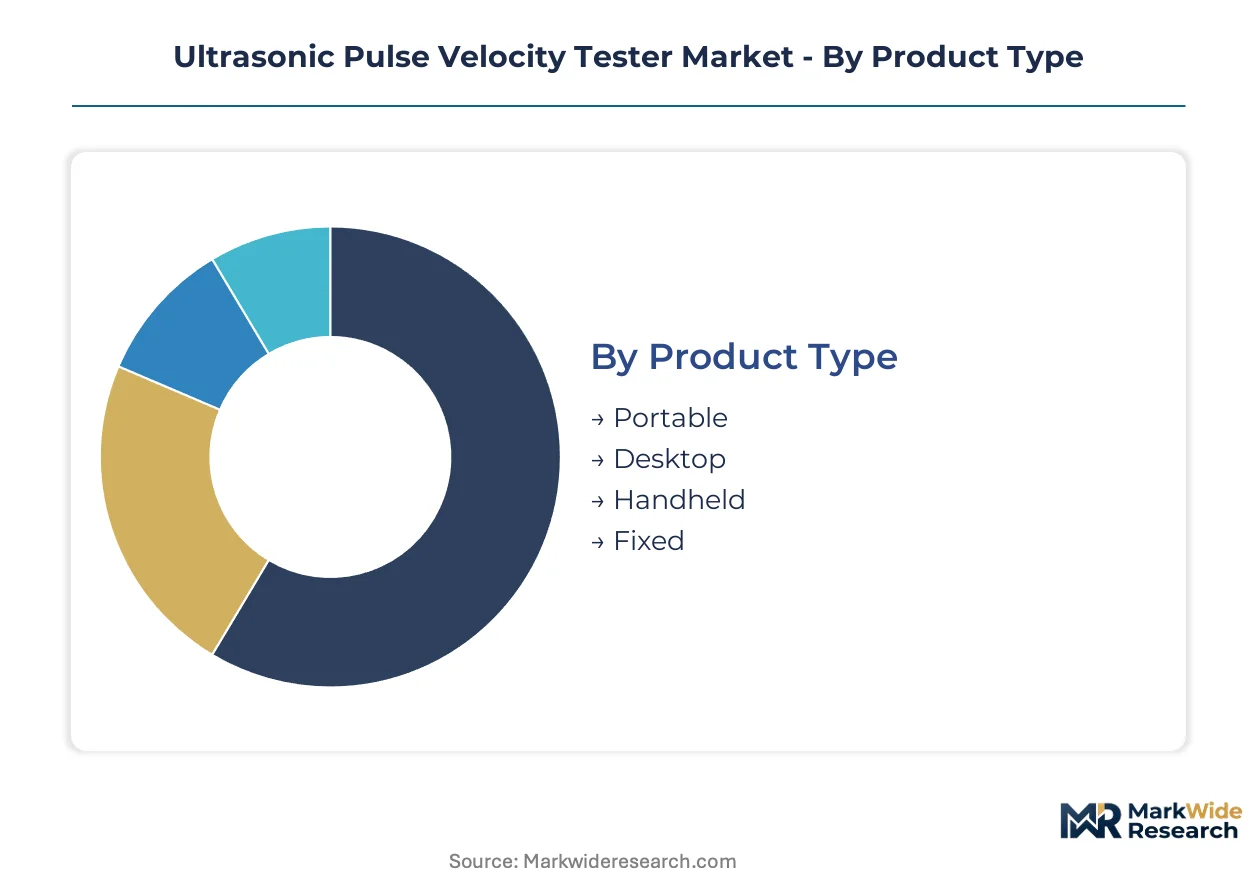
Equipment configuration determines technician productivity and data fidelity across inspection workflows. Segment boundaries reflect trade-offs between field portability and laboratory precision, between upfront hardware investment and recurring software commitments.
Product Type:
Portable units capture the widest margin pools through premium digital configurations and subscription software attach rates.
- Portable:Battery-powered digital systems with integrated waveform displays dominate bridge inspection contracts across Germany and the United States. Federal highway administration mandates in both countries drive recurring procurement cycles for field-deployable units that withstand construction site conditions.
- Desktop:Stationary precision instruments serve research institutions and calibration laboratories requiring ASTM C597 reference block protocols. German Federal Institute for Research on Building protocols specify desktop units for official compliance documentation.
- Handheld:Compact single-probe devices target rapid screening applications where full waveform recording is unnecessary.
- Fixed:Permanently installed monitoring arrays embed within critical infrastructure for continuous structural health tracking.
Portable holds installed capacity. Desktop is rotating up the share rankings through laboratory accreditation requirements.
Technology:
Digital signal processing depth now separates price tiers more than transducer hardware quality.
- Digital:Microprocessor-controlled units with automated transit time calculation and cloud connectivity integration command premium positioning. United States infrastructure contractors prioritize digital platforms for seamless data handoff to asset management systems.
- Wireless:Bluetooth and cellular-enabled field units transmit real-time measurements to central monitoring dashboards. Site-wide IoT infrastructure on German megaprojects is accelerating wireless configuration demand fastest.
- Analog:Oscilloscope-dependent systems retain price-accessible positioning for mid-tier contractors with limited software budgets.
- Hybrid:Dual-mode units switch between manual interpretation and automated processing based on inspection complexity.
Digital commands the revenue base. Wireless is climbing the fastest as connectivity standards mature.
End User:
Contractor procurement cycles concentrate volume, while institutional buyers anchor specification standards.
- Construction:General contractors and specialty concrete firms deploy portable units for quality assurance during pour and cure cycles. German construction sector procurement follows EN 12504-4 compliance mandates for commercial building handover documentation.
- Civil Engineering:Bridge, tunnel, and dam assessment specialists require multi-frequency capability for varying member thicknesses. United States state transportation departments specify civil engineering-grade equipment for National Bridge Inventory submissions.
- Material Testing:Independent laboratories perform third-party verification for litigation support and insurance claims.
- Research Institutions:Universities and national laboratories develop next-generation correlation algorithms between pulse velocity and compressive strength.
Construction holds installed capacity. Civil Engineering is rotating up the share rankings through infrastructure rehabilitation program expansion.
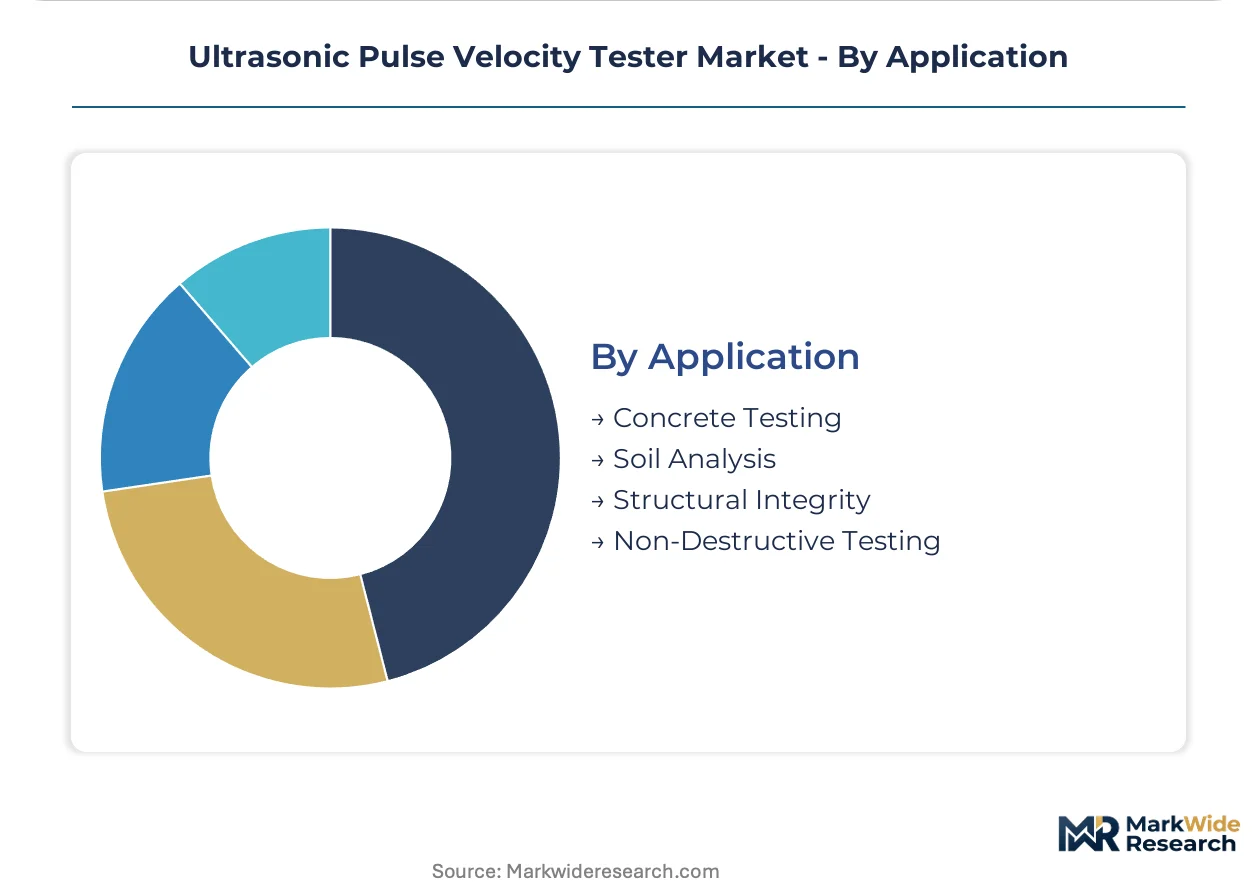
Application:
Concrete assessment generates recurring demand, while emerging applications create technology pull-through.
- Concrete Testing:Compressive strength estimation and uniformity mapping constitute the core use case across all geographies. ASTM C597 and EN 12504-4 standardization ensures equipment interoperability for cross-border infrastructure projects.
- Structural Integrity:Crack depth measurement and delamination detection support rehabilitation prioritization for aging post-war infrastructure in the United States and Germany.
- Non-Destructive Testing:General NDT service providers apply ultrasonic pulse velocity across multiple material classes beyond concrete.
- Soil Analysis:Geotechnical applications measure compaction and layer delineation in earthworks and embankment construction.
Concrete Testing holds installed capacity. Structural Integrity is rotating up the share rankings through bridge condition assessment mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment deployment patterns diverge sharply across geographies, with federal mandates driving standardized procurement in Western economies while emerging markets prioritize cost-accessible analog configurations for contractor-led quality assurance programs.
United States
Bridge rehabilitation contracts dominate equipment demand as state transportation departments manage over 600,000 federally inventoried structures. The Federal Highway Administration mandates National Bridge Inventory condition assessments every 24 months, creating recurring procurement cycles. Texas and California transportation departments anchor the largest state-level equipment deployments.
Germany
Federal highway administration protocols require EN 12504-4 compliant testing for commercial building handover documentation and periodic bridge assessment. The Federal Institute for Research on Building, Urban Affairs and Spatial Development specifies desktop units for official compliance certification. Bavaria and North Rhine-Westphalia concentrate civil engineering contractor activity.
China
High-speed rail expansion and urban subway construction generate demand for rapid concrete quality verification during pour cycles. GB standards for non-destructive testing provide national methodology reference. Yangtze River Delta infrastructure clusters in Shanghai and Jiangsu province deploy portable units across megaproject sites.
India
Smart Cities Mission urban infrastructure monitoring creates first-mover positioning for digital portable suppliers establishing service networks. The Bureau of Indian Standards maintains reference methodologies for concrete strength correlation. Maharashtra and Karnataka state public works departments pilot automated interpretation systems.
Japan
Seismic retrofit programs for aging concrete structures drive precision-focused equipment demand. METI industrial standards guide non-destructive testing protocol adoption. Kanto region engineering firms concentrate high-frequency transducer applications for dense aggregate composition analysis.
Ultrasonic Pulse Velocity Tester Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with premium digital platform providers commanding recurring software attach rates while mid-tier analog specialists compete on capital accessibility. The market structure reflects equipment longevity patterns that sustain legacy installed bases alongside connectivity-driven upgrade cycles. Two strategic archetypes dominate: Swiss-engineered precision instrument builders and Italian infrastructure agency relationship holders. Consolidation pressure concentrates on waveform interpretation software assets, while geographic service network expansion determines emerging market penetration.
Among European precision instrument builders, Proceq Group exemplifies the premium digital platform archetype through its Swiss engineering heritage positioning. Controls S.p.A. occupies a parallel tier, anchoring Southern European demand through deep institutional relationships with Italian infrastructure agencies. James Instruments Inc. represents the price-accessible vector, serving mid-tier contractors with analog system configurations that minimize recurring software commitments.
| Leading Market Players |
|---|
| Proceq Group |
| Controls S.p.A. |
| Roop Telsonic Ultrasonix |
| Stanlay |
| Canopus Instruments |
| James Instruments Inc. |
| Aimil Ltd. |
| Humboldt Mfg. Co. |
| Impact Test Equipment Ltd. |
| Others |
Value Chain & Pricing Dynamics
ASTM C597 and EN 12504-4 certification regimes simultaneously gate supply-side qualification and stratify price tiers across the ultrasonic pulse velocity tester market, compressing margins for non-compliant manufacturers while enabling premium capture by accredited precision instrument builders.
Pricing Analysis
Long-term service contracts with bundled calibration and software updates dominate municipal infrastructure agency procurement, displacing transactional equipment purchases. Three-tier pricing structure across premium digital platforms, standard portable units, and economy analog configurations reflects certification grade and waveform interpretation depth. Pricing pressure stems from mid-tier contractor budget constraints favoring analog systems with minimal recurring commitments. State transportation departments exhibit lowest price sensitivity due to federal mandate compliance requirements, while independent testing laboratories face acute cost compression.
Supply Chain Analysis
Inbound logistics costs from Japanese and German ceramic manufacturing clusters constrain piezoelectric transducer availability, with container capacity on Asia-Europe trade lanes creating intermittent supply bottlenecks. Specialty ceramic formulation draws from Japan, Germany, and select Chinese producers for critical sensor components. Single-source vulnerability concentrates in high-frequency transducer substrates. Distribution runs through authorized service networks for calibration-dependent digital platforms, supplemented by direct OEM relationships for analog system volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States state transportation departments and German federal infrastructure agencies, with procurement consolidation toward multi-year framework agreements reshaping vendor access and pricing leverage.
For Market Incumbents: Shield installed base relationships through backward integration into transducer ceramic production, mitigating Japanese supply concentration risk. Deepen certification investment in India's Smart Cities Mission pilot programs ahead of specification lock-in. Prioritize cloud-based waveform analytics R&D to differentiate against emerging AI-augmented entrants. For New Entrants and Emerging Players: Lead with wireless-enabled portable units targeting India's urban infrastructure monitoring protocols where service network gaps persist. Penetrate mid-tier contractor segments in Southern Europe through price-accessible hybrid configurations. Deploy equipment-as-a-service leasing models to bypass municipal capital budget constraints. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-centric digital platforms as recurring revenue models displace hardware-heavy analog production. Long-term viability favors waveform interpretation algorithm assets over transducer manufacturing. Target acquisition archetype: specialist firms with machine learning crack classification capabilities. Signal to watch: ASNT Level II certification pipeline expansion as technician scarcity inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Based Waveform Analytics Development | Machine learning pattern recognition for crack classification differentiates Proceq Group's premium digital offerings. |
| Equipment-as-a-Service Leasing Expansion | Multi-year contracts with bundled calibration penetrate United States state transportation department capital constraints. |
| Wireless Connectivity Integration | Bluetooth and cellular-enabled units align with German megaproject IoT infrastructure standards. |
| REACH-Compliant Ceramic Formulation Transition | Lead-free piezoelectric materials maintain CE marking eligibility for European market access. |
| India Service Network Establishment | First-mover positioning in Maharashtra and Karnataka state public works department pilot programs. |
Study Parameters
A standing panel of civil engineering contractors, state transportation department equipment procurement officers, non-destructive testing laboratory directors, and piezoelectric transducer manufacturing engineers provided ongoing calibration against field deployment realities. Primary interview insights triangulated with ASTM International standards documentation, Federal Highway Administration bridge inventory databases, EN 12504-4 compliance registries, and German Federal Institute for Research on Building technical protocols. Bottom-up equipment shipment analysis converged with top-down infrastructure rehabilitation budget allocations.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for ceramic sensor components and capital expenditure disclosures from major infrastructure agencies. Segmentation modeling spanned product configuration, signal processing technology, end-user industry vertical, and application type across the projection horizon. CAGRs derived from equipment replacement cycle analysis, mandate-driven procurement frequency, and connectivity upgrade adoption curves. Forecast inputs incorporated bridge condition assessment protocol expansion and technician certification pipeline constraints.
The analysis sits within stated boundaries; outcomes outside sustained federal infrastructure rehabilitation funding levels or accelerated REACH substance restriction timelines would require recalibration. Forecasts reflect documented assumptions regarding wireless connectivity standard maturation and AI-augmented interpretation adoption rates. Specific risk factors including piezoelectric ceramic supply disruption and aggregate variability in field concrete composition could revise equipment utilization and replacement projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Stress Test Equipment Market
Test and Measurement
Calibration Management Software Market
Test and Measurement
Ceramic Tester Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
ESG Sensor Data Quality and Validation Test Platforms Market
Test and Measurement
Cooling Laser Power Measurement Sphere Market
Test and Measurement
Test and Measurement Equipment Market
Test and Measurement
Calibration Solutions Market
Test and Measurement
Digital Oscilloscope Market
Test and Measurement
Automated Optical Inspection (AOI) Equipment Market
Test and Measurement
Fiber Optic Test Equipment (FOTE) Market
Test and Measurement
AI Inference Hardware Performance Benchmarking Test Systems Market
Test and Measurement
Global General Purpose Test Equipment (GPTE) Market
Test and Measurement
Cell Balancing Algorithm Hardware-in-the-Loop Test Platforms Market
Test and Measurement
Ultrasonic Wall Thickness Gauges Market
Test and Measurement
Impact Testing Machine Market