
 Global Error Monitoring Software Market | 2026-2036
Global Error Monitoring Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Error Monitoring Software Market Foresight
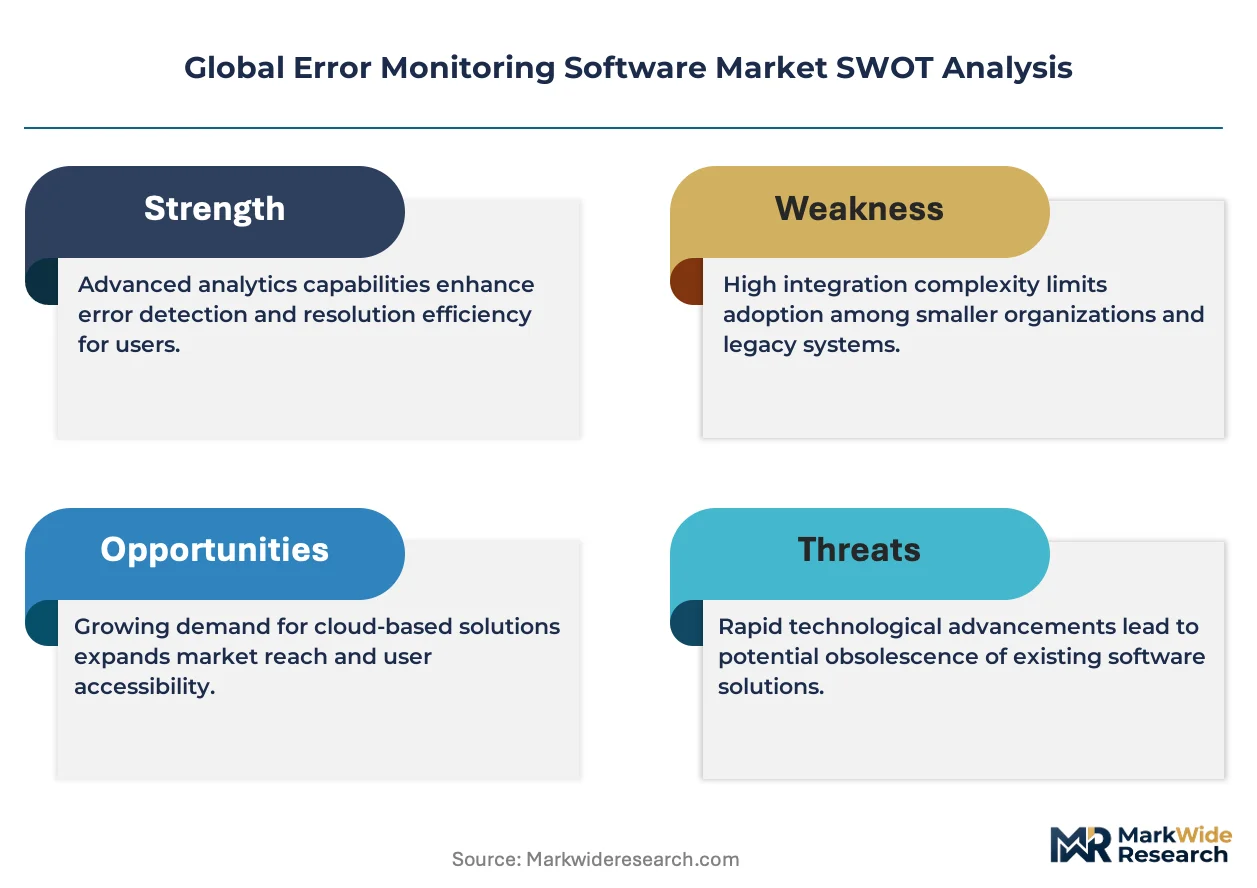
Subscription-based pricing for real-time alerting and root cause analysis is shifting how vendors package error monitoring capabilities. Datadog leverages its cloud observability platform to anchor enterprise accounts across multiple infrastructure layers. Sentry competes through open-source community engagement that sustains developer-centric adoption curves. Dynatrace differentiates via AI-assisted transaction tracing that positions its suite for complex hybrid environments.
Error monitoring software comprises code instrumentation agents, log aggregation pipelines, and exception tracking dashboards that capture runtime failures across distributed systems with millisecond-level timestamp precision. Its primary commercial purpose centers on minimizing mean time to resolution for production incidents that degrade user experience or trigger service-level agreement penalties. Cloud-based deployment leads segment economics due to elastic scaling aligned with microservices architectures, while root cause analysis commands premium pricing as organizations prioritize automated incident intelligence over basic alerting. API monitoring represents the fastest-growing use case as financial services and telecommunications firms harden interconnect reliability between partner systems.
The EU AI Act and GDPR impose algorithmic accountability and data residency requirements that shape product roadmaps for vendors serving European enterprises. The SEC's cybersecurity disclosure rules and HIPAA breach notification standards in the United States mandate documented incident response workflows that elevate error monitoring from operational convenience to compliance infrastructure. Stakeholders must weigh vendor concentration against the interoperability demands of multi-cloud strategies as procurement teams consolidate observability spending.
Market Dynamics
Microservices architecture proliferation is fragmenting application runtime environments, forcing error monitoring vendors to reconstruct distributed traces across container orchestration layers that traditional monolithic debugging tools cannot traverse.
Growth Catalysts
- GDPR Article 33:Mandatory breach notification timelines in Europe are converting error logs into compliance artifacts that require immutable audit trails and automated classification pipelines.
- Telecommunications API hardening:5G network slicing and edge computing deployments are mandating sub-second failure detection across multi-vendor interoperability zones.
- OpenTelemetry standardization:Vendor-neutral instrumentation protocols are collapsing proprietary agent lock-in and accelerating multi-tool observability stack adoption.
Market Restraints
- Cloud egress cost volatility:Log shipping fees from hyperscale providers are compressing gross margins for vendors operating centralized aggregation architectures.
- EU AI Act algorithmic accountability:Automated root cause classification systems face documentation burdens that slow feature release cycles and inflate compliance overhead.
- Substitute in-house tooling:Large technology firms are building captive error monitoring layers atop internal data platforms, displacing commercial procurement for core engineering teams.
Strategic Opportunities
- Brazilian financial modernization:PIX instant payment infrastructure expansion is generating demand for real-time transaction failure tracking among regional banks and fintechs.
- Edge-ML convergence:On-device inference error capture is opening deployment models that process telemetry locally before selective cloud synchronization.
- SEC cybersecurity disclosure mandates:Material incident reporting requirements are elevating error monitoring to board-level procurement priority with accelerated budget allocation.
Industry Challenges
- Distributed systems expertise scarcity:Site reliability engineering talent pools remain shallow relative to deployment complexity, elongating implementation timelines and inflating professional services dependency.
- Legacy monolith integration friction:Mainframe and COBOL environments resist standard instrumentation agents, forcing custom bridge development that fragments product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Error Monitoring Software Market |
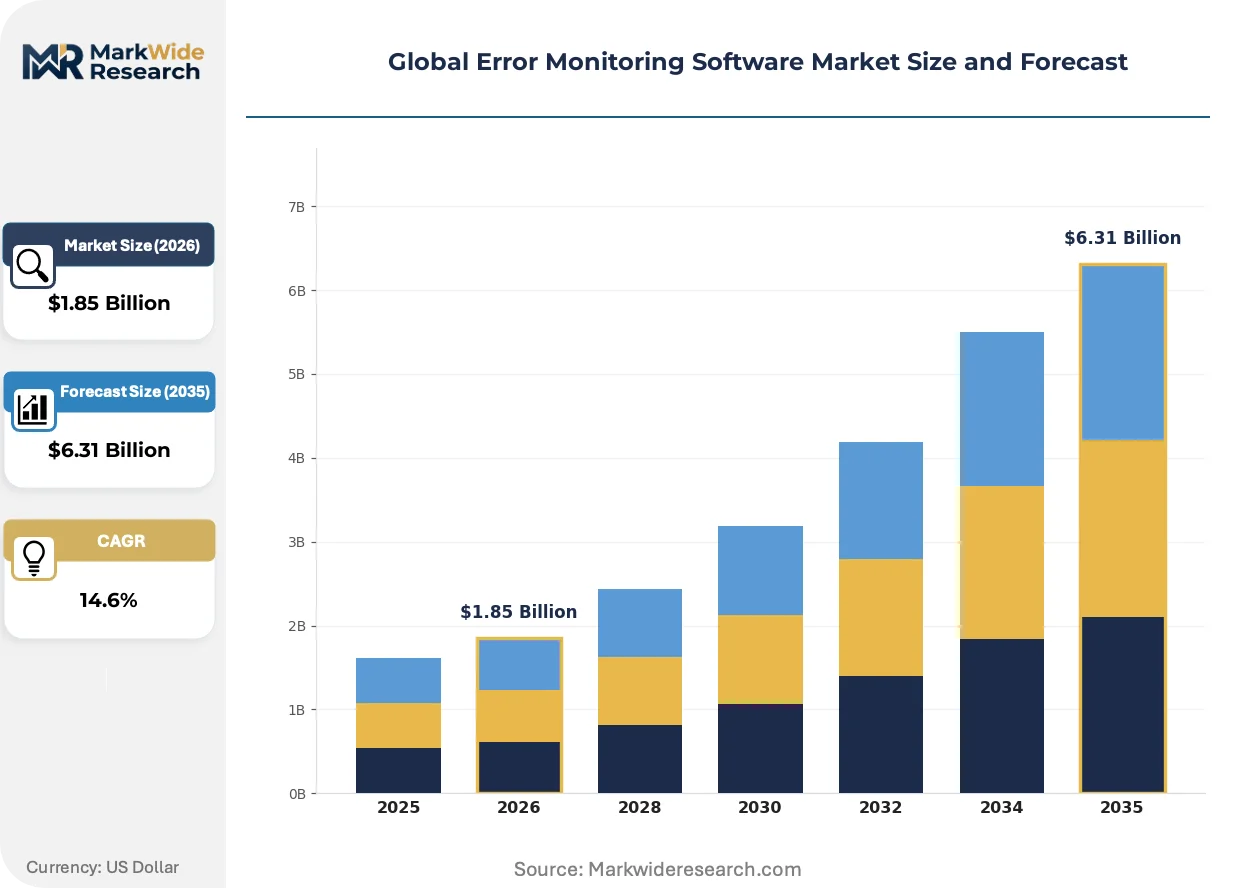
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.31 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Solution Offering: Real-Time Alerting, Root Cause Analysis, Log Management, Performance Monitoring, Transaction Tracing Use Case: Web Applications, Mobile Applications, Enterprise Software, Gaming Platforms, API Monitoring End User Industry: Banking & Finance, Telecommunications, E-commerce, Media & Entertainment, Education |
| Companies Covered | Datadog, Sentry, Dynatrace, AppDynamics, Raygun, Rollbar, Bugsnag, Honeybadger, Airbrake, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Error Monitoring Software Market Shifts & Advancements
Telemetry pipeline architectures are converging with security operations workflows, collapsing the historical separation between application performance management and threat detection infrastructure.
eBPF kernel instrumentation is integrating runtime security telemetry with error capture at the operating system layer. Financial services firms in Singapore and Switzerland are piloting unified pipelines that eliminate redundant agent overhead. This convergence is integrating previously siloed observability budgets into consolidated security-operations procurement.
The EU AI Act risk classification framework is mandating explainability logs for high-risk automated decision systems. Healthcare and credit-scoring deployments in Germany and France must now retain error traces that reconstruct model inference pathways. Medical device manufacturers are responding by embedding audit-ready exception handlers that preempt regulatory scrutiny.
Consumption-based pricing for telemetry volume is displacing seat-based subscription models among mid-market SaaS vendors. Engineering leadership at Series B software firms is negotiating event-per-dollar contracts that align vendor compensation with actual debugging utility. This reconfiguration is most visible in the United States, where venture-backed companies prioritize variable cost structures over fixed operational expenditures.
Global Error Monitoring Software Market Segmentation
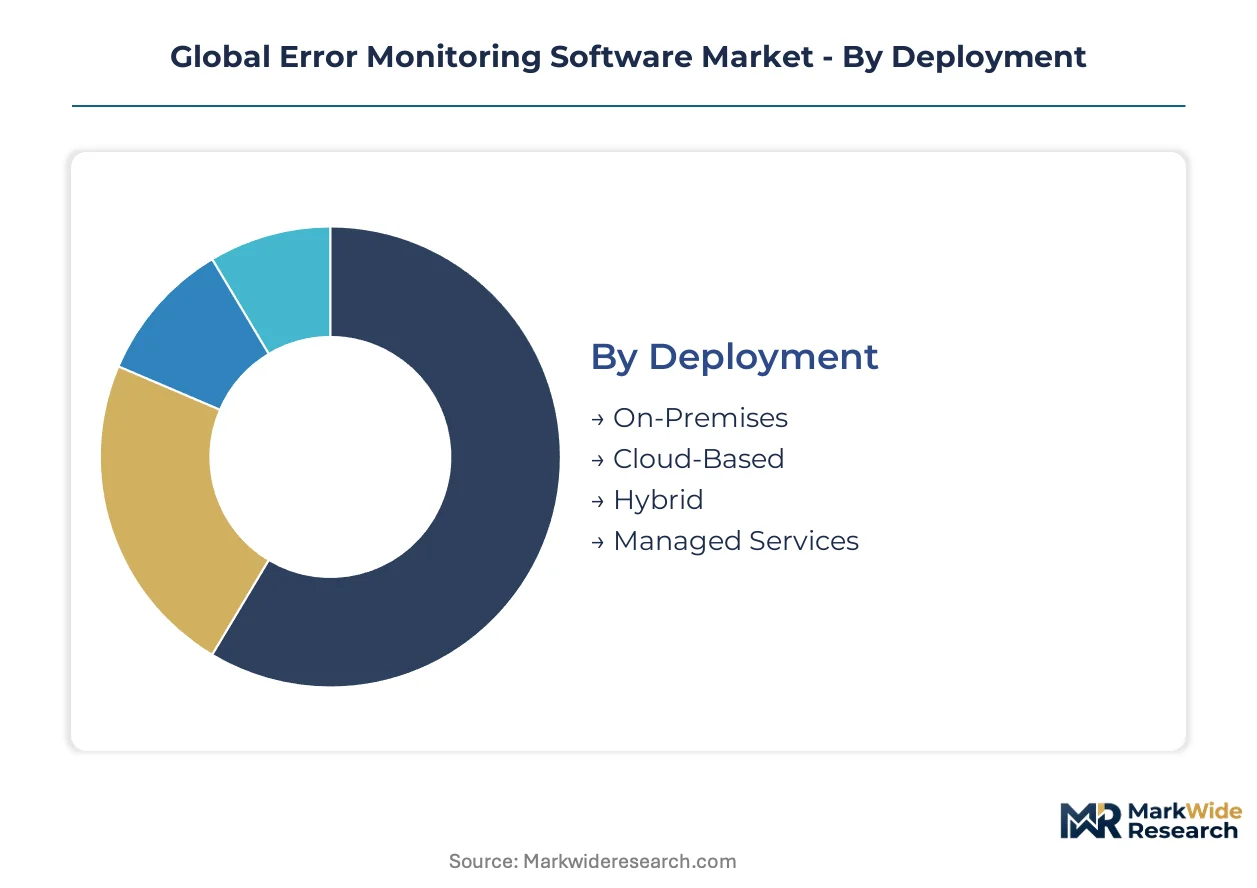
Error monitoring software vendors architect product portfolios around deployment flexibility, solution depth, and vertical specialization. Procurement teams evaluate segments against internal DevOps maturity and compliance exposure rather than feature checklists alone.
Deployment:
Customization intensity varies sharply across this spectrum, with fully managed offerings minimizing engineering overhead while self-hosted deployments maximize data sovereignty control.
- Cloud-Based:Elastic compute architectures enable millisecond-scale log ingestion without capacity planning. Financial services firms in Singapore and Germany favor this model for GDPR-aligned data residency through regional cloud zones.
- On-Premises:Air-gapped installations process telemetry within sovereign infrastructure boundaries. Defense contractors and national healthcare systems in France mandate this deployment for classified or patient-critical workloads.
- Hybrid:Federated architectures route sensitive traces locally while pushing aggregated metrics to cloud control planes. Manufacturing conglomerates with legacy SCADA dependencies adopt this bridging configuration.
- Managed Services:Fully outsourced observability stacks include 24/7 incident response staffing. Mid-market SaaS vendors without site reliability engineering benches purchase operational relief through this tier.
Leading the category by volume: Cloud-Based. Growing fastest: Managed Services.
Solution Offering:
Margin compression concentrates at the alerting layer while automated intelligence commands pricing power.
- Root Cause Analysis:Machine learning pipelines correlate distributed trace fragments to identify failure propagation paths. Telecommunications operators in South Korea deploy these systems for 5G network slice diagnostics.
- Real-Time Alerting:PagerDuty-style notification routing with escalation policies and on-call rotation management. E-commerce platforms during peak shopping windows depend on sub-minute detection thresholds.
- Log Management:Centralized ingestion, indexing, and search across structured and unstructured telemetry streams. Healthcare IT departments retain audit-ready records for HIPAA breach investigations.
- Performance Monitoring:Latency percentile tracking and throughput baselining for user-facing endpoints. Gaming studios monitor frame-rate degradation across console and PC hardware configurations.
- Transaction Tracing:End-to-end request flow reconstruction across microservice boundaries. Payment processors trace PIX instant settlement failures through Brazilian banking infrastructure.
Highest margin capture: Root Cause Analysis. Steepest expansion trajectory: Transaction Tracing.
Use Case:
Application runtime diversity forces instrumentation agent specialization.
- API Monitoring:Inter-service contract validation and latency SLAs for partner ecosystem reliability. Open banking mandates in the United Kingdom require this coverage for third-party fintech integrations.
- Mobile Applications:Crash reporting across iOS and Android with device-specific reproduction environments. Consumer banking apps in India track UPI payment failures on fragmented Android hardware.
- Web Applications:Browser-side JavaScript error capture with user session replay. Media streaming services diagnose playback failures across CDN edge populations.
- Enterprise Software:SAP and Salesforce plugin exception tracking within customized workflow deployments. Manufacturing ERP integrations generate specialized demand in Germany's industrial sector.
- Gaming Platforms:Unity and Unreal engine crash analytics with GPU telemetry correlation. Esports tournament operators require frame-precise stability monitoring.
Deepest penetration: Web Applications. Gaining share fastest: API Monitoring.
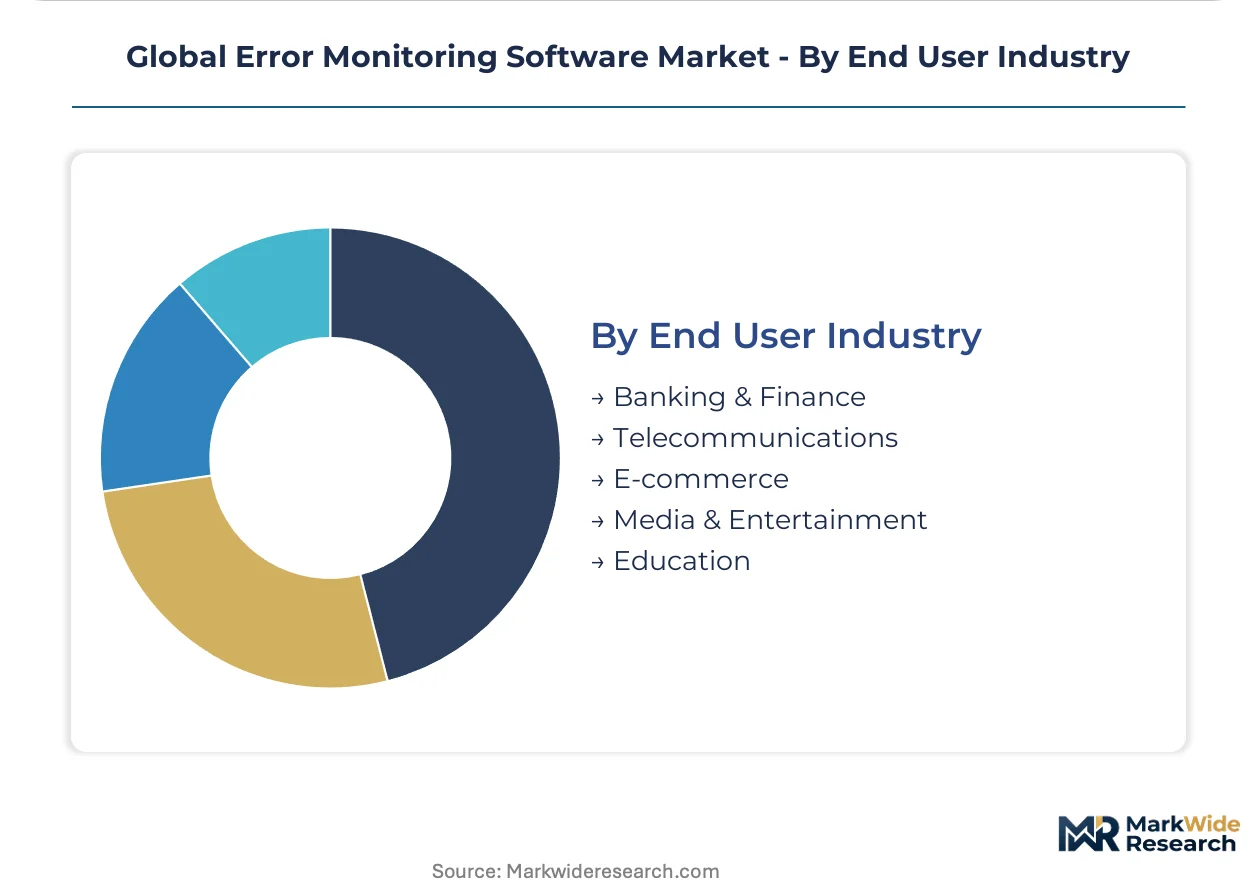
End User Industry:
Compliance burden intensity separates pricing tiers across verticals.
- Banking & Finance:SEC cybersecurity disclosure mandates and PCI-DSS audit trails elevate procurement to board-level priority. Real-time transaction failure tracking supports instant payment infrastructure reliability.
- Telecommunications:5G network slicing and edge computing deployments require sub-second failure detection across multi-vendor interoperability zones.
- E-commerce:Seasonal traffic spikes demand elastic observability scaling with checkout funnel monitoring. Cart abandonment attribution depends on frontend error correlation.
- Media & Entertainment:Live streaming quality-of-experience metrics with subscriber churn prediction. Ad insertion failure tracking protects programmatic revenue.
- Education:Learning management system uptime during high-stakes examination windows. Student data privacy constraints shape deployment architecture choices.
Largest current spend: Banking & Finance. Fastest budget acceleration: Telecommunications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering talent concentrates in the United States while compliance-driven procurement accelerates across European banking hubs. Consumption patterns diverge sharply between cloud-native SaaS corridors and regulated financial centers requiring sovereign data controls.
United States
SaaS infrastructure density and DevOps maturity outpace other national markets, with San Francisco Bay Area and Seattle tech corridors driving real-time alerting adoption. SEC cybersecurity disclosure rules mandate documented incident response workflows that elevate error monitoring to compliance infrastructure. New York financial services firms anchor demand for transaction tracing across instant payment networks.
Germany
Industrial manufacturing ERP integrations generate specialized demand for legacy system error tracking. GDPR Article 33 breach notification timelines convert error logs into compliance artifacts requiring immutable audit trails. Bavaria's automotive software clusters and Frankfurt banking infrastructure pilot AI-assisted root cause analysis for connected vehicle systems.
Singapore
Financial services firms pilot unified telemetry pipelines that integrate runtime security with error capture. Monetary Authority of Singapore operational resilience guidelines mandate sub-second failure detection for payment infrastructure. The city-state's wealth management technology hubs drive managed services procurement among mid-market fintechs lacking site reliability engineering benches.
Brazil
PIX instant payment infrastructure expansion generates demand for real-time transaction failure tracking among regional banks and fintechs. Central Bank of Brazil instant payment regulations require traceable error documentation for settlement disputes. São Paulo's fintech corridor anchors adoption curves as legacy institutions modernize core banking systems.
South Korea
Telecommunications operators deploy distributed trace systems for 5G network slice diagnostics across multi-vendor interoperability zones. Personal Information Protection Act amendments shape data residency requirements for cloud-based error aggregation. Seoul's cloud gaming studios and Busan smart port initiatives drive edge-computing error capture pilots.
Global Error Monitoring Software Market Competitive Landscape
Top-tier vendors anchor enterprise observability platforms, while developer-centric challengers compete through open-source community engagement. The vendor base stratifies across cloud-native incumbents with multi-layer infrastructure coverage, specialized error-tracking pure-plays, and emerging edge-ML telemetry providers. Strategic differentiation concentrates on AI-assisted transaction tracing, consumption-based pricing models, and compliance-ready audit architectures. Consolidation pressure intensifies as procurement teams seek to collapse redundant observability spending into unified security-operations procurement.
Within the cloud observability tier, Datadog leverages its platform breadth to anchor enterprise accounts, while Dynatrace occupies a position emphasizing AI-assisted diagnostics for hybrid environments. Sentry exemplifies the developer-centric archetype through sustained open-source community engagement that sustains adoption curves among engineering-native buyers. These three vendors represent contrasting strategic postures: infrastructure consolidation, automated intelligence, and bottom-up developer adoption.
| Leading Market Players |
|---|
| Datadog |
| Sentry |
| Dynatrace |
| AppDynamics |
| Raygun |
| Rollbar |
| Bugsnag |
| Honeybadger |
| Airbrake |
| Others |
Supply & Pricing Matrix
Enterprise SaaS procurement teams concentrated in United States financial services and technology corridors anchor pricing power toward consumption-based telemetry models that align vendor compensation with actual debugging utility rather than fixed seat licenses.
Pricing Analysis
Margin tightening in mid-market SaaS tiers reflects the displacement of seat-based subscriptions by event-per-dollar contracts that engineering leadership at venture-backed firms negotiate to prioritize variable cost structures. Three-tier pricing structure across premium, standard, and economy levels separates AI-assisted root cause analysis bundles from basic alerting and log management entry points. Price differentiation hinges on compliance-ready audit architectures and automated incident intelligence depth. Cloud egress cost volatility from hyperscale providers intensifies pricing pressure on vendors operating centralized aggregation architectures. Series B software firms exhibit highest price sensitivity; banking and finance verticals demonstrate lowest sensitivity due to SEC cybersecurity disclosure mandates.
Supply Chain Analysis
Regional distribution centers in Ireland, Singapore, and Virginia anchor hub-and-spoke patterns for GDPR-aligned data residency and sub-second latency delivery to financial services hubs. Software engineering talent concentration draws from the United States, Germany, and India. Cloud infrastructure dependencies rest on hyperscale compute and storage services from AWS, Azure, and Google Cloud. Single-source vulnerability in proprietary instrumentation agent architectures poses structural risk as OpenTelemetry standardization collapses vendor lock-in. Distribution runs through direct enterprise sales with managed services overlays and developer-centric self-serve channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into upstream AI model training pipelines and downstream security operations workflows is accelerating as vendors seek to collapse redundant observability spending into consolidated procurement.
For Market Incumbents: To counter open-source community erosion from OpenTelemetry standardization, anchor enterprise accounts through backward integration into cloud infrastructure layers and deepen certification investment for EU AI Act algorithmic accountability documentation. For New Entrants and Emerging Players: The premium-to-economy pricing gap in Brazilian fintech corridors and Southeast Asian mid-market SaaS vendors creates white-space entry through edge-ML telemetry pilots and consumption-based pricing disruption. For Investors and Strategic Acquirers: The window for entry favors vertically integrated observability platforms with security-operations convergence capabilities; signal inflection through regulatory procurement acceleration in telecommunications and healthcare verticals.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified telemetry pipelines collapse observability and security budgets into consolidated procurement at Singapore financial services firms. |
| Acquisition of Specialist Firm | Edge-ML telemetry providers extend capture capabilities to on-device inference error processing before selective cloud synchronization. |
| Strategic Partnership | Hyperscaler alliances mitigate cloud egress cost volatility compressing gross margins for centralized aggregation architectures. |
| Geographic Expansion | PIX instant payment infrastructure modernization in São Paulo generates demand for real-time transaction failure tracking. |
| Product Launch | Explainability logs for high-risk automated decision systems preempt EU AI Act regulatory scrutiny in German healthcare deployments. |
Research Methodology
Document review covered SEC cybersecurity disclosure filings, hyperscaler capex disclosures, and EU regulatory frameworks, complemented by interviews with platform engineers, IT procurement officers, DevOps directors, and integration specialists. Secondary validation drew from OpenTelemetry consortium documentation, GDPR Article 33 implementation guidance, and cloud infrastructure spending reports. Bottom-up telemetry volume modeling and top-down enterprise software spending analysis enabled triangulation.
Segmentation outputs across deployment models, organization size tiers, vertical compliance exposure, and regional adoption patterns were generated over the projection horizon. CAGRs derived from elastic scaling coefficients in microservices environments and regulatory procurement acceleration curves. AI-assisted diagnostics penetration and consumption-based pricing migration served as industry-specific forecast inputs.
Inputs from hyperscaler infrastructure disclosures and EU regulatory consultations were available through the study window; gaps in private fintech procurement data introduce uncertainty bands around emerging market estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Software Assurance Market
Security Software
Global Security Assertion Markup Language (SAML) Authentication Market
Security Software
US Hardware OTP Token Authentication Market
Security Software
Anomaly Detection Market
Security Software
Mobile Identity Management Market
Security Software
Secure Email Gateway Market
Security Software
SSL Inspection Solution Market
Security Software
Global Runtime Application Self-Protection Market
Security Software
Europe User Provisioning Market
Security Software
Global User Activity Monitoring Market
Security Software
Global Cloud IAM Market
Security Software
IAM Security Services Market
Security Software
Security Information and Event Management Software Market
Security Software
United States Consumer Identity and Access Management Market
Security Software
Mobile Data Protection Solutions and Services Market
Security Software
Global Electronic Passports Market