
 UAE Ecommerce Market | 2026-2036
UAE Ecommerce Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Ecommerce Market Insights
Dubai is reconfiguring Gulf digital commerce infrastructure through dedicated e-commerce free zones and bonded warehousing capacity. Noon AD Holdings Ltd leverages localized fulfillment networks to compete with cross-border incumbents. Amazon.ae anchors its position through Prime subscription penetration and same-day delivery coverage across the emirates. Namshi General Trading LLC specializes in fashion vertical integration, controlling private-label design and regional distribution.
UAE ecommerce denotes digitally mediated retail transactions executed via internet-connected platforms, encompassing web storefronts, mobile applications, and social commerce interfaces with integrated payment gateways and logistics orchestration. The primary commercial purpose centers on disintermediating traditional retail distribution to reduce consumer prices while expanding merchant market access beyond physical geography. Fashion and electronics categories dominate transaction volume, reflecting high-margin, high-velocity inventory turnover suited to digital discovery and comparison shopping. Mobile apps represent the fastest-growing distribution channel, driven by smartphone penetration exceeding regional benchmarks and super-app convergence of payment, browsing, and delivery tracking.
MOHAP regulates product safety standards for health and beauty goods sold online, requiring Arabic labeling and ingredient disclosure that shapes merchant compliance costs. The UAE Central Bank oversees digital wallet licensing and open banking APIs, determining which payment methods platforms can integrate. TRAI-equivalent telecommunications standards govern data localization and cross-border data flows for platform operators. Stakeholders must monitor evolving VAT enforcement on low-value cross-border parcels and the competitive implications of real-time payment settlement mandates.
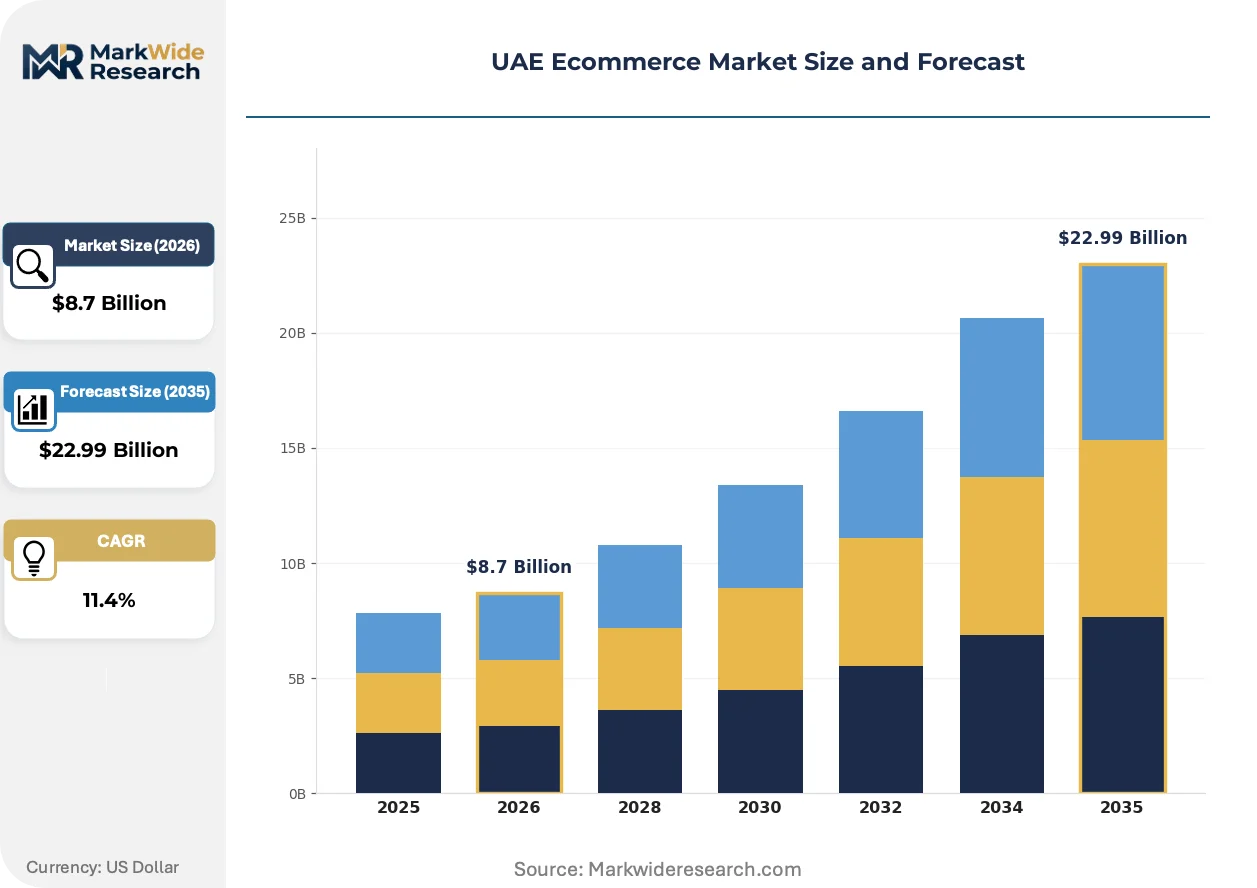
Market Dynamics
UAE ecommerce infrastructure is consolidating around Jebel Ali Free Zone's bonded warehousing capacity and real-time payment settlement rails mandated by the UAE Central Bank's open banking framework.
Growth Catalysts
- MOHAP product safety mandates:Arabic labeling and ingredient disclosure requirements for health and beauty goods are forcing merchant compliance investments that advantage established platforms with dedicated localization teams.
- Smartphone super-app convergence:Mobile applications integrating payment, browsing, and delivery tracking are capturing transaction volume as UAE smartphone penetration exceeds regional benchmarks.
- Jebel Ali logistics corridor:Dedicated e-commerce free zones and last-mile fulfillment centers connecting Dubai's port infrastructure are compressing delivery timelines for cross-border inventory.
Market Restraints
- VAT enforcement friction:Evolving low-value cross-border parcel taxation creates compliance uncertainty for international merchants without UAE-registered entities.
- Data localization requirements:TRAI-equivalent telecommunications standards governing cross-border data flows increase operational complexity for platform operators with centralized global infrastructure.
- Real estate cost concentration:Bonded warehousing capacity in Dubai's logistics corridor commands premium lease rates that structurally favor large-scale incumbents over emerging competitors.
Strategic Opportunities
- Abu Dhabi and Northern Emirates expansion:Same-day delivery coverage gaps outside Dubai present white space for localized fulfillment network investments.
- Grocery vertical penetration:Urban household adoption of scheduled delivery slots for fresh produce and staples remains underpenetrated relative to fashion and electronics categories.
- Digital wallet integration:UAE Central Bank's open banking APIs enable embedded finance products that reduce checkout friction and capture payment float revenue.
Industry Challenges
- Arabic content localization talent:Scarce technical and creative professionals capable of producing compliant product descriptions and customer service interfaces at scale.
- Legacy ERP integration:Mid-market merchants face complex middleware requirements to connect inventory management systems with marketplace APIs and logistics orchestration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Ecommerce Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Fashion, Electronics, Home & Kitchen, Beauty Distribution Channel: Online Marketplaces, Direct Retail, Social Media, Mobile Apps Payment Method: Credit Card, Cash on Delivery, Digital Wallets, Bank Transfer Customer Type: Individuals, Businesses, Government, Non-profits |
| Companies Covered | Noon AD Holdings Ltd, Amazon.ae, Namshi General Trading LLC, Sharaf DG LLC, LetsTango.Com, Carrefour UAE, Ounass.ae, Apple.com, eyewa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Ecommerce Market Trends and Innovations
Platform business models in UAE ecommerce are pivoting from transaction facilitation toward captive logistics and financial services monetization.
Artificial intelligence-powered demand forecasting is migrating from experimental pilot programs to core inventory allocation decisions. Fashion and electronics merchants with high SKU velocity are deploying machine learning models to predict size and color preferences by neighborhood. This capability is migrating from a competitive differentiator to a baseline operational requirement for participation in marketplace buy-box algorithms.
UAE Central Bank's real-time payment settlement mandate is compressing working capital cycles for marketplace sellers. The regulation requires instant fund availability upon transaction confirmation, eliminating traditional settlement delays. Small and medium merchants with thin liquidity buffers are restructuring pricing strategies to account for accelerated cash conversion.
Social commerce interfaces on Instagram and TikTok are capturing discovery-phase consumer attention previously directed toward search-based web storefronts. Influencer-led live shopping events in Dubai and Abu Dhabi are converting browse-to-buy journeys in single sessions. Fashion verticals targeting 18-34 demographics are reallocating marketing spend from search engine placement to content creator partnerships and shoppable video formats.
UAE Ecommerce Market Segmentation
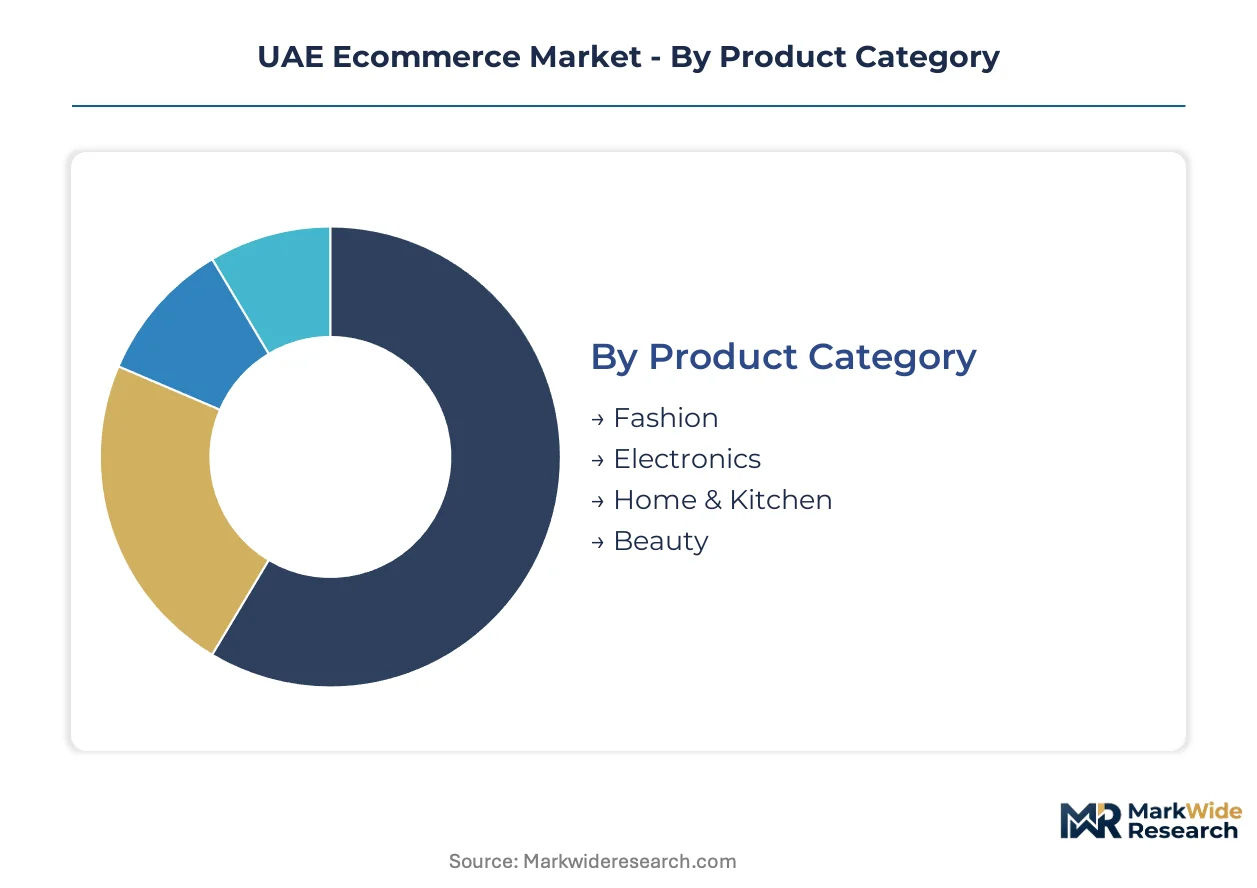
Segmentation in UAE ecommerce reveals how platform operators allocate capital across divergent margin profiles and fulfillment complexity. Each dimension carries distinct regulatory exposure and infrastructure requirements that shape competitive positioning.
Product Category:
Mature categories dominate transaction volume while emerging verticals absorb venture investment and experimental fulfillment models.
- Fashion:High-velocity SKU turnover with size and color fragmentation demanding neighborhood-level demand forecasting. Dubai's style-conscious consumer base drives premium private-label development and same-day return logistics. Jebel Ali bonded warehousing enables cross-border inventory positioning with compressed customs clearance.
- Electronics:Warranty servicing networks and authorized distribution agreements create defensive moats against gray-market competition. MOHAP certification requirements for connected health devices add compliance layers that advantage established retailers with regulatory affairs capacity.
- Home & Kitchen:Bulky freight economics favor marketplace models with consolidated last-mile fleets over direct retail.
- Beauty:Arabic ingredient labeling mandates and temperature-controlled storage requirements constrain merchant entry.
Fashion handles the majority of throughput; Beauty is expanding most quickly on share as localization investments mature.
Distribution Channel:
Channel economics stratify sharply by customer acquisition cost and lifetime value capture mechanisms.
- Online Marketplaces:Aggregated liquidity reduces merchant customer acquisition spend while extracting commission-plus-fulfillment fees. Noon and Amazon.ae compete on Prime-equivalent subscription penetration and delivery speed guarantees across the emirates.
- Mobile Apps:Super-app convergence of payment, browsing, and delivery tracking captures session duration and repeat purchase frequency. UAE smartphone penetration exceeding regional benchmarks accelerates wallet integration and push-notification re-engagement.
- Direct Retail:Brand-controlled experience commands premium pricing but requires standalone logistics investment.
- Social Media:Influencer-led discovery converts browse-to-buy journeys in single sessions for 18-34 demographics.
Online Marketplaces aggregate the deepest liquidity; Mobile Apps are climbing the fastest as super-app functionality matures.
Payment Method:
Payment infrastructure choices determine working capital cycles and fraud exposure profiles for platform operators.
- Digital Wallets:UAE Central Bank open banking APIs enable embedded finance products and real-time settlement that eliminates traditional merchant funding delays. Integration with Emirates ID verification reduces chargeback rates relative to card-not-present transactions.
- Credit Card:Mature fraud scoring and installment plan options sustain relevance for high-ticket purchases despite interchange costs.
- Cash on Delivery:Persistent preference in Northern Emirates and among unbanked segments creates return-rate and logistics cost challenges.
- Bank Transfer:Corporate procurement and B2B transactions favor this channel for invoice reconciliation and VAT documentation.
Credit Card processes the highest transaction values; Digital Wallets are gaining share fastest on the back of regulatory mandates.
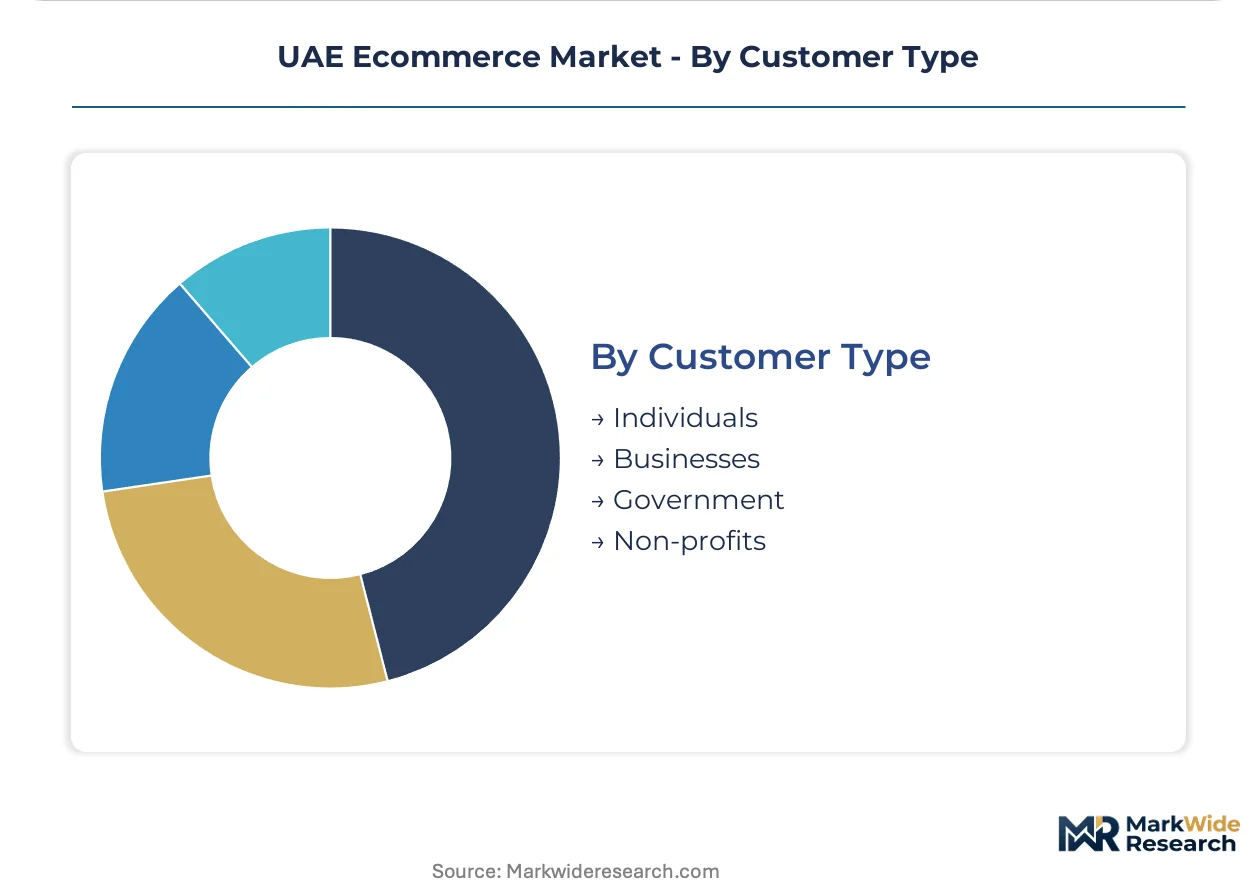
Customer Type:
Customer segmentation reveals divergent procurement authority and platform interface requirements.
- Individuals:Mobile-first discovery behavior and influencer-driven purchase decisions concentrate marketing spend on content creator partnerships. Scheduled delivery slot preferences for grocery and fresh produce remain underpenetrated relative to discretionary categories.
- Businesses:Bulk procurement workflows and multi-user account management require ERP integration and purchase order approval chains.
- Government:Tender compliance and local content requirements favor marketplace operators with UAE-registered entities and Arabic-language support infrastructure.
- Non-profits:Donation transparency and receipt automation shape platform selection criteria.
Individuals generate the highest transaction frequency; Businesses are expanding most quickly as B2B procurement digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MOHAP regulates product safety standards across the UAE's digital commerce corridors, anchoring compliance requirements that shape merchant entry costs and platform operational frameworks throughout the federation.
Dubai
Jebel Ali Free Zone's bonded warehousing capacity compresses customs clearance timelines for cross-border inventory. The Dubai Department of Economic Development licenses e-commerce free zones that exempt operators from certain foreign ownership restrictions. Last-mile fulfillment centers connecting the port infrastructure to urban residential clusters enable same-day delivery guarantees across the emirate.
Abu Dhabi
Corporate and government procurement digitization drives B2B marketplace penetration in the capital emirate. The Abu Dhabi Department of Economic Development oversees commercial licensing for digital platforms serving public sector tender processes. Yas Island and Al Maryah Island commercial districts concentrate headquarters operations for platforms targeting institutional buyers.
Sharjah
Price-sensitive consumer segments in the emirate sustain cash-on-delivery preference patterns above Dubai benchmarks. The Sharjah Economic Development Department regulates commercial permits for warehouse operations supporting Northern Emirates distribution. Industrial zones near Sharjah International Airport host cross-border fulfillment facilities serving lower-cost inventory positioning.
Northern Emirates
Ras Al Khaimah and Fujairah present coverage gaps for same-day delivery networks that incumbent platforms have not fully addressed. Local economic development authorities in each emirate issue commercial licenses under federal framework harmonization. Port infrastructure at Saqr and Khor Fakkan enables alternative entry routes reducing Jebel Ali congestion exposure.
UAE Ecommerce Market Competitive Landscape
Global marketplace operators and regional specialists split the market along fulfillment speed and product category dimensions. Consolidation pressure favors platforms with captive logistics networks and localized warehousing capacity. Three archetypes dominate: vertically integrated retailers controlling private-label design, marketplace aggregators monetizing third-party seller liquidity, and vertical specialists dominating single-category discovery. Competitive dynamics center on subscription program penetration and bonded warehousing lease commitments.
Within the regional specialist tier, Noon AD Holdings Ltd and Namshi General Trading LLC occupy positions anchored in localized fulfillment infrastructure and fashion vertical integration respectively. Amazon.ae exemplifies the global marketplace archetype through Prime-equivalent subscription mechanics and cross-emirate delivery coverage. Sharaf DG LLC represents electronics category concentration with warranty servicing networks that create defensive positioning against gray-market alternatives.
| Leading Market Players |
|---|
| Noon AD Holdings Ltd |
| Amazon.ae |
| Namshi General Trading LLC |
| Sharaf DG LLC |
| LetsTango.Com |
| Carrefour UAE |
| Ounass.ae |
| Apple.com |
| eyewa |
| Others |
Pricing and Supply Chain Analysis
Jebel Ali Free Zone's bonded warehousing capacity concentrates supply-side leverage among operators with long-term lease commitments, compressing customs clearance timelines while creating tiered fulfillment cost structures that propagate through final-mile delivery pricing. Premium same-day coverage commands substantial markups over standard multi-day slots, with cost differentiation widening between Dubai's logistics corridor and Northern Emirates distribution nodes.
Pricing Analysis
Geographic price spreads between Dubai's same-day delivery zones and Northern Emirates standard coverage run 25-40 percent for identical SKUs, reflecting bonded warehousing proximity and last-mile fleet density. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery speed guarantee and return logistics inclusion, with fashion and electronics merchants absorbing higher fulfillment fees to maintain buy-box visibility. Pricing pressure stems from real-time payment settlement mandates compressing merchant working capital cycles, forcing liquidity-constrained sellers toward thinner gross margins. Individual consumers demonstrate highest price sensitivity on delivery fees, while corporate procurement buyers prioritize invoice automation and multi-user account management over unit cost minimization.
Supply Chain Analysis
Tariff exposure between China and the UAE dominates supply chain risk calculus for electronics and fashion merchants dependent on Shenzhen and Guangzhou manufacturing clusters. Inventory positioning draws from China, India, and Turkey for apparel; China, South Korea, and Vietnam for consumer electronics; with Jebel Ali bonded warehousing enabling duty-deferred staging. Single-source vulnerability concentrates in semiconductor components and specialized packaging materials, where alternative supplier qualification timelines exceed seasonal demand windows. Distribution runs through marketplace-operated fulfillment centers for third-party sellers, direct-to-consumer fleets for vertical specialists, and hybrid models combining captive warehousing with outsourced last-mile.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from social commerce interfaces capturing discovery-phase consumer attention previously directed toward search-based storefronts, requiring defensive repositioning around fulfillment speed and subscription retention mechanics.
For Market Incumbents: Build captive logistics moats through dedicated last-mile fleet expansion into Northern Emirates coverage gaps, insulating Prime-equivalent subscription value propositions against emerging platform entrants. Deepen backward integration into Jebel Ali bonded warehousing through long-term lease commitments that structurally exclude capital-constrained competitors. Accelerate Arabic content localization capacity to satisfy MOHAP labeling mandates before compliance investments become table stakes.
For New Entrants and Emerging Players: Pursue grocery vertical penetration in Abu Dhabi and Sharjah urban corridors, where scheduled delivery slot infrastructure remains underdeveloped relative to fashion and electronics saturation. Target price-sensitive segments in Northern Emirates through cash-on-delivery optimization and localized customer service interfaces. Anchor go-to-market strategy around influencer-led social commerce partnerships that convert browse-to-buy journeys without competing for search placement against established incumbents.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with integrated payment float capture and real-time settlement infrastructure. Long-term viability hinges on regulatory navigation capacity across MOHAP product safety mandates and UAE Central Bank open banking evolution. Acquisition target archetype: vertically integrated fashion specialists with private-label design control and regional distribution networks. Signal to watch: same-day delivery coverage expansion announcements as inflection indicator for competitive intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Logistics Network Expansion | Dedicated last-mile fleets in Northern Emirates close coverage gaps against Amazon.ae and Noon. |
| Digital Wallet Integration | UAE Central Bank open banking APIs enable embedded finance products reducing checkout friction. |
| Arabic Localization Investment | MOHAP-compliant labeling and customer service infrastructure satisfy mandatory product safety standards. |
| Social Commerce Partnership | Influencer-led discovery on TikTok and Instagram captures 18-34 demographic attention from search. |
| Bonded Warehousing Commitment | Jebel Ali Free Zone long-term leases create structural cost advantages on cross-border inventory positioning. |
Research Methodology
Operator-level perspectives from marketplace executives, logistics fleet managers, merchant compliance officers, and UAE Central Bank regulatory specialists anchored the qualitative base for this analysis. Primary interviews combined with secondary validation against SEC filings of global marketplace operators, UAE customs trade data, and MOHAP product safety directive documentation. Bottom-up merchant volume estimates and top-down consumer expenditure benchmarks were triangulated to constrain forecast variance.
Scenario-bracketing around open banking adoption velocity and VAT enforcement stringency shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product category, distribution channel, payment method, and customer type, with cross-segment elasticity parameters estimated from historical channel shift patterns. CAGRs were derived from logistic diffusion curves fitted to smartphone penetration and digital wallet adoption trajectories, with grocery vertical penetration rates and social commerce conversion benchmarks as industry-specific forecast inputs.
Sensitivities concentrate around regulatory enforcement timing on low-value cross-border parcel taxation and real-time payment settlement mandate implementation schedules. Forecasts reflect assumptions regarding bonded warehousing capacity expansion and smartphone super-app convergence trajectories that could materially revise if infrastructure investment delays or platform consolidation accelerates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Italy Dropshipping Market
E-Commerce Solutions
3D Interactive Ticketing Solutions Market
E-Commerce Solutions
South Korea Ecommerce Logistics Market
E-Commerce Solutions
Argentina E-Commerce Market
E-Commerce Solutions
E-Commerce App Market
E-Commerce Solutions
Australia E-Commerce Market
E-Commerce Solutions
Quick Commerce Market
E-Commerce Solutions
Asia-Pacific E-Commerce Logistics Market
E-Commerce Solutions
China E-Commerce Market
E-Commerce Solutions
Asia-Pacific Automotive E-Commerce Market
E-Commerce Solutions
China Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Russia Alcohol E-Commerce Market
E-Commerce Solutions
Singapore E-Commerce Market
E-Commerce Solutions
Omnichannel Commerce Software Market
E-Commerce Solutions
US Social Commerce Market
E-Commerce Solutions
Latvia E-Commerce Market