
 Singapore E-Commerce Market | 2026-2036
Singapore E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore E-Commerce Market Outlook
IMDA's Data Protection Trustmark certification is redrawing competitive boundaries for marketplace operators in Singapore. Shopee leverages its integrated logistics and payment infrastructure to dominate cross-border fulfillment. Lazada sustains merchant loyalty through its LazMall branded storefront program and localized warehousing. Amazon Singapore competes on Prime delivery velocity and international catalog depth.
Singapore e-commerce encompasses digitally mediated transactions for goods and services conducted through internet-connected platforms, relying on encrypted payment gateways, mobile-optimized interfaces, and algorithmic recommendation engines to match buyers with sellers. The ecosystem serves retail distribution, consumer convenience, and SME market access functions across a city-state with ubiquitous smartphone penetration. Electronics and fashion product categories anchor transaction volume, though beauty and home living segments exhibit faster velocity as social commerce discovery tools mature. Mobile app and social media sales channels capture disproportionate engagement among Gen Z and millennial customer segments, while marketplace aggregations concentrate margin pools through advertising and fulfillment fee structures.
Singapore's Personal Data Protection Commission enforces consent and breach notification rules that elevate compliance costs for cross-border data flows. The Monetary Authority of Singapore coordinates with the Infocomm Media Development Authority on digital wallet interoperability and anti-money laundering protocols for e-payment providers. Stakeholders must monitor how platform liability frameworks and consumer protection amendments reshape seller onboarding requirements and dispute resolution obligations.
Market Dynamics
Singapore's Personal Data Protection Commission enforcement is compressing platform operating margins while accelerating compliance technology procurement across marketplace operators.
Growth Catalysts
- PDPA Trustmark Certification:IMDA's voluntary accreditation program creates differentiation premiums for data-responsible platforms. Marketplace operators invest in consent management infrastructure to secure this credential.
- Mobile Wallet Interoperability:The Monetary Authority of Singapore's unified QR code standards reduce payment friction across GrabPay, PayNow, and bank apps. Conversion rates improve as checkout steps compress.
- Live Commerce Streaming:TikTok Shop and Instagram Shopping integration is accelerating product discovery cycles among Gen Z cohorts. Beauty and fashion verticals capture disproportionate engagement from real-time purchase triggers.
Market Restraints
- Cross-Border Data Localization:PDPC's consent requirements for offshore server transfers add legal review costs to regional marketplace operations. Southeast Asian expansion plans face compliance timeline extensions.
- Last-Mile Labor Scarcity:Delivery workforce shortages in Singapore's tight immigration environment constrain same-day fulfillment scaling. Third-party logistics providers command premium rates during peak windows.
- Platform Fee Compression:Shopee and Lazada commission structures limit merchant net margins to single-digit percentages in electronics categories. Sellers migrate to direct-to-consumer channels where technically feasible.
Strategic Opportunities
- SME Export Enablement:Government Technology Agency grants subsidize cross-border listing tools for Singaporean manufacturers targeting Malaysia and Indonesia. Marketplace onboarding programs capture this vendor base.
- Recommerce Infrastructure:Circular economy mandates from the National Environment Agency create secondary market platforms for electronics and luxury goods. Authentication-as-a-service models emerge.
- AI-Powered Personalization:Generative recommendation engines converging with AR try-on tools reduce return rates in apparel verticals. Early adopters report fulfillment cost savings from improved size accuracy.
Industry Challenges
- Data Governance Talent Gap:Privacy engineering specialists command compensation premiums exceeding 40% above software engineering medians. Platforms compete with financial services for qualified compliance architects.
- Legacy ERP Integration:Merchant migration from on-premise inventory systems to marketplace APIs requires middleware development. Small retailers abandon multi-channel strategies due to technical complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore E-Commerce Market |
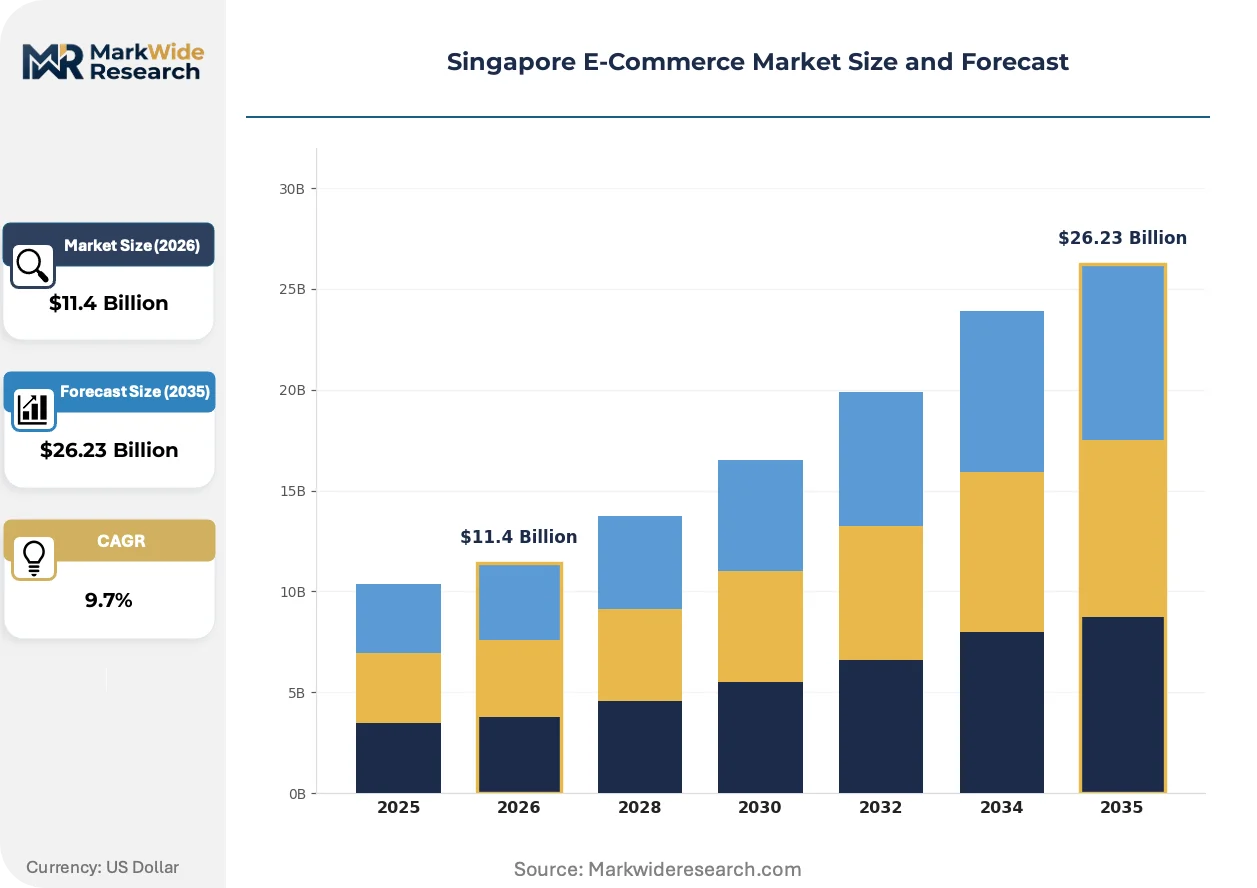
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $26.23 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Electronics, Fashion, Home & Living, Beauty Customer Segment: Millennials, Gen Z, Professionals, Families Payment Method: Credit Card, Digital Wallet, Bank Transfer, Cash on Delivery Sales Channel: Mobile App, Website, Social Media, Marketplaces |
| Companies Covered | Shopee, Lazada, Amazon Singapore, TikTok Shop, Qoo10, Carousell, RedMart, FairPrice Online, Shopify, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore E-Commerce Market Strategic Shifts
Algorithmic commerce interfaces are displacing traditional search-and-browse patterns across Singapore's mobile-first consumer base. Three developments merit particular attention.
Edge computing infrastructure is miniaturizing recommendation latency for live commerce streams. Shopee and Lazada deploy micro-data centers within Singapore's telco exchanges to sub-100 millisecond response times. Flash sale conversion rates climb as bidirectional video compression eliminates buffering friction during high-traffic product drops.
Singapore's Personal Data Protection Commission revised consent guidelines now mandate granular opt-in architectures for behavioral tracking. Marketplace operators re-engineer cookie consent flows to explicit permission layers. Beauty and health verticals face elevated compliance scrutiny given sensitive data classification of purchase histories.
Social discovery is displacing search-dominated purchase initiation among millennial cohorts. TikTok Shop's Singapore launch redirects apparel and electronics demand from traditional marketplace homepages. Influencer-commissioned sales now represent the fastest-growing traffic source for mid-market fashion merchants.
Singapore E-Commerce Market Segmentation
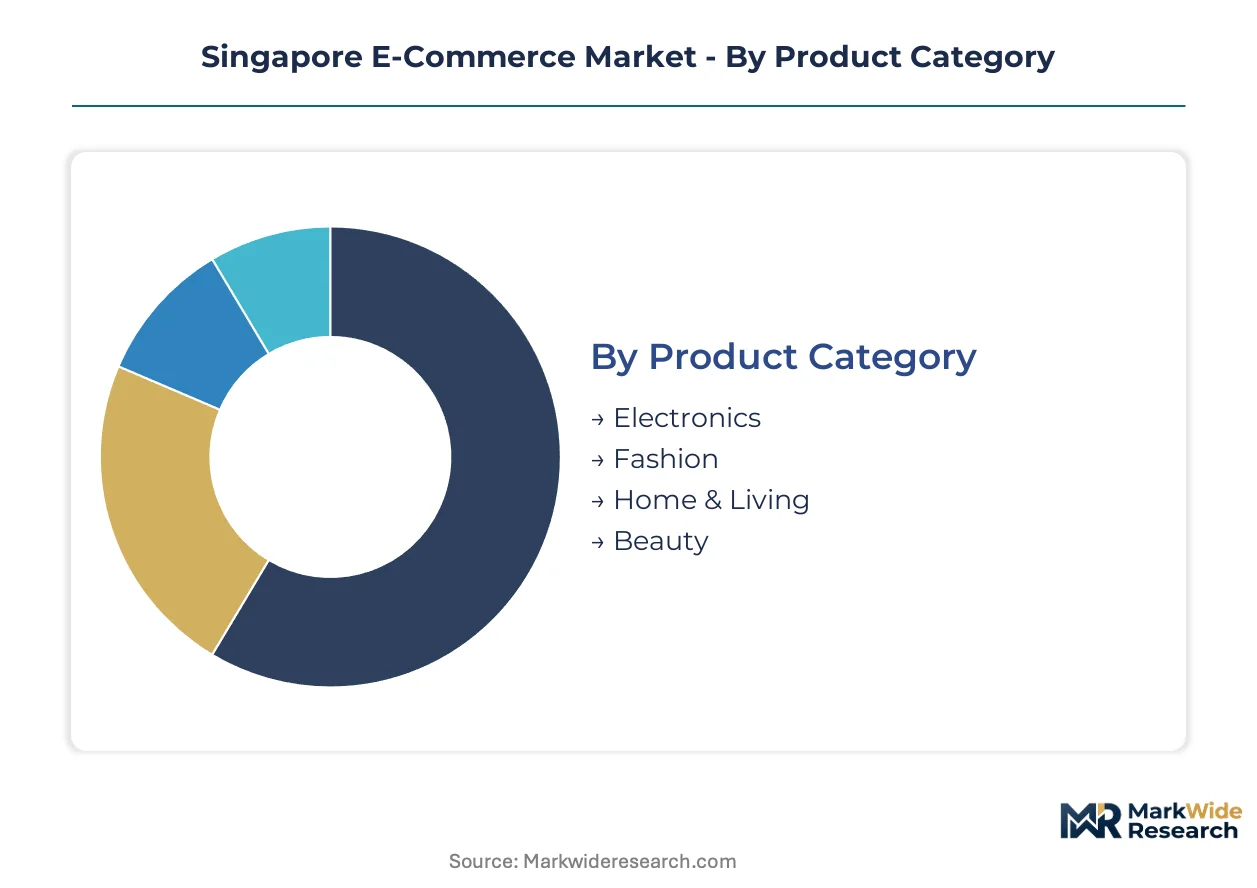
Singapore's e-commerce segmentation reveals distinct margin architectures across product categories and customer cohorts. Platform operators calibrate fulfillment investments and marketing spend based on these structural differences in purchase frequency and basket economics.
Product Category:
Electronics commands the highest absolute transaction values and generates substantial advertising revenue for marketplace operators through sponsored product placements.
- Electronics:Smartphones, laptops, and consumer appliances dominate transaction value. Demand concentrates among millennial professionals upgrading devices through LazMall and Shopee's official brand stores, driven by warranty reliability and installment financing availability.
- Fashion:Apparel, footwear, and accessories exhibit the highest return rates but also the strongest social commerce velocity. Gen Z discovery through TikTok Shop and Instagram Shopping is rotating purchase initiation away from traditional search, compressing merchant margins through influencer commission structures.
- Home & Living:Furniture, kitchenware, and décor items require specialized last-mile handling. Families represent the core customer base, with FairPrice Online and IKEA Singapore capturing recurring purchases through subscription delivery models.
- Beauty:Skincare, cosmetics, and personal care products show elevated repurchase frequency. Live streaming commerce from regional influencers drives impulse conversion, though PDPC consent requirements for sensitive purchase data elevate compliance overhead.
Electronics holds installed capacity. Beauty is rotating up the share rankings.
Customer Segment:
Generational divides in platform preference create distinct acquisition cost profiles for marketplace operators targeting Singapore's digitally saturated population.
- Millennials:Ages 28-43 with established purchasing power and brand loyalty patterns. Concentrated in marketplace loyalty programs and credit card-integrated checkout, this cohort sustains subscription commerce models for grocery and personal care.
- Gen Z:Ages 12-27 with platform-native discovery behaviors and low tolerance for friction. TikTok Shop and Instagram Shopping capture disproportionate engagement, with purchase decisions triggered by peer validation and limited-time drops rather than search intent.
- Professionals:Time-constrained white-collar workers prioritizing convenience over price comparison. Same-day delivery premiums and automated replenishment subscriptions characterize this segment's transaction patterns across RedMart and Amazon Singapore.
- Families:Multi-person households with high basket sizes and weekly purchase frequency. Online grocery platforms capture the majority of spend, with FairPrice Online's integration with physical store returns reducing perceived risk in fresh produce selection.
Millennials anchor current revenue. Gen Z is expanding most quickly as a share of transaction volume.
Payment Method:
Checkout infrastructure investments by platforms and financial institutions segment the market by transaction speed and fraud risk tolerance.
- Credit Card:Dominates high-value electronics and cross-border purchases. Bank-issued rewards programs and installment schemes sustain merchant preference despite interchange fees compressing net margins.
- Digital Wallet:GrabPay, PayNow, and ShopeePay capture growing share through unified QR standards mandated by the Monetary Authority of Singapore. Conversion rates improve as checkout steps compress to biometric authentication.
- Bank Transfer:Preferred by risk-averse consumers for large-ticket items. Manual processing introduces friction that platforms offset through escrow guarantees and seller verification badges.
- Cash on Delivery:Limited residual presence in Singapore's cashless economy. Remains relevant for first-time marketplace users and specific demographic pockets, though logistics costs render it economically marginal for operators.
Credit Card holds transaction value concentration. Digital Wallet is climbing the fastest in share of checkout volume.
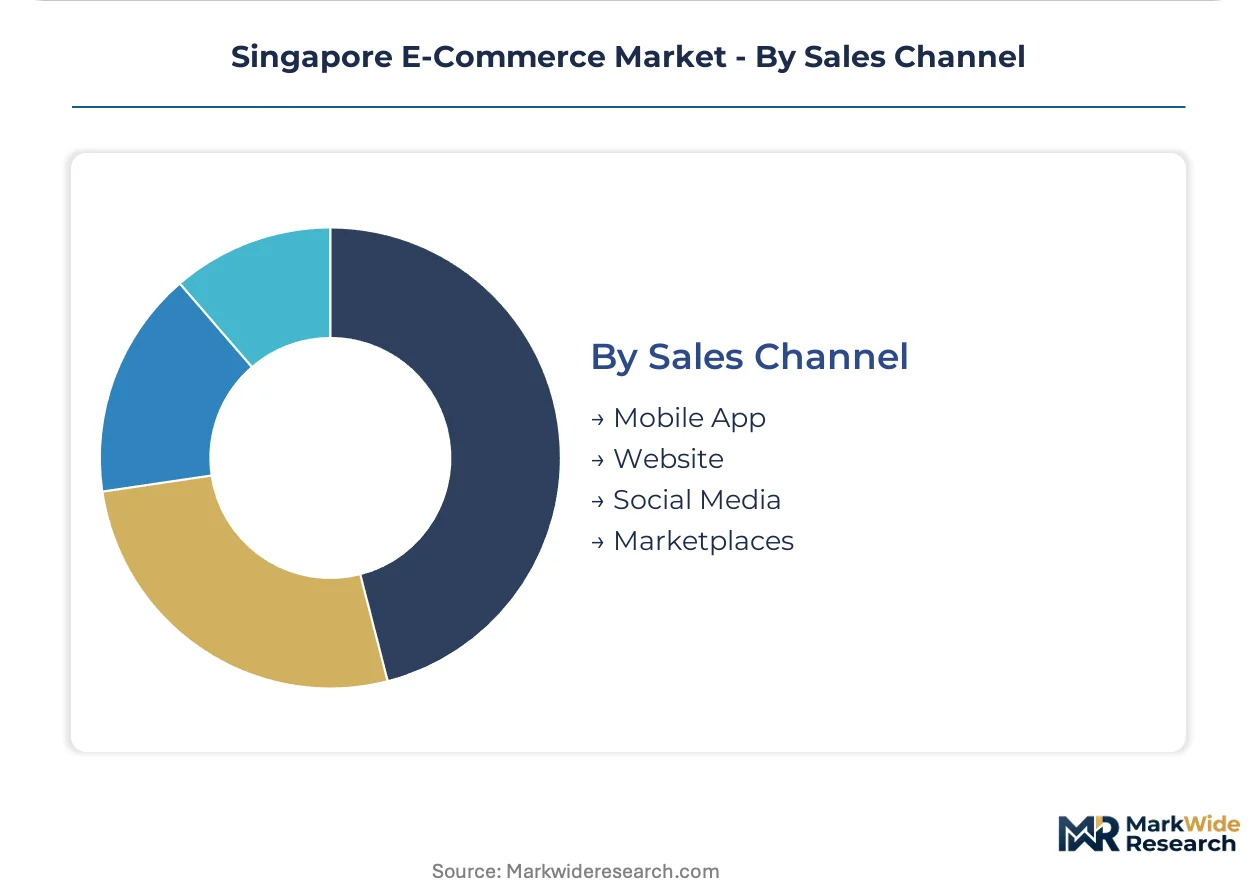
Sales Channel:
Traffic acquisition economics vary dramatically by channel, with algorithmic distribution reshaping merchant investment priorities.
- Mobile App:Native applications dominate session duration and push-notification-driven re-engagement. Shopee and Lazada invest in gamification and flash sale infrastructure to sustain daily active user metrics.
- Website:Browser-based commerce retains importance for comparison shopping and B2B procurement. Corporate purchasing and high-consideration categories sustain desktop-optimized experiences.
- Social Media:TikTok Shop and Instagram Shopping integration redirects discovery-stage demand. Influencer-commissioned sales now represent the steepest expansion trajectory for mid-market fashion and beauty merchants.
- Marketplaces:Aggregator platforms concentrate consumer trust and logistics infrastructure. LazMall and Shopee Mall branded storefronts command premium placement fees while offering counterfeit protection and return guarantees.
Mobile App holds user engagement duration. Social Media is gaining share fastest as a traffic origin point.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Smart Nation initiative channels SGD 2.5 billion annually into digital infrastructure, accelerating cross-border e-commerce corridors with Malaysia and Indonesia. The Infocomm Media Development Authority coordinates unified payment standards and data governance frameworks that reduce friction for regional marketplace expansion.
Malaysia
Cross-border fulfillment demand from Singaporean platforms drives warehouse investments in Johor Bahru and Port Klang. Bank Negara Malaysia's regulatory sandbox for digital wallets enables interoperability with Singapore's PayNow network. The Iskandar Malaysia special economic zone hosts last-mile distribution centers serving same-day delivery commitments to Singapore consumers.
Indonesia
Southeast Asia's largest population anchors volume growth for Singapore-based marketplace operators. Bank Indonesia's QRIS standardization mandates unified payment codes that Shopee and Lazada integrate for cross-border transactions. Batam's free trade zone facilities process returns and reverse logistics for Singapore-originated e-commerce shipments.
Thailand
Bangkok's influencer economy generates live commerce content consumed by Singaporean Gen Z demographics. The Bank of Thailand's PromptPay infrastructure connects to Singapore's FAST payment rails for instant cross-border settlement. Eastern Economic Corridor logistics parks serve as regional fulfillment hubs for beauty and electronics verticals.
Vietnam
Manufacturing cost advantages position Ho Chi Minh City as a sourcing origin for Singapore marketplace sellers. The State Bank of Vietnam's circular on e-payment licensing creates compliance checkpoints for regional platform operators. Da Nang's smart city investments include cold-chain infrastructure for cross-border grocery fulfillment trials.
Philippines
Remittance-linked e-wallet adoption in Manila creates payment behavior spillovers into Singapore-based platform usage. Bangko Sentral ng Pilipinas' National ID integration with financial services accelerates merchant onboarding for cross-border sellers. Cebu City's business process outsourcing sector supplies customer service operations for Singapore marketplace support functions.
Singapore E-Commerce Market Competitive Environment
Player mix skews toward integrated marketplace operators with captive logistics networks. Three domestic incumbents and two international platforms split transaction volume, with social commerce entrants eroding traditional search-based discovery. Strategic archetypes include full-stack aggregators, social-native platforms, and grocery-specialized operators. Competitive intensity manifests in flash sale frequency wars and same-day delivery radius expansion.
Among full-stack marketplace operators, Shopee, Lazada, and Amazon Singapore exemplify divergent fulfillment strategies. Shopee anchors the integrated logistics archetype through warehouse and last-mile assets. Lazada occupies the branded storefront position with LazMall certification programs. Amazon Singapore represents the international catalog depth model with Prime velocity guarantees. TikTok Shop and Carousell occupy the social discovery and recommerce niches respectively.
| Leading Market Players |
|---|
| Shopee |
| Lazada |
| Amazon Singapore |
| TikTok Shop |
| Qoo10 |
| Carousell |
| RedMart |
| FairPrice Online |
| Shopify |
| Others |
Value Chain & Pricing Dynamics
IMDA's Data Protection Trustmark certification gates both merchant platform access and consumer price tolerance simultaneously, compressing margins for non-compliant sellers while enabling premium positioning for accredited operators. Compliance infrastructure costs feed into final pricing, creating bifurcation between data-responsible and standard-tier marketplace participation.
Pricing Analysis
Cost-plus contracts with logistics indexation dominate fulfillment pricing between platforms and third-party delivery providers. Pricing stratifies across LazMall-certified, standard marketplace, and direct-to-consumer tiers based on warranty reliability and return guarantee differentiation. Cost compression in electronics verticals is intensifying because Shopee and Lazada commission structures squeeze merchant net margins to single-digit percentages. Small retailers exhibit highest price sensitivity and migrate to direct channels where technically feasible, while millennial professionals show lowest sensitivity for same-day delivery premiums.
Supply Chain Analysis
Inventory velocity and lead-time compression separate competing fulfillment architectures across Singapore's e-commerce landscape. Cross-border supply concentrates in China, Malaysia, and Indonesia for electronics and fashion sourcing. Raw material and component dependencies center on semiconductor chips, packaging materials, and last-mile delivery labor pools. Single-source vulnerability in Johor Bahru warehouse clusters exposes same-day delivery commitments to customs disruption risk. Distribution runs through captive logistics networks for Shopee and Lazada, with third-party providers filling capacity gaps during peak windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's e-commerce market operates as a defensive-moat story anchored in regulatory entrenchment, where PDPA compliance investments create switching costs that lock in merchant-platform relationships and deter casual market entry.
For Market Incumbents: Consolidate logistics infrastructure through micro-fulfillment center expansion in Singapore's telco exchanges to sub-100 millisecond response times for live commerce streams. Deepen backward integration into cross-border warehousing in Johor Bahru and Batam to defend against emerging social commerce entrants eroding traditional search-based discovery. Prioritize IMDA Data Protection Trustmark certification investment to maintain merchant acquisition cost advantages.
For New Entrants and Emerging Players: Differentiate on recommerce infrastructure and circular economy authentication services, where National Environment Agency mandates create white-space absent from incumbent marketplace coverage. Target SME export enablement segments through government-subsidized cross-border listing tools, the most penetrable vendor base outside Shopee-Lazada dominance. Pursue vertical specialization in beauty and health compliance-heavy categories where PDPC consent architecture expertise creates entry barriers.
For Investors and Strategic Acquirers: PDPC's revised consent guidelines for behavioral tracking reshape the acquisition landscape toward privacy-engineering capability targets over pure transaction volume. Long-term viability centers on platforms with embedded logistics networks and regulatory compliance technology stacks. The signal to watch is merchant churn rates among electronics sellers migrating to direct-to-consumer channels, indicating platform pricing power erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Center Deployment | Edge computing infrastructure in telco exchanges reduces recommendation latency below 100 milliseconds for live commerce. |
| PDPA Trustmark Certification Investment | IMDA accreditation creates merchant acquisition premiums and consumer trust differentiation against non-compliant competitors. |
| Cross-Border Warehouse Expansion | |
| Recommerce Platform Development | National Environment Agency circular economy mandates open secondary market revenue streams in electronics and luxury goods. |
| AI Personalization Engine Integration | Generative recommendation convergence with AR try-on tools reduces apparel return rates and fulfillment cost recovery. |
Study Parameters
Cross-validation between primary marketplace operator interviews and secondary regulatory filing analysis anchors the qualitative findings in this study. Conversations with platform logistics directors, merchant category managers, PDPC compliance officers, and payment infrastructure engineers combined with IMDA certification databases, Monetary Authority of Singapore payment system disclosures, and Infocomm Media Development Authority infrastructure reports. Bottom-up transaction volume modeling and top-down GDP-attribution approaches triangulate market sizing across the analysis window.
Sensitivity analysis on fulfillment cost inflation and merchant commission tolerance frames the forecast uncertainty bounds. Segmentation dimensions modeled include product category, customer generation cohort, payment method, and sales channel origin across the projection horizon. CAGRs derive from logistic adoption curve fitting and smartphone penetration saturation trajectories. Inputs incorporate PDPC enforcement intensity indices and cross-border payment interoperability rollout schedules.
The analysis sits within stated boundaries; outcomes outside sustained mobile wallet adoption velocity or escalated data localization requirements would require recalibration. Forecasts reflect documented assumptions about platform fee structures and logistics labor availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
United Arab Emirates E-Commerce Market
E-Commerce Solutions
Social Commerce Market
E-Commerce Solutions
M-Commerce Market
E-Commerce Solutions
E-Commerce Lockers Market
E-Commerce Solutions
Europe E-Commerce Apparel Market
E-Commerce Solutions
Croatia E-Commerce Market
E-Commerce Solutions
Asia-Pacific Automotive E-Commerce Market
E-Commerce Solutions
Cross Border Ecommerce Market
E-Commerce Solutions
Egypt E-Commerce Market
E-Commerce Solutions
Middle East and Africa E-Commerce Market
E-Commerce Solutions
Poland E-Commerce Market
E-Commerce Solutions
United Kingdom Same Day Delivery Market
E-Commerce Solutions
China Alcohol E-Commerce Market
E-Commerce Solutions
Argentina Alcohol E-Commerce Market
E-Commerce Solutions
Finland E-Commerce Market