
 Global Film Coating Machine Market | 2026-2036
Global Film Coating Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Film Coating Machine Market Analysis
A capital-intensity divergence between automated high-throughput systems and semi-automatic batch equipment is rotating competitive advantage toward vendors with integrated process analytical technology. Nordson Corporation leverages its precision spray control heritage to anchor North American pharmaceutical coating lines. Gema Switzerland GmbH sustains European leadership through electrostatic coating specialization for nutraceutical applications. ANEST IWATA Corporation competes aggressively across Asian markets with compact, energy-efficient immersion systems.
Film coating machines apply polymer-based coatings to solid dosage forms and food particles using controlled spray, immersion, or electrostatic deposition, typically operating at batch capacities from one kilogram to over one thousand kilograms with process temperatures between thirty and sixty degrees Celsius. Tablet coating systems dominate installed base value due to pharmaceutical validation requirements and replacement cycles, while electrostatic coating technology captures expanding margin pools in cosmetics and functional food applications where uniform thin-film deposition reduces active ingredient waste. Spray coating occupies the largest technology segment by unit volume across contract manufacturing facilities, though immersion systems lead in research institution procurement where flexibility across batch sizes outweighs throughput optimization.
FDA cGMP guidelines and EU MDR conformity assessment procedures enforce coating weight uniformity and batch record traceability, directly shaping equipment specification requirements for pharmaceutical and medical device applications. China's NMPA implementation of updated GMP annexes for pharmaceutical machinery creates additional compliance layers for imported coating systems. India's CDSCO alignment with ICH Q7 guidelines drives domestic manufacturers toward equipment with embedded process analytical technology. Stakeholders must evaluate regulatory divergence across FDA, EMA, and NMPA jurisdictions when configuring product portfolios for multinational deployment, as validation protocol harmonization remains incomplete and region-specific documentation burdens continue expanding.
Market Dynamics
Process analytical technology integration is compressing batch validation timelines while fragmenting vendor tiers between PAT-enabled system suppliers and legacy equipment maintainers.
Growth Catalysts
- Modified-release tablet expansion:Pharmaceutical manufacturers in India and China are scaling capacity for controlled-release formulations, driving demand for precision coating systems with real-time thickness monitoring.
- EU MDR conformity assessment:Medical device coating requirements under the EU's Medical Device Regulation are mandating enhanced batch traceability, forcing equipment upgrades across European contract manufacturers.
- Electrostatic thin-film deposition:Functional food and nutraceutical producers are adopting electrostatic coating to reduce active ingredient waste, opening margin pools beyond traditional pharmaceutical applications.
Market Restraints
- Stainless steel and polymer input volatility:Equipment fabrication costs fluctuate with specialty alloy and food-grade polymer pricing, squeezing margins for mid-scale system builders.
- Validation documentation burden:Divergent FDA cGMP, EMA GMP Annex 15, and NMPA pharmaceutical machinery requirements create region-specific compliance costs that deter single-configuration exports.
- Used equipment refurbishment:Secondary markets for validated coating systems extend replacement cycles among budget-constrained research institutions and emerging market CMOs.
Strategic Opportunities
- Brazilian ANVISA alignment:Latin American pharmaceutical regulators are harmonizing with ICH Q7 guidelines, creating first-mover advantage for PAT-integrated system vendors in São Paulo and Rio de Janeiro manufacturing clusters.
- Continuous processing convergence:Integration of film coating with continuous tablet manufacturing lines offers throughput advantages over batch systems for high-volume generic producers.
- Cosmetics micro-encapsulation:Premium skincare brands are adopting pharmaceutical-grade coating uniformity for active ingredient protection, transferring technical specifications across industry boundaries.
Industry Challenges
- Process analytical technology expertise scarcity:Equipment vendors struggle to staff field service teams capable of calibrating spectroscopic sensors and multivariate data analysis software.
- Legacy system integration complexity:Retrofitting PAT capabilities into existing coating lines requires mechanical and software modifications that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Film Coating Machine Market |
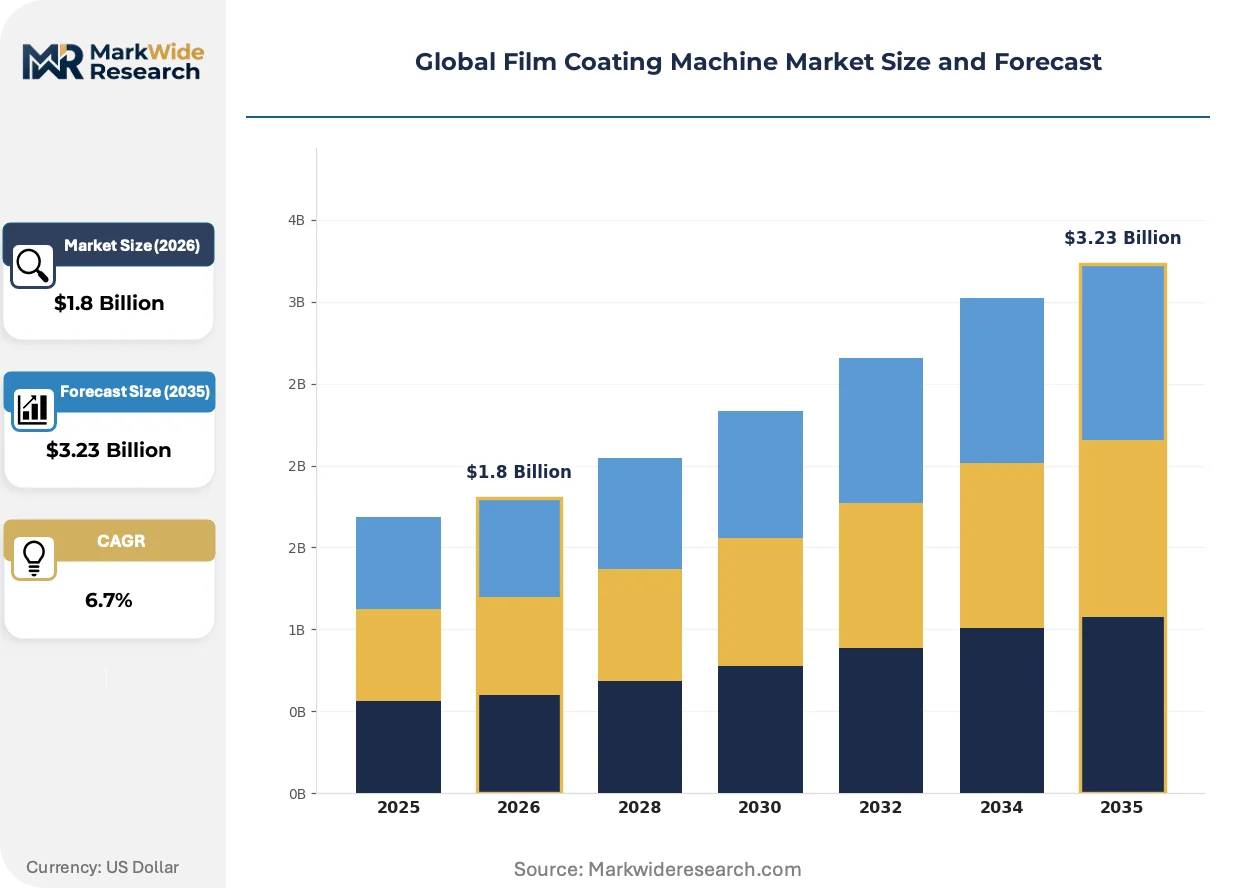
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet Coating, Granule Coating, Pellets Coating, Others Application: Pharmaceuticals, Food Industry, Nutraceuticals, Cosmetics Technology: Spray Coating, Immersion Coating, Electrostatic Coating, Others End User: Manufacturers, Contract Coaters, Research Institutions, Startups |
| Companies Covered | Wuxi Tianniu Intelligence Equipment Co., Ltd., Xi'an Rich Smart Technology Co., Ltd., Sprimag, Nordson Corporation, Gema Switzerland GmbH, J. Wagner GmbH, ANEST IWATA Corporation, Thomas Processing, Syntegon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Film Coating Machine Market Emerging Trajectories
Digital twin deployment is reshaping how coating process parameters are optimized before physical batch execution, compressing development cycles for new formulations.
Multivariate process modeling software is decomposing traditional design-of-experiments approaches in film coating development. Generic pharmaceutical manufacturers in India are deploying these tools aggressively to accelerate ANDA submissions. The technology is decomposing competitive advantage from hardware throughput toward algorithmic process knowledge capture.
China's NMPA implementation of updated GMP annexes for pharmaceutical machinery is mandating electronic batch records and audit trail functionality for imported coating systems. Domestic equipment manufacturers in Jiangsu and Zhejiang provinces are embedding compliance features natively to capture substitution opportunities. Foreign vendors are responding with localized software architectures and Mandarin-language human-machine interfaces.
Contract manufacturing organizations are consolidating equipment procurement decisions at regional hub levels rather than individual facility autonomy. Large CMOs in East Asia are standardizing on single-vendor coating platforms to simplify operator training and spare parts logistics. This concentration is most visible in Singapore and South Korea, where multinational pharmaceutical outsourcing has centralized technical decision-making with global supply chain functions.
Global Film Coating Machine Market Segmentation
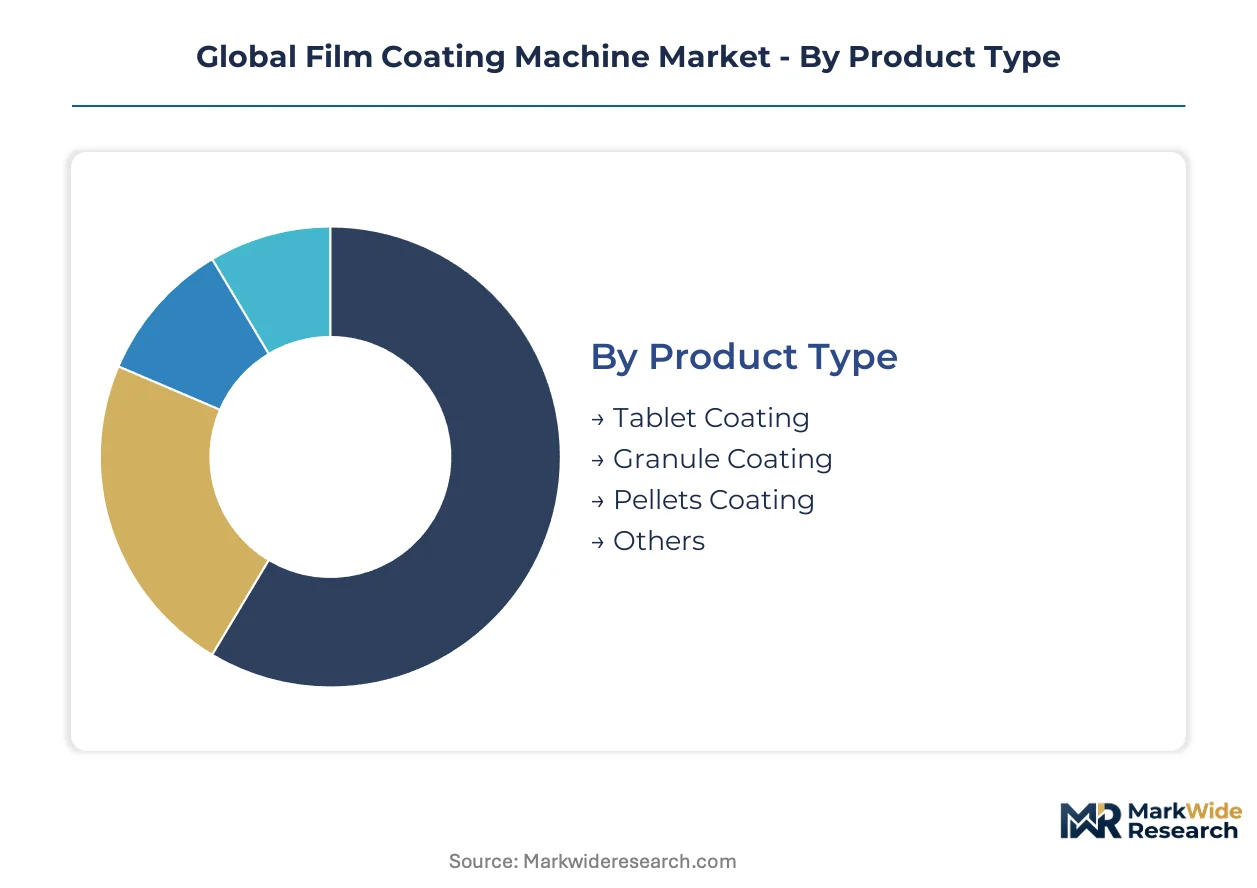
Film coating machine segmentation reveals how validation requirements, batch scale economics, and regulatory compliance reshape procurement priorities across pharmaceutical, food, and cosmetic applications. Equipment specification diverges sharply between high-throughput manufacturing lines and flexible research-scale systems.
Product Type:
Margin pools concentrate in tablet coating systems where pharmaceutical validation protocols and replacement cycles sustain premium pricing, while pellet coating equipment captures expanding nutraceutical contract manufacturing demand.
- Tablet Coating:These systems apply polymer films to solid oral dosages using perforated drum or fluidized bed configurations with batch capacities from five to over one thousand kilograms. Pharmaceutical manufacturers in India and China are scaling capacity for modified-release formulations, driving demand for precision spray control and real-time thickness monitoring to meet FDA cGMP and NMPA validation requirements.
- Granule Coating:Fluidized bed processors coat irregular particles for controlled-release applications and taste masking, operating with integrated process analytical technology for batch uniformity documentation. Functional food producers in Brazil and Southeast Asia are adopting these systems for probiotic and enzyme protection, opening margin pools beyond traditional pharmaceutical end-uses.
- Pellets Coating:Multi-particulate coating enables precise drug release kinetics and reduced gastric irritation through layered polymer deposition.
- Others:Specialized configurations include capsule coating and mini-tablet systems for pediatric and geriatric dosage forms.
Tablet coating holds installed capacity. Pellets coating is rotating up the share rankings.
Application:
Application-driven segmentation tracks how coating uniformity requirements migrate across industry boundaries, with pharmaceutical-grade specifications now penetrating cosmetics and functional food production.
- Pharmaceuticals:Solid oral dosage coating dominates value capture, with modified-release and enteric formulations requiring precise polymer deposition control. EU MDR conformity assessment procedures and FDA cGMP guidelines enforce batch traceability and coating weight uniformity, directly shaping equipment specifications for European and North American manufacturing facilities.
- Food Industry:Confectionery and functional ingredient coating demands flavor encapsulation, moisture barrier protection, and extended shelf-life performance. East Asian contract manufacturers in Singapore and South Korea are consolidating procurement decisions at regional hub levels, standardizing on single-vendor platforms to simplify operator training across multiple facilities.
- Nutraceuticals:Vitamin and mineral coating requires taste masking and oxidative stability for consumer acceptance.
- Cosmetics:Micro-encapsulation of active ingredients for skincare applications transfers pharmaceutical-grade uniformity specifications across industry boundaries.
Pharmaceuticals anchor revenue concentration. Cosmetics is gaining share fastest.
Technology:
Technology segmentation reflects a capital-intensity divergence between automated high-throughput spray systems and compact immersion equipment serving research and emerging market applications.
- Spray Coating:Perforated drum and fluidized bed spray systems apply atomized polymer solutions through precision nozzles with controlled airflow and temperature parameters. Contract manufacturing organizations across East Asia are deploying these systems for high-volume generic production, with CMOs in Singapore and South Korea standardizing procurement at regional hub levels to consolidate spare parts logistics.
- Immersion Coating:Dip-coating and pan-coating systems submerge substrates in coating baths for uniform film deposition, offering lower capital investment and operational simplicity. Research institutions in Japan and Germany favor these systems for flexibility across batch sizes where throughput optimization matters less than experimental adaptability.
- Electrostatic Coating:Charged particle deposition enables ultra-thin film application with minimal active ingredient waste for high-value nutraceutical and cosmetic applications.
- Others:Emerging technologies include supercritical fluid coating and atomic layer deposition for specialized barrier applications.
Spray coating dominates unit volume. Electrostatic coating shows the steepest expansion trajectory.
End User:
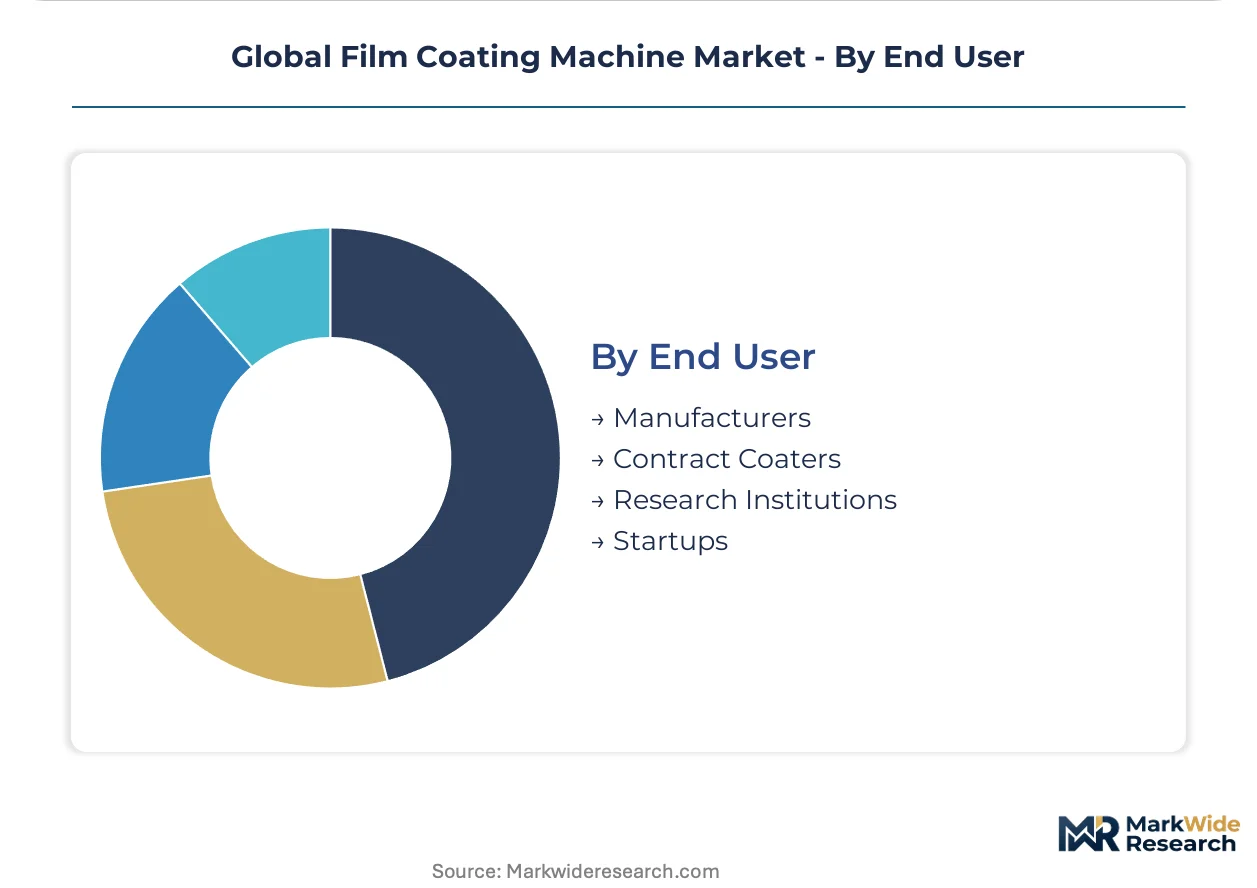
End user segmentation captures how procurement authority is consolidating toward regional CMO hubs while research institutions and startups fragment demand toward flexible, lower-capacity systems.
- Manufacturers:Integrated pharmaceutical and food companies operate captive coating facilities with validated production lines requiring embedded process analytical technology and electronic batch record functionality. Domestic equipment manufacturers in China's Jiangsu and Zhejiang provinces are embedding NMPA compliance features natively to capture substitution opportunities from foreign vendors.
- Contract Coaters:CMOs and specialized coating service providers aggregate demand from multiple clients, driving standardization on single-vendor platforms. Large contract manufacturers in East Asia are consolidating technical decision-making with global supply chain functions, centralizing equipment procurement at Singapore and South Korean regional hubs.
- Research Institutions:Universities and development laboratories prioritize batch flexibility and rapid changeover over throughput optimization.
- Startups:Emerging companies in nutraceuticals and cosmetics seek compact, semi-automatic systems with lower capital barriers.
Manufacturers retain the largest installed base. Contract coaters are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented pharmaceutical manufacturing in East Asia generates substantial equipment import demand, while European and North American markets favor replacement cycles over greenfield capacity. Trade flows concentrate coating machine procurement decisions in contract manufacturing hubs serving multinational drug sponsors.
China
Domestic pharmaceutical machinery builders in Jiangsu and Zhejiang provinces embed NMPA compliance features natively to capture substitution opportunities from foreign vendors. The regulator's updated GMP annexes mandate electronic batch records and audit trail functionality for imported systems. Shanghai and Suzhou manufacturing clusters anchor domestic production capacity for modified-release tablet coating lines.
United States
FDA cGMP guidelines enforce coating weight uniformity and batch record traceability, directly shaping equipment specifications for pharmaceutical applications. Precision spray control heritage anchors North American pharmaceutical coating line procurement decisions. New Jersey and North Carolina pharmaceutical manufacturing corridors drive validation-intensive replacement demand.
Germany
EMA GMP Annex 15 conformity assessment procedures mandate enhanced batch traceability for medical device coating applications. Electrostatic coating specialization sustains European leadership in nutraceutical thin-film deposition. Bavaria and Baden-Württemberg precision engineering clusters supply validated systems to contract manufacturers across the continent.
India
CDSCO alignment with ICH Q7 guidelines drives domestic manufacturers toward equipment with embedded process analytical technology. Modified-release tablet capacity expansion concentrates procurement decisions in Mumbai and Ahmedabad pharmaceutical manufacturing zones. Contract research organizations in Hyderabad accelerate demand for flexible batch-scale systems.
Brazil
ANVISA harmonization with ICH Q7 guidelines creates first-mover positioning for PAT-integrated system vendors. São Paulo and Rio de Janeiro manufacturing clusters consolidate regional pharmaceutical production decisions. Latin American contract manufacturers standardize equipment platforms to simplify cross-border regulatory submissions.
Global Film Coating Machine Market Vendor Landscape
Concentration sits with precision spray control specialists and electrostatic deposition technologists who anchor validated pharmaceutical production lines. The vendor base stratifies across three tiers: multinational industrial conglomerates with integrated process analytical technology portfolios, regional machinery builders with compliance-embedded domestic offerings, and specialized coating system houses with niche application expertise. Dominant competitive moves include strategic partnerships for PAT software integration and geographic expansion through localized service networks.
Among Asia-Pacific fabricators, Wuxi Tianniu Intelligence Equipment Co., Ltd. and Xi'an Rich Smart Technology Co., Ltd. occupy positions within the compliance-embedded domestic tier, while ANEST IWATA Corporation exemplifies the compact system specialization archetype for research-scale applications. These companies represent the competitive response to NMPA localization requirements and the research institution procurement segment respectively.
| Leading Market Players |
|---|
| Wuxi Tianniu Intelligence Equipment Co., Ltd. |
| Xi'an Rich Smart Technology Co., Ltd. |
| Sprimag |
| Nordson Corporation |
| Gema Switzerland GmbH |
| J. Wagner GmbH |
| ANEST IWATA Corporation |
| Thomas Processing |
| Syntegon |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between East Asian contract manufacturers and precision spray component suppliers lock in both stainless steel alloy access and eighteen-month price visibility for validated coating systems. These contracts insulate procurement teams from specialty polymer volatility while embedding FDA cGMP compliance documentation costs into baseline equipment pricing.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers capture pharmaceutical-grade validation packages with embedded process analytical technology, while economy configurations serve research institutions with stripped-down documentation. Cost compression in mid-scale batch equipment is intensifying because stainless steel input volatility squeezes fabricator margins. Generic pharmaceutical manufacturers in India exhibit the highest price sensitivity, whereas North American medical device coaters prioritize compliance assurance over unit economics.
Supply Chain Analysis
Strategic stockpiling of specialty alloys and food-grade polymers dominates inventory strategy among German and Swiss precision engineering clusters serving European pharmaceutical manufacturers. Component fabrication draws from Germany, China, and Japan for perforated drum assemblies, precision spray nozzles, and spectroscopic sensor modules. Single-source vulnerability concentrates in high-purity stainless steel grades sourced from specific European mills. Distribution runs through regional equipment distributors with certified service capabilities rather than direct manufacturer-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Film coating machine vendors increasingly monetize process analytical technology calibration contracts and multivariate modeling software subscriptions, both expanding faster than hardware shipments as pharmaceutical manufacturers outsource validation expertise.
For Market Incumbents: Shield installed base relationships by embedding proprietary PAT software architectures that increase switching costs for validated production lines. Deepen backward integration into precision nozzle manufacturing to offset stainless steel margin pressure from Asian component suppliers. Prioritize certification investment in Brazil's ANVISA-aligned validation protocols before regional competitors establish service footprints in São Paulo manufacturing clusters. For New Entrants and Emerging Players: Differentiate on compact immersion system configurations targeting Japanese and German research institutions where batch flexibility outweighs throughput optimization. White-space opportunities concentrate in cosmetics micro-encapsulation applications transferring pharmaceutical-grade uniformity specifications to premium skincare brands. Pursue direct-to-laboratory sales channels bypassing traditional distributor markups for lower-capacity equipment procurement. For Investors and Strategic Acquirers: Capital is best deployed toward PAT-enabled system specialists with embedded software recurring revenue streams rather than legacy hardware maintainers facing replacement cycle extension. Acquisition targets should demonstrate field service teams capable of spectroscopic sensor calibration and multivariate data analysis support. Watch for inflection when NMPA electronic batch record mandates accelerate domestic substitution pressure on foreign vendor market share in China.| Strategic Initiative | Industry Significance |
|---|---|
| PAT Software Integration Partnership | Spectroscopic sensor vendors gain locked-in calibration revenue from pharmaceutical coaters. |
| Backward Integration into Nozzle Manufacturing | Precision spray control heritage anchors margin defense against alloy input volatility. |
| ANVISA Validation Certification Program | First-mover positioning in São Paulo clusters captures Latin American generic pharmaceutical expansion. |
| Cosmetics Micro-encapsulation Product Line | Pharmaceutical-grade uniformity specifications transfer to premium skincare active ingredient protection. |
| Regional Hub Service Network Expansion | Singapore and South Korean CMO procurement consolidation demands localized spare parts logistics. |
Methodological Framework
Operator-level perspectives from pharmaceutical plant engineers, CMO technical procurement leads, and aftermarket service heads anchored the qualitative base for this analysis. Primary fieldwork combined with secondary validation from FDA cGMP guidance documents, EMA GMP Annex 15 conformity assessment procedures, and NMPA pharmaceutical machinery annexes. Bottom-up equipment shipment tallies triangulated against top-down pharmaceutical manufacturing capacity expansion announcements across India, China, and Brazil.
Sensitivity analysis tested forecast outputs against alternative scenarios for stainless steel pricing trajectories and regulatory harmonization timelines across the projection horizon. Segmentation dimensions modeled include coating technology type, batch capacity tier, end-use application, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and greenfield capacity announcements. Industry-specific inputs incorporated modified-release tablet pipeline data and contract manufacturing organization facility expansion tracking.
The analysis sits within stated boundaries; outcomes outside sustained pharmaceutical outsourcing trends or accelerated continuous processing adoption would require recalibration. Forecasts reflect assumptions regarding validation documentation burden persistence and process analytical technology penetration rates across emerging market manufacturing clusters. Revision becomes warranted when NMPA domestic substitution thresholds or Brazilian ANVISA harmonization implementation crosses materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Palletizing Machines Market
Packaging Machinery
Automatic Liquid Filling Machines Market
Packaging Machinery
Bag in Box Packaging Machine Market
Packaging Machinery
Binding & Lamination Machines Market
Packaging Machinery
Volumetric Filling Machines Market
Packaging Machinery
Form-Fill-Seal (FFS) Packaging Machine Market
Packaging Machinery
Tray Packing Machine Market
Packaging Machinery
Liquid Pouch Filling and Sealing Machine Market
Packaging Machinery
Kraft Paper Machines Market
Packaging Machinery
Multi-Head Filling Machines Market
Packaging Machinery
Polyester Strapping Machines Market
Packaging Machinery
Tissue Paper Unwinding Machine Market
Packaging Machinery
Bottle Blowing Machine Market
Packaging Machinery
In-Line Thermoforming Machine Market
Packaging Machinery
Global Vial Cap Sealing Machines Market
Packaging Machinery
Confectionery Packaging Machine Market