
 Enveloping & Stacking Machine Market | 2026-2036
Enveloping & Stacking Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Enveloping & Stacking Machine Market Insights
The EU Green Deal's packaging waste reduction targets is restructuring procurement priorities across European food processing units. ANDRITZ Sovema leverages its electromechanical servo platforms to dominate high-throughput paper packaging lines in Nordic markets. Manz AG anchors its position in electronics protection through precision stacking systems calibrated for lithium-ion cell formats. Shenzhen Better Technology competes aggressively on conveyor-based semi-automatic configurations for emerging Asian pharma manufacturing firms.
Enveloping and stacking machines integrate film wrapping, carton insertion, and pallet layering functions into continuous material handling workflows, typically operating at throughputs exceeding 200 cycles per minute with positioning accuracy within 0.5 millimeters. These systems serve primary industrial purposes in automating the terminal stages of production lines where product protection and unitization precede distribution logistics. Fully automatic configurations command the dominant share of value pools given their labor substitution economics in high-volume printing houses and electronics assembly lines, while servo-drive technology is capturing growth from pneumatic alternatives due to energy efficiency gains and programmable motion profiles that reduce changeover downtime. Conveyor-based systems occupy a mature, price-sensitive tier serving smaller food processing units with intermittent batch requirements.
FDA's Current Good Manufacturing Practice enforcement and EU MDR serialization requirements are elevating validation documentation burdens for pharma manufacturing firms sourcing bundling equipment, effectively raising barriers for non-certified suppliers. Germany's KBA and France's ANSM coordinate with EMA guidance to harmonize machine safety standards across CE-marked installations, compressing design cycles for pan-European deployments. Stakeholders must monitor how EU AI Act risk classifications will treat autonomous vision-guided stacking systems, as this determination will reshape R&D allocation between electromechanical and software-intensive architectures.
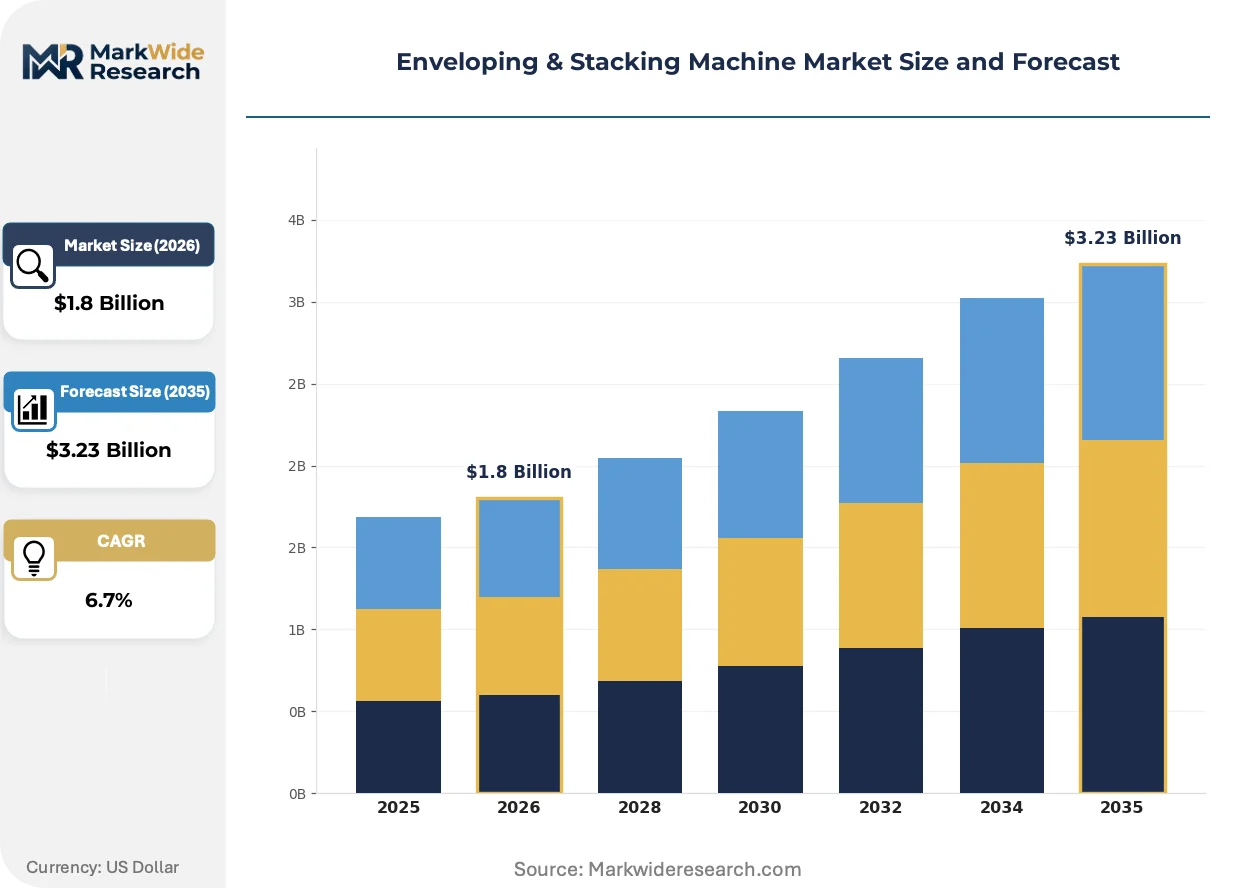
Market Dynamics
Servo-drive electromechanical architectures are systematically displacing pneumatic actuation across European packaging corridors, compressing energy consumption and programmable motion precision while raising capital intensity thresholds for mid-tier suppliers.
Growth Catalysts
- EU MDR serialization mandates:Pharmaceutical bundling operations must deploy automated enveloping lines with full track-and-trace capabilities, forcing equipment refresh cycles across contract manufacturing organizations.
- Battery cell format standardization:Lithium-ion production lines in Germany and South Korea require precision stacking systems calibrated to prismatic and pouch cell dimensions, creating sustained demand for electromechanical platforms.
- Servo-drive energy efficiency:Programmable motion profiles reduce changeover downtime by eliminating mechanical cam systems, compelling food processing units to modernize legacy pneumatic infrastructure.
Market Restraints
- Specialized component supply concentration:High-precision linear encoders and torque motors concentrate among Japanese and German component specialists, exposing OEMs to extended lead times.
- Validation documentation burdens:FDA Current Good Manufacturing Practice enforcement and EMA guidance harmonization through KBA and ANSM coordination compress design cycles while elevating compliance costs for pan-European deployments.
- Technical limitation in vision integration:Autonomous vision-guided stacking systems face uncertain risk classification under the EU AI Act, chilling R&D allocation toward software-intensive architectures.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO track-and-trace requirements are emerging, creating first-mover advantage for suppliers offering validated semi-automatic configurations with serialization modules.
- EU Green Deal packaging waste targets:The framework is restructuring procurement priorities across food processing units, favoring film-wrapping systems with biodegradable material compatibility.
- Convergence of servo platforms with edge analytics:Real-time vibration monitoring and predictive maintenance algorithms are opening subscription-based service revenue streams for OEMs serving high-throughput printing houses.
Industry Challenges
- Electromechanical systems integration:Legacy pneumatic stacking infrastructure in Mittelstand manufacturing facilities requires costly retrofit engineering to accommodate servo-drive motion controllers.
- Certification timeline compression:CE-marked installations must simultaneously satisfy KBA machine safety standards and evolving EMA guidance, extending validation phases for pharmaceutical bundling equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enveloping & Stacking Machine Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Fully Automatic, Semi Automatic, Manual, Conveyor-Based Technology: Servo Drive, Pneumatic, Hydraulic, Electromechanical Application: Paper Packaging, Food Wrapping, Pharmaceutical Bundling, Electronics Protection End User Industry: Printing Houses, Food Processing Units, Pharma Manufacturing Firms, Electronics Assembly Lines |
| Companies Covered | ANDRITZ Sovema, Zesar, Manz AG, Shenzhen Better Technology, Patel Material Handling Equipment, Semyung India, Shuttleworth, Soco System, Konecranes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enveloping & Stacking Machine Market Trends and Innovations
Electromechanical architectures, regulatory compliance automation, and outcome-based procurement models are converging to reshape competitive positioning across the terminal packaging equipment sector.
Vision-guided robotic stacking is automating pallet layering functions in electronics assembly lines. Tier-one battery manufacturers in South Korea and Germany are deploying these systems at throughput rates exceeding 200 cycles per minute. The technology is automating quality inspection previously handled by manual sampling, compressing labor substitution economics for high-volume operations.
EU AI Act risk classification frameworks are creating compliance uncertainty for autonomous vision systems. Machine builders must now document algorithmic decision pathways for pallet pattern optimization, adding engineering overhead. Electronics protection applications face the steepest documentation burdens as regulators scrutinize self-learning motion controllers.
After-sales service unbundling is fragmenting traditional maintenance contracts. Food processing units in Nordic markets now procure spare parts and remote diagnostics through digital platforms rather than OEM service agreements. This pattern concentrates in Denmark and Sweden where equipment density supports third-party technical labor pools.
Enveloping & Stacking Machine Market Segmentation
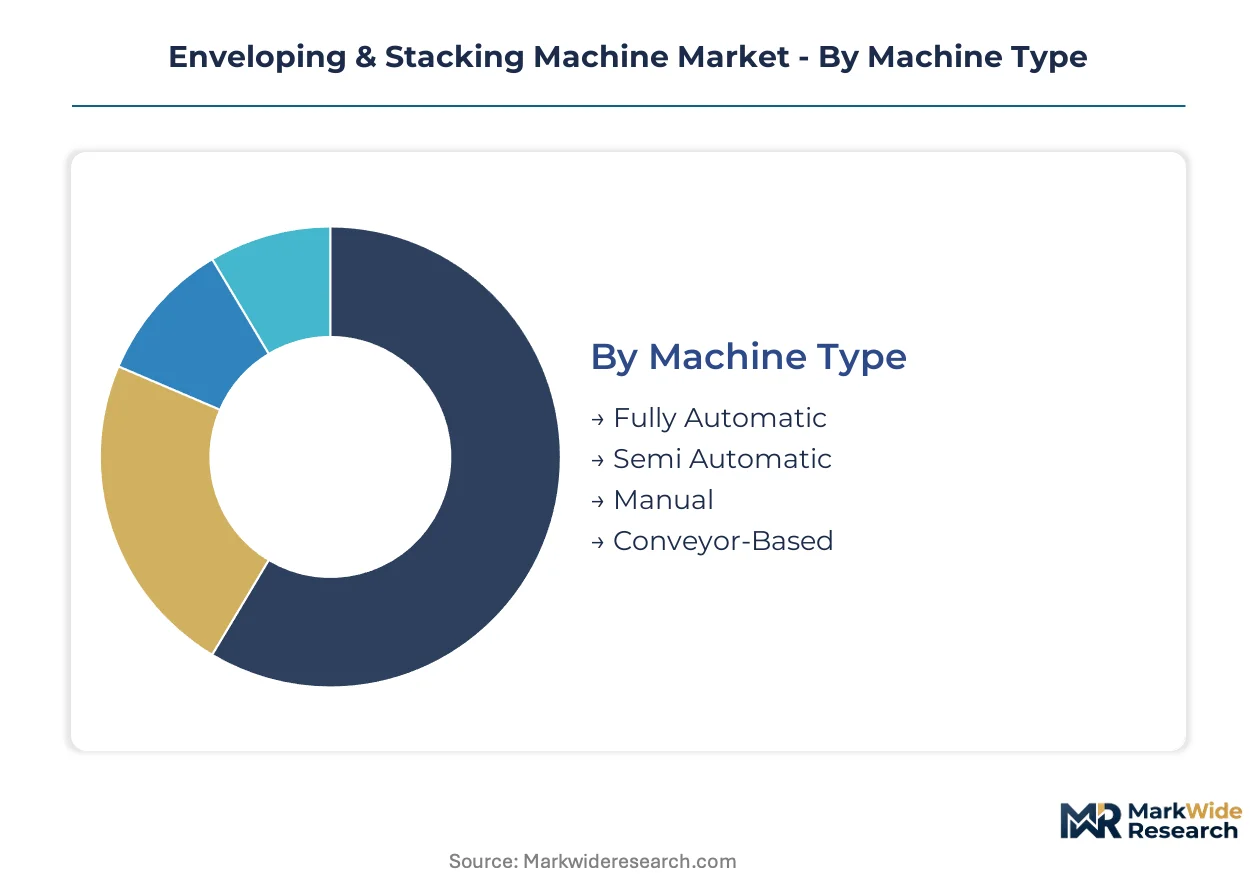
Segmentation in the enveloping and stacking machine market reflects divergent capital deployment strategies across automation tiers and motion control architectures. Equipment buyers balance throughput requirements against validation burdens and energy efficiency mandates when selecting configurations.
Machine Type:
Capital intensity escalates sharply across the automation spectrum, with integrated control systems and safety architectures driving upfront investment differentials.
- Fully Automatic:These systems integrate film wrapping, carton insertion, and pallet layering into continuous workflows exceeding 200 cycles per minute. Pharma manufacturing firms in Germany deploy these configurations to satisfy EU MDR serialization mandates while minimizing labor exposure in cleanroom environments.
- Semi Automatic:Conveyor-fed designs with operator-assisted loading stations dominate emerging Asian pharma manufacturing facilities where batch sizes fluctuate and capital budgets constrain full automation. CDSCO track-and-trace requirements in India are accelerating demand for these intermediate configurations.
- Manual:Hand-fed enveloping stations persist in artisanal food processing units with sub-scale throughput requirements.
- Conveyor-Based:Belt-driven material handling modules serve price-sensitive food wrapping operations with intermittent production schedules.
Fully automatic configurations absorb the bulk of installed capacity; semi automatic systems are expanding most quickly in emerging pharmaceutical manufacturing corridors.
Technology:
Motion control selection determines operational expenditure profiles and regulatory compliance trajectories across European packaging corridors.
- Servo Drive:Programmable electromechanical architectures eliminate mechanical cam systems and reduce changeover downtime through software-defined motion profiles. Nordic food processing units prioritize these systems to align with EU Green Deal energy efficiency targets.
- Pneumatic:Compressed air actuation retains installed base in legacy Mittelstand manufacturing facilities where retrofit engineering costs delay modernization timelines.
- Hydraulic:High-force actuation serves heavy-load palletizing applications in paper packaging lines with substantial unit weights.
- Electromechanical:Hybrid architectures combining servo precision with mechanical redundancy anchor precision stacking systems for lithium-ion cell production in South Korea and Germany.
Servo drive platforms command the steepest expansion trajectory as energy efficiency regulations tighten; pneumatic systems retain defensive positions in mature installed bases.
Application:
End-use specifications dictate validation intensity and material compatibility requirements across divergent product protection standards.
- Paper Packaging:High-throughput lines in printing houses require film-wrapping systems with biodegradable material compatibility to satisfy EU packaging waste reduction frameworks.
- Food Wrapping:Hygienic design specifications and washdown-rated enclosures dominate procurement criteria for processing units facing FSSAI and EFSA compliance obligations.
- Pharmaceutical Bundling:Serialization-ready enveloping lines must integrate track-and-trace modules satisfying FDA enforcement and EMA guidance harmonization.
- Electronics Protection:Anti-static film handling and ESD-safe stacking precision serve lithium-ion cell and semiconductor packaging requirements.
Paper packaging deploys the largest installed machine base; pharmaceutical bundling is climbing the fastest on regulatory-driven replacement cycles.
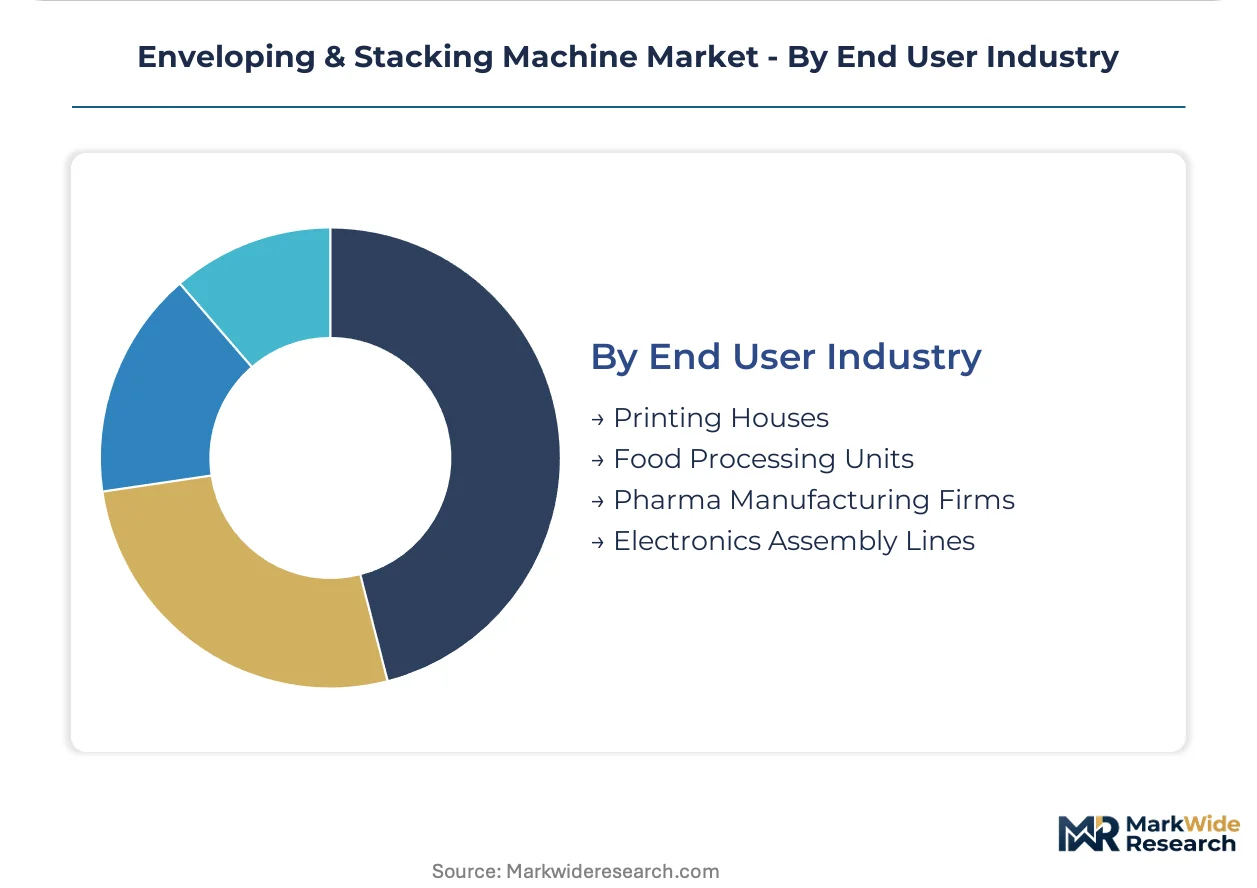
End User Industry:
Customer scale and vertical integration depth shape procurement negotiation leverage and aftermarket service attachment rates.
- Printing Houses:Consolidated buyers with high equipment density drive subscription-based predictive maintenance adoption through edge analytics platforms.
- Food Processing Units:Fragmented demand across Nordic and German markets favors third-party technical labor pools and digital spare parts procurement over OEM service contracts.
- Pharma Manufacturing Firms:Validation documentation burdens and CE-marking requirements compress supplier qualification timelines for contract manufacturing organizations.
- Electronics Assembly Lines:Tier-one battery manufacturers in Germany and South Korea specify precision stacking systems with vision-guided quality inspection integration.
Printing houses concentrate the highest value per installation; electronics assembly lines are gaining share fastest on battery cell format standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European demand for precision stacking systems as battery cell manufacturers cluster around Baden-Württemberg's automotive supply corridor. The city's Mittelstand fabricators are retrofitting legacy pneumatic lines with servo-drive architectures to meet EU Green Deal efficiency mandates.
Germany
Battery cell format standardization and pharmaceutical serialization mandates drive equipment refresh cycles across Stuttgart and Munich industrial zones. KBA machine safety standards coordinate with EMA guidance to compress CE-marking timelines for pan-European deployments. Bavarian contract manufacturers are modernizing enveloping lines to satisfy EU MDR track-and-trace requirements for export-bound pharma bundles.
United States
FDA Current Good Manufacturing Practice enforcement elevates validation documentation burdens for pharmaceutical bundling operations in New Jersey and North Carolina research triangles. The agency's track-and-trace rules force contract manufacturing organizations to automate terminal packaging workflows. Boston-area biotech clusters are deploying vision-guided stacking systems to minimize cleanroom labor exposure.
China
NMPA serialization requirements and dual carbon goals are restructuring procurement priorities across Yangtze River Delta electronics assembly corridors. SAMR standards harmonization accelerates servo-drive adoption in Shenzhen and Suzhou packaging hubs. Domestic manufacturers are scaling semi-automatic configurations for emerging pharma firms in Chengdu-Chongqing western development zones.
India
CDSCO track-and-trace regulations are emerging as pharmaceutical manufacturing expands across Maharashtra and Gujarat pharmaceutical clusters. FSSAI compliance obligations for food processing units in Haryana drive hygienic design specifications for washdown-rated enveloping equipment. Mumbai-Pune corridor contract manufacturers are qualifying semi-automatic lines with integrated serialization modules for export markets.
South Korea
MFDS pharmaceutical serialization mandates and METI-aligned battery safety standards concentrate precision stacking demand in Seoul Capital Area and Busan-Ulsan industrial belts. Tier-one lithium-ion manufacturers specify electromechanical platforms calibrated to prismatic cell dimensions. Daegu-Gyeongbuk machinery builders are localizing servo-drive component supply to reduce Japanese encoder dependency.
Enveloping & Stacking Machine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across automation tiers and validation documentation capabilities. The vendor base stratifies between fully automatic system integrators serving pharma serialization mandates and conveyor-based fabricators competing on price for food processing batch operations. Three archetypes dominate: electromechanical servo specialists, pneumatic legacy maintainers, and vision-guided robotics integrators. Competitive intensity centers on geographic expansion into Indian pharmaceutical corridors and portfolio diversification toward battery cell stacking applications.
Among European-headquartered precision equipment builders, ANDRITZ Sovema and Manz AG exemplify the servo-drive electromechanical archetype, while Shenzhen Better Technology occupies a position within the Asian semi-automatic conveyor tier. These three anchors illustrate how regional regulatory alignment—EU MDR serialization versus CDSCO emerging mandates—shapes competitive boundary definition across automation intensity levels.
| Leading Market Players |
|---|
| ANDRITZ Sovema |
| Zesar |
| Manz AG |
| Shenzhen Better Technology |
| Patel Material Handling Equipment |
| Semyung India |
| Shuttleworth |
| Soco System |
| Konecranes |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between CE-marked servo platforms and non-validated pneumatic systems splits procurement budgets across European pharma corridors and Asian batch operations. This bifurcation concentrates pricing power with electromechanical specialists serving FDA and EMA compliance mandates while compressing margins for conveyor-based fabricators in price-sensitive food processing tiers.
Pricing Analysis
Throughput-guarantee contracts anchor value-based pricing for fully automatic enveloping lines in German battery cell facilities. Three-tier pricing structure across premium, standard, and economy levels reflects validation documentation depth, with CE-FDA dual-certified configurations commanding substantial premiums over single-market alternatives. Cost compression in semi-automatic tiers is intensifying because Indian CDSCO-mandated serialization modules are commoditizing faster than expected. Contract manufacturing organizations exhibit highest price sensitivity; tier-one battery manufacturers show least.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shenzhen, and Seoul Capital Area orchestrate hub-and-spoke patterns for precision linear encoders and torque motors. Component supply draws from Japan, Germany, and South Korea, with high-precision motion control hardware resting on specialized electromechanical foundries. Single-source vulnerability concentrates in Japanese encoder specialists, exposing OEMs to extended fulfillment cycles. Distribution runs through authorized service depots co-located with battery manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around validation-capable electromechanical platforms as FDA and EMA documentation burdens force pneumatic legacy suppliers toward exit or acquisition.
For Market Incumbents: Lock in pharmaceutical bundling contracts through preemptive EU MDR serialization module integration before CDSCO mandates harden in India. Anchor aftermarket revenue through edge-analytics subscriptions for printing house predictive maintenance, defending against third-party technical labor pools in Nordic markets. Prioritize servo-drive component inventory buffers to offset Japanese encoder lead time volatility. For New Entrants and Emerging Players: Vision-guided robotic palletizing offers the most penetrable wedge for electronics assembly lines in South Korea and Germany where tier-one battery manufacturers seek quality inspection automation. Target Maharashtra and Gujarat pharmaceutical clusters with semi-automatic configurations featuring modular serialization upgrades. Pursue equipment-as-a-service models to bypass capital budget constraints at emerging Asian pharma manufacturing firms. For Investors and Strategic Acquirers: Re-rating potential sits with electromechanical servo specialists given EU AI Act risk classification clarity for autonomous vision systems. Five-to-ten year viability favors platforms with validated pharma documentation libraries and battery cell format calibration capabilities. Watch for MFDS and CDSCO serialization mandate synchronization as inflection indicator for emerging market equipment refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Drive Platform Standardization | Reduces changeover downtime for food processing units facing EU Green Deal efficiency targets. |
| Backward Integration into Motion Control Components | Mitigates Japanese encoder dependency for Korean and German battery cell equipment builders. |
| Pharma Serialization Module Certification | Secures FDA and EMA compliance positioning ahead of CDSCO mandate expansion. |
| Vision-Guided Robotics Acquisition | Accelerates quality inspection automation for lithium-ion cell palletizing in Stuttgart corridor. |
| Aftermarket Service Digital Platform Launch | Captures spare parts procurement shifting away from OEM contracts in Nordic food processing. |
Research Methodology
Trade association filings, customs shipment records, and regulatory submission databases formed the secondary backbone for this analysis. Primary interviews with packaging equipment procurement managers, plant engineers at battery manufacturing facilities, aftermarket service heads, and EMA regulatory consultants combined with secondary validation across KBA safety standards documentation and FDA Current Good Manufacturing Practice guidance. Bottom-up equipment shipment tallies and top-down end-use demand estimates were triangulated to anchor market sizing.
Historical trendline analysis of servo-drive adoption rates and pneumatic system replacement cycles informed projection modeling across the analysis window. Segmentation dimensions included automation tier, motion control architecture, end-use application, and regional regulatory cluster. CAGRs were derived from equipment refresh cycle timing, serialization mandate phase-in schedules, and battery cell production capacity expansion trajectories. Industry-specific forecast inputs incorporated EU AI Act implementation timelines and Green Deal packaging waste reduction compliance deadlines.
Several conditions sit outside the modeled scope, including speculative EU AI Act risk classification reversals, abrupt trade restrictions on Japanese motion control components, and pharmaceutical manufacturing facility closures unrelated to equipment obsolescence. Forecasts reflect assumptions about regulatory harmonization progress and technology substitution elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Paper Embossing Machine Market
Packaging Machinery
Shrink - Sleeve Wrapping Machinery Market
Packaging Machinery
Bagging Machine Market
Packaging Machinery
Wet Ink Coding Machines Market
Packaging Machinery
Automatic Liquid Filling Machines Market
Packaging Machinery
Induction Sealing Machine Market
Packaging Machinery
Straw Machine Market
Packaging Machinery
Air Cushion Machine Market
Packaging Machinery
Polyester Strapping Machines Market
Packaging Machinery
Global Volumetric Cup Fillers Market
Packaging Machinery
Puffer Machines Market
Packaging Machinery
Plastic Extrusion Equipment Market
Packaging Machinery
Screw Capping Machines Market
Packaging Machinery
Side Sealer Machines Market
Packaging Machinery
Molded Pulp Packaging Machines Market
Packaging Machinery
Global Form Fill Seal Machines Market