
 Fecal Pancreatic Elastase Testing Market | 2026-2036
Fecal Pancreatic Elastase Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Fecal Pancreatic Elastase Testing Market Foresight
Hospital procurement channels is reconfiguring as integrated delivery networks consolidate purchasing authority across regional health systems. ScheBo Biotech AG leverages its specialized immunoassay portfolio to anchor relationships with European reference laboratories. Immundiagnostik AG competes through its calibrated ELISA platforms that sustain repeat orders from academic medical centers. R-Biopharm AG controls distribution in German-speaking markets through direct sales teams that navigate complex reimbursement pathways.
Fecal pancreatic elastase testing measures the concentration of elastase-1 enzyme in stool samples, typically using monoclonal antibody-based immunoassay methods with detection thresholds near 15 micrograms per gram to assess exocrine pancreatic function. The primary commercial purpose is non-invasive differentiation between pancreatic and non-pancreatic causes of malabsorption in patients with chronic gastrointestinal symptoms. Test kits and reagents command the largest revenue share within product type segments due to recurring consumable demand tied to chronic disease monitoring protocols. Diagnostic laboratories represent the fastest-expanding end user channel as centralized testing absorbs volume from smaller clinic-based workflows. Immunoassay technology leads the technology landscape while chemiluminescent platforms attract investment for higher-throughput automation.
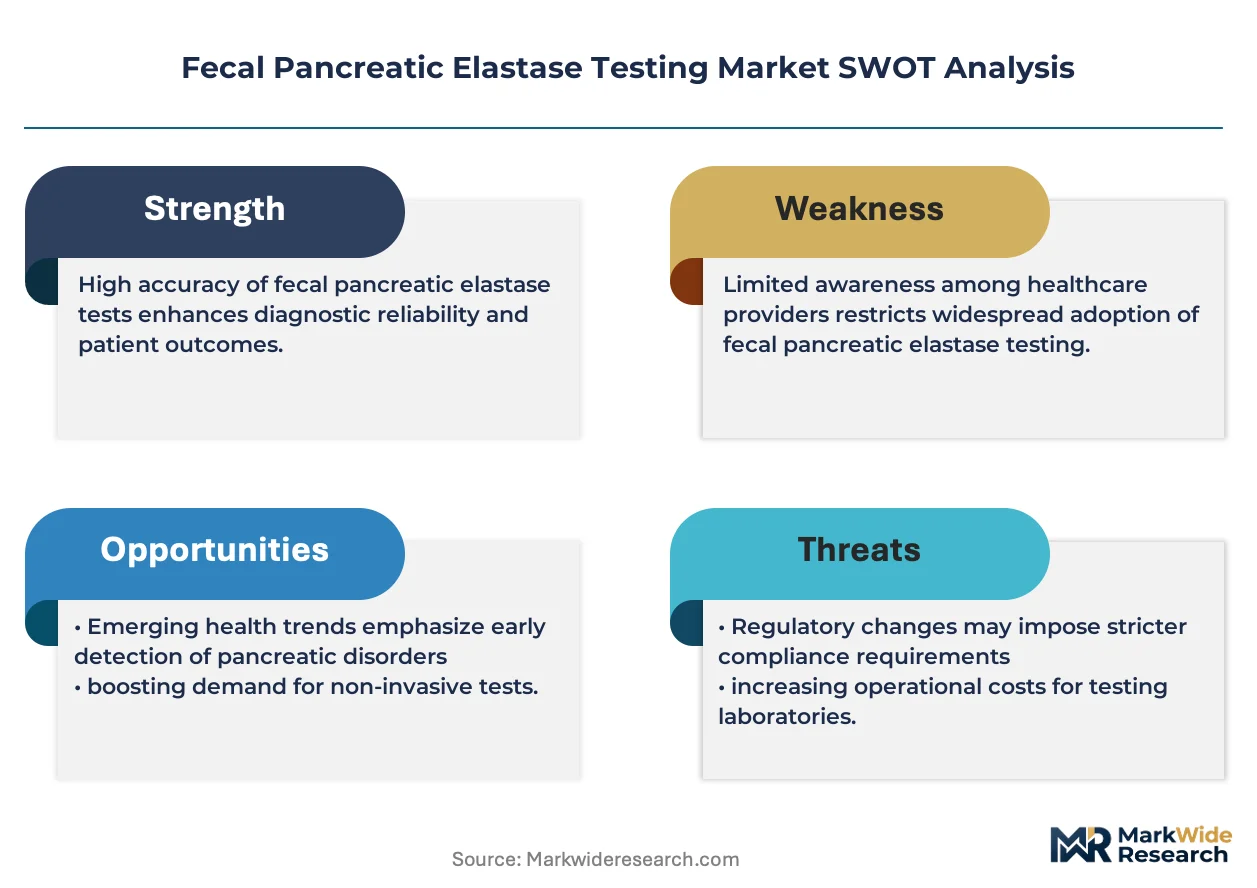
The FDA oversees analytical validity requirements for fecal elastase assays marketed as clinical diagnostic tools in the United States, while the EMA's in vitro diagnostic regulation framework governs CE marking obligations across European member states. ISO 13485 quality management standards shape manufacturing compliance for kit producers seeking multi-regional market access. Stakeholders must monitor evolving IVD classification thresholds that could reclassify quantitative elastase tests and trigger additional clinical evidence requirements.
Market Dynamics
Integrated delivery networks are consolidating hospital procurement authority across regional health systems, compressing vendor relationships and forcing assay suppliers to demonstrate cost-per-test economics at scale rather than clinical differentiation alone.
Growth Catalysts
- IVDR Compliance Deadlines:The EU's In Vitro Diagnostic Regulation is accelerating laboratory upgrades to CE-IVD certified quantitative platforms, creating replacement demand across European reference networks.
- Chronic Pancreatitis Prevalence:Rising alcohol-related and idiopathic pancreatic disease burdens in Germany and Japan are expanding routine monitoring protocols in gastroenterology clinics.
- ELISA Automation:Chemiluminescent immunoassay modules are displacing manual workflows in high-throughput diagnostic laboratories, reducing technician time per sample.
Market Restraints
- Monoclonal Antibody Supply Concentration:Critical reagent inputs concentrate among three specialized biologics suppliers, exposing kit manufacturers to batch-to-batch variability and allocation risk.
- Reimbursement Compression:Germany's EBM fee schedule and US Medicare clinical laboratory fee schedule have frozen elastase test pricing, squeezing margin on consumable-heavy business models.
- Serological Substitutes:Fecal calprotectin and fecal immunochemical tests compete for the same stool sample logistics, diverting laboratory capital from pancreatic function assays.
Strategic Opportunities
- Point-of-Care Expansion:India and Brazil present underpenetrated demand where decentralized clinic networks lack access to centralized laboratory infrastructure.
- Multi-Analyte Panels:Convergence of elastase quantification with fecal fat and calprotectin on single automated platforms creates bundled testing economics.
- Digital Pathway Integration:Direct-to-laboratory patient collection kits with smartphone-enabled sample tracking are opening pharmacy and e-commerce distribution channels.
Industry Challenges
- IVDR Technical Documentation:The EU's expanded clinical evidence requirements for Class C devices are extending certification timelines and consuming regulatory affairs capacity.
- Laboratory Information System Interoperability:Automated result transmission to electronic health records requires HL7 FHIR integration investment that mid-sized kit vendors struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fecal Pancreatic Elastase Testing Market |
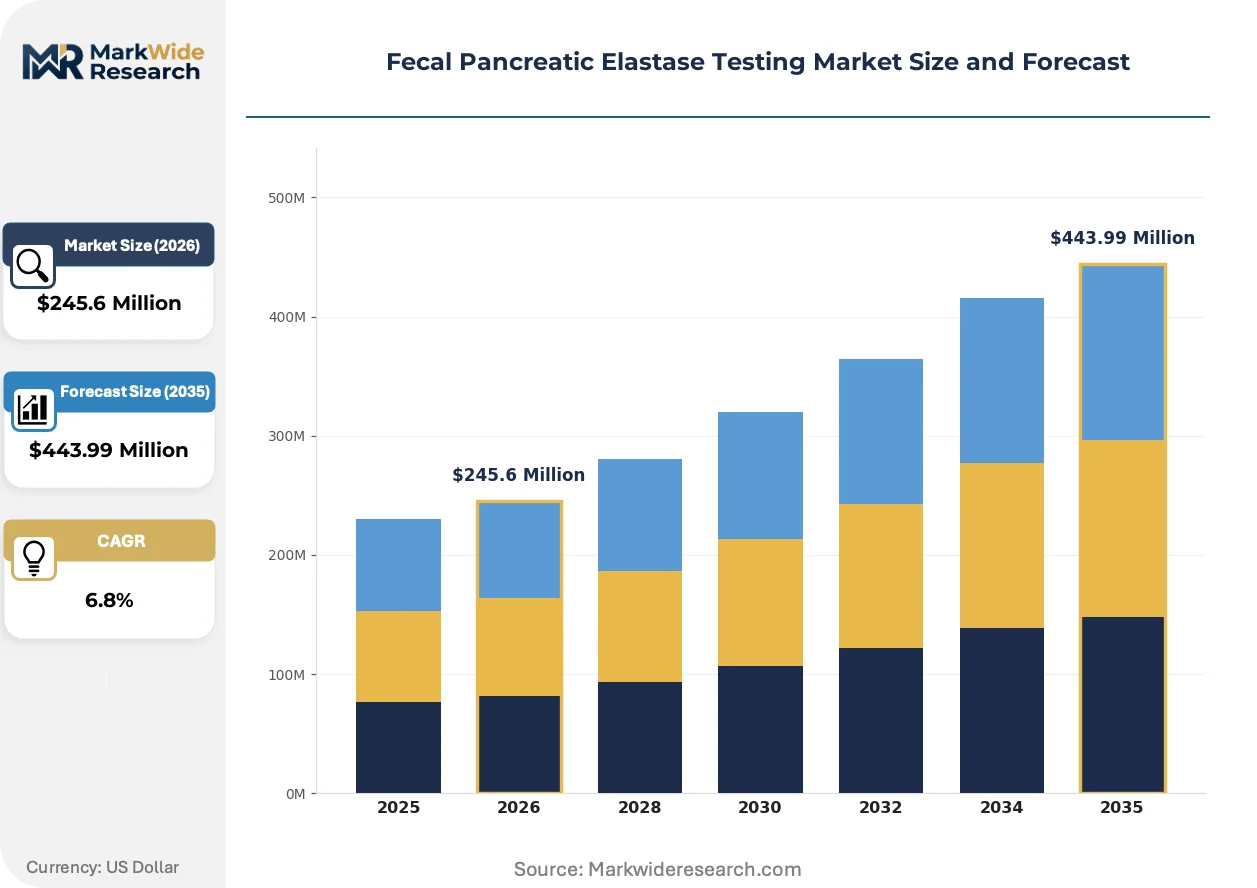
| Market Size in 2026 | $245.6 Million |
| Market Size in 2035 | $443.99 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Kits, Analyzers, Reagents, Consumables End User: Hospitals, Diagnostic Laboratories, Clinics, Research Institutions Technology: Immunoassay, ELISA, PCR, Chemiluminescent Assay Application: Chronic Pancreatitis, Cystic Fibrosis, Malabsorption Disorders, Screening |
| Companies Covered | ScheBo Biotech AG, Immundiagnostik AG, R-Biopharm AG, Verisana Laboratories, DRG Instruments GmbH, DiaSorin, BÜHLMANN Laboratories AG, CerTest Biotec, BioServUK Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fecal Pancreatic Elastase Testing Market Shifts & Advancements
Automation and regulatory harmonization are compressing the competitive window for manual assay platforms while opening premium positioning for integrated diagnostic systems that streamline pre-analytical handling.
Quantitative immunoassay platforms with barcode sample tracking and automated pipetting are digitizing pre-analytical workflow documentation, eliminating transcription errors that plague manual ELISA processing. Academic medical centers in Germany and the Netherlands are deploying these systems to meet ISO 15189 accreditation requirements for end-to-end traceability. The technology is digitizing quality control record-keeping, compressing audit preparation time from weeks to hours.
The EU Medical Device Regulation's post-market surveillance requirements are mandating annual safety update reports and trend analysis for IVD manufacturers. This policy is forcing kit producers to invest in vigilance infrastructure or outsource to specialized regulatory service providers. Small-to-mid immunoassay specialists without legacy quality management systems face disproportionate compliance cost absorption.
Hospital procurement committees are consolidating vendor contracts under three-year exclusive supply agreements with volume-tier pricing. This behavioral shift is displacing open-source reagent purchasing that allowed laboratories to arbitrage between kit manufacturers. The concentration is most visible in German-speaking markets where purchasing cooperatives like the Rhön-Klinikum group negotiate system-wide elastase assay supply.
Fecal Pancreatic Elastase Testing Market Segmentation
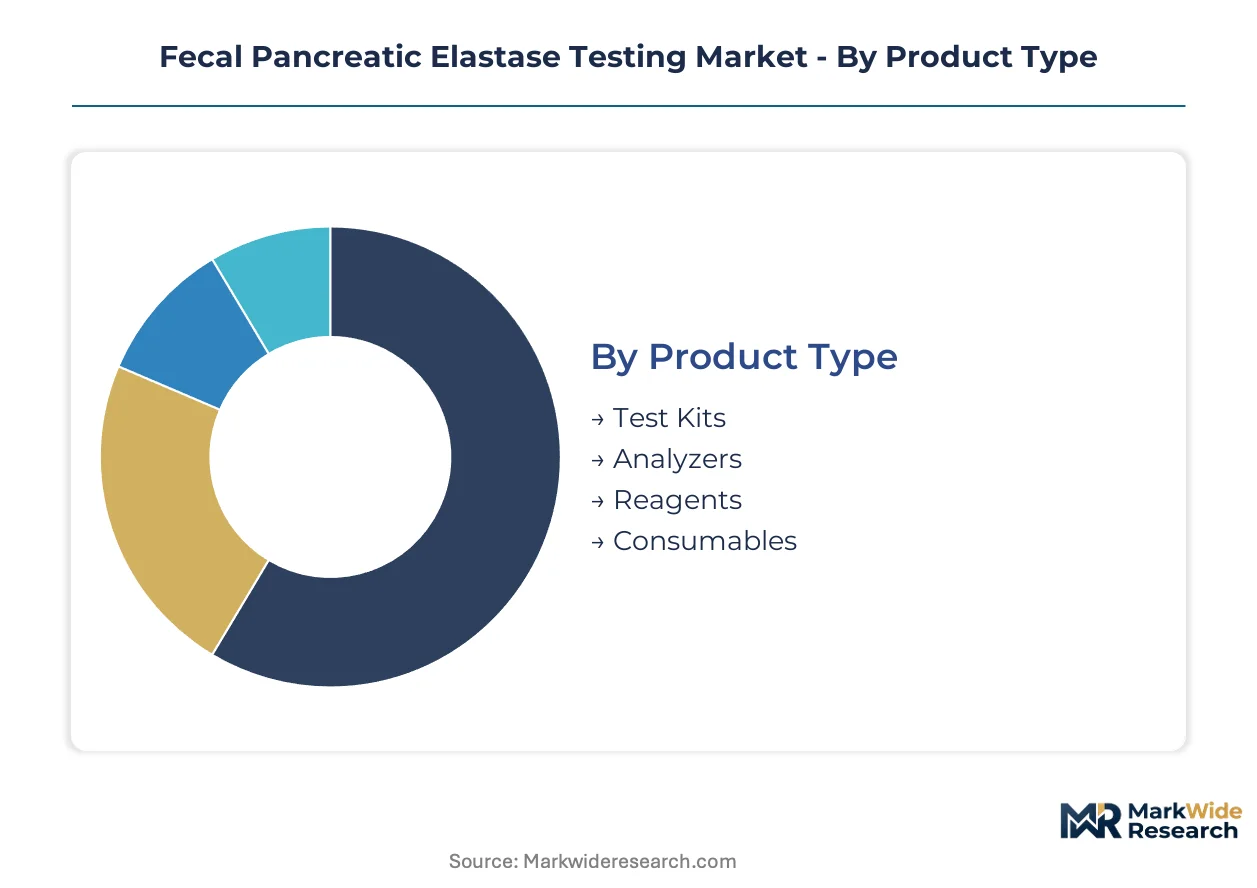
Segmentation in fecal pancreatic elastase testing reveals distinct procurement behaviors across product categories and end-user channels. Test kit economics differ sharply between high-throughput reference laboratories and low-volume clinic settings. Technology choices cascade through regulatory compliance requirements and automation infrastructure investments.
Product Type:
Mature consumable categories dominate recurring revenue while emerging analyzer platforms reshape capital deployment cycles.
- Test Kits:Monoclonal antibody-based immunoassay cartridges with standardized calibrator ranges ship in unit-dose formats for single-patient use. German diagnostic laboratories absorb the highest kit volumes as regional purchasing cooperatives negotiate multi-year supply agreements with tiered pricing structures.
- Reagents:Bulk enzyme conjugates and wash buffers constitute the highest-margin recurring revenue stream within kit manufacturing. Supply concentration among three specialized biologics suppliers in Switzerland and Germany exposes manufacturers to batch-to-batch variability risks.
- Analyzers:Automated ELISA processing platforms with barcode tracking and liquid handling robotics.
- Consumables:Pipette tips, microplate seals, and sample collection tubes with stabilizing buffers.
Test kits handle the majority of throughput; analyzers are gaining share fastest as laboratories automate manual workflows.
End User:
Customer type determines purchasing authority structure and technical support requirements.
- Diagnostic Laboratories:Centralized reference networks process thousands of elastase samples monthly using chemiluminescent immunoassay modules integrated with laboratory information systems. Academic medical centers in the Netherlands and Germany drive adoption of ISO 15189-accredited platforms with full audit trail documentation.
- Hospitals:Integrated delivery networks consolidate procurement across regional health systems under three-year exclusive supply contracts. Rhön-Klinikum and similar German purchasing cooperatives compress vendor relationships to two or three approved suppliers per assay category.
- Clinics:Smaller gastroenterology practices with limited on-site processing capability.
- Research Institutions:Academic centers conducting exocrine pancreatic function studies using custom assay configurations.
Diagnostic laboratories handle the majority of throughput; clinics are expanding most quickly as point-of-care models penetrate underserved markets.
Technology:
Platform maturity spans from established manual methods to capital-intensive automated systems.
- Immunoassay:Monoclonal antibody-based quantitative detection with microplate or cartridge formats remains the clinical standard. FDA-cleared and CE-IVD labeled platforms from established manufacturers anchor purchasing decisions in US and European hospital systems.
- ELISA:Enzyme-linked immunosorbent assay protocols with 96-well microplate processing and spectrophotometric readout. Manual workflows persist in mid-sized European laboratories lacking capital for chemiluminescent automation upgrades.
- Chemiluminescent Assay:Acridinium ester or alkaline phosphatase signal amplification with higher sensitivity and throughput. Random-access analyzers from Roche and Abbott displace batch-mode ELISA in German reference laboratories seeking technician time reduction.
- PCR:Nucleic acid amplification methods for genetic pancreatitis markers alongside elastase quantification.
Immunoassay handles the majority of throughput; chemiluminescent assay platforms are climbing the fastest on automation investment cycles.
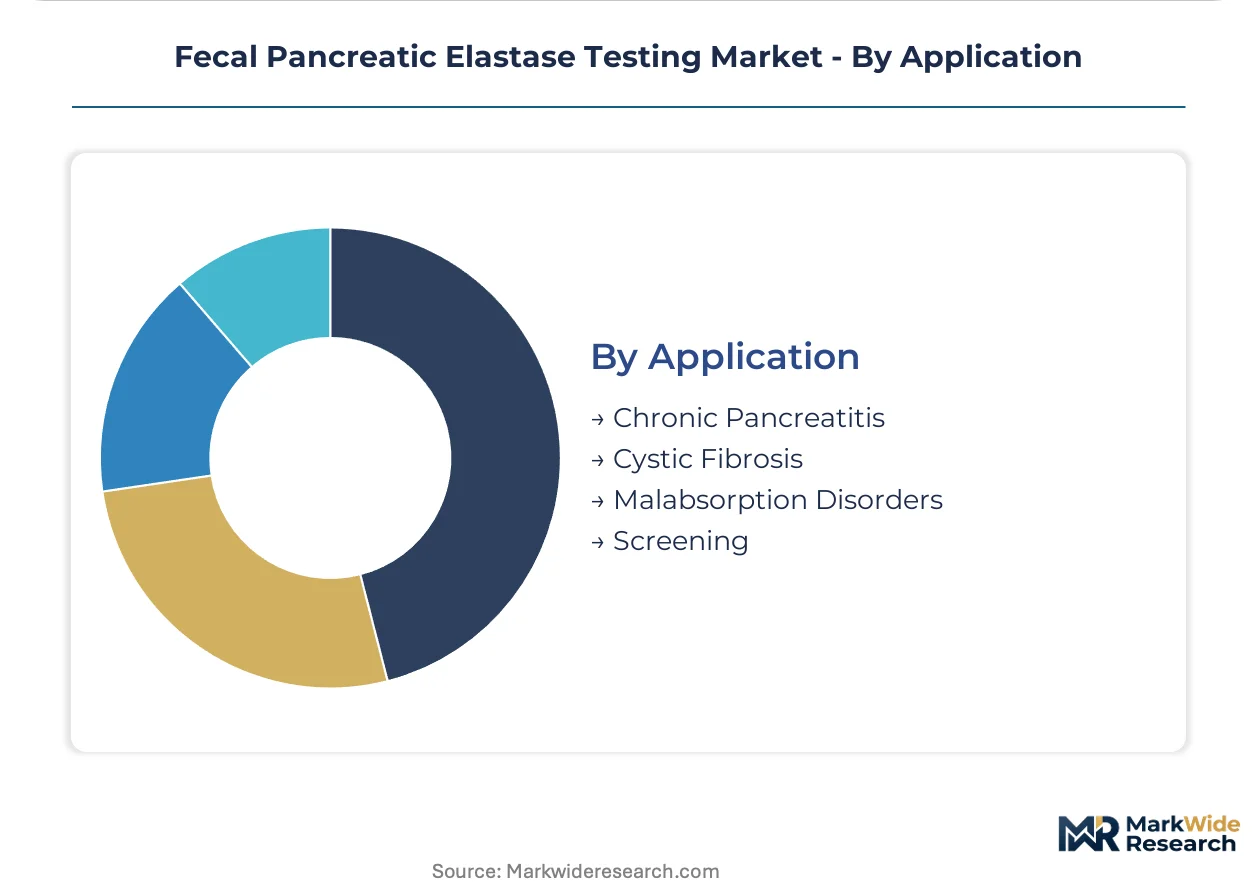
Application:
Disease indication drives testing frequency and reimbursement pathway complexity.
- Chronic Pancreatitis:Longitudinal monitoring of exocrine function in patients with alcohol-related or idiopathic disease. German gastroenterology networks operate dedicated pancreatic clinics with quarterly elastase testing protocols tied to enzyme replacement therapy titration.
- Malabsorption Disorders:Differential diagnosis between pancreatic and non-pancreatic causes of steatorrhea and weight loss. Primary care networks in Japan use elastase as a first-line screen before committing patients to invasive endoscopic procedures.
- Cystic Fibrosis:Pediatric and adult screening for pancreatic insufficiency in genetically confirmed patients.
- Screening:Asymptomatic population testing in high-risk cohorts with family history.
Chronic pancreatitis handles the majority of throughput; malabsorption disorders are expanding most quickly as primary care screening protocols standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's EBM fee schedule and Japan's aging gastroenterology protocols are concentrating procurement authority in integrated delivery networks across both markets. The FDA's clinical laboratory improvement amendments and the EU's In Vitro Diagnostic Regulation are reshaping quality benchmarks in North America and Europe. Brazil and India's decentralized clinic networks present underpenetrated demand where point-of-care models lack centralized laboratory infrastructure.
Germany
Specialized gastroenterology networks in Bavaria and Baden-Württemberg operate dedicated pancreatic clinics with quarterly elastase testing protocols. The EBM fee schedule has frozen test pricing, compressing margins on consumable-heavy business models. The Rhön-Klinikum purchasing cooperative negotiates system-wide supply agreements that consolidate vendor relationships to two or three approved suppliers per assay category.
United States
Integrated delivery networks across the Midwest and Southeast are consolidating hospital procurement authority under three-year exclusive supply contracts. The FDA's analytical validity requirements for fecal elastase assays marketed as clinical diagnostic tools shape quality benchmarks. Academic medical centers in Boston and Houston drive adoption of automated platforms with full audit trail documentation tied to Medicare reimbursement pathways.
Japan
Primary care networks in Tokyo and Osaka use elastase as a first-line screen before committing patients to invasive endoscopic procedures. METI's medical device reimbursement frameworks govern pricing for pancreatic function diagnostics. Rising alcohol-related and idiopathic pancreatic disease burdens are expanding routine monitoring protocols in Kansai region gastroenterology clinics.
Brazil
Decentralized clinic networks in São Paulo and Minas Gerais lack access to centralized laboratory infrastructure for quantitative elastase assays. ANVISA's in vitro diagnostic registration requirements create regulatory barriers for imported test kits. Private diagnostic chains in Rio de Janeiro are deploying chemiluminescent platforms to capture volume from fragmented clinic-based workflows.
India
Specialty gastroenterology practices in Maharashtra and Karnataka process limited on-site volumes due to capital constraints for automated systems. CDSCO's medical device rules govern import licensing for immunoassay platforms. Corporate hospital chains in Delhi-NCR are consolidating reference laboratory networks to absorb testing volume from smaller clinic-based operations.
Fecal Pancreatic Elastase Testing Market Competitive Landscape
On the supply side, the industry is consolidating around three specialized immunoassay manufacturers with entrenched relationships in European reference laboratories. The competitive structure fragments into tiered positioning: premium-tier suppliers with full regulatory dossiers, mid-tier regional specialists with partial CE marking, and emerging entrants targeting price-sensitive markets. Dominant competitive moves include multi-year exclusive supply agreements with purchasing cooperatives and backward integration into critical monoclonal antibody reagent production.
Within the specialized European tier, ScheBo Biotech AG, Immundiagnostik AG, and R-Biopharm AG occupy positions anchored by calibrated ELISA platforms and direct sales teams navigating complex reimbursement pathways. These Germany-based entities exemplify the archetype of regulatory-heavy specialists with captive distribution in German-speaking markets. Their positioning reflects the broader industry pattern where geographic proximity to reference laboratory clusters determines procurement relationships more than price differentiation alone.
| Leading Market Players |
|---|
| ScheBo Biotech AG |
| Immundiagnostik AG |
| R-Biopharm AG |
| Verisana Laboratories |
| DRG Instruments GmbH |
| DiaSorin |
| BÜHLMANN Laboratories AG |
| CerTest Biotec |
| BioServUK Ltd. |
| Others |
Supply & Pricing Matrix
The Basel-Zurich corridor anchors monoclonal antibody production for fecal elastase immunoassays, concentrating upstream biologics capacity among three specialized suppliers whose batch allocation decisions cascade directly into kit manufacturer pricing power. This geographic concentration of critical reagent inputs creates asymmetric leverage where supply constraints transmit immediately to downstream margin compression.
Pricing Analysis
Certification level creates the primary spread across the fecal pancreatic elastase testing landscape, with FDA-cleared and CE-IVD labeled platforms commanding substantial premiums over research-use-only alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects the divergence between automated chemiluminescent systems, calibrated ELISA workflows, and manual batch processing. Cost compression in the standard tier is intensifying because Germany's EBM fee schedule has frozen reimbursement rates, squeezing consumable-heavy business models. Academic medical centers exhibit the lowest price sensitivity due to ISO 15189 accreditation requirements, while smaller clinic networks in emerging markets prioritize per-test economics over traceability features.
Supply Chain Analysis
Monoclonal antibody feedstock draws from Switzerland, Germany, and Austria, where specialized biologics suppliers concentrate production of enzyme conjugates and capture reagents. Critical inputs hinge on hybridoma cell line maintenance, serum-free media formulations, and affinity-purified immunoglobulin fractions. Single-source vulnerability permeates the antibody supply layer, as kit manufacturers lack qualified secondary suppliers for validated clone lines. Distribution runs through direct sales teams in German-speaking markets and diagnostic distributor networks in North America and Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fecal pancreatic elastase testing sits in early-cycle expansion as point-of-care models penetrate clinic networks in India and Brazil where centralized laboratory infrastructure remains underdeveloped. This geographic white space, combined with multi-analyte panel convergence, sustains penetration tailwinds independent of mature market reimbursement dynamics.
For Market Incumbents: Entrench procurement relationships through multi-year exclusive supply agreements with integrated delivery networks like Rhön-Klinikum, while backward integration into monoclonal antibody production defends against batch-to-batch variability risks from Swiss and German biologics suppliers. IVDR technical documentation requirements for Class C devices consume regulatory affairs capacity that smaller competitors cannot resource, creating a certification moat around established CE-IVD portfolios. For New Entrants and Emerging Players: Establish a beachhead in decentralized clinic networks across Maharashtra and São Paulo where capital constraints exclude automated platform competition. Point-of-care quantitative formats with smartphone-enabled sample tracking open pharmacy and e-commerce distribution channels that bypass entrenched hospital procurement committees. Partner with regional diagnostic chains to embed test kits within existing stool sample logistics rather than building standalone infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a consumable-recurring archetype play because chronic pancreatitis monitoring protocols generate quarterly testing cadences tied to enzyme replacement therapy titration. Acquisition targets should display captive monoclonal antibody supply or validated IVDR technical documentation, with CDSCO import licensing progress in India serving as the inflection signal for emerging market traction.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVD Certification Pathway | Accelerates laboratory upgrade cycles across European reference networks ahead of IVDR deadlines. |
| Multi-Analyte Panel Development | Converges elastase with fecal calprotectin and fat quantification on single automated platforms. |
| Point-of-Care Format Launch | Captures volume from decentralized clinic networks in Brazil and India lacking central lab access. |
| Backward Integration into Antibody Supply | Reduces batch-to-batch variability exposure from concentrated Swiss and German biologics suppliers. |
| Digital Pathway Integration | Enables direct-to-laboratory patient collection with smartphone-enabled sample tracking. |
Research Methodology
The analysis maps immunoassay technology tiers, end-user procurement channels, and geographic regulatory clusters, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and diagnostic laboratory directors. Primary intelligence combines structured interviews with secondary validation from FDA 510(k) filings, EMA IVDR technical documentation databases, CMS Medicare clinical laboratory fee schedules, and German EBM reimbursement catalogs. Bottom-up test volume modeling and top-down market sizing triangulate through purchasing cooperative contract disclosures and regional gastroenterology network protocol documentation.
Forecast assumptions hold fixed the IVDR compliance deadline structure and current EBM/Medicare reimbursement levels while varying automation adoption curves and point-of-care penetration rates across emerging markets. Segmentation dimensions span product type, technology platform, end-user channel, disease application, and regional regulatory framework. CAGRs derive from logistic diffusion modeling of chemiluminescent platform displacement and elasticity-adjusted volume responses to pricing compression. Industry-specific inputs include quarterly testing protocol frequency in German pancreatic clinics and stool sample logistics consolidation patterns in Japanese primary care networks.
Sensitivities concentrate around IVDR classification threshold revisions that could reclassify quantitative elastase tests and trigger additional clinical evidence requirements, as well as monoclonal antibody supply disruptions from Swiss biologics manufacturers. Forecasts reflect documented assumptions regarding reimbursement stability and automation capital expenditure cycles. Cross-checking against hospital procurement database benchmarks and GPO contract award disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Minimal Residual Disease Testing Market
Testing Services
Global Vitamin D Testing Market
Testing Services
Breath Biopsy Testing Market
Testing Services
Ferritin Testing Market
Testing Services
Global Molecular Quality Controls Market
Testing Services
Bimetallic Thermometer Market
Testing Services
Biological Safety Testing Products and Services Market
Testing Services
Blood Borne Testing Market
Testing Services
Medical Device Testing, Inspection, and Certification Market
Testing Services
Arthropod-Borne Viral Infections Testing Market
Testing Services
Global Efficacy Testing Market
Testing Services
Viral Vector Integrity and Potency Analytics Test Instruments Market
Testing Services
Vaginal Panel Testing Market
Testing Services
Global Specimen Validity Testing Market
Testing Services
Urine Testing Cups Market
Testing Services
Platelet Function Test Market