
 Anti-Shock Trouser Market | 2026-2036
Anti-Shock Trouser Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Shock Trouser Market Analysis
Emergency medical technicians are unwinding historical reliance on hospital-only procurement of anti-shock trousers, shifting volume toward field-deployable units. Medtronic leverages its trauma-systems distribution network to capture pre-hospital demand. Smiths Medical anchors European tender channels through specialized emergency-care divisions. Cardinal Health competes on consolidated purchasing contracts with integrated health networks.
Anti-shock trousers are pneumatic compression garments engineered to apply circumferential pressure to the lower extremities, typically constructed with reinforced nylon bladders capable of sustaining inflation pressures sufficient to reverse venous blood flow toward the core. Their primary purpose is to stabilize patients experiencing hypovolemic shock by autotransfusing pooled blood from the legs to critical organs. Nylon-based constructions dominate institutional procurement due to superior burst strength and repeat sterilization tolerance, while cotton blends occupy cost-sensitive training and civilian sectors. Padded protection variants command premium positioning in motor sports and tactical applications where blunt-force trauma coexists with hemorrhage risk.
The FDA regulates anti-shock trousers as Class II medical devices requiring 510(k) premarket notification, while the EU MDR mandates notified-body conformity assessment for pneumatic tourniquet-classified products. These frameworks elevate barrier costs for new entrants and compel established manufacturers to maintain dual-quality management systems. Stakeholders must monitor evolving harmonization between FDA and MDR clinical-evidence requirements to preserve cross-Atlantic market access without duplicative testing expenditures.
Market Dynamics
Emergency medical services procurement is pivoting toward field-deployable anti-shock trousers as pre-hospital hemorrhage protocols tighten, compressing traditional hospital-centric supply chains while elevating pneumatic compression garment specifications for austere environments.
Growth Catalysts
- EU MDR compliance mandates:Notified-body conformity assessment for Class IIa pneumatic devices is consolidating quality standards, advantaging manufacturers with established technical documentation.
- Motor sports trauma protocols:Fédération Internationale de l'Automobile safety regulations are mandating padded protection variants at professional racing circuits.
- Nylon bladder engineering:Reinforced polymer constructions capable of sustaining autotransfusion pressures are displacing cotton blends in institutional tenders.
Market Restraints
- Dual-quality management burden:FDA 510(k) and EU MDR parallel compliance requires redundant clinical evidence packages, elevating fixed costs for cross-Atlantic market access.
- Sterilization cycle degradation:Cotton-blend constructions exhibit accelerated material fatigue under gamma and steam sterilization, limiting reuse economics in high-throughput emergency departments.
- Substitute hemorrhage control:Junctional tourniquet systems and resuscitative endovascular balloon occlusion are capturing critical trauma cases previously routed to pneumatic compression.
Strategic Opportunities
- Tactical military applications:Special operations forces procurement channels in NATO member states are specifying integrated blunt-force protection for combat casualty care.
- Training sector cost optimization:Civilian emergency response academies present volume potential for simplified cotton-blend variants with reduced pressure specifications.
- Harmonized FDA-MDR pathways:Emerging mutual recognition frameworks for pneumatic medical devices could collapse duplicate testing expenditures for qualified manufacturers.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in pneumatic pressure dynamics and trauma physiology remains concentrated at legacy device manufacturers.
- Legacy inventory integration:Health systems with substantial installed bases of pre-MDR certified garments face complex field-upgrade logistics and documentation reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Shock Trouser Market |
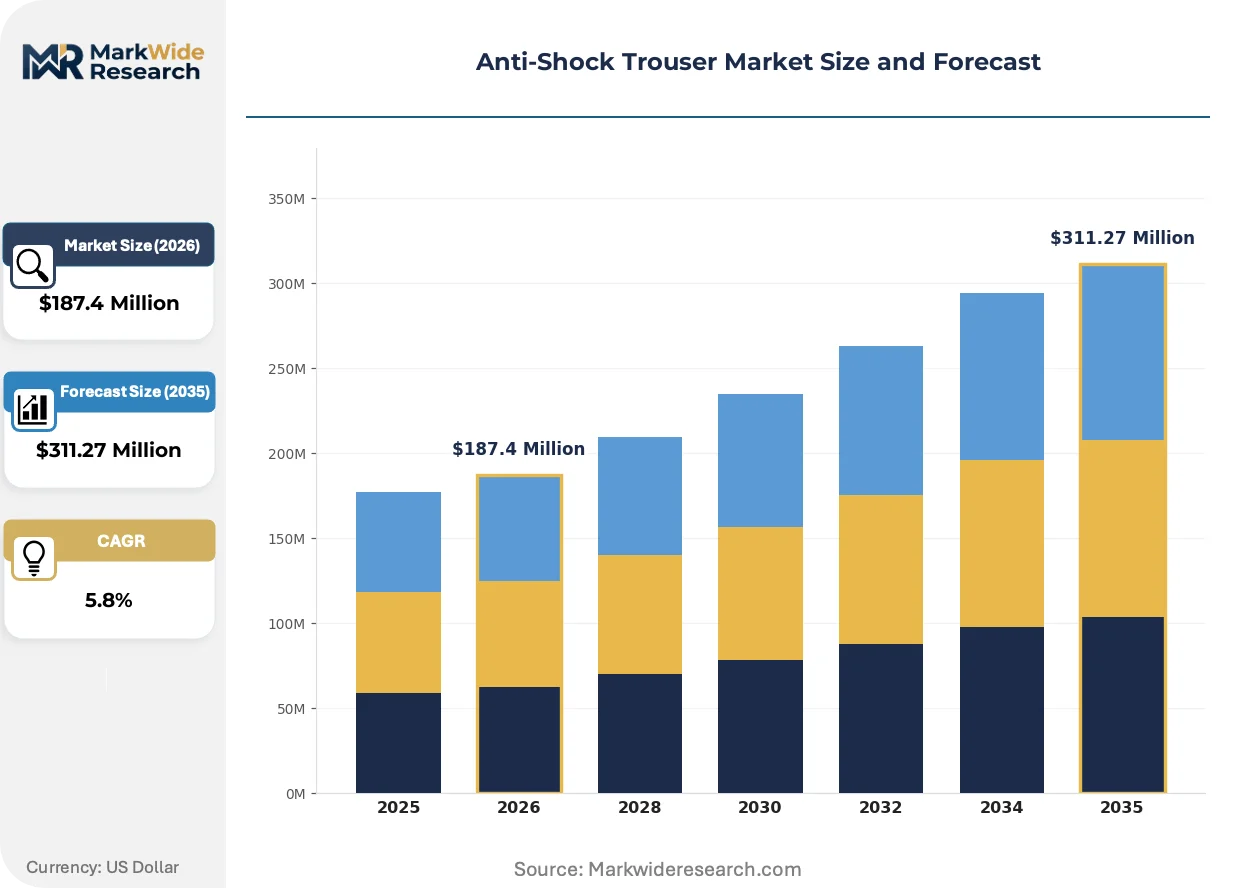
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Kevlar, Nylon, Polyester, Cotton End User: Construction Workers, Motorcyclists, Outdoor Enthusiasts, Sports Players Feature: Padded Protection, Water Resistant, Breathable Design, Thermal Insulation Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesale |
| Companies Covered | Medtronic, Smiths Medical, Allied Medical LLC, Becton Dickinson, Cardinal Health, Omni International, Philips Healthcare, Teleflex, Laerdal Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Shock Trouser Market Emerging Trajectories
Anti-shock trouser engineering is fragmenting across performance tiers as end-use specifications diverge between austere military deployment, civilian emergency medical services, and institutional hospital settings.
Smart pressure monitoring is decomposing traditional mechanical inflation systems. Pneumatic garments with integrated transducer feedback are penetrating special operations and air medical transport segments where real-time hemodynamic data guides field intervention. This capability compression is collapsing the gap between pre-hospital stabilization and trauma bay monitoring, enabling protocol standardization across care transitions.
EU MDR clinical evidence requirements are tightening post-market surveillance obligations for pneumatic tourniquet-classified devices. Manufacturers must now maintain active implantable-equivalent vigilance systems, compelling investment in European authorized representative infrastructure and periodic safety update reporting. German and French notified bodies are processing conformity assessments with extended timelines, delaying new entrant certification.
Consolidated purchasing contracts are compressing supplier fragmentation in North American health networks. Integrated delivery systems are unbundling device procurement from legacy distributor relationships, directly negotiating multi-year pneumatic garment supply agreements with performance guarantees. This channel rationalization is most advanced in United States regional trauma consortiums where standardization drives volume concentration.
Anti-Shock Trouser Market Segmentation
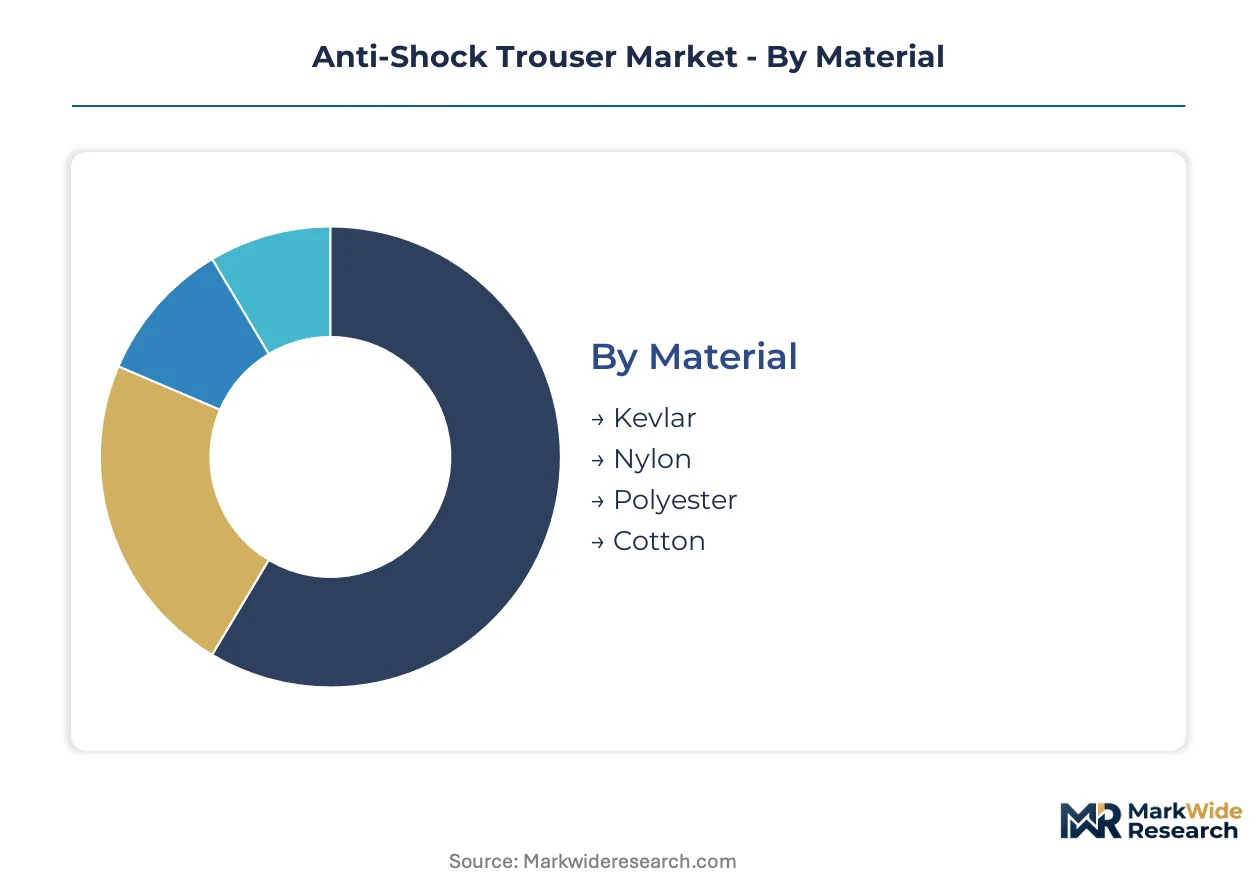
Anti-shock trouser procurement fragments across material specifications, end-user risk profiles, and channel economics. Each segmentation axis carries distinct regulatory weight and margin structure.
Material:
FDA 510(k) and EU MDR classify pneumatic compression garments by material burst strength and biocompatibility, elevating synthetic polymers over natural fibers in institutional tenders.
- Nylon:Reinforced polymer bladders sustain autotransfusion pressures exceeding 100 mmHg while tolerating gamma sterilization cycles. German emergency medical services specify nylon constructions for field-deployable units under BfArM technical documentation requirements.
- Kevlar:Aramid fiber reinforcement integrates blunt-force protection with pneumatic compression. French tactical procurement channels specify Kevlar-nylon hybrids for special operations casualty care under ANSM Class IIa conformity pathways.
- Polyester:Cost-engineered alternative with moderate burst strength serves civilian training academies and volunteer emergency response units.
- Cotton:Natural fiber construction degrades under steam sterilization but occupies price-sensitive segments in developing market pre-hospital systems.
Established volume favors Nylon; emerging adoption favors Kevlar.
End User:
Risk exposure severity and reimbursement pathways determine specification tiers across occupational and recreational segments.
- Construction Workers:OSHA-compliant fall protection mandates drive demand for padded variants with integrated hip and femoral compression. United States workers compensation reimbursement channels consolidate purchasing through regional safety equipment distributors.
- Motorcyclists:Fédération Internationale de l'Automobile safety regulations mandate padded protection variants at professional racing circuits. Italian and Spanish motorsport federations are extending requirements to amateur competition licenses.
- Sports Players:Contact sport trauma protocols in Australian rugby and American football specify pneumatic compression for acute hemorrhage stabilization on-field.
- Outdoor Enthusiasts:Remote wilderness exposure drives retail demand for compact, self-inflation systems through specialty mountaineering channels.
Procurement concentration sits with Construction Workers; steepest expansion trajectory belongs to Motorcyclists.
Feature:
Functional differentiation aligns with deployment environment severity and duration of field use.
- Padded Protection:Multi-layer foam and pneumatic bladder integration addresses blunt trauma coexisting with hemorrhage risk. NATO special operations specifications require this configuration for combat casualty extraction.
- Water Resistant:Sealed bladder membranes maintain inflation integrity in maritime and flood rescue scenarios. United Kingdom Coast Guard tenders specify IPX7-rated constructions.
- Breathable Design:Moisture-wicking outer layers reduce thermal burden during extended wear in tropical emergency medical deployments.
- Thermal Insulation:Cold-climate variants incorporate aerogel or synthetic down layers for hypothermia prevention in alpine and arctic rescue operations.
Institutional procurement prioritizes Padded Protection; recreational channels favor Breathable Design.
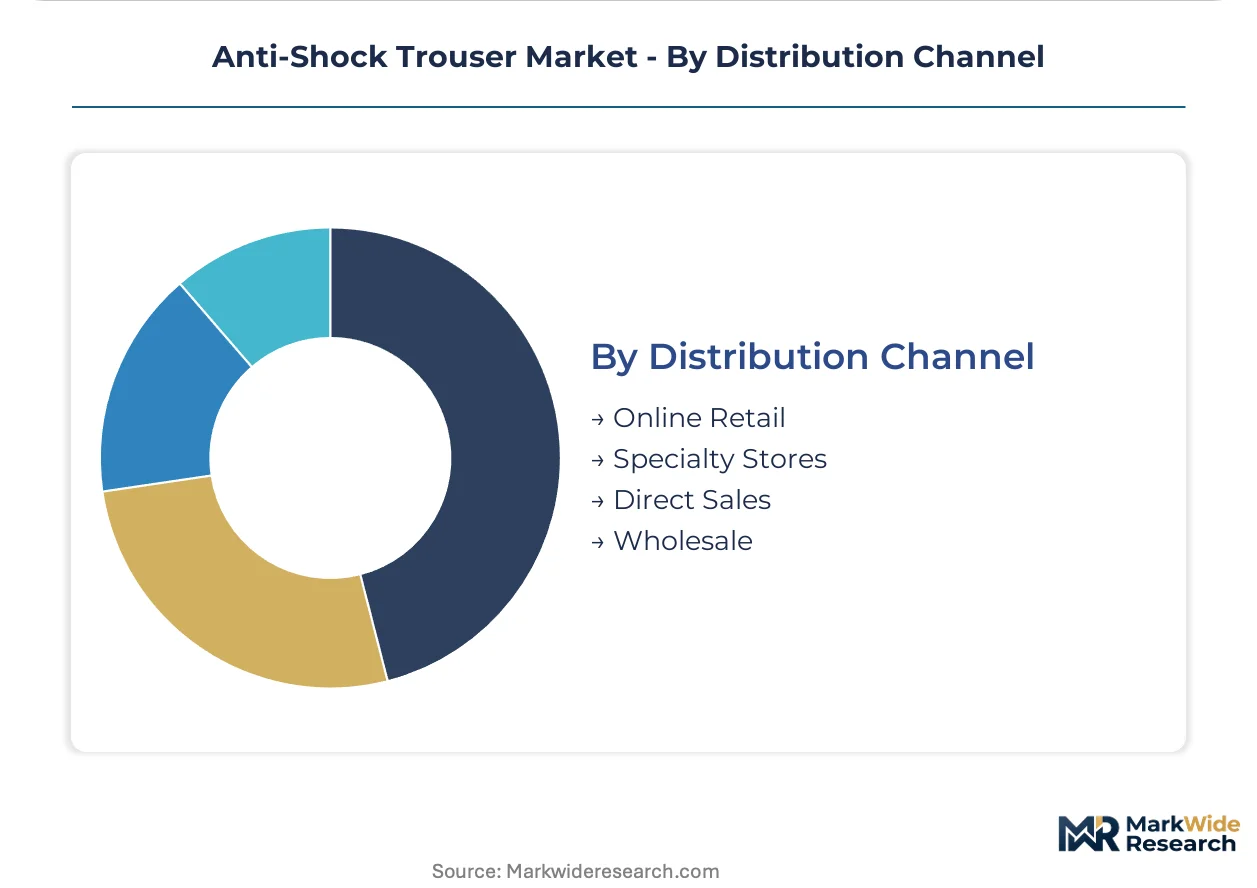
Distribution Channel:
Channel selection reflects buyer sophistication, volume scale, and technical support requirements.
- Direct Sales:Manufacturer field representatives negotiate multi-year supply agreements with integrated United States trauma consortiums and European hospital networks. EU MDR technical documentation transfer accompanies direct contracts.
- Specialty Stores:Emergency medical equipment retailers provide fitting services and training for municipal fire departments and volunteer rescue squads.
- Wholesale:Consolidated purchasing through group purchasing organizations captures standard nylon variants for high-throughput emergency departments.
- Online Retail:Direct-to-consumer channels serve individual motorcyclists and outdoor enthusiasts with simplified cotton-blend training variants.
Contract value concentrates in Direct Sales; volume growth flows through Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export pneumatic compression garments to United States trauma consortiums and French emergency medical services, establishing a trans-Atlantic trade corridor that channels technical documentation and regulatory compliance expertise alongside physical product flows.
United States
FDA 510(k) premarket notification requirements and OSHA-compliant fall protection mandates drive institutional procurement of reinforced nylon constructions. Regional trauma consortiums in Texas and California consolidate purchasing through integrated delivery networks, unbundling device procurement from legacy distributor relationships. Greater Boston anchors advanced pre-hospital hemorrhage protocol development, with Massachusetts General Hospital influencing field-deployable specifications nationwide.
Germany
BfArM technical documentation requirements and expanding emergency medical services fleets elevate demand for field-deployable nylon variants. The EU MDR notified-body conformity assessment process, administered through German certification bodies, extends timelines for new entrant market access. North Rhine-Westphalia concentrates manufacturing infrastructure, with Cologne-Düsseldorf industrial clusters supplying pneumatic bladder components to continental European tenders.
France
ANSM Class IIa conformity pathways and special operations casualty care procurement specifications favor Kevlar-nylon hybrid constructions. Motor sports trauma protocols mandated by national federations extend padded protection requirements to amateur competition circuits. Provence-Alpes-Côte d'Azur hosts tactical medical equipment testing facilities, with Nice-Sophia Antipolis clusters validating garment performance for NATO specifications.
United Kingdom
United Kingdom Coast Guard tenders specifying IPX7-rated water-resistant variants drive maritime rescue segment demand. Post-Brexit regulatory divergence from EU MDR creates parallel compliance obligations for manufacturers maintaining continental market access. London-Southeast concentrates emergency medical services headquarters procurement, with Thames Valley distribution networks channeling volume to municipal fire departments and volunteer rescue squads.
Japan
PMDA medical device registration requirements and aging population emergency response infrastructure investment expand institutional procurement. Contact sport trauma protocols in rugby and American football leagues specify pneumatic compression for acute hemorrhage stabilization. Kanto/Tokyo metropolitan emergency medical services standardize specifications, with Yokohama manufacturing clusters producing compact self-inflation systems for alpine and remote wilderness rescue operations.
Anti-Shock Trouser Market Vendor Landscape
Player mix skews toward diversified medical device conglomerates with established trauma-systems distribution networks. Market structure concentrates around three to five dominant suppliers capable of sustaining dual FDA-EU MDR quality management systems, with mid-tier specialists occupying niche tactical and training segments. Strategic archetypes include integrated health network contractors, emergency-care channel specialists, and military-tactical suppliers. Competitive moves center on consolidated purchasing contract capture and pre-hospital protocol standardization partnerships.
Within the diversified conglomerate tier, Medtronic, Smiths Medical, and Cardinal Health occupy positions representing distinct channel strategies. Medtronic exemplifies trauma-systems vertical integration, leveraging broad distribution infrastructure to capture field-deployable demand migration. Smiths Medical anchors European tender channels through specialized emergency-care divisions, maintaining technical documentation depth for BfArM and ANSM compliance pathways. Cardinal Health competes on consolidated purchasing contracts with integrated United States health networks, optimizing volume scale across standard nylon institutional variants.
| Leading Market Players |
|---|
| Medtronic |
| Smiths Medical |
| Allied Medical LLC |
| Becton Dickinson |
| Cardinal Health |
| Omni International |
| Philips Healthcare |
| Teleflex |
| Laerdal Medical |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements with integrated United States trauma consortiums lock in multi-year nylon bladder supply access while anchoring price visibility against raw material volatility. These contracts bundle technical documentation transfer with volume commitments, compressing spot market exposure for institutional procurement tiers.
Pricing Analysis
Current-generation smart pressure monitoring garments command substantial premiums over prior-generation mechanical inflation systems, while next-generation integrated hemodynamic feedback prototypes remain pre-commercial. Three-tier pricing structure across premium Kevlar-nylon hybrids, standard reinforced nylon, and economy cotton-blend variants reflects certification grade and sterilization cycle tolerance. Pricing pressure stems from consolidated purchasing contract concentration among United States regional trauma consortiums. Training academies and volunteer emergency response units exhibit highest price sensitivity, whereas NATO special operations procurement channels prioritize performance specifications over unit economics.
Supply Chain Analysis
Germany and the United States anchor pneumatic bladder component manufacturing, with North Rhine-Westphalia industrial clusters feeding continental European tenders and Massachusetts-based trauma-systems suppliers serving domestic consortiums. Raw material dependencies center on medical-grade nylon polymers, aramid fiber reinforcements, and precision inflation valve assemblies. Single-source vulnerability concentrates in gamma sterilization service providers, where facility capacity constraints create downstream bottlenecks for institutional-grade garment production. Distribution runs through specialized emergency medical equipment retailers and direct manufacturer field representatives, with consolidated purchasing organizations capturing standardized variants for high-throughput emergency departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-shock trouser market is emerging from a cyclical trough driven by EU MDR certification backlogs, with notified-body processing timelines normalizing and releasing pent-up tender volume.
For Market Incumbents: Compound technical documentation depth across BfArM and ANSM compliance pathways to widen certification moats against emerging entrants. Prioritize backward integration into nylon polymer compounding to secure supply continuity amid medical-grade resin allocation constraints. Defensive positioning must neutralize junctional tourniquet substitution threats through protocol partnership lock-in with major trauma consortiums. For New Entrants and Emerging Players: Post-market surveillance service gaps among legacy manufacturers present white-space entry points for EU-authorized representative infrastructure plays. Target French tactical medical equipment testing facilities and United Kingdom Coast Guard maritime rescue segments where specification diversity rewards agile certification strategies. Go-to-market traction flows through direct engagement with municipal fire departments bypassing consolidated purchasing organization concentration. For Investors and Strategic Acquirers: Specialized emergency-care divisions with established European tender channel relationships represent priority acquisition archetypes for trauma-systems portfolio expansion. Long-term viability hinges on harmonized FDA-MDR pathway emergence collapsing duplicate testing expenditures. Monitor mutual recognition framework negotiation momentum between FDA and EU notified bodies as inflection signal for cross-Atlantic market access economics.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment Acceleration | Notified-body capacity expansion in Germany compresses certification timelines for Class IIa pneumatic devices. |
| Smart Pressure Monitoring Integration | Transducer feedback capability penetration into air medical transport segments collapses pre-hospital and trauma bay monitoring gaps. |
| Backward Integration into Nylon Compounding | Captive polymer supply secures burst strength consistency for autotransfusion pressure specifications. |
| Training Sector Cotton-Blend Volume Capture | Simplified construction variants address cost-sensitive civilian emergency response academy procurement. |
| Harmonized FDA-MDR Pathway Advocacy | Mutual recognition framework pursuit reduces redundant clinical evidence expenditure for qualified manufacturers. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with emergency medical services procurement directors, biomedical engineering leads at trauma centers, GPO contracts managers, and notified-body technical documentation specialists; and secondary validation against FDA 510(k) filings, EU MDR conformity assessment databases, hospital procurement records, and BfArM technical documentation registries. Bottom-up segmentation modeling triangulated against top-down macroeconomic boundary conditions.
Across the analysis window, forecasts deployed material-grade, end-user risk profile, and feature-tier segmentation dimensions with geographic regulatory cluster overlays. CAGRs derived from installed base replacement cycles, emergency medical services fleet expansion trajectories, and protocol standardization adoption curves. Industry-specific inputs incorporated pneumatic pressure dynamics engineering constraints and sterilization cycle degradation curves.
Underlying assumptions cover EU MDR notified-body processing normalization, nylon polymer medical-grade resin supply continuity, and trauma consortium purchasing consolidation stability, with deviation risk concentrated in regulatory divergence acceleration and substitute hemorrhage control technology adoption. Recalibration cycles align with material shifts in harmonized pathway negotiations and special operations procurement specification releases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Hand Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Cuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
Booster Seat Type Child Safety Seats Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above-The-Neck PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Machine Safeguarding Solution Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Eye Wear Market
Safety Equipment and Personal Protective Equipment (PPE)
Human Airbag Wearable Market
Safety Equipment and Personal Protective Equipment (PPE)
Laser Safety Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
In Room Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Power Air Purifying Respirator Market