
 Palletizing Machines Market | 2026-2036
Palletizing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Palletizing Machines Market Outlook
Skilled robotics technician availability is unwinding across industrial hubs, forcing manufacturers to simplify deployment architectures. ABB leverages its integrated motion-control software to reduce commissioning complexity for end users with limited programming staff. FANUC Corporation sustains dominance through captive servo-motor production that insulates lead times from component shortages. KUKA AG competes on open-architecture controllers that allow third-party integration without proprietary lock-in.
Palletizing machines are material-handling systems that stack products onto pallets using programmable motion paths, typically achieving throughput rates of 20-40 cycles per minute depending on payload weight and gripper configuration. Their primary purpose is to replace manual stacking in high-volume distribution centers and production lines, reducing ergonomic injuries while stabilizing load uniformity for transport. Robotic machine type configurations lead installed base value due to flexibility in handling mixed-SKU loads, while conventional systems anchor margin pools in bulk commodity sectors with predictable, repetitive patterns. Food and beverage end users represent the fastest-growing demand segment as chilled and frozen product lines require sanitary stainless-steel construction and washdown-rated actuators.
OSHA lockout/tagout standards and the EU Machinery Directive shape machine design by mandating redundant safety circuits and physical guarding around articulated arms, adding engineering cost but creating compliance barriers for low-cost entrants. ISO 10218-1/2 robot safety standards further constrain product architecture by defining collaborative speed limits and force thresholds that determine whether human-robot coexistence is permissible without caging. Stakeholders must monitor how evolving collaborative robot regulations redefine the boundary between standalone and integrated deployment modes.
Market Dynamics
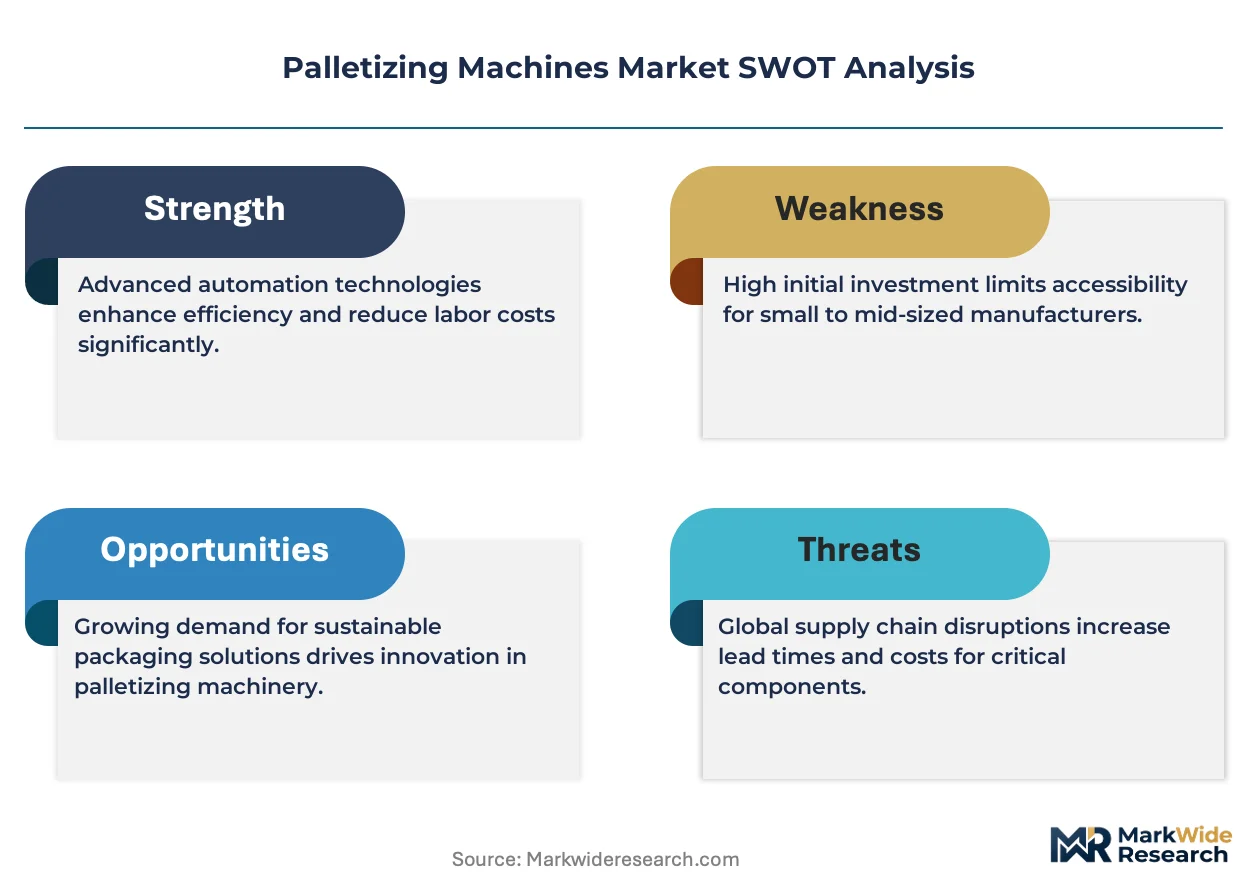
Robot safety standards are fragmenting deployment architectures as ISO 10218-1/2 force thresholds determine whether articulated arms require physical caging or can operate in collaborative modes, compressing the addressable market for uncertified low-cost systems.
Growth Catalysts
- EU Machinery Directive compliance mandates:Redundant safety circuits and physical guarding requirements accelerate replacement cycles for legacy palletizing systems across German automotive clusters.
- Food and beverage throughput pressure:Chilled and frozen product lines drive automated palletizing capacity expansion to meet distribution center velocity targets.
- Stainless steel washdown construction:Sanitary-rated actuators and corrosion-resistant frames enable deployment in hygienic processing environments previously served by manual stacking.
Market Restraints
- Servo motor supply concentration:Captive production by Japanese and German component specialists creates lead time vulnerability for system integrators without backward integration into motor manufacturing.
- ISO 10218-1/2 certification cost:Force threshold testing and collaborative speed validation add engineering expense that eliminates margin for price-competitive entrants.
- Manual stacking substitution ceiling:Irregular SKU mixes and low-volume batch operations in specialty chemical packaging resist full automation.
Strategic Opportunities
- India logistics automation:E-commerce fulfillment center buildouts in Mumbai and Delhi industrial corridors create first-mover positioning for robotic palletizing vendors.
- Brazil cold chain expansion:ANVISA sanitary requirements for temperature-controlled pharmaceuticals drive demand for washdown-rated stainless steel systems.
- AI Act compliance services:EU machinery manufacturers can bundle risk management system documentation with palletizing deployments to capture adjacent revenue.
Industry Challenges
- Robotics technician scarcity:Programming and commissioning expertise concentrates in Stuttgart, Detroit, and Nagoya industrial hubs, forcing manufacturers to simplify deployment architectures for peripheral markets.
- Legacy controller integration:Proprietary communication protocols in decade-old warehouse management systems obstruct seamless robotic palletizing adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Palletizing Machines Market |
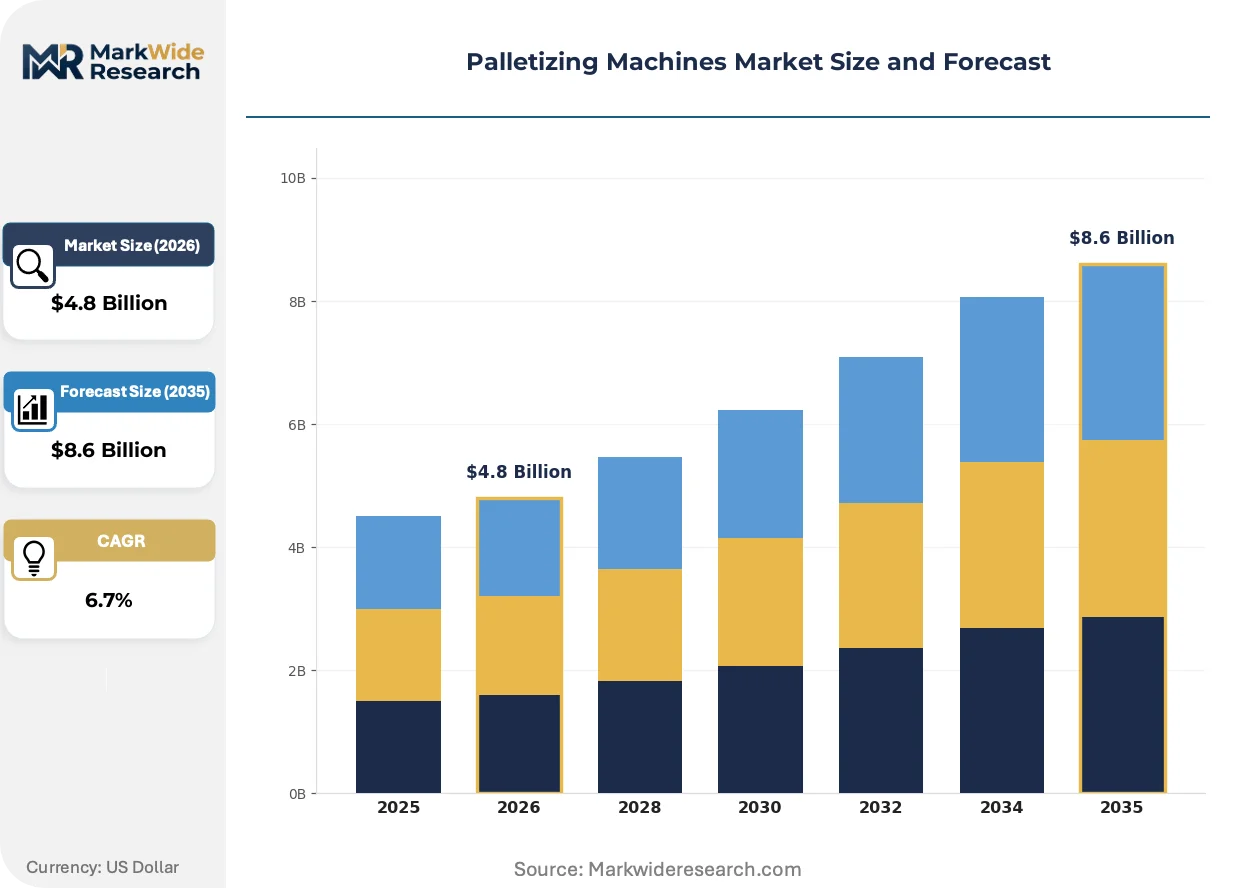
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Robotic, Conventional, Hybrid, Automated End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Chemicals Deployment: On-premise, Cloud-based, Integrated, Standalone Operation Mode: Manual, Semi-automatic, Fully Automatic, Randomized |
| Companies Covered | ABB, Universal Robots, FANUC Corporation, Doosan Robotics, Yaskawa Electric, KION Group AG, Honeywell International, Krones AG, KUKA AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Palletizing Machines Market Strategic Shifts
Software-defined motion control is decomposing traditional hardware-centric architectures, enabling remote diagnostics and predictive maintenance that alter service revenue models across the installed base.
Vision-guided depalletizing is decomposing fixed-pick-point assumptions in mixed-SKU operations. Food and beverage distributors in the Netherlands and Belgium are deploying 3D camera arrays at pilot scale. The technology is decomposing the boundary between robotic and conventional system selection criteria by eliminating the need for consistent product dimensions.
REACH substance restrictions on lubricants and hydraulic fluids are forcing reformulation of actuator maintenance protocols. German machinery OEMs now specify biodegradable greases for washdown environments. The chilled dairy segment faces the steepest compliance cost inflation as frequent cleaning cycles accelerate fluid degradation.
Buyer consolidation among third-party logistics operators is compressing vendor negotiation cycles. Large European 3PLs now demand outcome-based throughput guarantees rather than equipment purchase. The Benelux region exhibits the most aggressive contract restructuring as DHL and Kuehne+Nagel centralize automation procurement decisions.
Palletizing Machines Market Segmentation
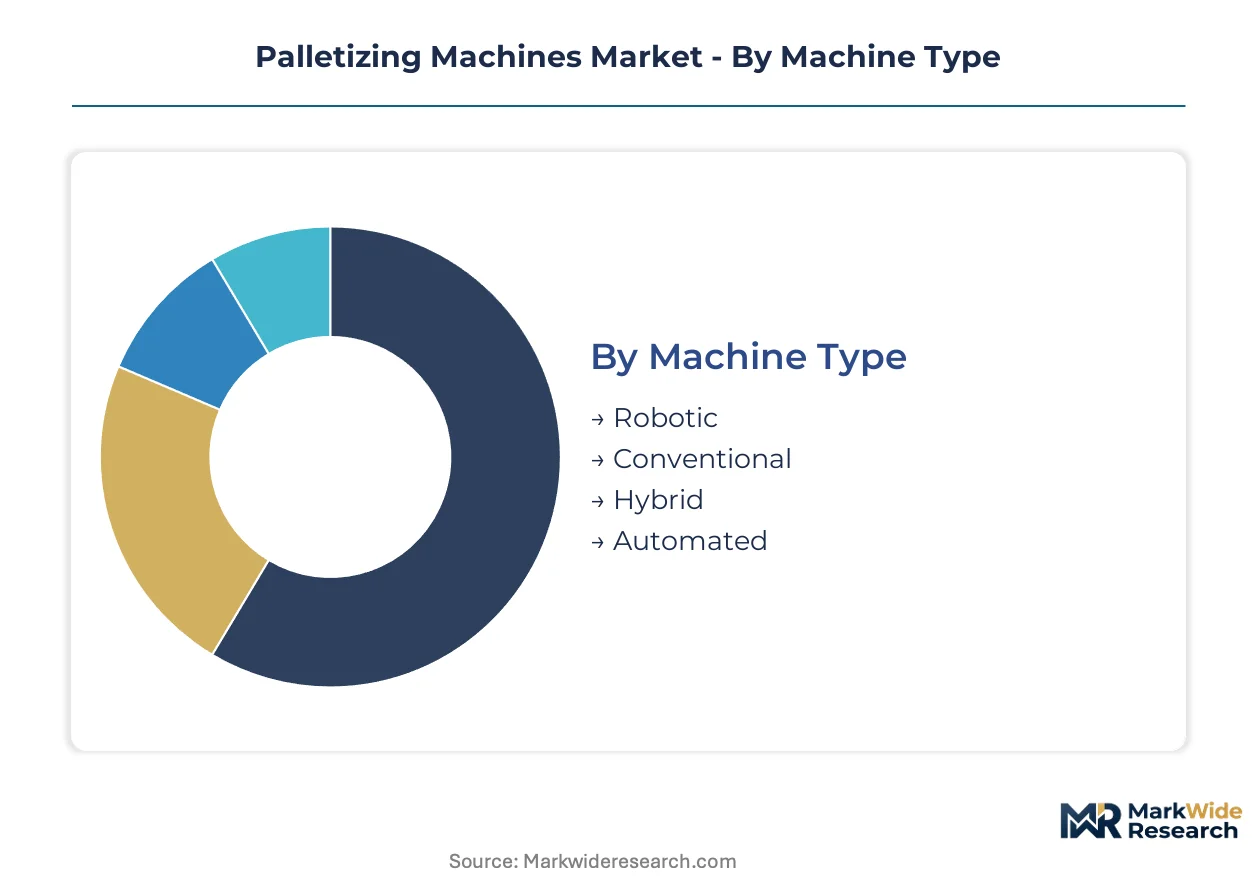
Palletizing machine configurations diverge sharply across deployment contexts, with channel economics dictating whether robotic flexibility or conventional throughput anchors procurement decisions. Understanding segment boundaries clarifies where specification premiums command pricing power versus where standardization drives margin compression.
Machine Type:
Channel mix varies by throughput requirements and SKU complexity, with system integrators pushing robotic configurations for mixed-load operations while conventional systems flow through direct OEM relationships in commodity sectors.
- Robotic:Articulated arm configurations with programmable motion paths handle mixed-SKU loads through vision-guided pick points. Food and beverage distributors in the Netherlands and Belgium deploy these for chilled dairy operations where load patterns shift hourly. Stainless steel washdown construction and force-limited collaborative modes command specification premiums in hygienic environments.
- Conventional:Fixed mechanical gantries and layer-forming systems achieve sustained throughput rates for uniform product dimensions. Bulk grain and cement packaging operations in Germany's industrial corridors favor these for predictable repetitive patterns with minimal programming overhead.
- Hybrid:Combines robotic flexibility with conventional speed through modular end-effector switching.
- Automated:Fully integrated lines with upstream conveyor synchronization and downstream stretch-wrapping coordination.
Conventional systems dominate installed base. Robotic configurations are where expansion concentrates.
End User:
Cost tiers separate specification requirements, with pharmaceutical and food segments absorbing stainless steel construction premiums while chemicals and consumer goods optimize for throughput per capital dollar.
- Food & Beverage:Chilled and frozen product lines demand sanitary-rated actuators and corrosion-resistant frames for washdown compliance. ANVISA requirements in Brazil and EU Machinery Directive mandates across Germany and France accelerate replacement cycles for legacy equipment in temperature-controlled distribution.
- Pharmaceuticals:Cleanroom-compatible palletizing with validated motion control and audit trail documentation. Temperature-sensitive biologics drive demand for integrated environmental monitoring in Mumbai and Delhi industrial corridors.
- Consumer Goods:High-velocity e-commerce fulfillment centers prioritize cycle speed over payload flexibility.
- Chemicals:Explosion-proof enclosures and hazardous area certifications constrain vendor selection in specialty packaging.
Food and beverage anchors revenue concentration. Pharmaceuticals are expanding most quickly.
Deployment:
Customer type determines architecture complexity, with multinational 3PLs demanding cloud-connected fleet management while regional manufacturers favor standalone simplicity to avoid IT integration costs.
- On-premise:Local controller architecture with proprietary software stacks and captive maintenance protocols. German automotive clusters favor these for deterministic cycle timing and minimal network dependency in high-volume production environments.
- Cloud-based:Remote diagnostics and predictive maintenance through software-defined motion control platforms. Large European 3PLs in the Benelux region now require outcome-based throughput guarantees enabled by centralized fleet monitoring.
- Integrated:Warehouse management system connectivity with upstream order processing coordination.
- Standalone:Self-contained units with minimal external system dependencies for rapid deployment.
On-premise configurations retain majority share. Cloud-based deployments are gaining share fastest.
Operation Mode:
Maturity curves separate segments, with fully automatic systems approaching commoditization while randomized modes capture specification premiums for unstructured environments.
- Manual:Operator-assisted loading with mechanical aids for ergonomic injury reduction. Specialty chemical packaging with irregular SKU mixes and low-volume batch operations resists full automation in peripheral European markets.
- Semi-automatic:Human-robot collaborative modes operating within ISO 10218-1/2 force thresholds. EU Machinery Directive compliance mandates redundant safety circuits and physical guarding, eliminating margin for uncertified entrants in collaborative speed validation.
- Fully Automatic:Unattended operation with fixed pick points and predetermined stacking patterns.
- Randomized:Vision-guided depalletizing with 3D camera arrays eliminating consistent product dimension requirements.
Fully automatic systems dominate unit shipments. Randomized modes show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Machinery Directive enforcement anchors European demand, with ISO 10218 safety standards accelerating replacement cycles for legacy systems across industrial clusters in Germany, the Netherlands, and France.
Germany
Automotive and logistics clusters in Stuttgart and Munich drive high-volume robotic palletizing deployments. EU Machinery Directive mandates for redundant safety circuits and physical guarding accelerate machine upgrades. The Baden-Württemberg industrial corridor concentrates system integrator expertise and captive servo-motor production.
United States
OSHA lockout/tagout standards shape palletizing machine design for distribution centers serving e-commerce fulfillment. FDA sanitary requirements for food contact surfaces drive stainless steel construction in dairy processing regions. The Midwest manufacturing belt around Chicago and Detroit anchors conventional system demand for bulk commodity packaging.
China
MIIT industrial automation policies accelerate robotic palletizing adoption in Yangtze River Delta logistics hubs. GB standards for machinery safety create compliance barriers for uncertified equipment imports. The Pearl River Delta manufacturing cluster concentrates high-velocity consumer goods palletizing for export-oriented production.
India
E-commerce fulfillment center buildouts in Mumbai and Delhi industrial corridors create first-mover positioning for robotic palletizing vendors. BIS machinery safety certification requirements add validation overhead for imported systems. The Gujarat pharmaceutical manufacturing belt drives demand for cleanroom-compatible palletizing with audit trail documentation.
Brazil
ANVISA sanitary requirements for temperature-controlled pharmaceuticals drive demand for washdown-rated stainless steel systems. Cold chain infrastructure expansion in São Paulo and Rio de Janeiro accelerates automated palletizing capacity for chilled distribution. The Minas Gerais dairy processing cluster faces steep REACH substance compliance costs for lubricant reformulation.
Palletizing Machines Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in palletizing machines, with captive component production and open-architecture controllers defining competitive position. The market structure rewards backward integration into servo-motor manufacturing and motion-control software stacks. Three archetypes dominate: diversified industrial automation conglomerates with captive supply chains, pure-play robotic system specialists, and conventional machinery OEMs with retrofit service networks. Capacity expansion in Asian logistics corridors and strategic partnerships for AI Act compliance services represent the dominant competitive moves.
Within the integrated automation tier, ABB leverages integrated motion-control software to reduce commissioning complexity, while FANUC Corporation sustains market presence through captive servo-motor production. KUKA AG occupies a position exemplifying open-architecture controller strategies that enable third-party integration. These three anchors represent distinct approaches to addressing robotics technician scarcity through deployment simplification, supply chain insulation, and interoperability flexibility respectively.
| Leading Market Players |
|---|
| ABB |
| Universal Robots |
| FANUC Corporation |
| Doosan Robotics |
| Yaskawa Electric |
| KION Group AG |
| Honeywell International |
| Krones AG |
| KUKA AG |
| Others |
Value Chain & Pricing Dynamics
ISO 10218-1/2 certification requirements simultaneously gate supply-side qualification and stratify price tiers by safety architecture complexity, forcing uncertified entrants toward commodity conventional systems while compliant vendors capture collaborative robot premiums.
Pricing Analysis
German automotive clusters command 15-25% specification premiums over Southeast Asian logistics deployments for equivalent robotic throughput. Three-tier pricing structure across collaborative-certified, standard industrial, and economy conventional levels anchors the market, with force-threshold validation and stainless steel washdown construction as primary differentiation drivers. Cost compression in economy tiers is intensifying because Chinese system integrators are flooding bulk grain handling with uncertified gantry systems. Third-party logistics operators in the Benelux region exhibit lowest price sensitivity due to outcome-based contract structures, while regional dairy processors in peripheral EU markets face acute budget constraints.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for Japanese servo-motor shipments to German system integrators. Captive production concentrates in Japan, Germany, and China, with FANUC and Yaskawa drawing from in-house motor manufacturing while European specialists rest on third-party supply. Rare earth magnet dependency and precision gearbox sourcing create single-source vulnerability around Nagoya and Stuttgart industrial hubs. Distribution runs through system integrator networks for robotic configurations and direct OEM relationships for conventional bulk systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are proliferating as food and beverage distributors demand application-specific hygienic configurations that defy standardized platform economics.
For Market Incumbents: Consolidate around captive servo-motor supply and motion-control software stacks to insulate lead times from component shortages. Defend margin position by acquiring regional system integrators in Mumbai and Delhi corridors before specialized local players anchor first-mover relationships. ISO 10218 collaborative certification investment represents the priority defensive lever against Chinese price competition. For New Entrants and Emerging Players: Lead with AI Act compliance documentation services bundled with palletizing deployments to capture adjacent revenue from EU machinery manufacturers. Target Brazil's ANVISA-regulated cold chain expansion with washdown-rated stainless steel configurations priced below Krones and KUKA premium tiers. Direct-to-plant commissioning partnerships with under-served dairy processors in Minas Gerais offer the most penetrable entry vector. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-based deployment models as software-defined motion control reduces hardware content per installation. Long-term viability across the analysis window favors targets with backward-integrated component production and open-architecture controller platforms. The signal to monitor is DHL and Kuehne+Nagel procurement centralization velocity in the Benelux region.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo-Motor Production | FANUC's captive supply chain insulates lead times from rare earth magnet volatility. |
| AI Act Compliance Service Bundling | EU machinery OEMs capture adjacent revenue through risk management documentation. |
| Cloud-Based Fleet Management Platform | Large European 3PLs demand outcome-based throughput guarantees from centralized monitoring. |
| Vision-Guided Depalletizing Deployment | 3D camera arrays in Netherlands and Belgium eliminate fixed-pick-point constraints. |
| Regional System Integrator Acquisition | First-mover positioning in Mumbai and Delhi corridors secures e-commerce fulfillment contracts. |
Study Parameters
Initial hypotheses were tested against primary input from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads, then refined through secondary validation against SEC 10-K filings, customs trade data, machinery safety certification databases, and EU Machinery Directive implementation reports. Bottom-up triangulation across installed base estimates and top-down reconciliation against capital expenditure disclosures anchored volume and value outputs.
Variance decomposition across machine type, end-use industry, deployment architecture, and regional regulatory cluster shaped the analytical framework throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Industry-specific forecast inputs included EU Machinery Directive replacement cycle timing and food and beverage throughput pressure indices from distribution center velocity targets.
Forecasts assume regulatory continuity in EU Machinery Directive enforcement and OSHA lockout/tagout standards; material policy shifts would require re-modeling. Supply chain disruption scenarios and collaborative robot speed threshold revisions represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Combination Filler Machine Market
Packaging Machinery
Tube Filling Machine Market
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Banding Machine Market
Packaging Machinery
Pick Fill Seal Machines Market
Packaging Machinery
Autofill Drums & Totes Machines Market
Packaging Machinery
Global Form Fill Seal Machines Market
Packaging Machinery
Case Packing Machines Market
Packaging Machinery
Sack Fillers Market
Packaging Machinery
Volumetric Boom Filling Machine Market
Packaging Machinery
Plastic Extruding Equipment Market
Packaging Machinery
Bagging Machine Market
Packaging Machinery
LAMEA Printing Machinery Market
Packaging Machinery
Global Filling Machines Market
Packaging Machinery
Laminating Machines Market