
 Thermal Underwear Market | 2026-2036
Thermal Underwear Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Underwear Market Analysis
Buyer concentration across outdoor specialty retailers is expanding as direct-to-consumer channels fragment the traditional wholesale landscape. Under Armour leverages its performance apparel heritage to compete in athletic thermal segments with moisture-wicking innovations. Smartwool anchors its position through vertical control of merino wool sourcing from New Zealand ranching networks. Hanesbrands sustains mass-market volume through dominant shelf presence in big-box retail channels.
Thermal underwear comprises engineered knit garments designed to regulate body temperature through moisture management and insulating air-trapping structures, typically constructed from synthetic blends or natural fibers with thermal resistance values measured in clo units. Base layer products dominate commercial volume due to universal applicability across end uses, while merino wool segments command premium positioning through odor-resistance and temperature-modulating properties that polyester alternatives struggle to replicate. The industrial workers category within end users represents an underserved structural opportunity as employers mandate cold-stress protective equipment under evolving workplace safety frameworks.
REACH in Europe restricts hazardous chemical inputs in textile finishing, compelling reformulation of anti-microbial and wicking treatments across supply chains. OSHA cold-stress guidelines in the United States shape procurement specifications for industrial thermal garments in construction and logistics sectors. OEKO-TEX Standard 100 certification increasingly gates retail access in German-speaking markets. Stakeholders must monitor how divergent chemical safety regimes between jurisdictions fragment product platform strategies and compliance costs.
Market Dynamics
REACH compliance mandates in Europe are forcing wholesale reformulation of anti-microbial and moisture-wicking chemical treatments, creating supply chain friction for manufacturers serving multiple regulatory jurisdictions.
Growth Catalysts
- Winter sports infrastructure expansion:China's domestic ski resort construction and ice hockey venue development is generating institutional procurement contracts for cold-climate base layer systems.
- OSHA cold-stress enforcement:The United States workplace safety regulator's updated guidelines mandate thermal protective equipment for outdoor construction and logistics workers, expanding industrial end-use demand.
- Merino wool temperature modulation:Natural fiber performance advantages in odor management and moisture buffering are pulling premium outdoor enthusiasts away from synthetic alternatives.
Market Restraints
- Petrochemical input volatility:Polyester and polypropylene fiber production depends on crude oil derivatives, exposing margin structures to energy price swings.
- New Zealand ranching concentration:Premium merino wool sourcing clusters in a single geography, creating weather and biosecurity vulnerability for brands dependent on natural fiber positioning.
- REACH chemical restriction scope:The European regulation's expanding list of restricted substances limits treatment options for anti-microbial and wicking functionality.
Strategic Opportunities
- Industrial cold-stress compliance:Employer mandates under evolving workplace safety frameworks in Germany and the United States create specification-driven procurement for base layer systems.
- Direct-to-consumer channel maturation:Digital-native thermal brands bypass wholesale margin structures to capture full retail value from outdoor enthusiasts.
- Sustainable fiber certification premiums:OEKO-TEX Standard 100 and ZQ Merino credentials command shelf price premiums in German-speaking retail markets.
Industry Challenges
- Multi-jurisdiction chemical compliance:Divergent safety regimes between REACH, EPA TSCA, and China's GB standards fragment product platform strategies and inflate testing costs.
- Knitting equipment retooling cycles:Seamless construction and 3D knitting technologies require capital-intensive machinery upgrades that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Underwear Market |
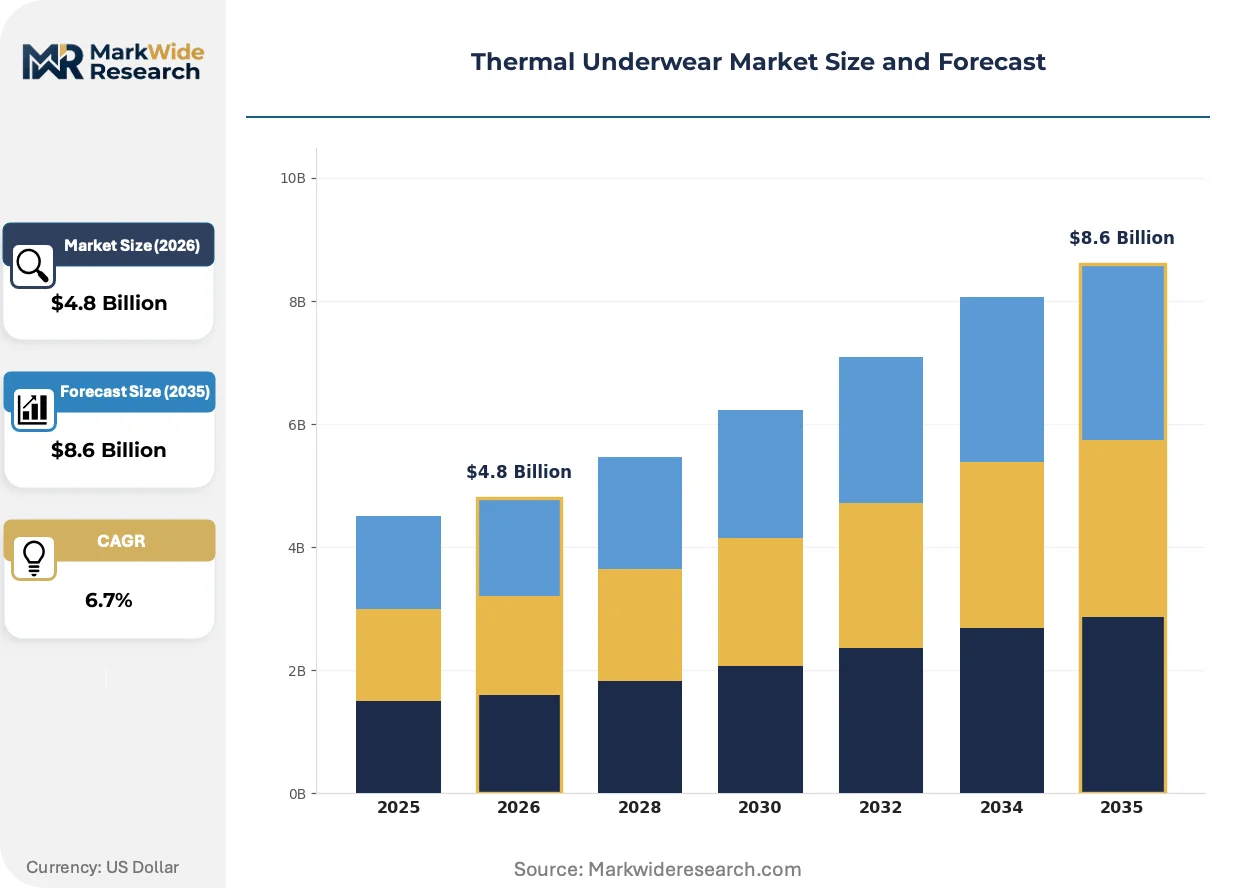
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Layer, Mid Layer, Full Body Suit, Accessories Material: Merino Wool, Polyester, Cotton, Fleece Gender: Men, Women, Kids, Unisex End User: Outdoor Enthusiasts, Athletes, Casual Users, Industrial Workers |
| Companies Covered | Jockey International, Fruit of the Loom, Under Armour, L.L.Bean, Smartwool, Hanesbrands, PVH Corp., Marks and Spencer, Adidas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Underwear Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are simultaneously compressing legacy treatment portfolios and opening white space for bio-based functional finishes.
Seamless knitting technology is automating the elimination of stitch seams that historically created friction points and thermal bridges in base layer construction. Alpine and backcountry ski segments are adopting these garments fastest, with specialty retailers reporting accelerated sell-through compared to traditional flatlock-sewn alternatives. The technology is automating the compression of labor-intensive sewing operations while enabling anatomical panel engineering that was previously cost-prohibitive.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating durable water repellent chemistries from thermal underwear finishing lines. European manufacturers face reformulation timelines that compress product development cycles and force reliance on less durable bio-based alternatives. Base layer categories targeting Nordic hiking and ski touring are most affected, with brands accelerating plasma and silicone-based treatment testing to maintain performance claims.
Certification-driven purchasing is displacing brand-loyal selection among outdoor specialty buyers who prioritize OEKO-TEX and bluesign credentials over heritage labels. Specialty retailers in Germany and Austria are reorganizing shelf space around chemical safety tiers rather than traditional price-performance positioning. This behavior is most visible in the alpine regions of Bavaria and Tyrol, where consumer education on textile chemistry has advanced fastest through mountaineering club purchasing guidelines.
Thermal Underwear Market Segmentation
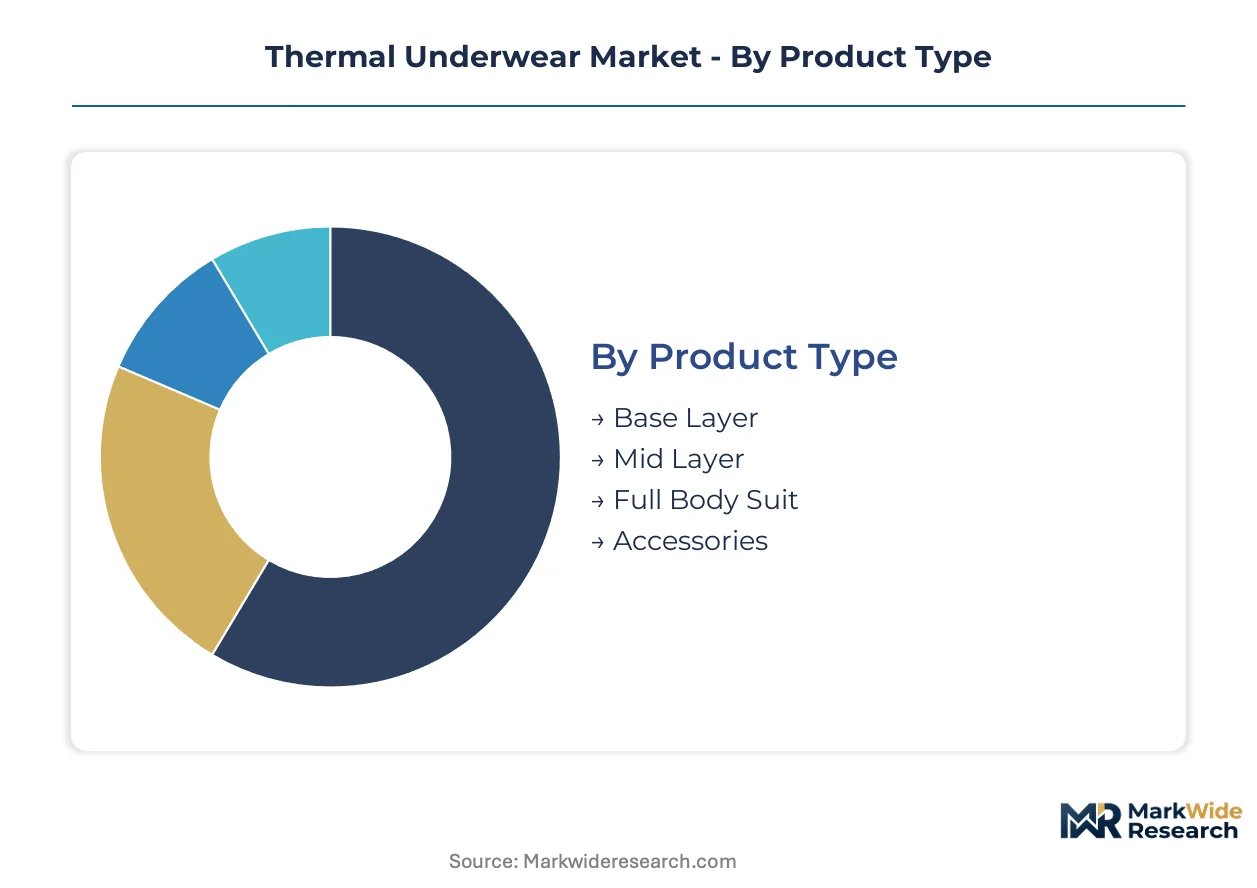
Thermal underwear segmentation reveals divergent margin structures across material science tiers and regulatory exposure profiles. Product architecture and fiber chemistry determine which buyer segments capture premium positioning versus commodity volume.
Product Type:
Layering position in the thermal system dictates price architecture and replacement frequency across buyer types.
- Base Layer:Engineered knit garments worn directly against skin with moisture-wicking and odor-control specifications. Outdoor enthusiasts in alpine skiing and backcountry hiking drive specification-heavy procurement for merino-polyester blends with flatlock or seamless construction.
- Mid Layer:Insulating garments that trap air between base and shell layers, typically constructed from fleece or lightweight synthetic pilling. Demand concentrates among casual users in temperate climates where full system layering is optional rather than mandatory.
- Full Body Suit:Integrated single-piece construction eliminating thermal bridges at waist and wrist junctions. Industrial workers in logistics and construction sectors under OSHA cold-stress mandates specification.
- Accessories:Supplementary items including thermal socks, neck gaiters, and balaclavas completing the base layer system. Outdoor specialty retailers bundle these with core garment purchases.
Volume sits with Base Layer; growth tilts toward Full Body Suit.
Material:
Fiber selection determines chemical compliance burden and sourcing geography concentration for manufacturers.
- Merino Wool:Natural protein fiber from New Zealand ranching networks with inherent temperature modulation and odor resistance. REACH and OEKO-TEX certification requirements in German-speaking markets pull premium outdoor enthusiasts toward ZQ-certified sourcing.
- Polyester:Petroleum-derived synthetic with hydrophobic wicking properties and lower unit cost. Petrochemical input volatility constrains margin stability for mass-market positioning.
- Cotton:Cellulosic fiber with moisture-retention limitations that restrict performance applications. Casual users in low-exertion cold-weather scenarios accept cotton for comfort familiarity.
- Fleece:Brushed synthetic or natural fiber pile creating lofted air-trapping structures. Mid-layer applications dominate fleece consumption.
Polyester commands volume share; merino wool captures the steepest expansion trajectory.
Gender:
Anatomical patterning requirements and sizing granularity separate manufacturing complexity across buyer categories.
- Men:Larger average sizing and broader shoulder proportioning with standardized grading scales. Industrial procurement contracts default to men's cuts for workforce uniformity.
- Women:Contoured patterning with expanded size grading and colorway diversity. Outdoor specialty retailers report faster inventory turns in women's technical base layers.
- Kids:Rapid growth-stage replacement cycles with lower absolute price points. Parents prioritize durability over performance specifications.
- Unisex:Simplified sizing matrices reducing SKU complexity for mass-market distribution. Big-box retail channels favor unisex for inventory efficiency.
Men's segment holds volume concentration; women's technical base layers are climbing the fastest.
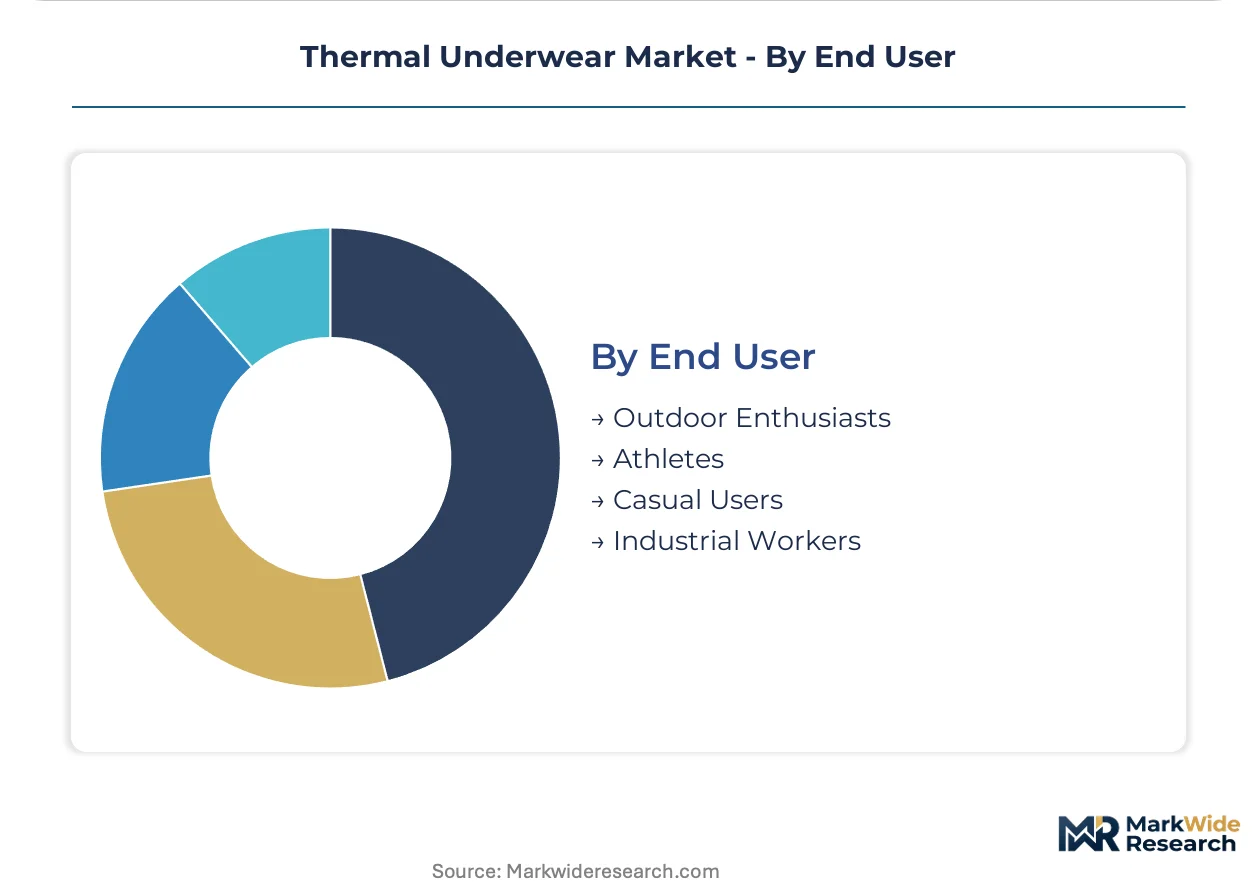
End User:
Activity intensity and regulatory environment shape performance requirements and procurement authority structures.
- Outdoor Enthusiasts:Self-directed buyers prioritizing technical performance and chemical safety credentials. OEKO-TEX and bluesign certification visibility influences purchase decisions in German and Austrian alpine markets.
- Athletes:Team and institutional procurement with moisture-management and compression specifications. Moisture-wicking synthetic blends dominate this segment.
- Casual Users:Price-sensitive occasional cold-weather wearers with lower performance expectations. Cotton and cotton-blend products serve this demand.
- Industrial Workers:Employer-mandated protective equipment under evolving cold-stress safety frameworks. OSHA enforcement in the United States and emerging protocols in China specification.
Outdoor Enthusiasts anchor premium revenue; Industrial Workers represent the most underpenetrated structural opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the steepest demand trajectory as domestic winter sports infrastructure and cold-climate workplace safety protocols expand simultaneously. Outdoor enthusiasts across alpine regions in Europe and North America anchor premium positioning, while industrial procurement in the United States generates specification-driven volume under evolving regulatory mandates.
China
Domestic ski resort construction and ice hockey venue development generate institutional procurement contracts for cold-climate base layer systems. GB standards for textile safety and workplace cold protection are expanding compliance requirements for domestic manufacturers. Heilongjiang and Jilin provinces cluster winter sports infrastructure investment, driving regional demand concentration for performance thermal systems.
United States
OSHA cold-stress enforcement mandates thermal protective equipment for outdoor construction and logistics workers, expanding industrial end-use demand. EPA TSCA chemical regulations constrain anti-microbial treatment formulations for domestic production. Denver and Salt Lake City anchor outdoor specialty retail concentration, with backcountry skiing communities driving premium merino wool adoption.
Germany
REACH compliance mandates wholesale reformulation of moisture-wicking chemical treatments, creating supply chain friction for manufacturers serving European markets. OEKO-TEX Standard 100 certification gates retail access in German-speaking markets, pulling consumer preference toward certified sustainable fibers. Bavaria and Tyrol alpine regions reorganize specialty retail shelf space around chemical safety tiers rather than traditional price-performance positioning.
Japan
Mountaineering and backcountry skiing communities drive technical base layer specification with emphasis on odor-resistance and temperature modulation. METI industrial standards and JIS textile regulations shape domestic product safety frameworks. Nagano Prefecture clusters winter sports infrastructure and outdoor specialty retail concentration, with domestic brands competing on seamless knitting technology adoption.
Australia
Outdoor recreation participation in alpine and high-country regions sustains demand for merino wool base layers leveraging temperature-modulating properties. The country's national workplace safety regulator mandates cold-stress protective equipment for mining and agricultural outdoor workers. Victorian alpine resorts and Tasmanian high-country regions concentrate specialty retail distribution for technical thermal systems.
Thermal Underwear Market Vendor Landscape
United States producers anchor one tier; European specialists hold premium positioning through certified fiber sourcing. The vendor base distributes across mass-market volume players, technical outdoor specialists, and industrial procurement suppliers. Three strategic archetypes dominate: heritage apparel conglomerates with dominant retail shelf presence, merino wool vertical integrators controlling upstream ranching networks, and performance athletic brands leveraging moisture-wicking innovation heritage. Competitive moves concentrate on seamless knitting equipment retooling and sustainable fiber certification acquisition.
Within the heritage conglomerate tier, Hanesbrands and Fruit of the Loom exemplify mass-market positioning through big-box retail channel dominance. Under Armour occupies a position among athletic-performance specialists translating moisture-management heritage into thermal segments. Smartwool represents the vertical-integrator archetype with captive supply chain positioning in natural fiber sourcing. These three companies illustrate divergent strategic paths: scale-driven distribution efficiency, technical performance innovation, and upstream supply control.
| Leading Market Players |
|---|
| Jockey International |
| Fruit of the Loom |
| Under Armour |
| L.L.Bean |
| Smartwool |
| Hanesbrands |
| PVH Corp. |
| Marks and Spencer |
| Adidas |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between OEKO-TEX-certified merino wool systems and commodity polyester base layers manifests in both shelf price architecture and upstream sourcing configurations, with premium tiers commanding captive ranching relationships while mass-market positioning depends on spot-market petrochemical derivatives.
Pricing Analysis
Volume-mass concentration in polyester base layers compresses per-unit margins while merino wool segments sustain premium capture through ZQ certification scarcity and temperature-modulating performance claims. Three-tier pricing structure across premium, standard, and economy levels separates outdoor specialty certification tiers from big-box retail efficiency plays. Cost compression in synthetic tiers is intensifying because crude derivative volatility feeds directly into fiber input costs. Industrial procurement contracts under OSHA mandates show lowest price sensitivity; casual cotton buyers exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Germany and the United States anchor hub-and-spoke patterns serving outdoor specialty retail, while direct-to-consumer brands bypass wholesale layers entirely. Manufacturing concentrates in China, Vietnam, and Bangladesh for cut-and-sew operations; New Zealand ranching networks supply premium fiber. Raw material dependencies rest on merino wool clip volumes, polyester chip flows, and elastane content for seamless construction. Single-source vulnerability clusters in New Zealand wool supply. Distribution runs through big-box retail for mass-market tiers and outdoor specialty channels for technical segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
New Zealand ranching capacity constraints prop merino wool pricing, creating a supply-constrained structure where fiber scarcity sustains premium tier capture regardless of synthetic substitution pressure.
For Market Incumbents: Deploy seamless knitting equipment retooling to automate labor-intensive sewing operations and compress unit costs against emerging digital-native competitors. Consolidate position by acquiring OEKO-TEX and ZQ Merino certification credentials that gate German-speaking retail access. Channel control through exclusive outdoor specialty partnerships defends against direct-to-consumer fragmentation. For New Entrants and Emerging Players: OSHA cold-stress guidelines in the United States open a window for specification-driven industrial procurement contracts underserved by heritage outdoor brands. White-space concentrates in full-body suit construction for logistics and construction employers mandating protective equipment. Penetrate through direct-to-consumer digital channels bypassing wholesale margin structures that burden incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in vertical-integrator archetypes with captive New Zealand wool sourcing and established certification portfolios. Long-term viability favors brands with backward integration into ranching networks rather than synthetic-dependent positioning. Watch seamless knitting technology adoption rates as inflection indicator for manufacturing cost structure divergence.| Strategic Initiative | Industry Significance |
|---|---|
| Seamless Knitting Equipment Retooling | Automates stitch elimination and enables anatomical panel engineering previously cost-prohibitive for alpine segments. |
| ZQ Merino Certification Acquisition | Gates retail access in Bavaria and Tyrol where mountaineering club guidelines prioritize chemical safety tiers. |
| Direct-to-Consumer Channel Launch | Bypasses wholesale margin compression and captures full retail value from outdoor enthusiast segments. |
| Industrial Cold-Stress Compliance Positioning | Captures specification-driven procurement under OSHA mandates in construction and logistics sectors. |
| Bio-Based Treatment Formulation R&D | Addresses REACH Annex XVII restrictions eliminating per- and polyfluoroalkyl substances from finishing lines. |
Methodological Framework
Multi-period observation of fiber input costs, certification penetration rates, and cold-weather recreation participation anchored the trend analysis, supplemented by interviews with brand sourcing directors, outdoor specialty retail buyers, New Zealand wool cooperative managers, and industrial safety procurement officers. Secondary validation drew from OEKO-TEX certification databases, customs trade records for textile imports, SEC 10-K apparel filings, and GB standards documentation for Chinese workplace safety protocols. Bottom-up demand modeling triangulated against top-down macroeconomic indicators.
Input-output matrices mapped fiber chemistry costs through manufacturing tiers to end-use price realization across the projection horizon. Segmentation dimensions modeled include layering position, material science tier, gender patterning complexity, and regulatory compliance exposure. CAGRs derived from regression analysis of historical participation trends and infrastructure investment pipelines. Forecast inputs incorporated petrochemical price volatility indices and winter sports venue construction timelines.
The model assumes a particular technology adoption path for seamless knitting equipment; alternative pathways for 3D-knitting automation would alter the outlook for labor cost structures. Forecasts reflect documented assumptions regarding REACH enforcement timelines and OSHA cold-stress mandate expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Secondhand Apparel Market
Apparel & Footwear
Sports Inspired Clothing Market
Apparel & Footwear
Surfing Apparel and Accessory Market
Apparel & Footwear
Fast Fashion Apparel Market
Apparel & Footwear
Press-To-Close Zippers Market
Apparel & Footwear
Jeans Market
Apparel & Footwear
Rugby Apparel Market
Apparel & Footwear
Multiple Toe Socks Market
Apparel & Footwear
Global Sleepwear and Loungewear Market
Apparel & Footwear
Sailing Jackets Market
Apparel & Footwear
Streetwear Market
Apparel & Footwear
Smart Heating Scarf Market
Apparel & Footwear
Athletic and Sports Socks Market
Apparel & Footwear
Womens Swimwear Market
Apparel & Footwear
Loungewear Market
Apparel & Footwear
Official Football Kits Market