
 Fast Fashion Apparel Market | 2026-2036
Fast Fashion Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Fast Fashion Apparel Market Insights
Direct-to-consumer channels is narrowing as Shein and ASOS compress design-to-delivery cycles through algorithmic demand forecasting. Inditex sustains manufacturing proximity with Spanish, Portuguese, and Moroccan suppliers. H&M Group navigates sustainability verification requirements while expanding its resale platform infrastructure. Fast Retailing anchors quality-perception through technical fabric R&D in its LifeWear category.
Fast fashion apparel denotes garments designed, manufactured, and distributed within weeks to mirror runway trends, typically using polyester-cotton blends or virgin synthetics produced through cut-make-trim assembly. The category serves mass-market consumers seeking trend accessibility at low price points with high turnover frequency. Tops and bottoms dominate volume throughput due to lower fit complexity and faster pattern replication. Women's wear captures the largest margin pool, though unisex lines are expanding as gender-fluid styling gains commercial traction. Online channels now coordinate inventory allocation with social media trend velocity, compressing the traditional seasonal calendar.
The EU Green Deal's textile strategy and France's AGEC anti-waste law mandate extended producer responsibility and recycled content thresholds, reshaping material sourcing obligations across European markets. The US EPA and state-level California SB 707 frameworks are introducing microfiber filtration and chemical disclosure requirements that affect synthetic-dominant supply chains. Stakeholders must monitor regulatory divergence between jurisdictions while recalibrating speed-to-market models against compliance lead times.
Market Dynamics
Algorithmic demand forecasting is compressing design-to-delivery cycles from months to days, forcing legacy players to restructure supply networks around real-time trend ingestion from social platforms.
Growth Catalysts
- EU Green Deal textile strategy:Extended producer responsibility mandates are accelerating investment in closed-loop recycling infrastructure across European markets.
- Social commerce platforms:Live-streaming interfaces in China and Southeast Asia are collapsing purchase decision timelines and amplifying impulse conversion rates.
- Polyester-cotton blend innovation:Mechanical recycling advances for mixed-fiber textiles are expanding feedstock availability for circular production models.
Market Restraints
- Petrochemical input volatility:Virgin polyester pricing fluctuates with crude oil markets, compressing margin buffers for synthetic-dominant product lines.
- Guangdong supply concentration:Shein's supplier base clustering in Pearl River Delta creates systemic disruption risk from regional lockdowns or logistics bottlenecks.
- France AGEC compliance timelines:The anti-waste law's 2025 recycled content thresholds require material certification pipelines that outpace current testing capacity.
Strategic Opportunities
- India domestic market penetration:Reliance Retail and Nykaa Fashion are building last-mile infrastructure for tier-2 and tier-3 city expansion.
- Textile-to-textile chemical recycling:Enzymatic depolymerization partnerships between fiber producers and biotechnology firms are unlocking feedstock quality previously limited to bottle-to-fiber pathways.
- Resale platform integration:H&M Group's investment in secondhand infrastructure creates proprietary customer data loops that inform primary production forecasting.
Industry Challenges
- Microfiber filtration retrofitting:California SB 707 and EU Ecodesign requirements demand washing machine and wastewater infrastructure upgrades that textile brands cannot directly control.
- Life cycle assessment standardization:Competing certification schemes from Higg Index, EU PEF, and ISO 14040 create conflicting environmental claims that confuse procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fast Fashion Apparel Market |
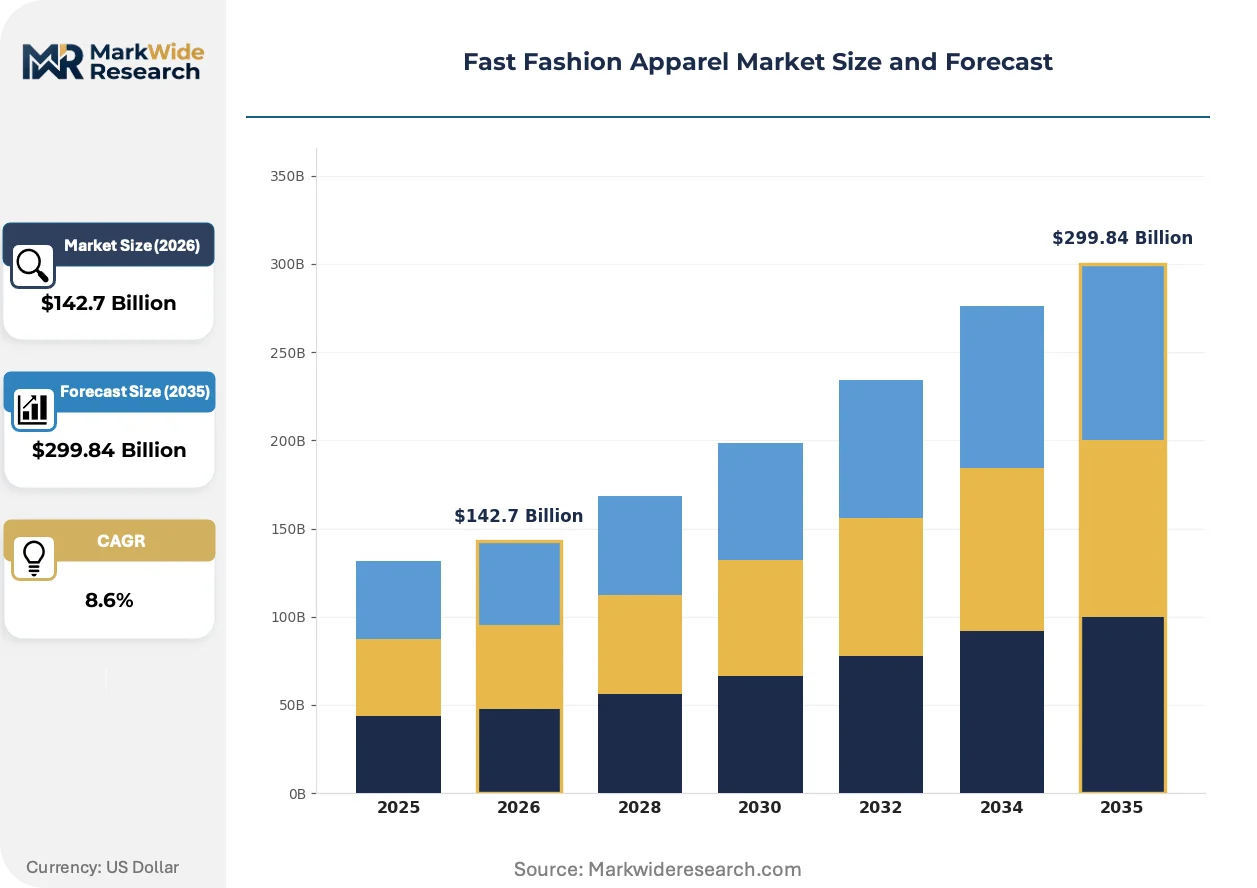
| Market Size in 2026 | $142.7 Billion |
| Market Size in 2035 | $299.84 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tops, Dresses, Bottoms, Outerwear Consumer Type: Men, Women, Children, Unisex Distribution Channel: Online, Offline, Direct-to-Consumer, Wholesalers Price Tier: Luxury, Mid-range, Budget, Discount |
| Companies Covered | Fast Retailing (Uniqlo), Primark (AB Foods), Shein, Urban Outfitters, Inc., Mango, Inditex (Zara), Gap Inc., ASOS, H&M Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fast Fashion Apparel Market Trends and Innovations
Digital twinning of garment samples is eliminating physical prototyping waste while compressing buyer approval cycles. Three interconnected shifts are restructuring how value flows through the apparel pipeline.
3D virtual sampling software is virtualizing the traditional cut-and-sew approval process. Mid-market brands in Los Angeles and London are adopting CLO and Browzwear platforms at 40% annual adoption velocity. This technology is virtualizing the physical showroom model, collapsing the sampling calendar from eight weeks to 72 hours and reducing air-freight carbon intensity for pre-production approvals.
France's AGEC law and the EU Green Deal textile strategy are mandating digital product passports with fiber composition and origin disclosure. These frameworks are forcing supply chain visibility investments that previously served only premium positioning. Fast fashion retailers sourcing from Turkey and Morocco are accelerating blockchain-traceability pilots to meet 2025 compliance deadlines without sacrificing speed-to-market.
Gen Z purchase behavior is fragmenting across platform-native discovery channels. TikTok Shop and Instagram Checkout are displacing traditional e-commerce landing pages for trend-responsive categories. This channel rotation is most visible in China's Douyin ecosystem, where live-streaming hosts generate single-session sellouts that obsolete traditional inventory allocation models.
Fast Fashion Apparel Market Segmentation
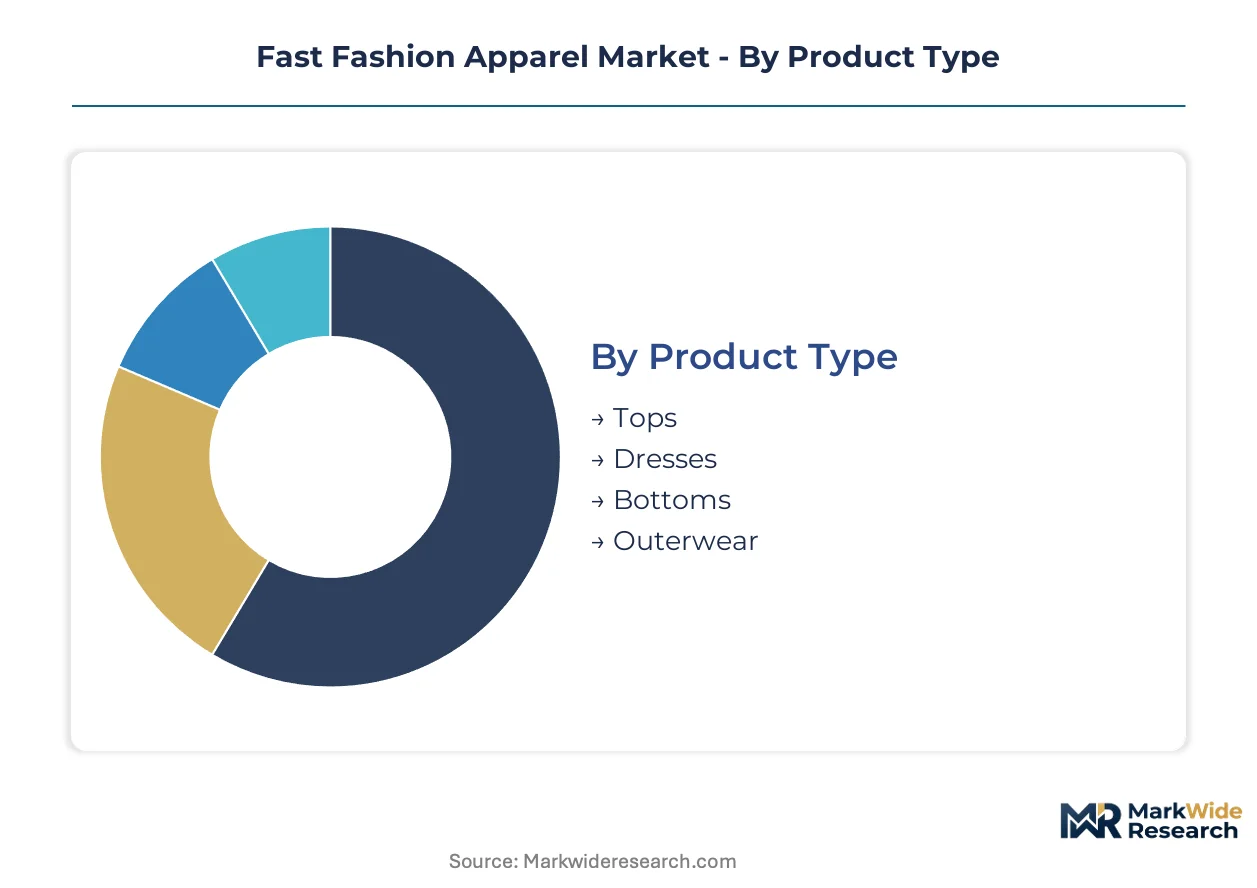
Fast fashion segmentation determines inventory velocity, margin structure, and supply chain configuration. Distinct product lifecycles and channel economics force brands to optimize segment-specific forecasting models rather than apply uniform strategies.
Product Type:
After-sales-service intensity varies sharply across garment categories, with complex construction demanding higher return-handling infrastructure and fit-consultation resources.
- Tops:Simple construction using knit polyester-cotton blends enables rapid pattern replication and minimal quality variance. Demand concentrates in China's Douyin live-streaming ecosystem, where algorithmic trend detection collapses design-to-delivery cycles to under 72 hours.
- Bottoms:Denim and trouser categories require more precise sizing infrastructure but sustain higher repeat-purchase rates. Fit-technology investments from Los Angeles-based brands are reducing return rates in this segment through AI-powered size prediction.
- Dresses:Seasonal occasion-wear with concentrated demand spikes around festival calendars.
- Outerwear:Higher unit economics with extended production lead times due to technical fabric sourcing.
Tops holds the largest share; momentum sits with Bottoms as virtual fitting technology improves conversion rates.
Consumer Type:
Cost tier stratification across consumer segments determines material specification and marketing spend allocation, with women's lines commanding premium positioning budgets.
- Women:The margin-dominant segment with highest purchase frequency and trend responsiveness. Shein's algorithmic demand forecasting infrastructure was built specifically around this segment's social-commerce discovery patterns in Guangdong supply corridors.
- Men:Lower return rates and higher basket sizes, with demand concentrating in basic-heavy assortments. Fast Retailing's LifeWear technical fabric R&D targets this segment's quality-perception requirements in Japanese and South Korean urban markets.
- Children:Size-turnover velocity drives replacement demand with lower sustainability scrutiny.
- Unisex:Gender-fluid styling expansion capturing Gen Z purchase behavior shifts.
Women's lines generate the highest absolute margin contribution; unisex is expanding most quickly as gender-fluid styling gains commercial traction.
Distribution Channel:
Volume concentration patterns determine fulfillment infrastructure requirements, with direct channels demanding proprietary logistics investment versus marketplace reliance.
- Online:Algorithmic inventory allocation coordinated with TikTok Shop and Instagram Checkout trend velocity. China's live-streaming commerce infrastructure enables single-session sellouts that compress traditional seasonal calendars.
- Direct-to-Consumer:Proprietary customer data loops informing primary production forecasting. H&M Group's resale platform integration creates circular data assets unavailable to wholesale-dependent competitors.
- Offline:Remains critical for fit-dependent categories and impulse purchases in dense urban corridors.
- Wholesalers:Volume clearance channel with compressed margins and limited brand control.
Online channels hold the largest share; direct-to-consumer is climbing the fastest as brands prioritize data ownership over marketplace reach.
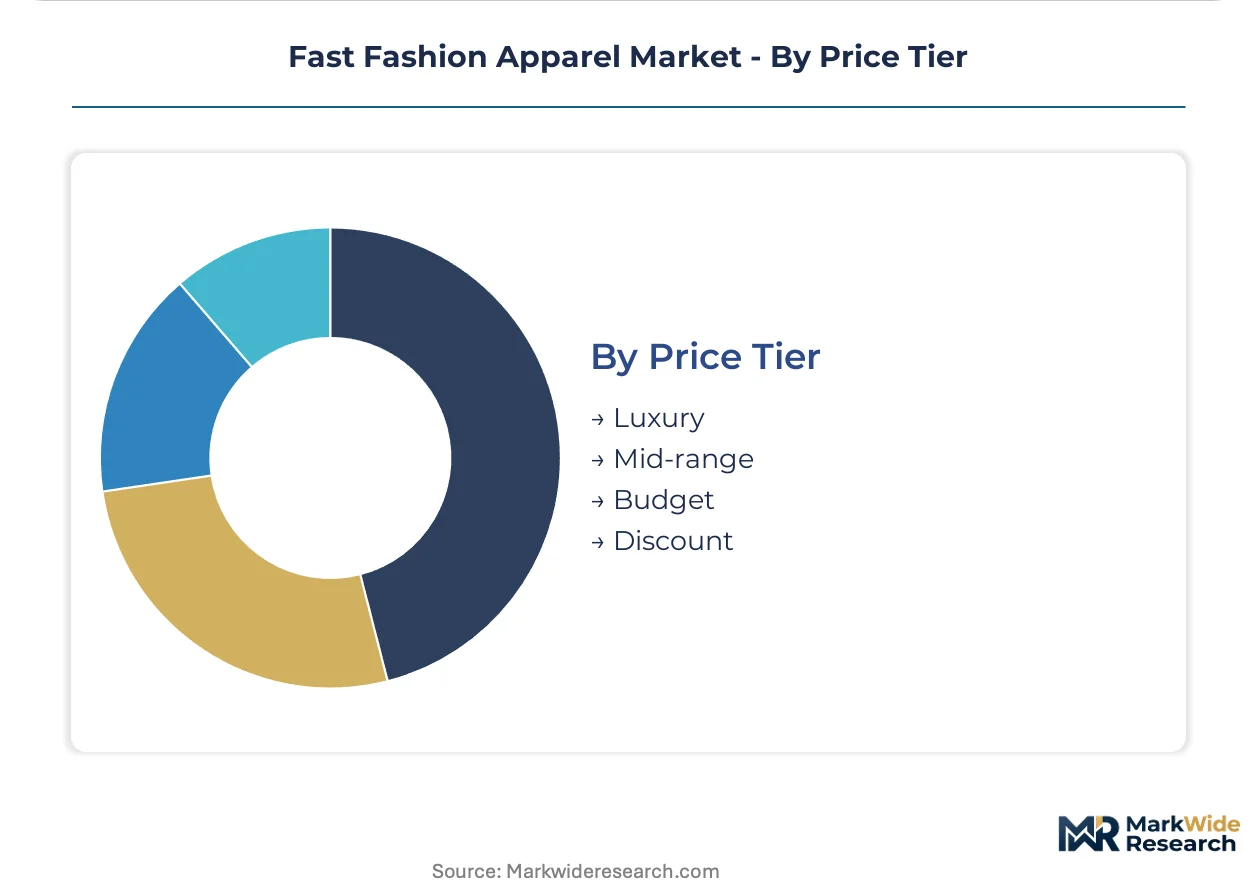
Price Tier:
Supply concentration by price positioning determines sourcing geography, with budget-tier production clustering in specific manufacturing corridors facing regulatory pressure.
- Budget:Polyester-dominant construction from Pearl River Delta suppliers serving ultra-fast turnaround requirements. France's AGEC law recycled content thresholds threaten this tier's cost structure through material certification pipeline constraints.
- Mid-range:Balanced quality-speed positioning with Turkey and Morocco sourcing gaining share for European market proximity. Inditex maintains manufacturing relationships across Spanish, Portuguese, and Moroccan supplier bases to sustain this tier's speed-to-market.
- Luxury:Limited fast fashion penetration due to brand positioning conflicts.
- Discount:End-of-life clearance positioning with minimal new production.
Budget tier holds the largest share; mid-range is gaining share fastest as regulatory compliance costs compress budget-tier margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in France and Italy where luxury adjacency commands margin premiums, while volume manufacturing clusters in China's Pearl River Delta compress unit economics through supplier density. Regulatory divergence between EU extended producer responsibility mandates and US state-level disclosure frameworks creates compliance fragmentation. Demand formation now tracks social commerce velocity rather than traditional seasonal calendars.
China
Live-streaming commerce on Douyin and Xiaohongshu collapses purchase decision timelines to single-session events. The Ministry of Ecology and Environment enforces dual carbon goals that pressure polyester-dominant supply chains in Guangdong province. Shein's supplier base clustering in the Pearl River Delta enables 72-hour design-to-delivery cycles unmatched elsewhere.
United States
Gen Z purchase behavior fragments across TikTok Shop and Instagram Checkout, displacing traditional e-commerce landing pages. The EPA and California SB 707 introduce microfiber filtration and chemical disclosure requirements affecting synthetic-heavy imports. Los Angeles-based mid-market brands adopt 3D virtual sampling platforms to compress buyer approval cycles from eight weeks to 72 hours.
France
AGEC anti-waste law mandates digital product passports with fiber origin disclosure, forcing supply chain visibility investments. The law's 2025 recycled content thresholds outpace current material certification testing capacity. Paris anchors premium positioning budgets where sustainability verification serves as a competitive differentiator rather than compliance cost.
Germany
Mid-range positioning gains share as regulatory compliance costs compress budget-tier margins. The EU Green Deal textile strategy accelerates closed-loop recycling infrastructure investment across Baden-Württemberg industrial corridors. Berlin-based resale platform operators build proprietary customer data loops that inform primary production forecasting.
India
Tier-2 and tier-3 city expansion drives domestic market penetration through Reliance Retail and Nykaa Fashion last-mile infrastructure. The Bureau of Indian Standards and DGFT navigate PLI scheme incentives for textile manufacturing scale-up. Maharashtra and Gujarat industrial zones attract mid-range sourcing shifts from China as brands diversify supplier geography.
Fast Fashion Apparel Market Competitive Landscape
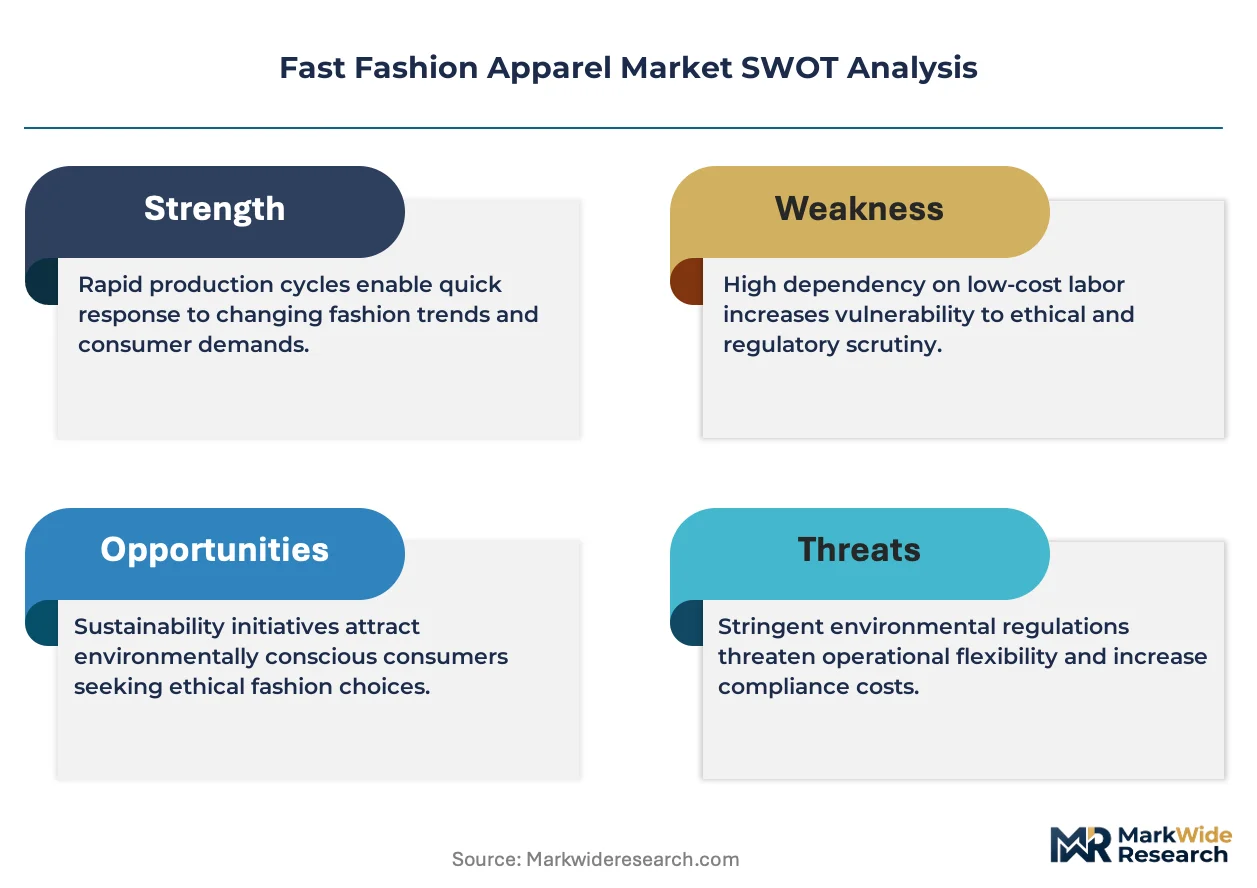
Ultra-fast algorithmic retailers and proximity-sourced legacy players split the market between velocity-driven and margin-defended models. Market structure shows tiered consolidation: three to four dominant players control algorithmic demand forecasting infrastructure while mid-scale operators compete on sustainability verification and resale platform integration. Strategic archetypes include social-native ultra-fast fashion, proximity-sourced European heritage, and technical fabric quality anchors. Competitive moves center on supply chain regionalization to reduce China concentration risk and enzymatic recycling partnerships to secure circular feedstock.
Within the social-native ultra-fast tier, Shein exemplifies algorithmic demand forecasting built around Guangdong supplier density. Among proximity-sourced European heritage operators, Inditex maintains Spanish, Portuguese, and Moroccan manufacturing relationships to sustain speed-to-market without transcontinental logistics. H&M Group occupies a position bridging resale platform integration with primary production forecasting through circular data assets. Fast Retailing anchors the technical fabric quality vector through LifeWear R&D investments targeting quality-perception requirements in Japanese and South Korean urban markets.
| Leading Market Players |
|---|
| Fast Retailing (Uniqlo) |
| Primark (AB Foods) |
| Shein |
| Urban Outfitters, Inc. |
| Mango |
| Inditex (Zara) |
| Gap Inc. |
| ASOS |
| H&M Group |
| Others |
Pricing and Supply Chain Analysis
Guangdong's Pearl River Delta supplier density compresses unit economics through cut-make-trim assembly clustering while amplifying pricing power for algorithmic retailers with captive demand forecasting. France's AGEC recycled content thresholds and EU Green Deal extended producer responsibility mandates are forcing material certification investments that widen the spread between budget-tier polyester-dominant lines and mid-range Turkey-Morocco sourced alternatives.
Pricing Analysis
The customization-premium spread separates standard polyester-cotton blend tops from algorithmic-configured limited drops, with three-tier pricing structure across premium, standard, and economy levels dominating the market. Price differentiation hinges on certification grade for EU Green Deal compliance and geographic delivery cost from Pearl River Delta versus Turkish manufacturing bases. Cost compression in the budget tier is intensifying because France AGEC testing capacity constraints outpace 2025 compliance timelines. Fast fashion's mass-market consumer segment exhibits highest price sensitivity, while mid-range positioning in German and French urban corridors commands lowest elasticity.
Supply Chain Analysis
Upstream feedstock of virgin polyester, organic cotton bales, and elastane fibers draws from petrochemical complexes in China, India, and South Korea before converging on garment assembly. Geographic supply concentration clusters in China's Guangdong province, Bangladesh's Dhaka corridor, and Vietnam's Ho Chi Minh City industrial zones. Single-source vulnerability from Shein's Pearl River Delta supplier base creates systemic disruption risk from regional lockdowns or logistics bottlenecks. Distribution runs through direct-to-consumer proprietary channels, TikTok Shop live-streaming interfaces, and third-party marketplace aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fast fashion apparel operates as a high-growth disruption where algorithmic demand forecasting and social commerce velocity are compressing design-to-delivery cycles from months to days, reshaping competitive positioning against legacy proximity-sourced operators.
For Market Incumbents: Harden supply chain regionalization through Turkey and Morocco manufacturing relationships to reduce China concentration risk from Guangdong lockdowns. Invest in enzymatic depolymerization partnerships with biotechnology firms to secure circular feedstock ahead of EU Green Deal recycled content mandates. Build proprietary resale platform infrastructure to create customer data loops that inform primary production forecasting against ultra-fast algorithmic entrants.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 and tier-3 cities through Reliance Retail and Nykaa Fashion last-mile infrastructure partnerships. Target unisex gender-fluid styling as the most penetrable segment capturing Gen Z purchase behavior shifts with minimal incumbent saturation. Deploy 3D virtual sampling software to compress buyer approval cycles and eliminate physical prototyping waste as a go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a circular infrastructure play because regulatory compliance costs will consolidate budget-tier players while rewarding closed-loop recycling investments. Acquisition target archetype: mid-scale operators with blockchain-traceability pilots and resale platform integration. The signal to watch is California SB 707 microfiber filtration mandate enforcement timelines as an inflection indicator for synthetic-dominant supply chain restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Supply Chain Regionalization | Diversification into Turkey and Morocco reduces Pearl River Delta concentration risk for European market access. |
| Resale Platform Integration | H&M Group's circular data assets create proprietary customer loops unavailable to wholesale-dependent competitors. |
| Enzymatic Recycling Partnerships | Textile-to-textile chemical recycling unlocks feedstock quality beyond bottle-to-fiber pathways for EU compliance. |
| 3D Virtual Sampling Adoption | CLO and Browzwear platforms collapse sampling calendars from eight weeks to 72 hours for Los Angeles mid-market brands. |
| Live-Streaming Commerce Infrastructure | Douyin and Xiaohongshu interfaces enable single-session sellouts that obsolete traditional inventory allocation models. |
Research Methodology
A spread of perspectives from brand supply chain directors, social commerce platform operators, textile recycling technology providers, and EU regulatory affairs consultants converged on the working assumptions shaping this analysis. Primary interviews with fast fashion sourcing executives and secondary validation against customs records, SEC apparel retailer filings, and EU Green Deal implementation guidance established the foundational dataset. Bottom-up triangulation across product type, consumer segment, distribution channel, and price tier dimensions combined with top-down macroeconomic calibration.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeling spanning garment category, gender line, channel format, and sourcing geography. CAGRs were derived from trend extrapolation against algorithmic adoption curves and regulatory compliance cost trajectories. Key forecast inputs included social commerce penetration velocity in China's Douyin ecosystem and mechanical recycling capacity buildout across European markets.
Stress conditions across petrochemical input volatility, Guangdong logistics disruption probability, and France AGEC certification pipeline constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about live-streaming commerce adoption and EU textile strategy enforcement intensity. Cross-checking against IEA industrial energy data and national customs textile trade statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Europe Second-Hand Apparel Market
Apparel & Footwear
Official Football Kits Market
Apparel & Footwear
Children's Dresses and Skirts Market
Apparel & Footwear
Ballet Pointe Shoes Market
Apparel & Footwear
Outdoor Jacket Market
Apparel & Footwear
Premium Denim Jeans Market
Apparel & Footwear
Apparel Re-Commerce Market
Apparel & Footwear
Asia-Pacific Jeans Market
Apparel & Footwear
Global Pickleball Clothing and Apparel Market
Apparel & Footwear
Men Shirts Market
Apparel & Footwear
Global Silk Pajamas Market
Apparel & Footwear
Football Kits Market
Apparel & Footwear
Asia Pacific Hats Market
Apparel & Footwear
Women's Night and Underwear Market
Apparel & Footwear
Mexico Denim Jeans Market
Apparel & Footwear
Global Shirt Market