
 Streetwear Market | 2026-2036
Streetwear Market Size, Share, and Industry Trends Forecast 2026-2036
Streetwear Market Insights
The price-performance boundary between luxury and budget streetwear is hardening. Nike sustains global manufacturing scale across footwear and apparel tiers. Supreme controls scarcity-driven drops that anchor resale economics. Fear of God differentiates through elevated minimalism at premium price points.
Streetwear denotes casual apparel rooted in skate, hip-hop, and sport cultures, typically constructed from cotton fleece, heavyweight canvas, or technical knit blends with graphic embellishment, embroidery, or deconstructed tailoring. Its commercial purpose centers on self-expression and subcultural identity signaling within youth-driven fashion economies. Sneakers command the highest margin pools across product types due to limited-edition mechanics and aftermarket premiums. Young Adults represent the fastest-expanding customer type as purchasing power matures. Collaborations between brands and artists or athletes concentrate demand spikes and reshape seasonal release calendars.
FDA textile labeling requirements, EPA chemical discharge standards for dye operations, and EU REACH substance restrictions shape material sourcing and cross-border market access for streetwear producers. California's Proposition 65 warning mandates and China's GB standards for textile safety add compliance layers for brands operating in those jurisdictions. Stakeholders must monitor how sustainability disclosure rules in Europe and North America reshape supplier qualification and consumer purchase criteria.
Market Dynamics
Digital printing and on-demand manufacturing are compressing production lead times from months to days, collapsing the traditional seasonal calendar and enabling micro-batch drops that respond to real-time social media sentiment rather than forecast-driven bulk orders.
Growth Catalysts
- Gen Z Purchasing Power:Secondary school and university students in the United States, Japan, and South Korea command discretionary income that concentrates demand around limited-edition releases and artist collaborations.
- EU REACH Substance Standards:Stricter chemical safety protocols for textile dyes and finishes are accelerating supplier consolidation toward certified mills capable of compliance documentation.
- Social Media Discovery Engines:Algorithmic content distribution on short-form video platforms is replacing traditional advertising as the primary path to brand awareness among 16-24 year old buyers.
Market Restraints
- Cotton Price Volatility:Weather-driven supply fluctuations in major producing regions compress margin predictability for fleece and canvas-dependent product lines.
- Concentrated Manufacturing Geography:Heavy reliance on Guangdong and Zhejiang province suppliers creates single-point vulnerability to regional lockdowns, port congestion, or trade policy shifts.
- Technical Limitations in Biodegradable Synthetics:Current plant-based alternatives to polyester lack the durability and colorfastness required for high-wear streetwear applications.
Strategic Opportunities
- India Apparel Market Penetration:Urban youth populations in Mumbai, Delhi, and Bangalore exhibit rising brand consciousness with limited domestic streetwear supply.
- CSRD-Driven Sustainability Disclosure:European corporate sustainability reporting mandates create first-mover advantage for brands with verified supply chain transparency.
- AI-Assisted Design Convergence:Generative tools paired with on-demand printing enable personalized graphic drops at unit economics previously reserved for mass production.
Industry Challenges
- Specialized Talent Scarcity:Shortage of technicians proficient in both digital textile printing and color management software limits production scaling for mid-tier brands.
- California Proposition 65 Compliance Burden:Warning label requirements for chemical content create litigation exposure and inventory hold risks for direct-to-consumer shipments.
- Legacy ERP Integration Friction:On-demand manufacturing platforms require real-time inventory APIs that conflict with wholesale-oriented systems at established apparel houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Streetwear Market |
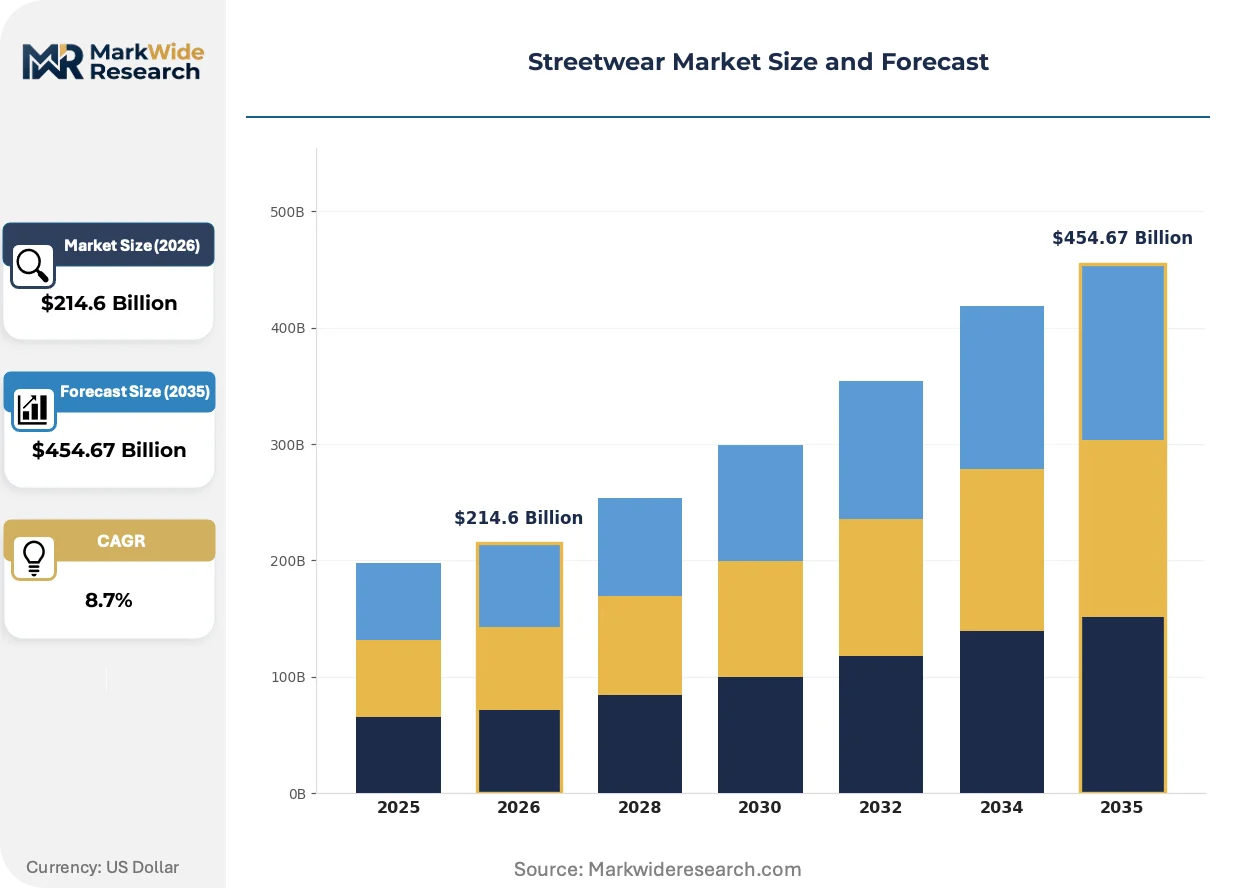
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $454.67 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Shirts, Hoodies, Sneakers, Caps Customer Type: Teenagers, Young Adults, Collectors, Influencers Price Tier: Luxury, Mid-Range, Budget, Discount Distribution Channel: Online Retail, Physical Stores, Boutiques, Collaborations |
| Companies Covered | KITH, Carhartt, Nike, Off-White, Fear of God, Supreme, Stüssy, Aimé Leon Dore, Palace Skateboards, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Streetwear Market Trends and Innovations
Production technology, regulatory disclosure requirements, and buyer discovery behavior are converging to fragment the traditional wholesale-retail hierarchy and elevate transparency as a competitive differentiator.
Direct-to-garment digital printing is decentralizing production geography by enabling micro-factories within 48-hour shipping radius of major demand clusters. Independent designers in Berlin, Los Angeles, and Seoul now operate profitable studios without minimum order commitments. This compression of physical supply chains is eroding the volume advantages historically held by centralized Asian manufacturing hubs.
EU CSRD sustainability disclosure rules are mandating granular supply chain documentation for brands above revenue thresholds. Auditors now require fiber origin tracing, dye house chemical inventories, and subcontractor labor verification. Premium positioning in European markets increasingly depends on third-party certification rather than marketing claims alone.
Resale platform integration is altering how collectors authenticate and transact limited-edition sneakers and apparel. Digital product passports with blockchain-backed provenance records are displacing paper receipts and subjective grading. Japan and South Korea lead adoption, where aftermarket premiums for verified vintage pieces now exceed original retail by multiples.
Streetwear Market Segmentation
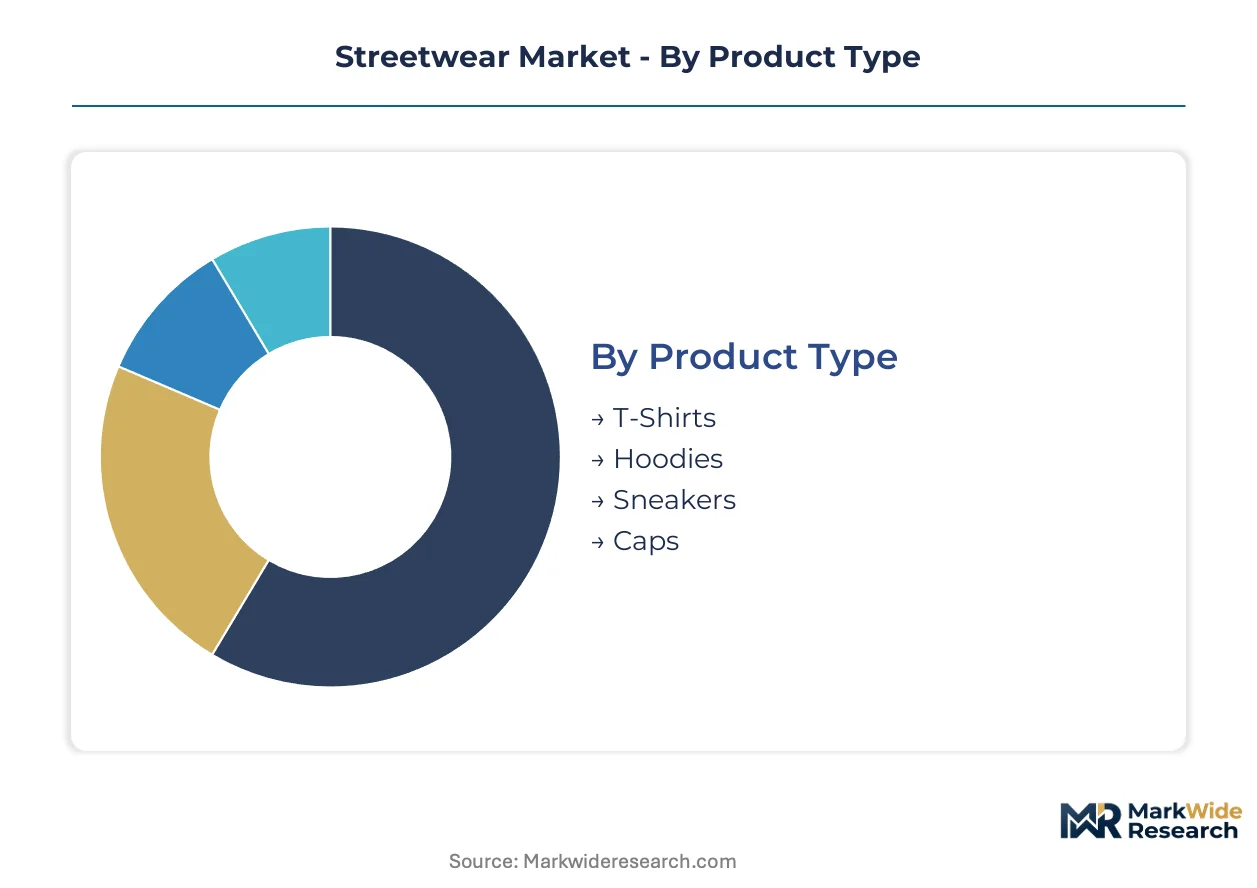
Streetwear segmentation reveals how production certification burdens, resale economics, and discovery channel preferences fragment demand across distinct buyer psychographics. Each dimension carries unique compliance obligations and margin structures that reshape competitive positioning.
Product Type:
FDA textile labeling requirements apply differentially across product categories, with skin-contact apparel facing stricter fiber disclosure rules than headwear or footwear. EPA discharge standards for dye operations concentrate compliance costs in cotton-dominant segments.
- Sneakers:Constructed from technical knit uppers, rubber outsoles, and foam midsoles with limited-edition mechanics driving aftermarket premiums. Demand concentrates in the United States and Japan where resale platform integration and blockchain-backed provenance records displace paper authentication. EU REACH substance restrictions on adhesives and synthetic leathers add material qualification layers for export-bound production.
- Hoodies:Cotton fleece or heavyweight cotton-poly blends with graphic embellishment, embroidery, or deconstructed tailoring. Young Adults in South Korea and Japan drive adoption through social media discovery on short-form video platforms. California Proposition 65 warning mandates create litigation exposure for chemical content in dyes and treatments.
- T-Shirts:Lightweight cotton or cotton-modal blends with direct-to-garment digital printing enabling micro-batch drops. Digital printing technology compresses lead times from months to days.
- Caps:Canvas, wool, or technical synthetic constructions with structured or unstructured crowns. Lower skin-contact classification reduces labeling burden versus apparel categories.
Leading the category by volume: T-Shirts. Growing fastest: Sneakers.
Customer Type:
Cost tier alignment separates discretionary spending patterns, with university-age buyers commanding sustained purchasing power versus episodic collector expenditure. Social media algorithmic distribution concentrates awareness building among digitally native segments.
- Young Adults:University students and early-career professionals with maturing purchasing power driving sustained demand for mid-range and luxury tiers. Secondary school and university populations in the United States, Japan, and South Korea concentrate around limited-edition releases and artist collaborations. This segment gains share fastest as income curves steepen.
- Teenagers:Secondary school students with parent-mediated or allowance-based budgets concentrating in budget and mid-range tiers. Social media discovery engines replace traditional advertising as primary path to brand awareness.
- Collectors:Provenance-focused buyers prioritizing scarcity and authentication over wearability. Japan and South Korea lead aftermarket adoption where verified vintage premiums exceed original retail.
- Influencers:Content creators monetizing brand partnerships and early access to generate audience engagement. Algorithmic content distribution on short-form platforms creates demand spikes around unboxing and styling content.
Young Adults anchor revenue concentration. Teenagers show steepest expansion trajectory as social media discovery penetrates younger cohorts.
Price Tier:
Margin structure stratification reflects supply chain control depth, with luxury tiers capturing scarcity premiums and budget tiers competing on Guangdong and Zhejiang province manufacturing scale.
- Luxury:Elevated minimalism at premium price points with controlled distribution and limited production runs. Scarcity-driven drops anchor resale economics and aftermarket premiums.
- Mid-Range:Balanced quality and accessibility with artist and athlete collaborations concentrating demand spikes. EU CSRD sustainability disclosure mandates create first-mover advantage for brands with verified supply chain transparency.
- Budget:Volume-driven production leveraging digital printing and on-demand manufacturing for graphic differentiation. Cotton price volatility compresses margin predictability for fleece-dependent lines.
- Discount:Closeout and overstock channels with minimal brand control and compressed margin structures. Heavy reliance on concentrated manufacturing geography creates single-point vulnerability.
Mid-Range generates highest collaboration-driven revenue spikes. Luxury climbs fastest on resale platform integration.
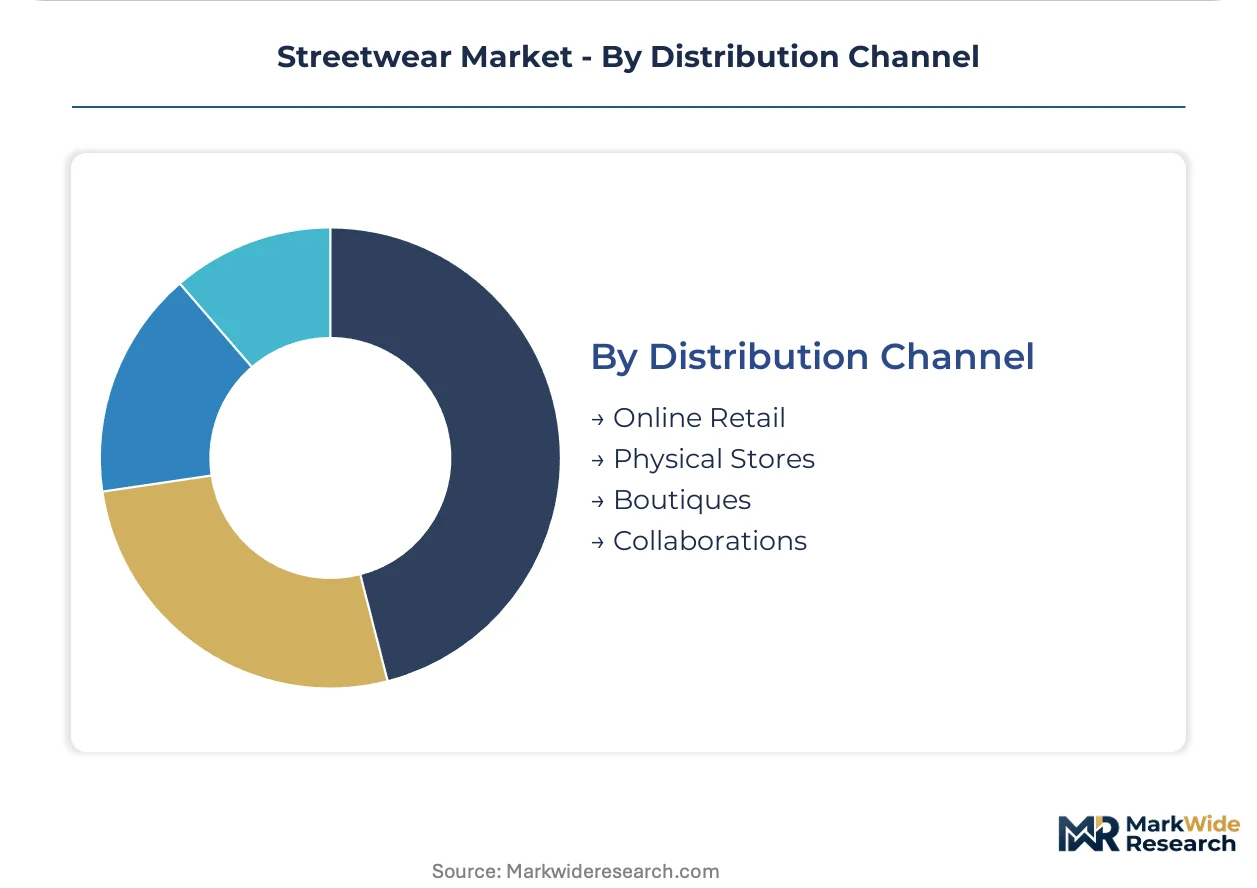
Distribution Channel:
Physical versus digital channel mix determines inventory risk profile, with on-demand manufacturing platforms requiring real-time APIs that conflict with wholesale-oriented systems at established houses.
- Online Retail:Direct-to-consumer platforms with algorithmic personalization and social media checkout integration. AI-assisted design convergence enables personalized graphic drops at unit economics previously reserved for mass production.
- Physical Stores:Flagship and mall-based locations with experiential merchandising and release-day queue mechanics. Legacy ERP integration friction limits on-demand manufacturing adoption.
- Boutiques:Curated independent retailers with localized brand curation and community anchoring. Berlin, Los Angeles, and Seoul micro-factories operate within 48-hour shipping radius without minimum order commitments.
- Collaborations:Limited-time artist and athlete partnerships with concentrated marketing spend and scarcity mechanics. Resale platform integration alters authentication and transaction patterns for verified provenance.
Online Retail leads by transaction volume. Collaborations expand most quickly as brand partnership frequency accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors streetwear design and celebrity-driven brand launches, while Tokyo's Harajuku district sustains resale platform density and provenance verification infrastructure for limited-edition mechanics.
United States
University populations in New York and Los Angeles concentrate demand around artist collaborations and scarcity-driven drops. FDA textile labeling requirements apply differentially across skin-contact apparel categories. Miami and Atlanta emerging as micro-factory hubs for direct-to-garment digital printing within 48-hour shipping radius of southeastern demand clusters.
Japan
Secondary school and young adult buyers in Tokyo and Osaka drive aftermarket premiums through blockchain-backed authentication systems. METI standards for textile safety shape import qualification for foreign brands. Fukuoka and Sapporo developing boutique retail corridors with localized curation and community anchoring independent designers.
South Korea
Seoul Capital Area youth command discretionary income concentrating around limited-edition sneaker releases and social media discovery on short-form platforms. MFDS textile safety regulations govern chemical content in dye operations. Busan-Ulsan corridor expanding on-demand manufacturing capacity for micro-batch graphic drops responding to real-time sentiment.
China
Guangdong and Zhejiang province suppliers dominate contract manufacturing for global streetwear brands despite single-point vulnerability to regional disruptions. GB standards for textile safety and dual carbon goals reshape supplier qualification criteria. Chengdu and Hangzhou emerging as domestic consumption hubs with rising brand consciousness among urban youth populations.
United Kingdom
London's Shoreditch and Soho districts anchor independent boutique density with curated brand selection and experiential merchandising. EU REACH substance restrictions on textile dyes apply to cross-border market access despite post-Brexit regulatory divergence. Manchester and Birmingham developing micro-factory networks for decentralized production geography.
Streetwear Market Competitive Landscape
Premium-margin players sit above commodity-margin players across scarcity mechanics and resale platform integration, with luxury-tier brands capturing aftermarket premiums while budget-tier competitors compete on Guangdong manufacturing scale. The vendor base stratifies into three tiers: global sportswear houses with footwear dominance, independent labels with controlled distribution, and digital-native direct-to-consumer upstarts. Consolidation pressures concentrate around M&A activity targeting provenance verification technology and strategic partnerships linking artist collaborations to seasonal release calendars.
Within the scarcity-driven independent tier, Supreme and Fear of God exemplify contrasting positioning archetypes—one through drop mechanics and resale economics, the other through elevated minimalism at premium price points. Nike occupies a position spanning multiple tiers with global manufacturing scale across footwear and apparel categories. Among legacy workwear-rooted labels, Carhartt sits within the authenticity-driven segment leveraging heritage positioning for streetwear crossover appeal.
| Leading Market Players |
|---|
| KITH |
| Carhartt |
| Nike |
| Off-White |
| Fear of God |
| Supreme |
| Stüssy |
| Aimé Leon Dore |
| Palace Skateboards |
| Others |
Pricing and Supply Chain Analysis
EU CSRD sustainability disclosure mandates gate qualified supply access and premium-tier pricing power, as brands lacking verified fiber origin tracing and dye house chemical documentation face exclusion from European retail channels while certified competitors capture scarcity premiums.
Pricing Analysis
Aftermarket resale value anchors pricing architecture across limited-edition sneakers and apparel, with provenance-verified pieces commanding multiples above original retail. Three-tier pricing structure across premium, standard, and economy levels separates luxury scarcity drops from mid-range collaboration releases and budget digital-printed basics. Cost compression in budget tiers intensifies because cotton price volatility and Guangdong manufacturing concentration squeeze margin predictability. Teenage buyers with allowance-mediated budgets exhibit highest price sensitivity, while collectors prioritizing authentication over wearability demonstrate lowest sensitivity to retail markup.
Supply Chain Analysis
Direct-to-garment digital printing platforms enable micro-factories within 48-hour shipping radius of demand clusters, displacing traditional wholesale-distributor networks. Manufacturing gravity centers on Guangdong and Zhejiang provinces in China, with emerging capacity in South Korea's Busan-Ulsan corridor and India's Mumbai-Delhi axis. Raw material flows draw from cotton belt regions, technical knit suppliers, and synthetic leather producers. Single-source vulnerability to regional lockdowns or port congestion creates systemic risk. Distribution runs through direct-to-consumer online retail, curated boutiques, and flagship experiential locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital printing and on-demand manufacturing technologies are displacing forecast-driven bulk production, compressing lead times from months to days and fragmenting competitive advantage away from centralized Asian manufacturing scale.
For Market Incumbents: Lock in scarcity mechanics through controlled distribution and blockchain-backed provenance verification before resale platform integration becomes table stakes. Invest in backward integration into certified dye houses capable of EU REACH and California Proposition 65 compliance documentation. Prioritize API development for real-time inventory systems that interface with on-demand manufacturing platforms. For New Entrants and Emerging Players: Boutique retailers in underserved Indian urban centers offer white-space access with limited domestic streetwear supply and rising brand consciousness among Mumbai, Delhi, and Bangalore youth. AI-assisted design tools paired with micro-batch digital printing enable personalized drops at unit economics previously reserved for mass production. Target university-age young adults through short-form video platform algorithmic distribution rather than traditional advertising spend. For Investors and Strategic Acquirers: CSRD-driven sustainability disclosure mandates in Europe are the leading indicator that verified supply chain transparency will separate premium-margin players from commodity competitors over the next decade. Acquisition targets should exhibit third-party certification infrastructure and fiber origin tracing capabilities. Watch for consolidation signals around provenance verification technology providers as resale platform density matures in Japan and South Korea.| Strategic Initiative | Industry Significance |
|---|---|
| On-Demand Manufacturing Scale-Up | Micro-batch production responds to real-time social media sentiment rather than seasonal forecasts. |
| Blockchain Provenance Integration | Digital product passports displace paper receipts in Japan and South Korea resale markets. |
| Sustainability Certification Investment | EU CSRD compliance documentation creates first-mover advantage in European retail channels. |
| Artist Collaboration Pipeline | Limited-edition drops with creative partners concentrate demand spikes and reshape release calendars. |
| Direct-to-Consumer Platform Launch | Algorithmic personalization and social media checkout integration bypass wholesale margin compression. |
Research Methodology
Trade publications, customs records, and SEC filings from publicly traded apparel companies formed the secondary backbone, supplemented by Nielsen retail audit data and social media platform engagement metrics. Primary fieldwork encompassed interviews with brand managers at independent labels, category buyers at multi-brand retailers, supply planners at contract manufacturers, and resale platform operations leads. Bottom-up and top-down triangulation validated volume estimates across product categories and price tiers.
Bottom-up modeling built from individual SKU-level pricing and volume assumptions, while top-down analysis cross-checked against aggregate market sizing from trade associations and regulatory filings. Segmentation dimensions encompassed product type, customer psychographic, price tier, and distribution channel, with geographic clustering by metropolitan demand density. CAGRs derived from trend extrapolation of historical growth patterns adjusted for technology adoption curves and regulatory implementation timelines. Digital printing penetration rates and social media platform user growth served as industry-specific demand drivers.
Several conditions sit outside the modeled scope, including geopolitical trade policy shifts affecting Guangdong supplier access, abrupt cotton commodity price spikes from weather events, and platform algorithm changes altering discovery mechanics. Forecasts reflect assumptions about sustained Gen Z purchasing power maturation and continued short-form video platform dominance in brand awareness. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Vegan Footwear Market
Apparel & Footwear
Boot Market
Apparel & Footwear
Insulated Jacket Market
Apparel & Footwear
Designer Sneaker Market
Apparel & Footwear
Alpaca Apparel and Accessories Market
Apparel & Footwear
Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market
Apparel & Footwear
Sports Apparel Market
Apparel & Footwear
Compression and Shapewear Market
Apparel & Footwear
Custom Cycling Clothing Market
Apparel & Footwear
Jeans Market
Apparel & Footwear
Platform Shoes Market
Apparel & Footwear
Thermal Underwear Market
Apparel & Footwear
Outdoor Jacket Market
Apparel & Footwear
Mister Cap Market
Apparel & Footwear
Fitness Apparel Market
Apparel & Footwear
Plus Size Women's Clothing Market