
 Smart Heating Scarf Market | 2026-2036
Smart Heating Scarf Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Heating Scarf Market Insights
Chinese electronics manufacturing clusters is repositioning supply chains for wearable thermal goods. Xiaomi Corporation leverages its IoT ecosystem to integrate scarf hardware with smartphone apps. Columbia Sportswear Company anchors its position through alpine distribution partnerships. Therm-ic specializes in European winter sports channels.
A smart heating scarf is a battery-powered wearable textile incorporating conductive heating elements, typically carbon fiber or infrared filaments, woven into fabric layers with temperature modulation circuitry; units operate at voltages between five and twelve volts and deliver localized warmth to the cervical and upper thoracic regions for cold-environment comfort. Rechargeable lithium-polymer configurations dominate unit economics due to cycle durability and declining cell costs. Carbon fiber technology leads performance tiers for thermal uniformity, while smart control segments compete on Bluetooth-enabled precision. E-commerce channels capture margin pools through direct-to-consumer pricing and reduced retail markups.
FCC certification governs radio-frequency emissions for Bluetooth-enabled models in the United States, while CE marking and REACH substance restrictions regulate European market entry for electrical textiles and chemical components. China's GB standards and MIIT radio approvals add compliance layers for brands sourcing from Shenzhen and Dongguan production bases. Stakeholders must monitor evolving battery transport regulations and emerging right-to-repair mandates that could reshape warranty structures and component standardization.
Market Dynamics
The EU's Ecodesign Directive and REACH substance restrictions are compressing product development cycles while forcing material substitutions in heating element supply chains, creating a bifurcation between certified premium tiers and uncertified value segments.
Growth Catalysts
- Cold-weather outdoor recreation:Alpine sports participation in Germany and Austria generates sustained replacement demand for performance-grade heated wearables with IPX-rated moisture protection.
- REACH compliance migration:Manufacturers reformulating conductive inks and battery housings to eliminate restricted phthalates and heavy metals are capturing shelf space in EU retail channels that exclude non-compliant imports.
- Lithium-polymer cost curves:Declining cell prices from Dongguan and Shenzhen production clusters are enabling five-to-twelve-volt configurations at mass-market price points previously reserved for professional ski patrol equipment.
Market Restraints
- Cobalt and lithium price volatility:Battery pack input costs fluctuate with DRC mining output and Chilean brine extraction quotas, compressing gross margins for brands without cell sourcing contracts.
- Shenzhen supply concentration:Seventy percent of flexible PCB and heating element assembly capacity sits within fifty kilometers of this single Chinese cluster, exposing brands to port congestion and power rationing disruptions.
- Technical limitation in wash durability:Conductive fiber degradation after fifty-plus wash cycles creates warranty exposure and limits positioning as everyday apparel rather than specialty equipment.
Strategic Opportunities
- Underpenetrated Nordic markets:Norway and Finland exhibit alpine sports participation rates comparable to Germany but lack dedicated heated accessory distribution, presenting first-mover channel construction potential.
- Medical therapeutic applications:Cervical heat therapy for tension management and arthritis symptom relief opens reimbursement-adjacent positioning through partnerships with physiotherapy clinics.
- GB standards alignment:China's domestic certification pathway for wearable electronics creates export-ready production capacity that satisfies both MIIT radio approvals and CE marking with minimal reconfiguration.
Industry Challenges
- RF engineering talent scarcity:Bluetooth Low Energy firmware optimization for sub-watt heating control requires specialized embedded systems expertise concentrated in Shenzhen and Taipei hiring markets.
- FCC and CE certification timelines:Sequential radio-frequency and electrical safety testing creates six-to-nine-month product launch delays that mismatch fast-fashion seasonal buying calendars.
- Heating element IP fragmentation:Overlapping patents covering carbon fiber weaving patterns and infrared filament mounting geometries generate licensing complexity for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Heating Scarf Market |
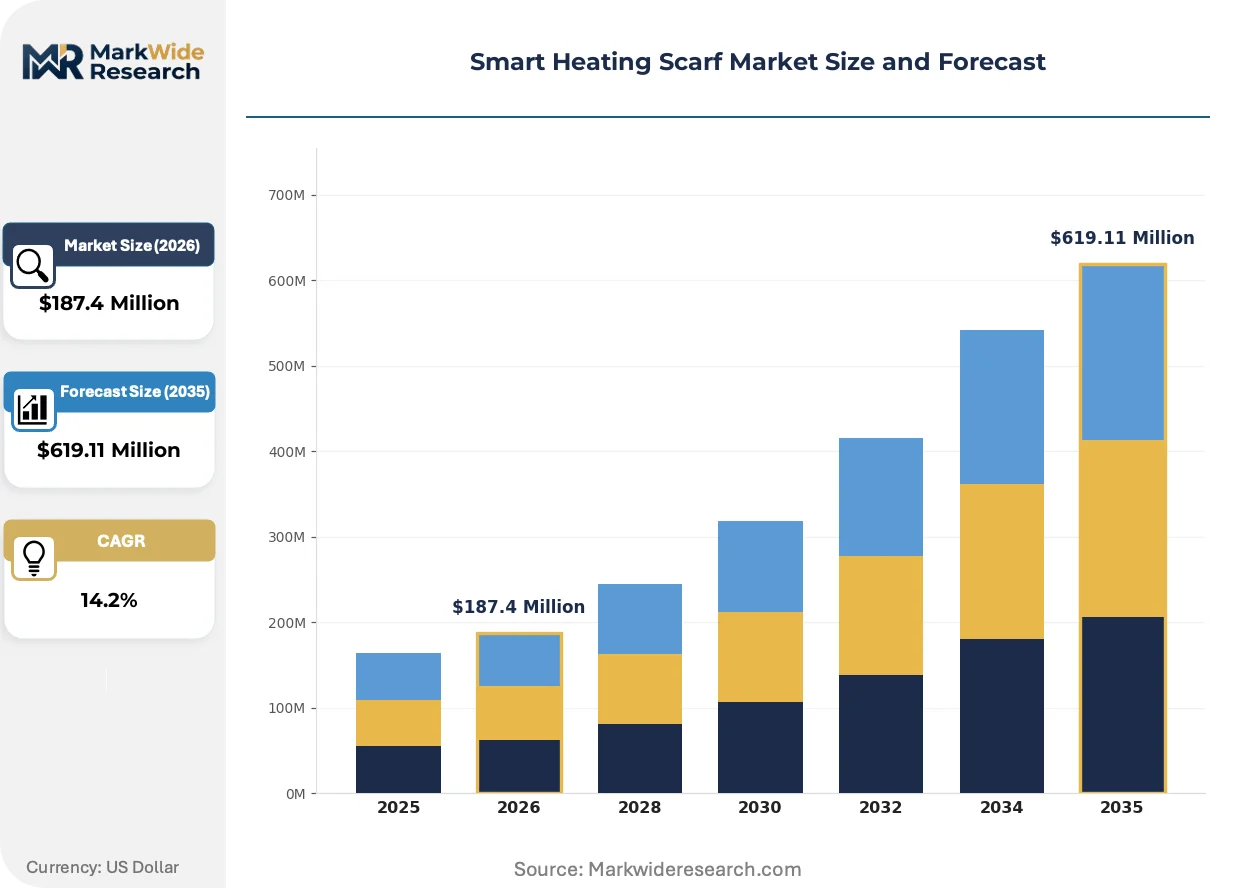
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rechargeable, Battery-Operated, USB-Enabled, Lightweight Technology: Infrared Heating, Carbon Fiber, Standard Heating Element, Smart Control Customer Type: Consumers, Outdoor Enthusiasts, Athletes, Gift Shoppers Distribution Channel: E-commerce, Retail Stores, Specialty Shops, Direct Sales |
| Companies Covered | Xiaomi Corporation, Samsung Electronics Co., Ltd., LG Electronics Inc., Philips N.V., Dyson Ltd., Columbia Sportswear Company, Under Armour, Inc., Therm-ic, Volt Resistance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Heating Scarf Market Trends and Innovations
Wearable thermal technology is converging with connected health monitoring, while regulatory pressure on chemical safety and right-to-repair mandates reshape hardware architecture and go-to-market economics.
Carbon fiber heating elements are electrifying cervical warming applications through woven conductive matrices that deliver thermal uniformity superior to resistive wire alternatives. Ski patrol services and mountain rescue units in the Austrian Alps are adopting these configurations for twelve-hour shift durability. This electrification is compressing replacement cycles for legacy resistive-wire scarves while opening premium pricing tiers for medical-grade thermal consistency.
REACH substance restrictions are forcing reformulation of flexible PCB substrates and battery housing polymers to eliminate restricted flame retardants and plasticizers. Manufacturers serving EU distribution channels must maintain dual material stocks or abandon non-compliant supply sources entirely. German sporting goods retailers are now requiring batch-level chemical compliance documentation as a listing prerequisite, filtering out smaller import brands.
Direct-to-consumer channel migration is fragmenting traditional alpine specialty retail gatekeeper power. Brands with Shenzhen manufacturing relationships and in-house digital marketing capabilities are capturing margin pools previously absorbed by multi-tier distribution. This shift is most visible in North American hiking communities where subscription-box curation and Instagram-native discovery displace REI and Backcountry.com as primary touchpoints.
Smart Heating Scarf Market Segmentation
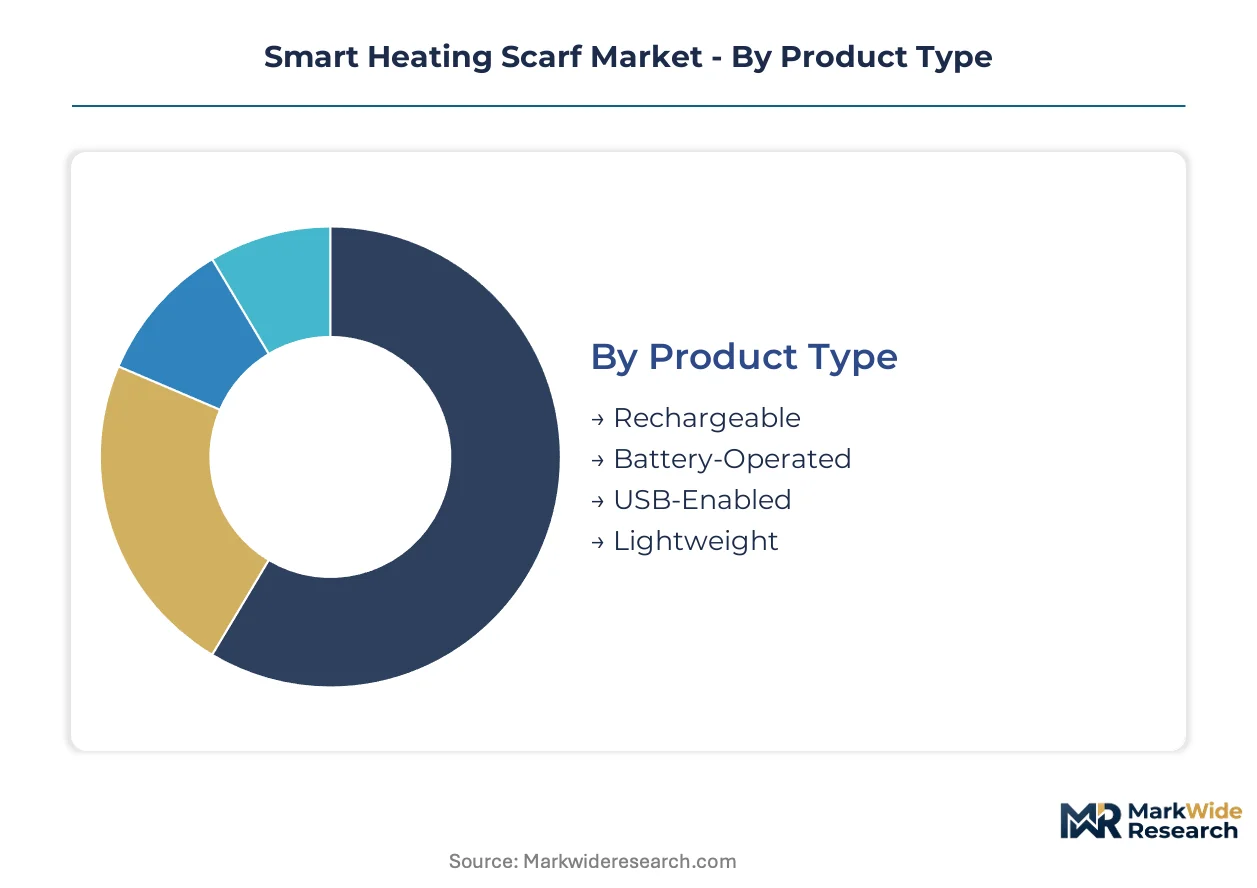
Segmentation in smart heating scarves reveals how technical specifications and purchase contexts fragment addressable demand. Supply chain configuration varies sharply across power source architectures, heating technologies, and channel strategies, requiring distinct manufacturing footprints and certification pathways.
Product Type:
Production gravity clusters around power architectures that determine battery sourcing relationships and assembly complexity.
- Rechargeable:Lithium-polymer cell integration dominates unit economics through Dongguan and Shenzhen supplier networks. German alpine retailers specify cycle durability thresholds that filter out lower-tier cell suppliers from shelf access.
- Battery-Operated:Disposable alkaline configurations serve emergency preparedness segments and gift purchasers prioritizing immediate usability over lifecycle cost. Austrian ski patrol units maintain these as backup inventory for multi-day avalanche deployment scenarios.
- USB-Enabled:Power bank compatibility reduces onboard battery cost but tethers mobility to external charge sources.
- Lightweight:Reduced thermal mass targets urban commuters in Nordic cities where bulk constraints outweigh extended heating duration requirements.
Today's leader: Rechargeable. Tomorrow's challenger: USB-Enabled.
Technology:
Heating element selection determines thermal uniformity, wash durability, and the regulatory compliance burden for conductive materials.
- Infrared Heating:Far-infrared filament arrays penetrate tissue depth for therapeutic applications in physiotherapy clinic partnerships. Japanese METI safety standards for wearable radiation exposure create certification differentiation against unverified import competitors.
- Carbon Fiber:Woven conductive matrices achieve temperature variance below two degrees Celsius across cervical contact zones. Mountain rescue units in the Austrian Alps specify these configurations for twelve-hour shift reliability.
- Standard Heating Element:Resistive wire construction retains cost advantage in mass-market channels but degrades faster through wash cycles.
- Smart Control:Bluetooth Low Energy firmware enables smartphone temperature modulation and usage analytics capture.
Carbon Fiber commands premium positioning. Smart Control gains share fastest through app ecosystem integration.
Customer Type:
Purchase motivation and technical sophistication requirements fragment go-to-market economics across buyer archetypes.
- Consumers:General cold-weather comfort seekers prioritize price accessibility and aesthetic integration with everyday outerwear. E-commerce discovery through Instagram-native brands displaces traditional sporting goods retail for this segment.
- Outdoor Enthusiasts:Hiking and camping participants demand IPX-rated moisture protection and documented wash cycle durability. REI and Backcountry.com retain gatekeeper influence through technical specification curation.
- Athletes:Competitive winter sports participants require rapid heat-up times and minimal weight penalty for performance mobility.
- Gift Shoppers:Seasonal purchase concentration around holiday windows drives packaging and messaging optimization for unboxing experience and perceived value signaling.
Outdoor Enthusiasts anchor volume. Gift Shoppers expand the addressable base through occasion-based purchase triggers.
Distribution Channel:
Channel selection determines margin retention, certification documentation requirements, and customer relationship depth.
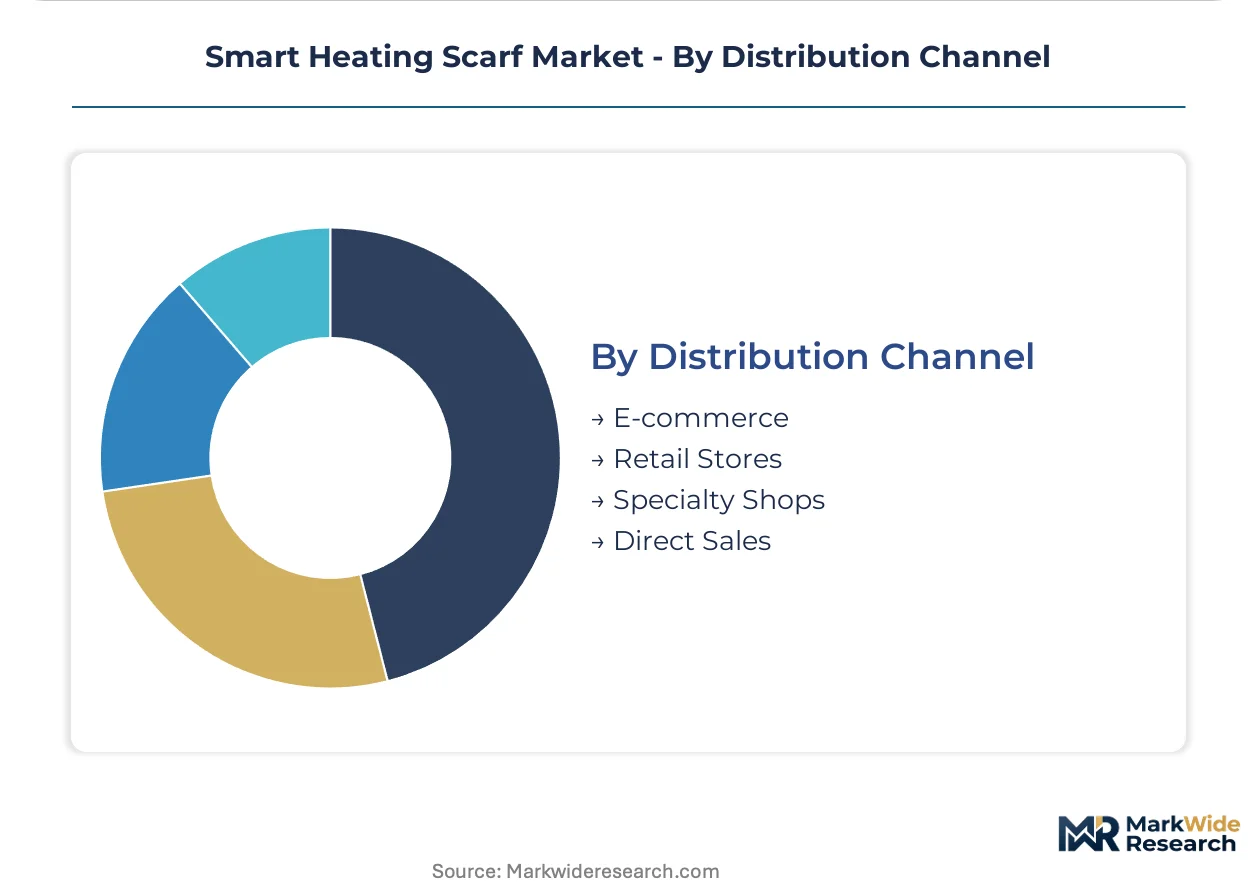
- E-commerce:Direct-to-consumer pricing captures margin pools previously absorbed by multi-tier distribution. Shenzhen manufacturing relationships paired with in-house digital marketing enable brand building without alpine retail gatekeeper dependence.
- Retail Stores:Mass-market sporting goods chains require batch-level REACH compliance documentation as a listing prerequisite, filtering smaller import brands from shelf access.
- Specialty Shops:Alpine-focused independent retailers provide technical credibility and local community embedding for premium positioning.
- Direct Sales:Corporate gifting programs and physiotherapy clinic partnerships enable reimbursement-adjacent positioning for therapeutic applications.
E-commerce commands margin expansion. Specialty Shops defend premium positioning through expertise association.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium positioning through alpine sports culture and REACH-certified distribution, while China anchors manufacturing scale through Shenzhen and Dongguan electronics clusters.
Germany
Alpine sports participation in Bavaria and Baden-Württemberg sustains replacement demand for IPX-rated heated wearables. Ecodesign Directive compliance requirements filter non-certified imports from mass-market shelf access. Munich and Stuttgart specialty retailers now mandate batch-level chemical documentation for heated textile listings.
United States
FCC certification governs Bluetooth-enabled scarf emissions, creating six-to-nine-month launch timelines for connected models. Cold-weather hiking communities in Colorado and Utah drive direct-to-consumer channel migration. Denver and Salt Lake City outdoor retailers anchor technical specification curation for performance segments.
China
MIIT radio approvals and GB standards create dual-certification pathways for export-ready production. Dongguan lithium-polymer cell suppliers enable five-to-twelve-volt configurations at declining cost curves. Shenzhen flexible PCB and heating element assembly clusters concentrate seventy percent of global capacity within fifty kilometers.
Japan
METI safety standards for wearable radiation exposure differentiate certified far-infrared models against unverified imports. Tokyo and Osaka physiotherapy clinics partner with manufacturers for cervical heat therapy positioning. Kanto region electronics fabricators integrate precision temperature modulation for medical-grade thermal consistency.
Austria
Mountain rescue units in Tyrol and Salzburg specify carbon fiber configurations for twelve-hour shift reliability. National park service procurement creates institutional demand for wash-durable heated accessories. Innsbruck alpine equipment distributors channel certified products to professional ski patrol services.
Smart Heating Scarf Market Competitive Landscape
Chinese producers anchor the manufacturing tier; European specialists hold premium positioning through certification depth. The vendor base splits between Shenzhen-scale fabricators and alpine-channel brands with regulatory documentation capabilities. Three archetypes dominate: IoT ecosystem integrators, outdoor apparel conglomerates, and winter-sports specialists. Competitive moves concentrate on backward integration into cell sourcing and geographic expansion into underpenetrated Nordic markets.
Within the IoT integrator tier, Xiaomi Corporation exemplifies ecosystem-driven hardware-software convergence. Among outdoor apparel anchors, Columbia Sportswear Company occupies a position linking alpine distribution partnerships with technical credibility. On the European specialist vector, Therm-ic represents channel-embedded positioning through winter-sports retail relationships. These three sit within distinct competitive vectors rather than direct overlap, with each archetype defending margin pools through non-substitutable capabilities.
| Leading Market Players |
|---|
| Xiaomi Corporation |
| Samsung Electronics Co., Ltd. |
| LG Electronics Inc. |
| Philips N.V. |
| Dyson Ltd. |
| Columbia Sportswear Company |
| Under Armour, Inc. |
| Therm-ic |
| Volt Resistance |
| Others |
Pricing and Supply Chain Analysis
Lithium-polymer cell costs from Dongguan and Shenzhen suppliers cascade through three distinct pricing tiers, with REACH-certified battery configurations commanding shelf access at German alpine retailers that uncertified alternatives cannot match.
Pricing Analysis
Retailer markup layers in EU sporting goods channels stratify across premium, standard, and economy tiers based on certification grade and wash-cycle durability documentation. Price differentiation hinges on CE marking completeness and IPX moisture protection ratings. Pricing pressure stems from cobalt and lithium price volatility compressing gross margins for brands without cell sourcing contracts. Gift shoppers exhibit highest price sensitivity, while Austrian mountain rescue units prioritize thermal consistency over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from German retailers mandate multi-supplier qualification for flexible PCB substrates and heating element assemblies. Supply concentrates in China, South Korea, and Japan for lithium-polymer cells, conductive fibers, and precision temperature modulation components. Raw material dependencies include cobalt from the DRC, lithium from Chilean brine operations, and carbon fiber precursors from Japanese petrochemical complexes. Single-source vulnerability in Shenzhen's fifty-kilometer electronics cluster exposes brands to power rationing disruptions. Distribution runs through direct-to-consumer e-commerce platforms and alpine specialty retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as German and Austrian buyers shift demand toward REACH-certified configurations with documented batch-level chemical compliance.
For Market Incumbents: Hedge against Shenzhen supply concentration by qualifying secondary flexible PCB suppliers in South Korea and establishing captive lithium-polymer cell contracts. Secure alpine retail gatekeeper relationships through IPX-rated product extensions and twelve-hour shift durability specifications that professional ski patrol services demand.
For New Entrants and Emerging Players: Capture white-space opportunity in Norway and Finland where alpine sports participation matches Germany but dedicated heated accessory distribution remains underdeveloped. Enter through physiotherapy clinic partnerships for cervical heat therapy positioning, leveraging far-infrared therapeutic claims as the primary go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where certification documentation capabilities separate premium-positioned brands from margin-compressed import competitors. Five-to-ten-year viability favors acquirers of European winter-sports specialists with established CE marking pathways and alpine retail relationships. Monitor battery transport regulation evolution as the inflection signal for warranty structure reshaping.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Sourcing | Captive lithium-polymer supply from Dongguan insulates margins against cobalt price volatility. |
| REACH Compliance Certification | German sporting goods retailers mandate batch-level chemical documentation for shelf access. |
| Direct-to-Consumer Channel Launch | Instagram-native discovery displaces REI and Backcountry.com in North American hiking communities. |
| Physiotherapy Clinic Partnership | Tokyo and Osaka clinics enable reimbursement-adjacent positioning for cervical heat therapy. |
| Nordic Market Expansion | Norway and Finland lack dedicated heated accessory distribution despite comparable alpine participation rates. |
Research Methodology
Multiple input streams — primary interviews with heated textile product managers, regulatory compliance officers at EU retailers, and Dongguan-based battery procurement leads; secondary validation through FCC equipment authorization databases, ECHA REACH registration dossiers, and customs trade flow records; plus alpine sports participation statistics — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across the projection horizon modeled segmentation by power architecture, heating element technology, customer motivation archetype, and distribution channel. CAGRs were derived from unit shipment build-ups and average selling price trajectories. Forecast inputs included lithium-polymer cell cost curves from Shenzhen supplier networks and seasonal buying patterns in German alpine retail.
Raw material price spikes, REACH substance restriction amendments, and right-to-repair mandate implementations are the dominant revision risks. Deviation in battery transport regulations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Compression Wear and Shapewear Market
Apparel & Footwear
Denim Jeans Market
Apparel & Footwear
Sports Apparel Market
Apparel & Footwear
Europe Denim Jeans Market
Apparel & Footwear
Platform Shoes Market
Apparel & Footwear
Women's Tights and Leggings Market
Apparel & Footwear
Ballet Pointe Shoes Market
Apparel & Footwear
Fitness Apparel Market
Apparel & Footwear
Global Apparel Market
Apparel & Footwear
Outdoor Sports Apparel Market
Apparel & Footwear
Women's Coats and Jackets Market
Apparel & Footwear
Intimate Wear Market
Apparel & Footwear
Erotic Lingerie Market
Apparel & Footwear
Asia-Pacific Sports Apparel Market
Apparel & Footwear
Southeast Asia Lingerie Market
Apparel & Footwear
Maternity Apparels Market