
 Jeans Market | 2026-2036
Jeans Market Size, Share, and Industry Trends Forecast 2026-2036
Jeans Market Intelligence
The capital-intensity divergence between vertically integrated mills and brand licensors is rotating competitive advantage toward supply-chain owners. Levi Strauss & Co. leverages its proprietary Water Jeans are trousers constructed from cotton twill fabric, typically weighing 12 to 14.5 ounces per square yard, with a distinctive diagonal rib weave created by passing the weft thread under two or more warp threads. The garment serves as durable casual wear across occupational, social, and fashion contexts worldwide. Skinny and straight-leg cuts dominate volume sales in mature markets, while eco-friendly material formulations represent the fastest-expanding margin pool as brands absorb green premiums. Women's unisex styling lines show particular dynamism where stretch-denim blends enable crossover appeal. REACH regulations in Europe restrict hazardous chemical inputs in textile finishing, while EPA wastewater discharge rules in the United States elevate treatment costs for domestic laundries. The EU Green Deal's textile strategy further mandates extended producer responsibility schemes that reshape cost structures across the value chain. Stakeholders must monitor how chemical compliance timelines intersect with consumer willingness to pay for certified sustainable construction. Waterless dyeing technology and REACH chemical compliance timelines are compressing traditional finishing capacity while rerouting capital toward certified organic cotton sourcing and closed-loop recycling infrastructure. Get the full picture before you read further. Download a free sample with table of contents, companies, segments, and methodology. Digital finishing technologies and chemical transparency mandates are restructuring how denim manufacturers compete on speed, compliance, and material storytelling rather than volume scale alone. Laser-ablation surface treatment is decomposing the traditional potassium permanganate spray-and-wash sequence that dominated vintage-effect production. Specialty mills in Los Angeles and Valencia are retrofitting Jeanologia and Tonello systems to eliminate water-intensive distressing. The technology is decomposing competitive advantage away from low-labor-cost wet processing zones toward proximity manufacturing clusters that can iterate designs in 72-hour cycles. REACH Annex XVII restrictions on chromium VI and certain azo dyes are forcing reformulation of dark-indigo sulfur dye recipes across European finishing houses. ECHA compliance deadlines in 2026 are compressing R&D timelines for alternative reducing agents. German and Dutch brands with direct retail exposure are absorbing 8-12% cost premiums for certified chemical-free construction to preempt liability exposure. Direct-to-consumer resale authentication services are fragmenting traditional wholesale relationships as Gen Z buyers prioritize verified secondhand over new entry-price denim. Platforms specializing in vintage Levi's and Japanese raw denim are capturing margin that previously flowed through department store concessions. The shift is most visible in United States coastal metros and London, where circular economy participation rates exceed national averages by 40 percentage points. Jeans manufacturers compete across four distinct axes that reshape margin capture and capital allocation. Product silhouettes and material formulations determine technical differentiation, while customer targeting and price positioning govern distribution economics. Substitute pressure from athleisure trousers and performance knit bottoms weighs most heavily on legacy cuts that lack stretch engineering or styling versatility. Straight leg retains volume leadership; skinny holds the steepest expansion curve. Cost tier stratification separates commodity twill from certified sustainable inputs that absorb green premiums across German and Japanese retail channels. Conventional denim dominates unit economics; eco-friendly formulations are climbing the fastest. Application context varies sharply across occupational, social, and developmental use cases that dictate fit engineering and durability specifications.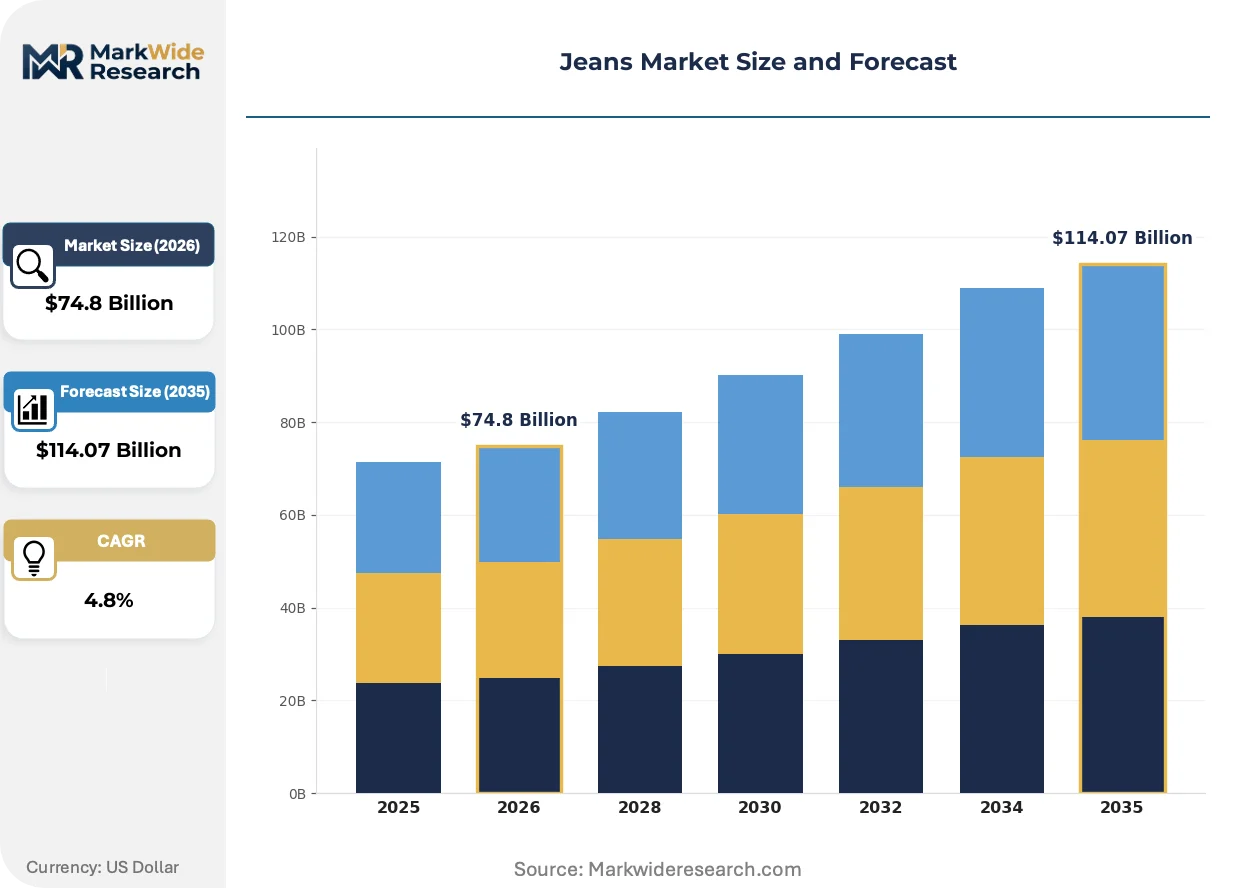
Market Dynamics
Growth Catalysts
Market Restraints
Strategic Opportunities
Industry Challenges
Report Scope
MarkWide ResearchAttributes Details Report Title Jeans Market Market Size in 2026 $74.8 Billion Market Size in 2035 $114.07 Billion CAGR (2026 – 2036) 4.8% Historical Year 2020-2024 Base Year 2025 Forecast Period 2026-2036 Segmentation Companies Covered Levi Strauss & Co., Kontoor Brands, Inc., PVH Corporation, Gap, Inc., H&M Group, VF Corporation, Inditex, American Eagle Outfitters, Inc., Bestseller A/S, Others Regions Covered Jeans Market Strategic Shifts & Innovations
Jeans Market Segmentation
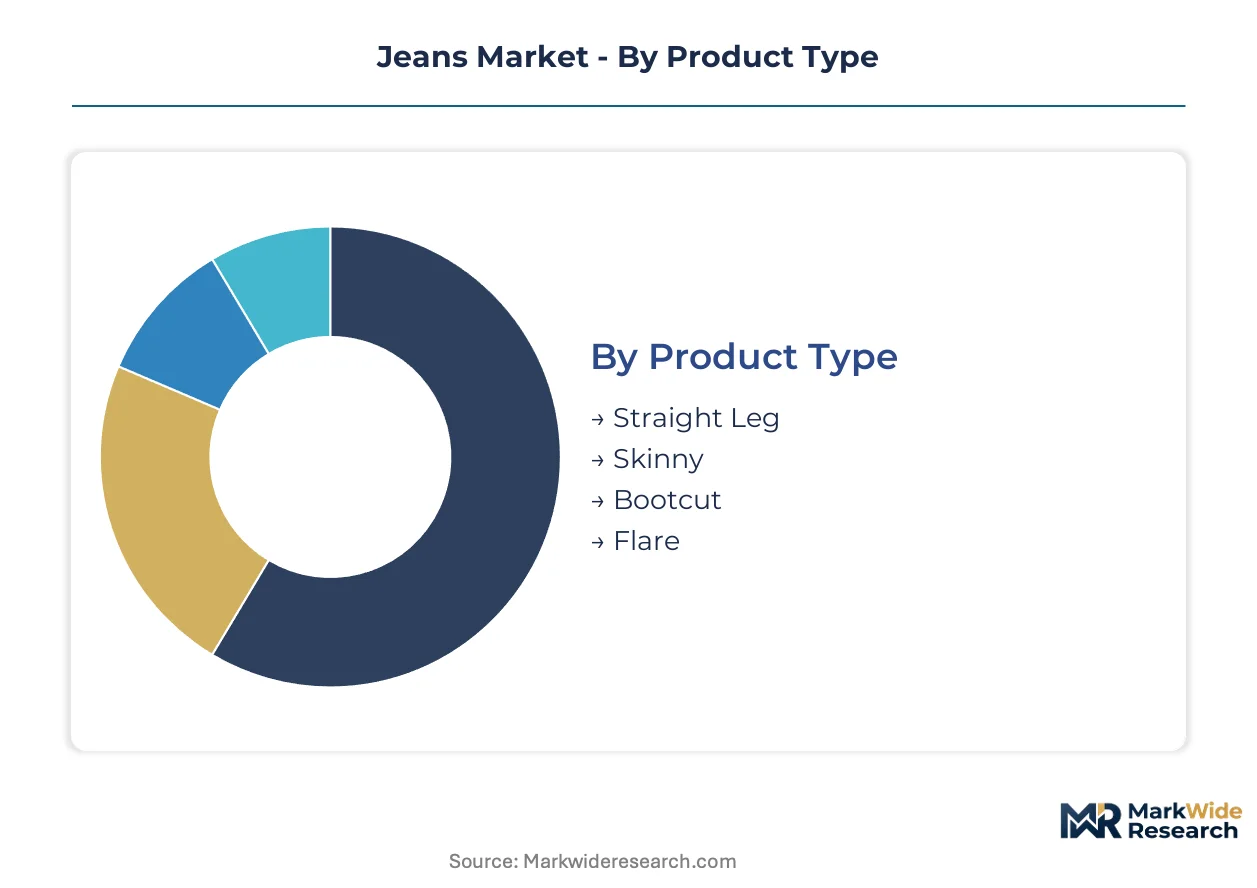
Product Type:
Material:
Customer Type:
Women's segmentation leads revenue concentration; unisex is gaining share fastest.
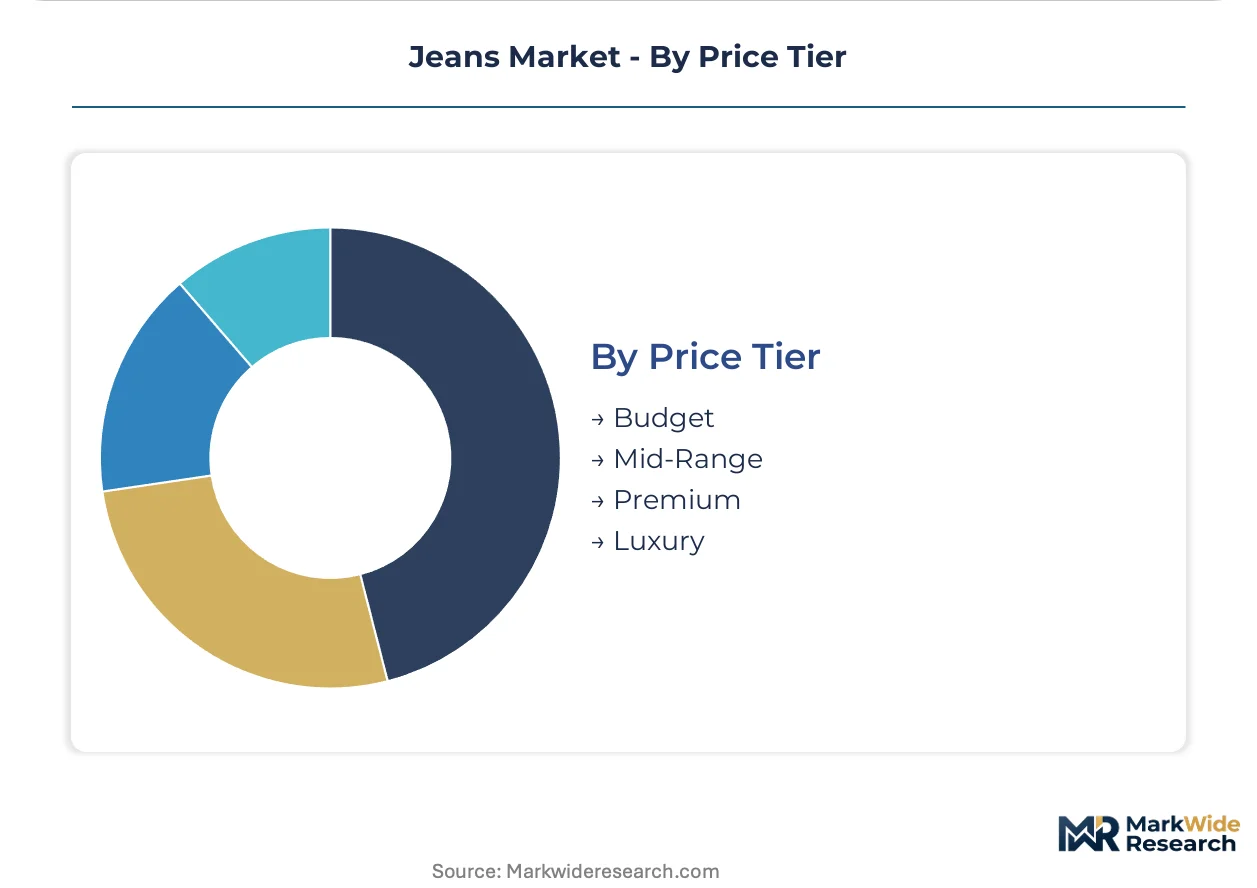
Price Tier:
Margin structure concentrates in certified sustainable construction where German and Dutch brands absorb 8-12% cost premiums to preempt REACH liability exposure.
- Budget:Mass-market positioning through value retailers and hypermarket channels. Price compression from Pakistan and Bangladesh supply concentration squeezes mill margins without backward yarn integration.
- Mid-Range:Department store and specialty retailer placement with seasonal fashion cycling. Inditex rapid-response manufacturing compresses design-to-rack timelines against traditional wholesale calendars.
- Premium:Limited-run selvedge and Japanese raw denim with provenance storytelling. Tokyo and Osaka vintage resale auctions are establishing price benchmarks that validate production investment.
- Luxury:Designer collaboration and artisanal finishing with blockchain-enabled authentication. Direct-to-consumer resale platforms are capturing margin previously flowing through department store concessions.
Mid-range commands absolute volume; premium tier shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jeans consumption patterns diverge sharply across mature economies: American buyers favor workplace-casual versatility while Japanese collectors drive scarcity premiums through archival sourcing. European demand clusters around regulatory-compliant sustainable construction. Emerging manufacturing hubs in South Asia supply volume, but regulatory pressure and energy constraints are redrawing production maps.
United States
Hybrid office policies across Silicon Valley and Manhattan financial districts normalize denim in professional settings. EPA wastewater discharge rules elevate treatment costs for domestic laundries in Los Angeles and North Carolina finishing clusters. The Inflation Reduction Act's clean manufacturing credits offset capital expenditure for laser-finishing equipment upgrades in California specialty mills.
Germany
REACH Annex XVII chemical restrictions force reformulation of sulfur-based dark-indigo recipes across European finishing houses. The EU Green Deal's extended producer responsibility mandates accelerate brand investment in take-back programs and fiber-to-fiber recycling partnerships. Berlin and Hamburg host the densest concentration of certified organic cotton retail placement, absorbing 8-12% cost premiums for chemical-free construction.
Japan
Archive denim auctions in Tokyo and Osaka establish price benchmarks validating investment in limited-run selvedge production. METI standards for textile chemical labeling reinforce consumer preference for provenance transparency. Kojima district in Okayama Prefecture remains the global center for shuttle-loom selvedge manufacturing, supplying heritage brands and independent ateliers.
United Kingdom
Vintage revival cycles in London and Manchester drive intermittent replenishment of flare silhouettes without consistent volume. The Competition and Markets Authority's greenwashing enforcement pressures brands to substantiate sustainability claims with third-party certification. Leicester's garment district concentrates fast-fashion denim finishing, though labor compliance audits have compressed supplier margins.
Bangladesh
Wet processing capacity clusters in Dhaka and Chittagong export zones create vulnerability to energy rationing and trade preference shocks. The central bank's export refinancing schemes partially offset cotton price volatility for mills lacking backward yarn integration. German and Dutch brands source certified chemical-free construction from compliant factories in the Ashulia industrial corridor.
Jeans Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with competitive advantage rotating toward supply-chain owners who control finishing technology and organic cotton sourcing. The market structure rewards capital deployment into waterless dyeing infrastructure and rapid-response manufacturing capabilities. Two strategic archetypes dominate: heritage workwear licensors anchored in western specialty channels, and fast-fashion conglomerates competing through compressed design-to-rack cycles. Dominant competitive moves include strategic partnerships for closed-loop recycling infrastructure and geographic expansion into premium vintage resale authentication services.
Within the heritage denim tier, Levi Strauss & Co. and Kontoor Brands, Inc. exemplify supply-chain control strategies, while Inditex occupies a position exemplifying rapid-response manufacturing compression. These three anchors illustrate how competitive positioning diverges between proprietary finishing technology ownership and design-iteration velocity.
| Leading Market Players |
|---|
| Levi Strauss & Co. |
| Kontoor Brands, Inc. |
| PVH Corporation |
| Gap, Inc. |
| H&M Group |
| VF Corporation |
| Inditex |
| American Eagle Outfitters, Inc. |
| Bestseller A/S |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between German and Dutch brands and certified organic cotton cooperatives lock in supply access while anchoring price visibility against conventional cotton volatility. These contracts absorb 8-12% cost premiums for REACH-compliant chemical-free construction, creating tiered margin structures that separate sustainability-certified production from commodity wet processing.
Pricing Analysis
Spot purchasing for conventional 12-14.5 ounce cotton twill dominates budget-tier transactions, while premium-mid-economy pricing differentiation rests on certification grade and brand provenance. German retailers absorb green premiums for GOTS organic and OEKO-TEX labels to preempt ECHA liability exposure. Cost compression in mass-market channels is intensifying because Pakistan and Bangladesh supply concentration exposes mills to energy rationing without backward yarn integration. Fast-fashion buyers show highest price sensitivity; Japanese vintage collectors exhibit least.
Supply Chain Analysis
Inventory lead times stretch 90-180 days for South Asian wet processing clusters, compressing to 72-hour cycles in Los Angeles and Valencia laser-finishing installations. Raw material flows draw from organic cotton cooperatives in Turkey and India, elastane suppliers in South Korea, and indigo dye houses in China. Single-source vulnerability concentrates in Dhaka and Chittagong export zones where energy rationing disrupts finishing capacity. Distribution runs through department store concessions, direct-to-consumer platforms, and Western specialty ranch supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical athleisure trousers with moisture-wicking properties threaten denim's hold on casual occasions, forcing incumbents to defend styling versatility and workplace normalization gains.
For Market Incumbents: Consolidate proprietary finishing technology ownership through laser-ablation equipment deployment in California and European proximity clusters. Anchor backward integration into organic cotton sourcing to offset REACH compliance cost premiums and preempt supply disruption from South Asian energy rationing. For New Entrants and Emerging Players: Lead with blockchain-enabled provenance tracking to decompose information asymmetry in certified sustainable construction. Target Japan's premium vintage resale channel where Tokyo and Osaka auction benchmarks validate limited-run selvedge production investment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors supply-chain owners with captive waterless dyeing infrastructure. Five-to-ten year viability hinges on extended producer responsibility scheme compliance and fiber-to-fiber recycling partnership access. Watch EU Green Deal textile strategy implementation timelines as inflection indicator for capital rotation toward certified sustainable production.| Strategic Initiative | Industry Significance |
|---|---|
| Waterless Dyeing Technology Deployment | Jeanologia and Tonello system adoption eliminates potassium permanganate spray sequences in Los Angeles specialty mills. |
| Extended Producer Responsibility Partnership | Fiber-to-fiber recycling alliances with German brands satisfy EU Green Deal textile strategy mandates. |
| Blockchain Provenance Integration | Distributed ledger systems with organic certification decompose information asymmetry for conscious buyers. |
| Laser-Finishing Technician Training | Vocational pipeline expansion addresses precision ablation skill shortages outpacing current output. |
| Premium Vintage Resale Authentication | Direct-to-consumer platforms capture margin previously flowing through department store concessions. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across brand managers, category buyers at German and Japanese retailers, denim mill procurement leads, and laser-finishing technical directors. Secondary validation drew from ECHA REACH filings, EU Green Deal textile strategy documents, EPA wastewater discharge records, and customs trade data for cotton and elastane flows. Bottom-up volume triangulation against top-down macroeconomic anchors ensured cross-verification.
Across the projection horizon, the analytical framework modeled product silhouette, material formulation, customer application context, and price tier positioning. CAGRs were derived from segment-level growth trajectory analysis applied to baseline volume estimates. Forecast inputs incorporated workplace dress code normalization rates, REACH Annex XVII compliance timelines, and laser-finishing equipment penetration curves.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated technical athleisure substitution would require recalibration. Forecasts reflect documented assumptions on consumer willingness to pay for certified sustainable construction and cotton price volatility ranges. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Sports Apparel Market
Apparel & Footwear
New Smart Wardrobe Market
Apparel & Footwear
Southeast Asia Lingerie Market
Apparel & Footwear
Erotic Lingerie Market
Apparel & Footwear
Europe Jeans Market
Apparel & Footwear
Sailing Jackets Market
Apparel & Footwear
Children's Suits and Ensembles Market
Apparel & Footwear
France Denim Jeans Market
Apparel & Footwear
Maternity Apparels Market
Apparel & Footwear
Gymnastic Leotards Market
Apparel & Footwear
Fanny Packs Market
Apparel & Footwear
Men's Coats and Jackets Market
Apparel & Footwear
Decorated Apparel Market
Apparel & Footwear
Menswear Market
Apparel & Footwear
Asia-Pacific Denim Jeans Market
Apparel & Footwear
Insulated Jacket Market