
 Sports Inspired Clothing Market | 2026-2036
Sports Inspired Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Inspired Clothing Market Analytics
Digital textile printing and on-demand manufacturing is reshaping production economics in sports inspired clothing, collapsing lead times from months to days. Nike, Inc. leverages its proprietary Flyknit technology to control material waste and customize regional output. Adidas Group anchors its competitive stance through automated Speedfactories that localize production near European and North American demand clusters. PUMA SE differentiates via partnerships with esports leagues, capturing younger demographics outside traditional athletic channels.
Sports inspired clothing encompasses garments engineered with moisture-wicking synthetic blends, four-way stretch constructions, and seam-free knitting techniques designed for physical performance and casual crossover wear. Primary commercial purpose spans gym-to-street functionality where technical specifications merge with everyday aesthetics. Athleisure commands the largest revenue pool as workplace dress codes relax across corporate environments, while online stores represent the fastest-expanding sales channel driven by direct-to-consumer platform investments. Polyester dominates material volumes due to cost efficiency and recyclability pathways, though spandex blends command premium positioning in compression and yoga segments.
REACH in Europe mandates restricted substance lists for textile dyes and finishes, forcing reformulation of water-repellent coatings across supplier networks. The US Consumer Product Safety Commission enforces flammability standards for synthetic activewear sold to youth segments, shaping material selection in children's lines. California's Safer Consumer Products regulations extend disclosure requirements to perfluorinated compounds used in performance outerwear. Stakeholders must monitor emerging extended producer responsibility frameworks that will shift end-of-life collection costs onto brand owners across multiple jurisdictions.
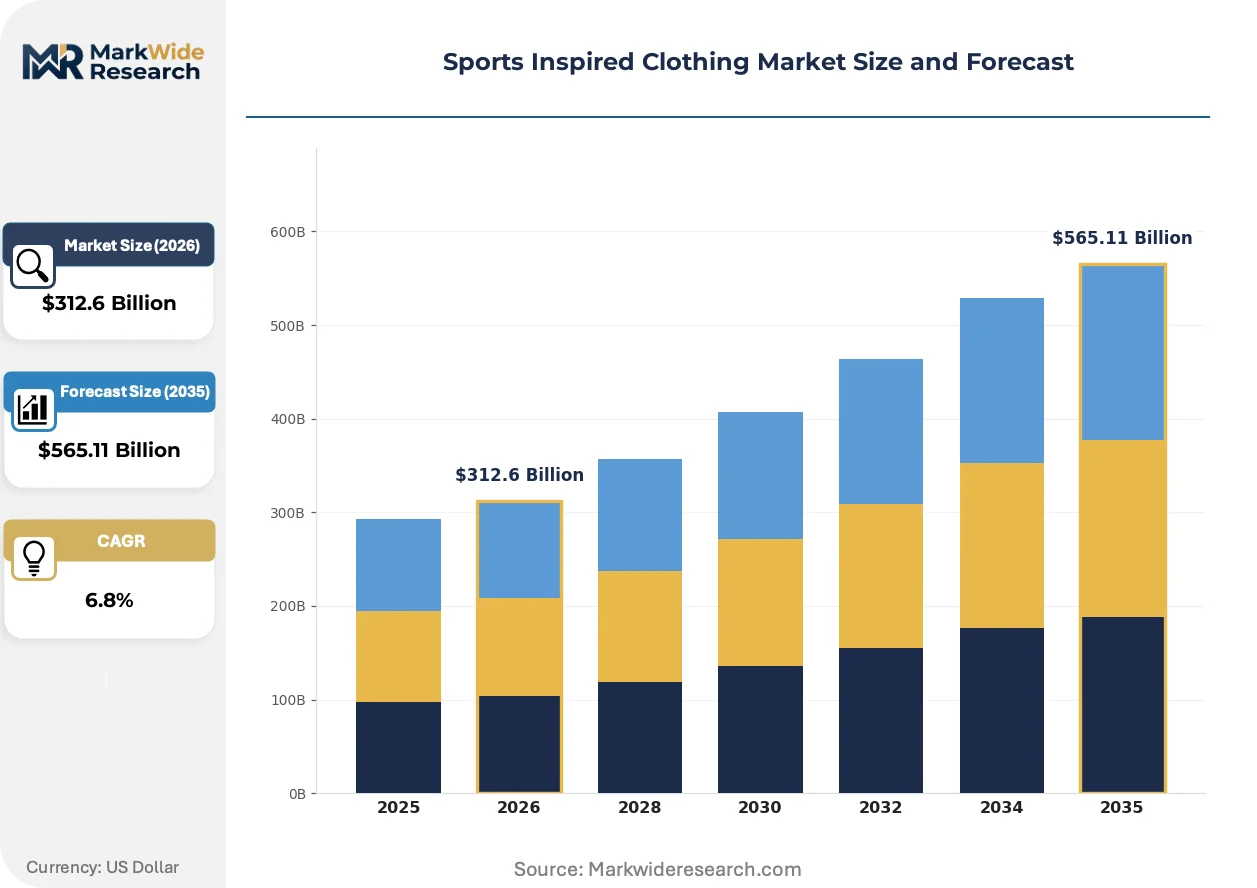
Market Dynamics
Digital textile printing and on-demand manufacturing are collapsing production lead times from months to days, forcing legacy batch-manufacturing networks to restructure capital deployment and inventory strategies.
Growth Catalysts
- REACH compliance mandates:ECHA's restricted substance lists for textile dyes are accelerating reformulation investments across European supplier networks, creating first-mover advantages for compliant chemical innovators.
- Esports league partnerships:Competitive gaming demographics outside traditional athletic channels are unlocking incremental revenue pools through licensed apparel and team merchandise.
- Recyclability pathways:Post-consumer polyester recovery infrastructure is expanding material input options for circular production models, reducing virgin polymer dependency.
Market Restraints
- Petrochemical input volatility:Crude oil price swings directly compress margins on polyester and spandex blends, forcing hedging costs onto mid-tier manufacturers without backward integration.
- Supplier concentration in Zhejiang Province:Synthetic textile weaving capacity clusters in eastern China, exposing brands to single-point disruption risks from regional power rationing or logistics bottlenecks.
- Perfluorinated compound substitution:Water-repellent coatings face technical performance gaps versus legacy chemistries, limiting immediate compliance with California's Safer Consumer Products regulations.
Strategic Opportunities
- India's expanding fitness infrastructure:Urban gym penetration and marathon participation rates are creating underexploited demand for performance-to-casual crossover garments in tier-1 and tier-2 cities.
- EU Green Deal procurement incentives:Public sector uniform contracts with recycled content mandates are opening institutional volume channels for certified sustainable sportswear.
- AI-driven sizing algorithms:Machine learning fit prediction is converging with 3D body scanning to reduce return rates in direct-to-consumer channels, compressing last-mile logistics costs.
Industry Challenges
- Seam-free knitting technician scarcity:Advanced circular knitting machine programming requires specialized vocational training that outpaces current apprenticeship pipeline output in manufacturing hubs.
- Multi-jurisdiction EPR compliance:Extended producer responsibility frameworks shifting end-of-life collection costs onto brand owners demand new reverse logistics infrastructure across divergent national implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Inspired Clothing Market |
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activewear, Athleisure, Sports Equipment, Footwear Target Customer: Fitness Enthusiasts, Casual Wearers, Athletes, Competitors Material: Polyester, Cotton, Nylon, Spandex Sales Channel: Online Stores, Retail Outlets, Wholesale Distributors, Brand Boutiques |
| Companies Covered | Nike, Inc., Adidas Group, PUMA SE, Under Armour, Inc., Lululemon Athletica Inc., New Balance Athletics, Inc., ASICS Corporation, Gymshark Limited, Fila Holdings Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Inspired Clothing Market Evolving Landscape
Three interconnected shifts are restructuring how sports inspired clothing moves from design concept to consumer possession, with implications for capital intensity, geographic production placement, and competitive differentiation.
Seam-free knitting technology eliminates cut-and-sew assembly through computerized circular machines that construct garments in single-piece tubes. Performance yoga and compression wear brands are adopting these systems at accelerating rates to reduce labor inputs and material waste. Traditional cut-make-trim subcontracting networks across Southeast Asia are rendering obsolete as brands relocate automated production closer to demand clusters.
California's Safer Consumer Products regulations now mandate disclosure and eventual phase-out of perfluorinated compounds in performance outerwear, forcing reformulation of durable water-repellent finishes. The industrial consequence is a supplier scramble for silicone-based and hydrocarbon alternatives that meet technical specifications without toxicity profiles. Youth-oriented synthetic activewear lines face the most compressed compliance timelines, with several brands accelerating third-party certification investments to maintain shelf access.
Direct-to-consumer platform investments are disintermediating traditional wholesale relationships as primary revenue channels for emerging sportswear labels. Boutique fitness studios and micro-influencer networks are replacing department store floor space as discovery mechanisms, particularly for women's athleisure. This channel rotation is most visible in North American and Western European urban markets where digital-native purchasing behaviors dominate millennial and Generation Z demographics.
Sports Inspired Clothing Market Segmentation
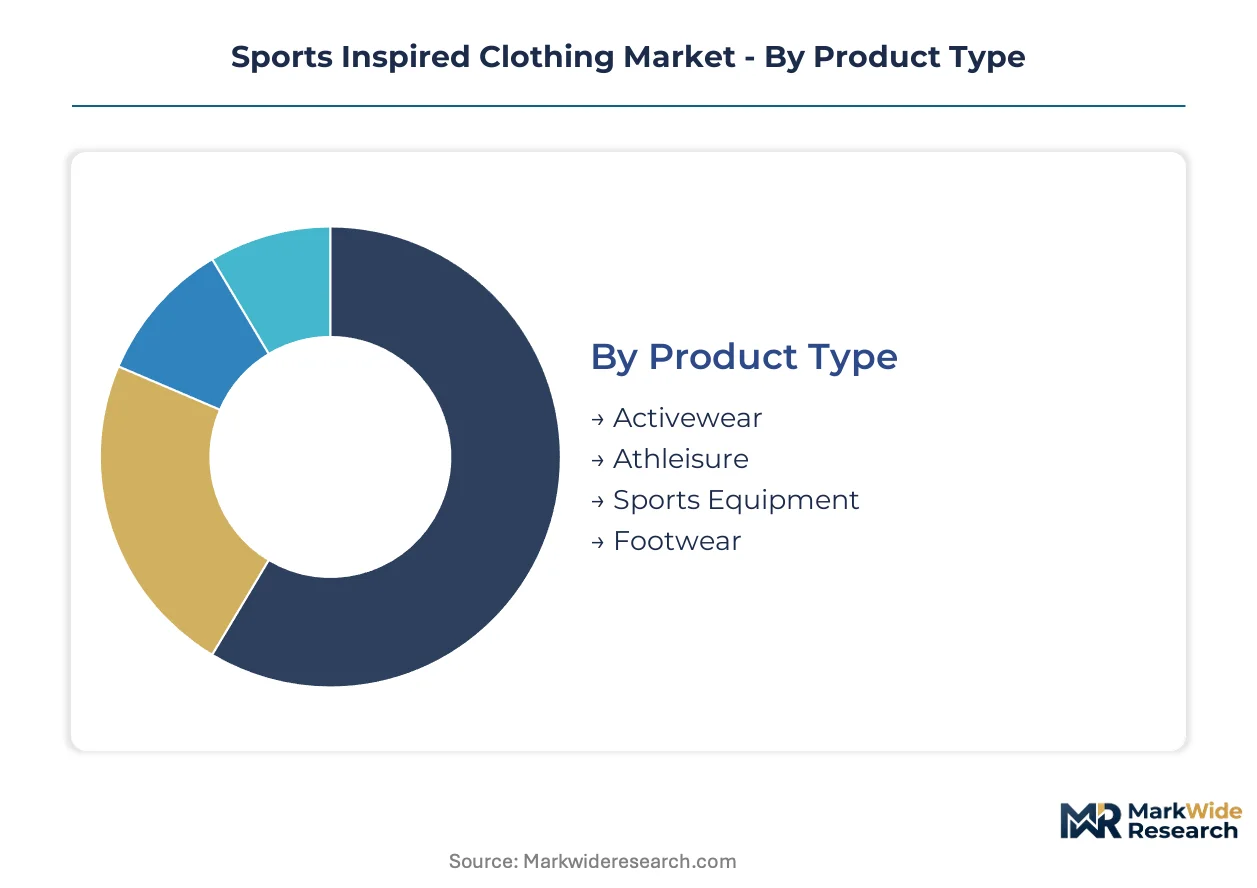
Sports inspired clothing segments diverge sharply by technical specification and purchase context. Material chemistry and channel economics create distinct margin profiles that reshape how brands allocate R&D and distribution capital.
Product Type:
Cost tier stratification separates commodity basics from engineered performance garments with specialized finishing.
- Activewear:Engineered with moisture-wicking synthetic blends and four-way stretch constructions for gym-to-street functionality. Demand concentrates in corporate environments where dress codes relax, driving volume through direct-to-consumer platforms.
- Athleisure:Merges technical specifications with everyday aesthetics through seam-free knitting and compression fabrics. Urban centers across tier-1 Chinese cities anchor consumption as middle-class consumers expand wardrobe crossover purchases.
- Sports Equipment:Performance accessories and protective gear with specialized material requirements.
- Footwear:Technical soles and upper constructions spanning running, training, and lifestyle categories.
Athleisure commands the established base. The steepest expansion runs through Activewear.
Target Customer:
Application intensity varies from professional training regimens to occasional lifestyle adoption.
- Fitness Enthusiasts:High-frequency purchasers prioritizing technical performance and durability metrics. Marathon participation rates and urban gym penetration in India create underexploited demand clusters for performance-to-casual crossover garments.
- Casual Wearers:Style-driven buyers seeking aesthetic alignment with athletic culture without functional requirements. Micro-influencer networks and boutique fitness studios replace department stores as discovery mechanisms in North American urban markets.
- Athletes:Competitive performers requiring certified performance specifications.
- Competitors:Elite participants with customized equipment needs and team affiliation requirements.
Casual Wearers command the established base. Fitness Enthusiasts are gaining share fastest.
Material:
Volume and margin profiles diverge based on petrochemical input exposure and circular recovery pathways.
- Polyester:Dominates material volumes through cost efficiency and expanding post-consumer recovery infrastructure. REACH compliance in Europe tightens chemical disclosure requirements, forcing reformulation investments across supplier networks.
- Spandex:Commands premium positioning in compression and yoga segments through elasticity retention and shape recovery. California's Safer Consumer Products regulations extend disclosure mandates to perfluorinated compounds, shaping material selection in performance outerwear.
- Cotton:Natural fiber alternative with breathability advantages in casual applications.
- Nylon:High-tenacity synthetic for abrasion-resistant outerwear and equipment applications.
Polyester commands the established base. Spandex is climbing the fastest.
Sales Channel:
Customer type and geography determine channel preference, with digital-native demographics accelerating platform migration.
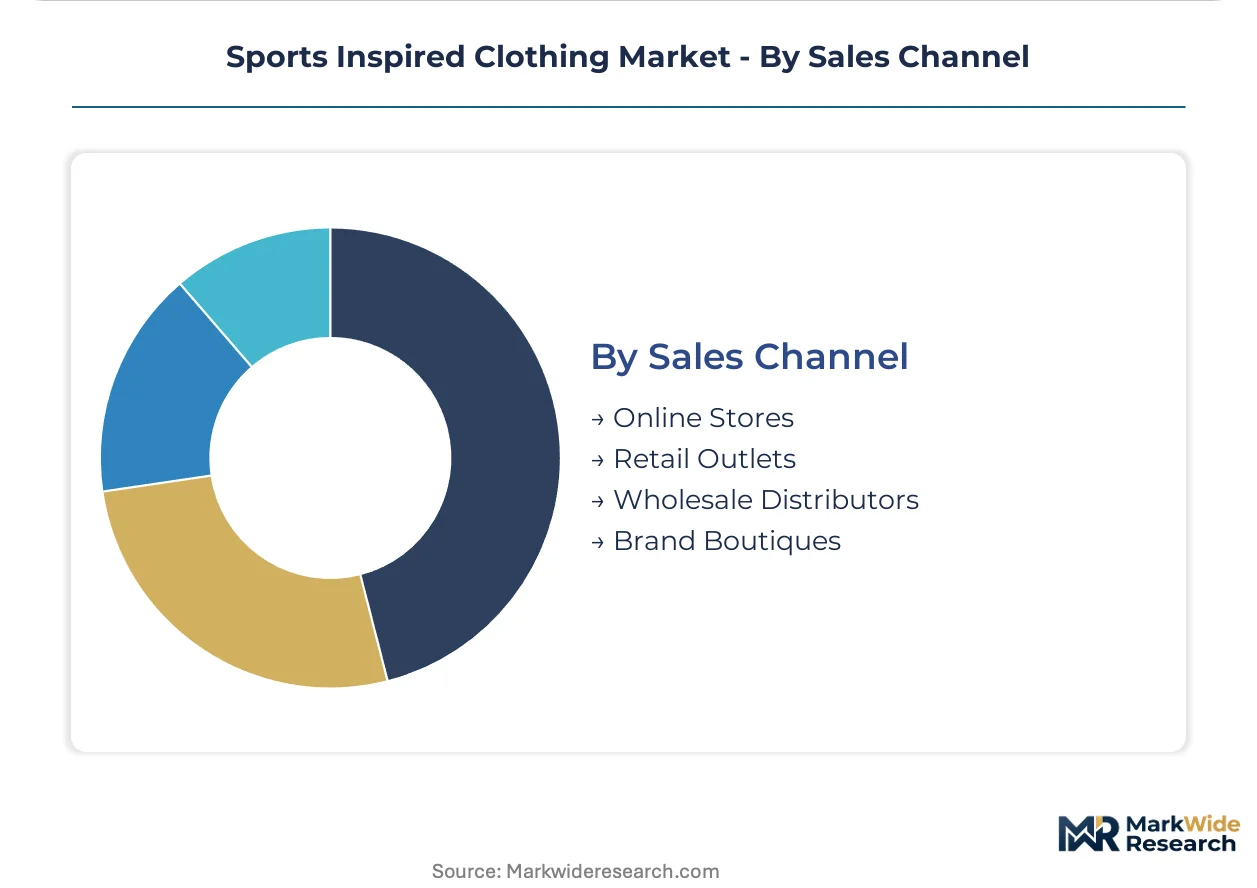
- Online Stores:Direct-to-consumer investments collapse traditional wholesale relationships through AI-driven sizing algorithms and 3D body scanning. Return rate compression and last-mile logistics optimization drive margin expansion in millennial and Generation Z demographics.
- Brand Boutiques:Controlled environment for technical storytelling and customization services. Automated Speedfactory localization near European demand clusters enables rapid regional output adjustment.
- Retail Outlets:Multi-brand physical presence with inventory risk borne by intermediaries.
- Wholesale Distributors:Volume aggregation for mass-market penetration and international market entry.
Retail Outlets command the established base. Online Stores are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness enthusiasts cluster in urban centers across multiple geographies, with middle-class expansion and workplace dress-code relaxation driving crossover garment adoption. Regulatory tightening on chemical disclosure and extended producer responsibility shapes supplier network investments. Production localization accelerates near demand clusters through automated manufacturing.
United States
Marathon participation rates and boutique fitness studio proliferation sustain demand for performance-to-casual crossover garments. California's Safer Consumer Products regulations mandate perfluorinated compound phase-out in performance outerwear, compressing compliance timelines for youth-oriented lines. The Los Angeles metro area concentrates technical design talent and direct-to-consumer platform headquarters.
China
Expanding middle-class wardrobes in tier-1 and tier-2 cities anchor athleisure volume growth. The Ministry of Ecology and Environment enforces dual carbon goals that reshape synthetic textile production energy sourcing. Zhejiang Province clusters synthetic textile weaving capacity, exposing brands to single-point disruption risks from regional power rationing.
Germany
Automated Speedfactory localization serves European demand clusters with compressed lead times. ECHA's REACH restricted substance lists accelerate reformulation investments across textile dye supplier networks. Bavaria anchors technical manufacturing infrastructure and circular economy pilot programs for post-consumer polyester recovery.
India
Urban gym penetration in Mumbai and Delhi-NCR creates underexploited demand for performance-to-casual garments. The Bureau of Indian Standards enforces textile quality mandates that shape import substitution strategies. Tamil Nadu's knitting cluster expands seam-free circular machine capacity to serve export and domestic markets simultaneously.
United Kingdom
Digital-native purchasing behaviors among millennial and Generation Z demographics accelerate direct-to-consumer platform migration. The UK's extended producer responsibility framework shifts end-of-life collection costs onto brand owners, demanding reverse logistics infrastructure. London concentrates esports league partnership activity and micro-influencer network headquarters.
Sports Inspired Clothing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation pressures mount as direct-to-consumer platforms disintermediate traditional wholesale relationships. Three archetypes dominate: vertically integrated multinationals with proprietary manufacturing technology, digitally native challengers leveraging influencer networks, and heritage sportswear brands pivoting toward lifestyle positioning. Competitive moves center on automated production localization and strategic partnerships with non-traditional athletic channels.
Within the vertically integrated tier, Nike, Inc. and Adidas Group exemplify capital-intensive control over material innovation and regional output customization. PUMA SE occupies a distinct position through esports league partnerships that capture younger demographics outside traditional athletic channels. These three entities anchor the competitive structure through divergent strategic bets on manufacturing automation, channel disintermediation, and demographic expansion.
| Leading Market Players |
|---|
| Nike, Inc. |
| Adidas Group |
| PUMA SE |
| Under Armour, Inc. |
| Lululemon Athletica Inc. |
| New Balance Athletics, Inc. |
| ASICS Corporation |
| Gymshark Limited |
| Fila Holdings Corp. |
| Others |
Value Network & Pricing Analysis
Petrochemical input volatility determines both pricing tier spreads and supply chain shape across sports inspired clothing, compressing polyester and spandex blend margins while forcing hedging costs onto mid-tier manufacturers without backward integration.
Pricing Analysis
Cost-plus contracts with crude oil indexation dominate polyester and spandex procurement, anchoring raw material pass-through mechanisms. Three-tier pricing structure across premium, standard, and economy levels separates Flyknit-equivalent engineered garments from commodity activewear basics. Pricing pressure stems from virgin polymer dependency as brands compete for limited post-consumer recycled feedstock. Casual Wearers exhibit highest price sensitivity, while Fitness Enthusiasts absorb premiums for technical certification and durability metrics.
Supply Chain Analysis
Upstream feedstock concentration in Saudi Arabia, Kuwait, and Texas shapes synthetic fiber cost structures through naphtha and paraxylene availability. Manufacturing draws from Zhejiang Province weaving clusters, Tamil Nadu knitting infrastructure, and Vietnamese cut-make-trim networks. Single-source vulnerability concentrates in eastern China's synthetic textile capacity, exposing brands to regional power rationing. Distribution runs through direct-to-consumer platforms, automated Speedfactory nodes, and traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sports inspired clothing operates as a defensive-moat market where regulatory entrenchment around REACH compliance and California's Safer Consumer Products regulations creates switching costs for certified supplier relationships.
For Market Incumbents: Harden compliance infrastructure through ECHA-registered chemical formulation partnerships, insulating against reformulation mandates that disrupt smaller competitors. Deepen automated production localization near European and North American demand clusters, reducing lead time exposure to Zhejiang logistics bottlenecks. Prioritize seam-free knitting technician apprenticeship pipelines to capture scarce vocational capacity before mid-tier rivals. For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 urban fitness infrastructure, where marathon participation and gym penetration outrun established brand presence. Target esports league licensing as a demographic expansion vector, capturing younger consumers outside traditional athletic retail channels. Deploy AI-driven sizing algorithms to compress return rates and justify direct-to-consumer platform economics against wholesale-dependent incumbents. For Investors and Strategic Acquirers: Digitally native challengers with captive influencer networks and circular economy certification represent the optimal acquisition archetype, combining channel control with regulatory-ready supply chains. Monitor extended producer responsibility framework implementation timelines as the critical inflection signal, since jurisdictions shifting end-of-life collection costs onto brand owners will accelerate consolidation pressure. Long-term viability hinges on post-consumer polyester recovery infrastructure ownership.| Strategic Initiative | Industry Significance |
|---|---|
| Seam-free Knitting Capacity Expansion | Tamil Nadu's circular machine installations reduce labor inputs and material waste for yoga and compression lines. |
| Direct-to-Consumer Platform Launch | AI-driven sizing algorithms from 3D body scanning compress return rates in millennial and Generation Z demographics. |
| Esports League Partnership | Licensed apparel unlocks incremental revenue pools through competitive gaming demographics outside traditional athletic channels. |
| Post-consumer Polyester Recovery Investment | Circular production models reduce virgin polymer dependency and satisfy EU Green Deal procurement incentives. |
| REACH Compliance Certification | ECHA-registered chemical formulations create first-mover advantages as restricted substance lists tighten across European supplier networks. |
Research Methodology
The analysis maps activewear, athleisure, sports equipment, and footwear segments, each validated through primary interviews with brand supply chain directors, textile chemical formulators, circular economy infrastructure operators, and direct-to-consumer platform executives. Secondary sources include customs and trade data, ECHA substance registration databases, SEC 10-K filings from publicly traded sportswear companies, and California DTSC Safer Consumer Products regulatory filings. Bottom-up volume estimates triangulate against top-down category spending patterns across the analysis window.
Assumptions around petrochemical input pricing stability, REACH implementation timelines, and extended producer responsibility framework adoption were held fixed across baseline scenarios, with sensitivity testing applied to polyester recovery infrastructure buildout rates and automated manufacturing localization speed. Segmentation dimensions include product type, target customer intensity, material chemistry, and sales channel architecture. CAGRs derive from regression analysis against urban gym penetration, marathon participation, and middle-class wardrobe expansion indicators.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories, Chinese power grid stability, or European regulatory enforcement intensity would shift the trajectory. Cross-checking against IEA petrochemical demand forecasts and national textile production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Sailing Jackets Market
Apparel & Footwear
Touchscreen Gloves Market
Apparel & Footwear
Headwear Market
Apparel & Footwear
Alpaca Apparel and Accessories Market
Apparel & Footwear
Maternity Activewear Market
Apparel & Footwear
Gym Apparel Market
Apparel & Footwear
Global Leggings Market
Apparel & Footwear
Children's Dresses and Skirts Market
Apparel & Footwear
Women's Blazer Market
Apparel & Footwear
Ballet Pointe Shoes Market
Apparel & Footwear
India Denim Jeans Market
Apparel & Footwear
Cosplay Costumes Market
Apparel & Footwear
Women's Trousers Market
Apparel & Footwear
Global Swimwear (Swimsuit) Market
Apparel & Footwear
Seamless Underwear for Men Market
Apparel & Footwear
Ethnic Wear Market