
 Secondhand Apparel Market | 2026-2036
Secondhand Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Secondhand Apparel Market Outlook
France's AGEC anti-waste law is restructuring compliance obligations for fashion brands entering circular resale channels. ThredUp leverages its proprietary resale-as-a-service technology to anchor white-label partnerships with mainstream retailers. Vestiaire Collective dominates European luxury authentication, while Poshmark sustains its social-commerce model through community-driven listing tools.
Secondhand apparel encompasses pre-owned garments reintroduced to commercial circulation through resale, consignment, or donation channels, typically graded by condition tiers from like-new to damaged and processed through authentication, cleaning, and quality-assessment protocols before re-sale. The category serves both budget-conscious consumers and collectors seeking discontinued or vintage inventory unavailable through primary retail. Online marketplaces lead transaction volume growth, though thrift stores retain margin advantages in lower-income demographics where operational overhead stays minimal. Eco-conscious consumers represent the fastest-expanding customer segment, while vintage collectors command premium pricing for authenticated archival pieces.
The European Commission's Ecodesign for Sustainable Products Regulation, the US EPA's textile waste diversion frameworks, and China's GB standards for recycled fiber content collectively reshape product eligibility, traceability requirements, and cross-border resale logistics. These frameworks elevate authentication and chain-of-custody documentation from optional brand signals to operational necessities. Stakeholders must now decide whether to build in-house resale infrastructure or embed through platform partnerships before compliance thresholds harden.
Market Dynamics
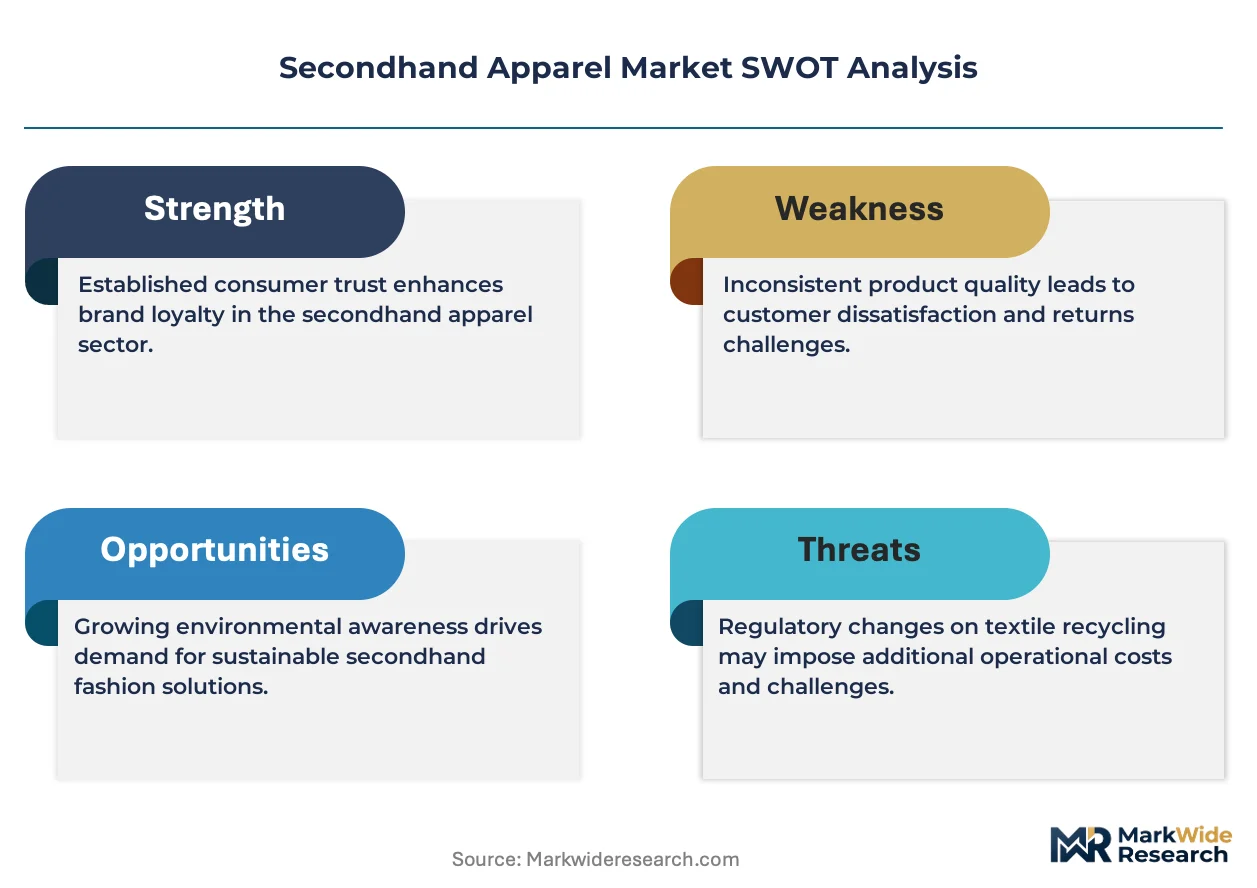
France's AGEC law and the EU Ecodesign for Sustainable Products Regulation are forcing fashion brands to build chain-of-custody documentation into resale operations, converting voluntary circularity into compliance infrastructure.
Growth Catalysts
- Gen Z digital-native adoption:Mobile-first resale platforms capture this demographic through social authentication features and peer-to-peer listing tools. Urban clusters in the United States concentrate transaction density.
- Extended Producer Responsibility mandates:France's AGEC law requires textile producers to finance end-of-life collection and recycling. Compliance deadlines accelerate brand investment in resale-as-a-service partnerships.
- Venture-backed authentication technology:Computer vision and blockchain-based provenance tracking reduce buyer risk in luxury segments. These tools expand addressable inventory into higher-value archival pieces.
Market Restraints
- Authentication labor costs:Manual grading and condition assessment require skilled technicians. Wage inflation in logistics hubs compresses platform unit economics.
- Textile waste diversion infrastructure gaps:Municipal sorting facilities in the United States lack capacity to handle mixed fiber streams. Downcycling rates exceed closed-loop recycling by substantial margins.
- Cross-border customs complexity:Varying definitions of "used goods" versus "waste" create seizure risk. Harmonized System code ambiguities delay clearance at EU and US ports.
Strategic Opportunities
- White-label resale infrastructure:Mainstream retailers embed third-party authentication and logistics without capital-intensive buildouts. This channel unlocks inventory access from brands previously absent from secondary markets.
- Garment-as-a-service models:Subscription-based clothing rental converges with resale exit pathways. Nordic markets demonstrate consumer willingness to pay for access over ownership.
- AI-powered dynamic pricing:Machine learning models adjust listing prices based on demand signals, seasonality, and comparable sales velocity. Adoption concentrates in high-frequency apparel categories.
Industry Challenges
- Authentication skill scarcity:Trained graders capable of identifying counterfeit luxury goods command premium wages. Training pipelines fail to match platform expansion timelines.
- Legacy inventory system integration:ERP architectures designed for single-sale retail require expensive retrofitting to track item-level circularity. Data field standardization across brand partners remains unresolved.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Secondhand Apparel Market |
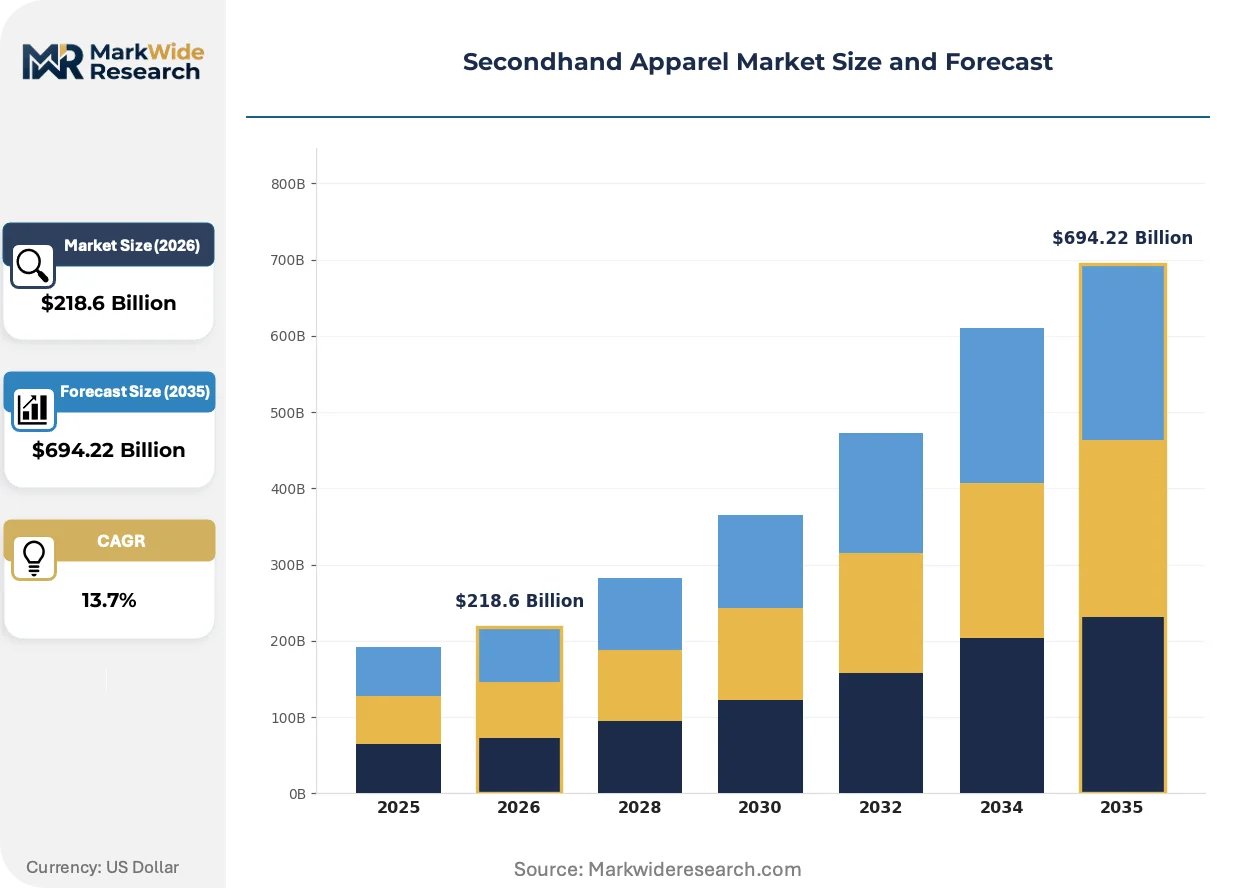
| Market Size in 2026 | $218.6 Billion |
| Market Size in 2035 | $694.22 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Shirts, Jeans, Jackets, Dresses Customer Type: Teens, Young Adults, Vintage Collectors, Eco-Conscious Consumers Sales Channel: Online Marketplaces, Thrift Stores, Consignment Shops, Garage Sales Condition: Like New, Gently Used, Worn, Damaged |
| Companies Covered | ThredUp, Poshmark, The RealReal, Vinted, Depop, Vestiaire Collective, Tradesy, Grailed, Micolet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Secondhand Apparel Market Strategic Shifts
Digital infrastructure is fragmenting the resale value chain into specialized components, enabling new entrants to compete without vertically integrated operations. Three developments define this restructuring.
Blockchain-based provenance tracking is modularizing trust infrastructure across authentication workflows. Luxury consignment platforms deploy distributed ledger technology to immutably record ownership history and condition grades. This decomposition allows smaller marketplaces to license verification layers rather than building proprietary systems.
The EU Ecodesign for Sustainable Products Regulation mandates digital product passports for textiles entering European circulation. Brands must embed scannable identifiers linking to fiber composition, manufacturing origin, and repair instructions. French and Italian luxury houses are piloting NFC-enabled hangtags to satisfy traceability requirements ahead of enforcement deadlines.
Social commerce interfaces are displacing traditional search-based discovery in Gen Z acquisition patterns. Community-driven curation tools replace keyword queries with algorithmic feeds styled by user-generated content. This behavioral shift is most pronounced in United States urban markets where platform-native sellers build follower-based distribution channels independent of paid advertising.
Secondhand Apparel Market Segmentation
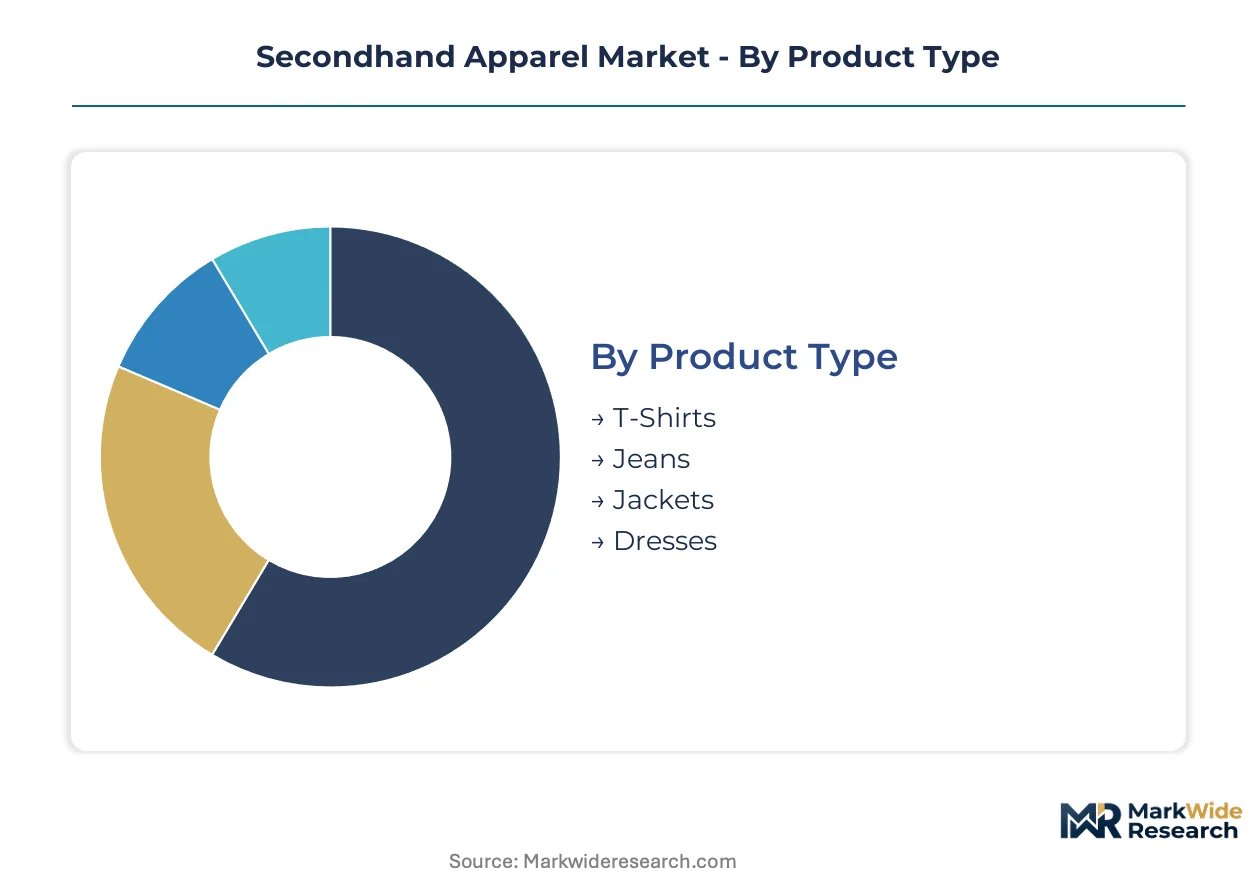
Segmentation in secondhand apparel reveals how inventory velocity, authentication complexity, and margin profiles diverge across product categories and buyer psychographics. Supply concentration in specific garment types and customer cohorts determines platform merchandising strategies and logistics investments.
Product Type:
Supply concentrates in denim and outerwear where durability extends resale cycles and authentication protocols are standardized.
- Jeans:Heavyweight cotton denim withstands multiple wear cycles with minimal degradation. Demand clusters in United States urban markets where vintage Levi's and designer denim command authentication premiums. ThredUp and Poshmark process the highest denim volumes through automated condition grading.
- Jackets:Outerwear requires structured storage and seasonal demand forecasting. Leather and technical shells drive the highest per-unit margins in Vestiaire Collective's European luxury authentication pipeline. Supply scarcity in archival pieces creates bidding dynamics absent in mass-market categories.
- T-Shirts:High-velocity basics with compressed margins and rapid inventory turnover.
- Dresses:Occasion-driven purchases with concentrated demand in formal and vintage subcategories.
Today's leader: Jeans. Tomorrow's challenger: Jackets.
Customer Type:
Cost tier stratification separates browsers seeking utility from collectors paying authentication premiums.
- Eco-Conscious Consumers:Purchase decisions integrate carbon footprint data and circularity credentials. This cohort demonstrates the highest willingness to pay for authenticated pre-owned inventory over comparable new fast-fashion alternatives. France's AGEC compliance labeling directly influences their platform selection.
- Vintage Collectors:Specialized knowledge of designer archives and production eras drives acquisition behavior. Authentication labor costs concentrate on serving this segment's provenance documentation requirements. Blockchain-based ownership records are gaining adoption fastest among this buyer type.
- Teens:Price-sensitive mobile-native users discovering resale through social commerce interfaces.
- Young Adults:Transitional wardrobe builders balancing budget constraints with style experimentation.
Eco-Conscious Consumers anchor current volume expansion. Vintage Collectors are climbing the fastest in revenue per transaction.
Sales Channel:
Volume distribution is accelerating toward digital infrastructure while physical retail retains margin advantages in lower-cost geographies.
- Online Marketplaces:Computer vision and algorithmic pricing enable scale economics impossible in physical retail. Mobile-first discovery patterns concentrate Gen Z transaction density in United States coastal cities. White-label resale-as-a-service partnerships embed these platforms into mainstream brand websites.
- Thrift Stores:Minimal overhead structures sustain profitability in lower-income demographics where price elasticity dominates. Municipal textile diversion partnerships in France and selected United States cities provide inventory access at below-market acquisition costs.
- Consignment Shops:Curated selection with higher touch service and authentication premiums.
- Garage Sales:Unstructured peer-to-peer transactions with minimal quality assurance.
Online Marketplaces captured the steepest expansion trajectory. Thrift Stores defend position through cost structure.
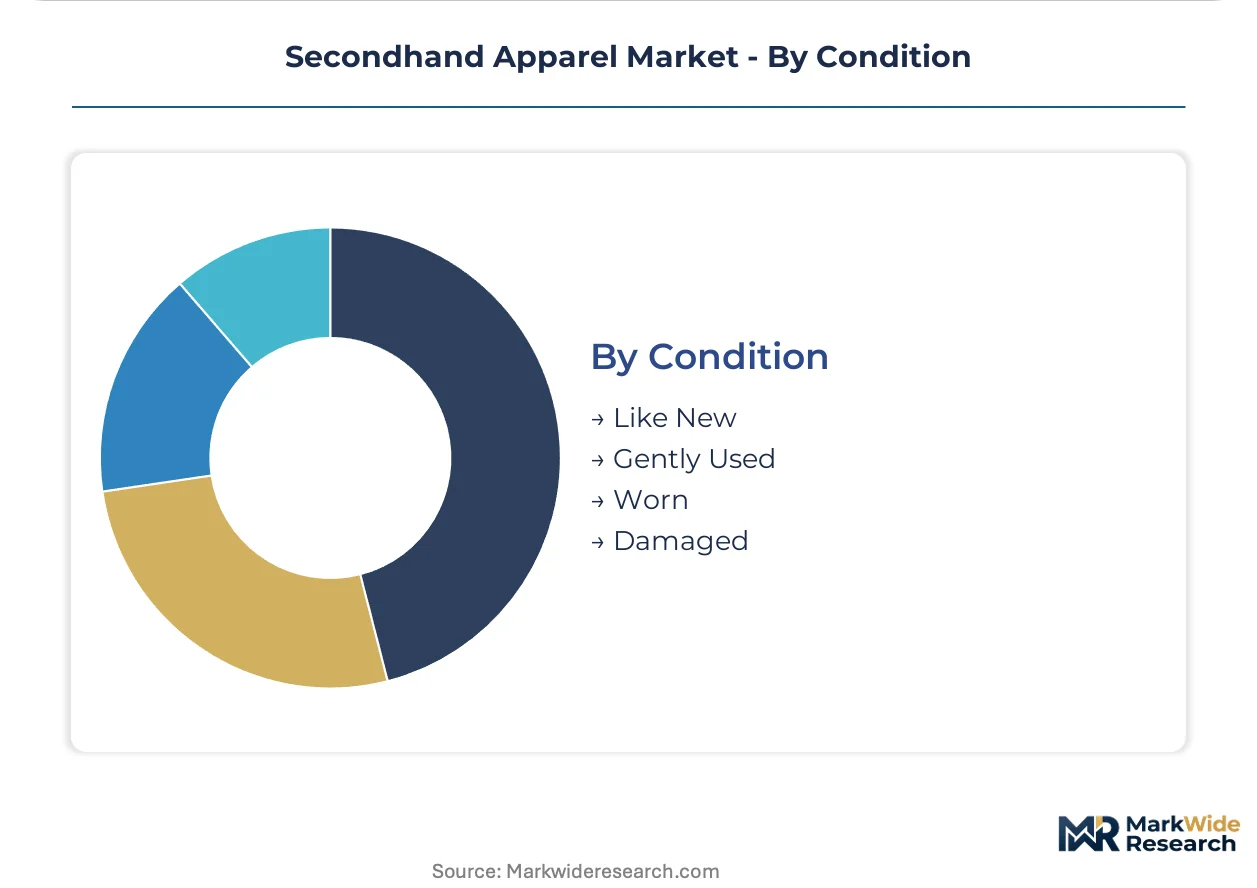
Condition:
Margin tiering separates inventory pools requiring differentiated authentication labor and pricing algorithms.
- Like New:Garments with original tags or single-wear provenance achieve price parity with off-season new retail. Authentication protocols focus on counterfeit detection rather than damage assessment. Luxury consignment platforms restrict listings to this tier for high-value submissions.
- Gently Used:Visible wear without structural compromise constitutes the volume base of mainstream resale. Grading standardization across platforms remains incomplete, creating arbitrage opportunities for sophisticated sellers.
- Worn:Functional garments with evident use cycles targeting pure budget buyers.
- Damaged:Repairable or upcyclable inventory diverted to craft and maker communities.
Like New commands premium positioning. Gently Used represents the deepest inventory pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban resale ecosystems concentrate skilled authentication technicians and venture-backed platform engineering talent in coastal metropolitan clusters. France's AGEC compliance mandates and EU Ecodesign regulations are redistributing operational investment toward traceability infrastructure. City-level thrift density and digital marketplace penetration now determine transaction velocity more than national income averages.
United States
Gen Z mobile-native buyers and venture capital flows into resale-as-a-service platforms dominate demand formation. The EPA's textile waste diversion frameworks push municipal partnerships with thrift operators. New York and Los Angeles anchor authentication labor pools and white-label technology development for mainstream retail embedding.
France
Eco-conscious consumer willingness to pay for circularity credentials exceeds comparable European markets. The AGEC anti-waste law mandates producer financing of end-of-life collection, accelerating brand compliance investment. Paris concentrates Vestiaire Collective's luxury authentication infrastructure and NFC-enabled digital product passport pilot programs.
United Kingdom
Social commerce discovery patterns and peer-to-peer listing tool adoption drive Gen Z transaction density. The country's national environmental regulator advances extended producer responsibility consultations for textiles. London's Depop community and Manchester's vintage wholesale clusters specialize in trend-responsive inventory curation.
Germany
Garment-as-a-service subscription models and access-over-ownership consumer segments show highest adoption rates. The EU Ecodesign for Sustainable Products Regulation enforcement timeline pressures brand traceability system upgrades. Berlin's circular fashion startups and Hamburg's logistics hubs experiment with AI-powered dynamic pricing for high-velocity categories.
Japan
Vintage collectors seeking authenticated archival pieces command premium pricing for discontinued designer inventory. METI guidelines on resource circulation influence corporate resale partnership strategies. Tokyo's Harajuku district and Osaka's Americana vintage clusters maintain specialized authentication expertise for heritage workwear and luxury streetwear.
Secondhand Apparel Market Competitive Environment
The competitive structure tilts toward platform-native authentication technology and white-label infrastructure licensing over vertically integrated retail operations. Venture-backed marketplaces and social commerce interfaces now capture transaction volume growth that physical consignment networks previously dominated. Two archetypes define positioning: authentication-heavy luxury consignment platforms and mass-market resale-as-a-service enablers. Strategic moves concentrate on embedding third-party logistics into mainstream brand websites and licensing computer vision grading tools to smaller regional marketplaces.
Within the authentication-technology tier, ThredUp exemplifies white-label infrastructure licensing to mainstream retailers seeking circular compliance without capital-intensive buildouts. Vestiaire Collective occupies a position representing European luxury authentication standards and blockchain-based provenance documentation. Poshmark anchors the social-commerce archetype through community-driven discovery tools that algorithmic feeds and user-generated curation displace from traditional search-based acquisition patterns.
| Leading Market Players |
|---|
| ThredUp |
| Poshmark |
| The RealReal |
| Vinted |
| Depop |
| Vestiaire Collective |
| Tradesy |
| Grailed |
| Micolet |
| Others |
Value Chain & Pricing Dynamics
AI-powered condition grading is compressing authentication labor costs while concentrating pricing power among platforms with proprietary computer vision infrastructure. This technology shift simultaneously enables margin expansion in premium tiers and price erosion in mass-market categories where automated grading replaces manual assessment.
Pricing Analysis
Platform pricing splits between bundled resale-as-a-service subscriptions and unbundled per-transaction fees. Three-tier pricing structure across premium authentication, standard consignment, and economy direct-listing levels separates luxury consignment platforms from mass-market peers. Price differentiation rests on authentication depth and brand certification status. Margins are tightening in the economy tier due to wage inflation in logistics hubs. Eco-conscious consumers demonstrate lowest price sensitivity while teen mobile-native users anchor the most elastic demand segment.
Supply Chain Analysis
EU digital product passport mandates and France's AGEC compliance labeling are gating market access for inventory lacking chain-of-custody documentation. Supply concentrates in the United States, France, and Japan where authentication technician pools and venture-backed platform engineering cluster. Raw material flows draw from municipal textile diversion partnerships, brand take-back programs, and peer-to-peer donation streams. Single-source vulnerability sits with concentrated authentication labor in Paris, New York, and Tokyo. Distribution runs through hybrid models combining centralized authentication hubs with last-mile postal networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where authentication labor cost differentials between the United States and Eastern European hubs create margin expansion opportunities for platform operators with cross-border logistics infrastructure.
For Market Incumbents: Hedge against authentication skill scarcity by embedding AI-powered grading tools and securing exclusive municipal diversion partnerships in France and selected United States cities. Vertical integration into proprietary resale-as-a-service technology protects margin position against white-label platform competitors. Priority investment targets NFC-enabled digital product passport infrastructure ahead of EU Ecodesign enforcement deadlines. For New Entrants and Emerging Players: Begin with garment-as-a-service subscription models in Nordic markets where access-over-ownership willingness exceeds global benchmarks. White-space concentration sits in AI-powered dynamic pricing tools for high-velocity apparel categories underserved by incumbent platforms. Go-to-market execution should prioritize direct-to-consumer rental-to-resale exit pathways rather than competing head-to-head with established marketplace volume. For Investors and Strategic Acquirers: Valuations sit cheapest among authentication-technology specialists with modular blockchain provenance licensing capabilities rather than vertically integrated retail operations. Long-term viability across the analysis window favors platform-native infrastructure providers over physical consignment networks. The inflection signal to watch is mandatory digital product passport adoption velocity in EU member states.| Strategic Initiative | Industry Significance |
|---|---|
| Authentication Technology Licensing | Computer vision grading tools enable smaller marketplaces to compete without proprietary buildouts. |
| Resale-as-a-Service Partnership | White-label embedding unlocks mainstream retailer inventory previously absent from secondary markets. |
| Digital Product Passport Integration | NFC-enabled hangtags satisfy EU Ecodesign traceability requirements ahead of enforcement deadlines. |
| Municipal Diversion Partnership | Exclusive textile waste collection agreements provide below-market inventory acquisition costs. |
| AI-Powered Dynamic Pricing Deployment | Machine learning models optimize listing prices based on demand signals and comparable sales velocity. |
Study Parameters
Multiple input streams — executive interviews with resale platform operators, authentication technician workforce surveys, and municipal textile diversion program assessments — were reconciled against secondary validation from customs records, SEC filings of publicly traded marketplace operators, and EU regulatory documentation. Primary fieldwork captured perspectives from brand sustainability officers, logistics hub managers, and luxury consignment curators. Secondary sources included France's AGEC implementation guidance, EPA textile waste diversion frameworks, and platform engineering patent filings. Bottom-up transaction volume estimates and top-down circular economy adoption models were cross-referenced for triangulation.
Historical growth trajectories were benchmarked against panel input from industry participants to anchor projection assumptions across the modeling period. Segmentation dimensions modeled include product condition tier, customer psychographic archetype, sales channel format, and regional regulatory cluster. CAGRs were derived from demand elasticity coefficients and authentication capacity expansion schedules. Forecast inputs incorporated Gen Z mobile-native adoption curves and extended producer responsibility compliance investment timelines.
Several conditions sit outside the modeled scope, including abrupt tariff reclassifications of used goods, breakthrough recycling technologies enabling fiber-to-fiber closed-loop processing, and platform operator consolidation events. Forecasts reflect documented assumptions about authentication labor supply elasticity and cross-border customs clearance efficiency. A model refresh is warranted upon material change in EU Ecodesign enforcement timelines or municipal textile diversion funding allocations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Ballet Pointe Shoes Market
Apparel & Footwear
Smart Heating Scarf Market
Apparel & Footwear
Cosplay Costumes Market
Apparel & Footwear
Compression and Shapewear Market
Apparel & Footwear
Innerwear Market
Apparel & Footwear
Yoga Clothing Market
Apparel & Footwear
Global Luxury Underwear Market
Apparel & Footwear
Ethnic Wear Market
Apparel & Footwear
Hats Market
Apparel & Footwear
Mexico Denim Jeans Market
Apparel & Footwear
Children's Dresses and Skirts Market
Apparel & Footwear
Fanny Packs Market
Apparel & Footwear
Plus Size Clothing Market
Apparel & Footwear
Global Leggings Market
Apparel & Footwear
Brazil Pet Clothing Market
Apparel & Footwear
Asia Pacific Hats Market