
 Womens Swimwear Market | 2026-2036
Womens Swimwear Market Size, Share, and Industry Trends Forecast 2026-2036
Womens Swimwear Market Outlook
REACH compliance is pivoting the cost-of-entry calculus for women's swimwear brands seeking European market access, as chemical restrictions on dyes and synthetic finishes force reformulation investments. Adidas AG leverages its materials science infrastructure to navigate these compliance thresholds, while LVMH Moet Hennessy Louis Vuitton anchors its positioning through controlled verticality in luxury textile sourcing. Arena S.p.A specializes in competitive-grade fabric performance, sustaining differentiation in the athlete sub-segment where technical certification requirements intensify.
Women's swimwear comprises engineered textile garments designed for aquatic environments, typically constructed from chlorine-resistant nylon-polyester blends with elastane content ranging from 15% to 25% to achieve compression and shape retention. These products serve recreational, competitive, and resort-wear applications where hydrodynamic performance and UV protection ratings determine commercial viability. Bikinis and one-piece styles occupy divergent margin pools, with fashion-forward one-piece silhouettes commanding premium positioning while sporty tankinis capture volume in the teenager and athlete target audiences. Material composition is shifting toward recycled polyester variants as brands respond to sustainability-driven procurement criteria from retail partners.
The EU Green Deal and REACH framework impose chemical and circularity standards that reshape supplier qualification across European distribution channels, while the US EPA and state-level California Safer Consumer Products regulations extend comparable pressure in North America. BIS textile labeling requirements in India and China's GB standards for textile safety create a fragmented compliance landscape that advantages multinationals with dedicated regulatory affairs capacity. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to absorb compliance costs or pass them through pricing architecture in a category where consumer elasticity varies sharply by style tier.
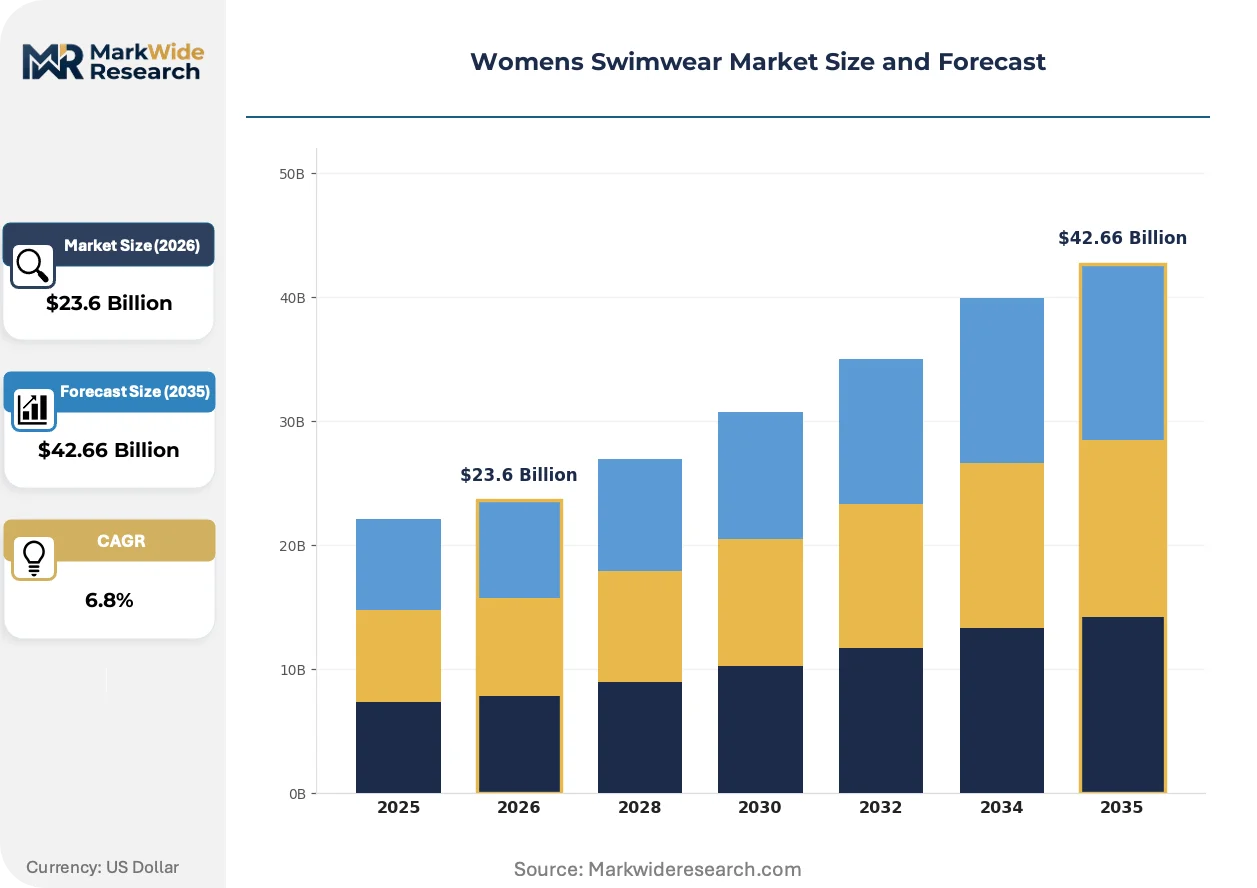
Market Dynamics
EU Green Deal textile mandates and REACH chemical restrictions are forcing wholesale material reformulation across European supply chains, compressing margins for brands lacking dedicated compliance infrastructure while advantaging those with captive materials science capabilities.
Growth Catalysts
- Resort channel expansion:Cruise-line and resort operators now constitute a fast-expanding procurement channel with consolidated volume purchasing power and seasonal demand predictability.
- REACH-driven premiumization:European chemical restrictions on dyes and synthetic finishes force reformulation investments that filter out price-competing entrants and elevate certified product positioning.
- Brazilian demand concentration:Beach culture normalization and domestic manufacturing cluster density in São Paulo and Rio de Janeiro reinforce category pull across South American distribution networks.
Market Restraints
- Elastane cost volatility:Petroleum-derived spandex pricing fluctuates with crude oil benchmarks, compressing margins on mid-tier products where price elasticity limits pass-through capacity.
- Asian supply concentration:Nylon and polyester precursor production concentrates in Zhejiang and Guangdong provinces, exposing brands to single-region disruption risk from logistics bottlenecks or energy rationing.
- Chlorine degradation limitation:Recycled polyester variants exhibit accelerated fiber breakdown in chlorinated pool environments versus virgin polymer performance, constraining competitive swimwear application.
Strategic Opportunities
- Extended producer responsibility tailwinds:France's AGEC law and emerging EU textile EPR frameworks create first-mover advantages for brands with closed-loop collection infrastructure.
- Competitive athlete sub-segment:Technical certification requirements for FINA-compliant competition wear intensify, creating defensible positioning for specialized fabric engineering capabilities.
- Direct-to-resort distribution:Bypassing wholesale intermediaries to supply cruise operators and hospitality groups directly captures margin and secures exclusive capsule placement.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with chlorine-resistant elastomer expertise command premium compensation, constraining R&D velocity for mid-cap brands.
- Multi-jurisdiction labeling complexity:Simultaneous compliance with BIS textile labeling in India, GB standards in China, and California Safer Consumer Products regulations fragments quality assurance workflows.
- Legacy dye house retooling:Converting conventional synthetic dyeing infrastructure to low-impact alternatives requires capital outlays that strain privately held manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Womens Swimwear Market |
| Market Size in 2026 | $23.6 Billion |
| Market Size in 2035 | $42.66 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bikinis, One-piece, Swim Dresses, Tankinis Material: Nylon, Polyester, Spandex, Cotton Style: Sporty, Fashion, Classic, Trendy Target Audience: Teenagers, Adults, Plus-size, Athletes |
| Companies Covered | Adidas AG, Nike Inc., Puma SE, LVMH Moet Hennessy Louis Vuitton, Swimwear Anywhere Inc., Arena S.p.A, Boardriders Inc., Chanel Group, LA Perla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Womens Swimwear Market Strategic Shifts
Material science convergence with sustainability mandates is compressing product development cycles while elevating technical performance thresholds across recreational and competitive segments.
Digital knitting technology is integrating 3D seamless construction into high-volume production lines, eliminating seam failure points and enabling gradient compression zoning. Performance-oriented buyers in the masters swimming demographic adopt these garments at accelerating rates. This manufacturing shift is integrating body-mapping data from biometric scanning into pattern engineering, collapsing the traditional sampling-to-production timeline.
REACH Annex XVII restrictions on NPEOs and PFAS in textile treatments entered enforcement phases across EU member states, compelling dyestuff substitution and wastewater treatment upgrades. Industrial consequence includes supplier consolidation as smaller finish houses exit compliance. Competitive swimwear brands with athlete certification requirements face the steepest reformulation timelines, accelerating partnerships with polymer laboratories in Germany and Switzerland.
Resort wear buyers now consolidate purchasing through hospitality procurement platforms, unbundling traditional seasonal wholesale relationships. Independent boutiques and specialty retailers lose shelf space to cruise-line exclusive collections and hotel gift shop placement. This channel rotation is most visible in Caribbean and Mediterranean resort corridors where property management companies centralize amenity sourcing.
Womens Swimwear Market Segmentation
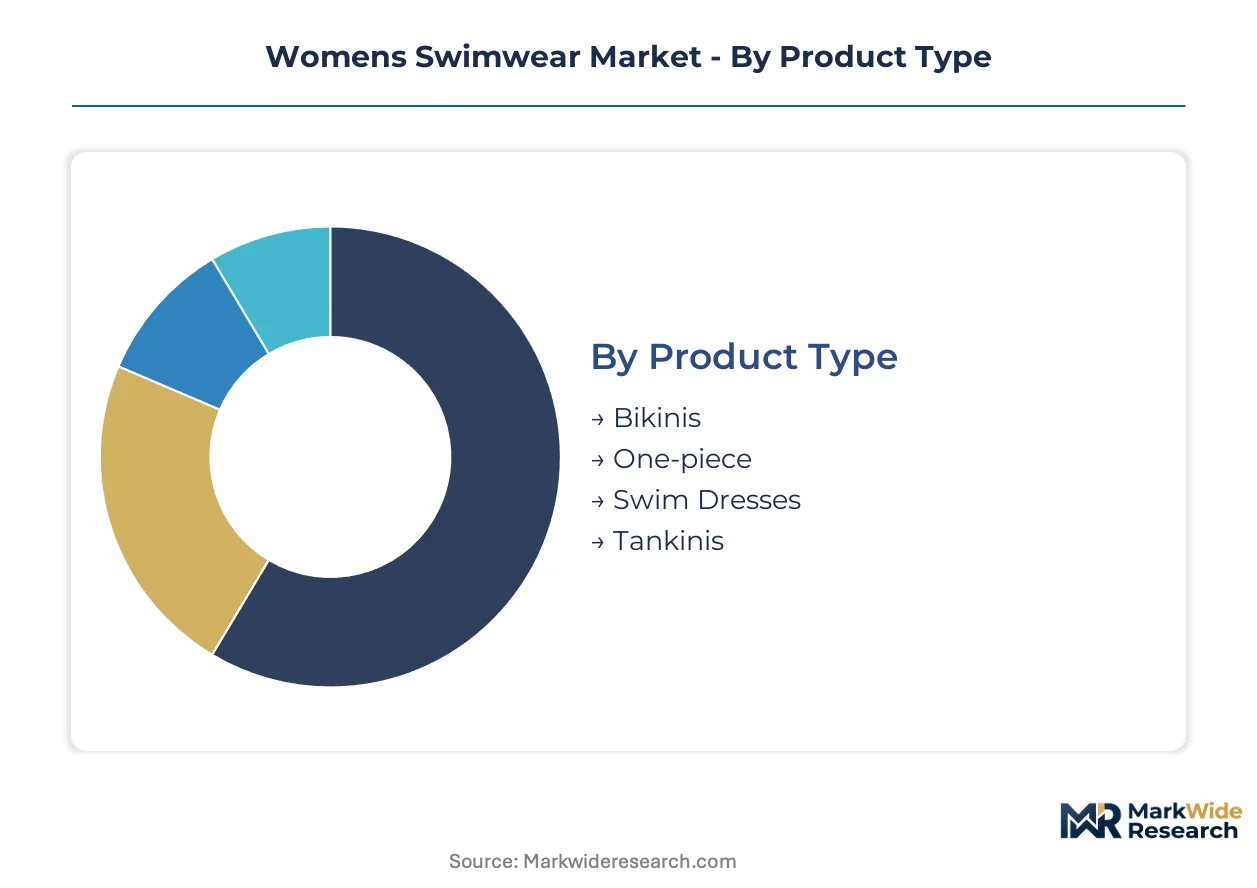
Swimwear segmentation reflects divergent margin architectures across style tiers and performance requirements. Material composition and end-use application determine compliance burden and pricing power. Distribution channel selection varies sharply by target demographic and geographic market.
Product Type:
Volume concentration favors mass-market silhouettes with seasonal turnover, while premium positioning attaches to specialized cuts with technical certification or resort exclusivity.
- Bikinis:Two-piece construction utilizing 15-20% elastane blends for adjustable fit and tan-line minimization. Brazilian beach culture and Mediterranean resort corridors concentrate demand, where fast-fashion velocity and influencer-driven trend cycles accelerate inventory turns.
- One-piece:Engineered chlorine-resistant nylon-polyester shells with graduated compression panels for hydrodynamic performance. Competitive swimming federations and masters athletics programs drive specification intensity, with FINA certification requirements filtering supplier pools.
- Swim Dresses:Skirted silhouettes combining modesty coverage with quick-dry textile engineering.
- Tankinis:Hybrid construction merging bikini separates with torso coverage for teenager and post-maternity segments.
Mature deployment sits with One-piece in competitive and resort channels. Newer deployment is concentrated in Tankinis as multi-generational household purchasing expands.
Material:
Petroleum-derived feedstock pricing and regulatory chemical restrictions are compressing margin structures differently across synthetic versus natural fiber categories.
- Nylon:Chlorine-resistant polyamide 6,6 variants dominate competitive swimwear for dimensional stability under repeated pool exposure. REACH Annex XVII dye restrictions and EU Green Deal circularity mandates are forcing recycled content transitions in European supply chains.
- Polyester:Recycled PET variants from post-consumer bottle feedstock now constitute the majority of sustainability-positioned resort collections. Accelerated fiber degradation in chlorinated environments versus virgin polymer limits competitive swimming application.
- Spandex:Elastane content ranging 15-25% provides compression and shape retention across all product tiers.
- Cotton:Limited to cover-up and loungewear adjacent categories due to water absorption and chlorine sensitivity constraints.
Upstream integration into polymer production distinguishes Nylon suppliers with cost control. Polyester recycling infrastructure is expanding most quickly in Asian manufacturing clusters.
Style:
Margin stratification follows performance certification requirements versus fashion velocity, with technical segments commanding price premiums and trend-dependent categories facing higher obsolescence risk.
- Sporty:Compression-engineered construction with UPF 50+ ratings and flatlock seam finishing for reduced drag. Athlete certification programs and masters swimming demographics anchor demand in Australia, Germany, and California training corridors.
- Fashion:Runway-influenced silhouettes with seasonal print rotation and hardware embellishment. Resort procurement platforms and cruise-line exclusive collections now consolidate volume purchasing power away from traditional wholesale.
- Classic:Timeless cuts with minimal hardware and extended colorway continuity for reduced SKU complexity.
- Trendy:Social-media-driven micro-seasonality with abbreviated production runs and rapid replenishment logistics.
Defensible positioning attaches to Sporty through technical barriers. Fashion deployment is climbing the fastest as hospitality procurement centralization accelerates.
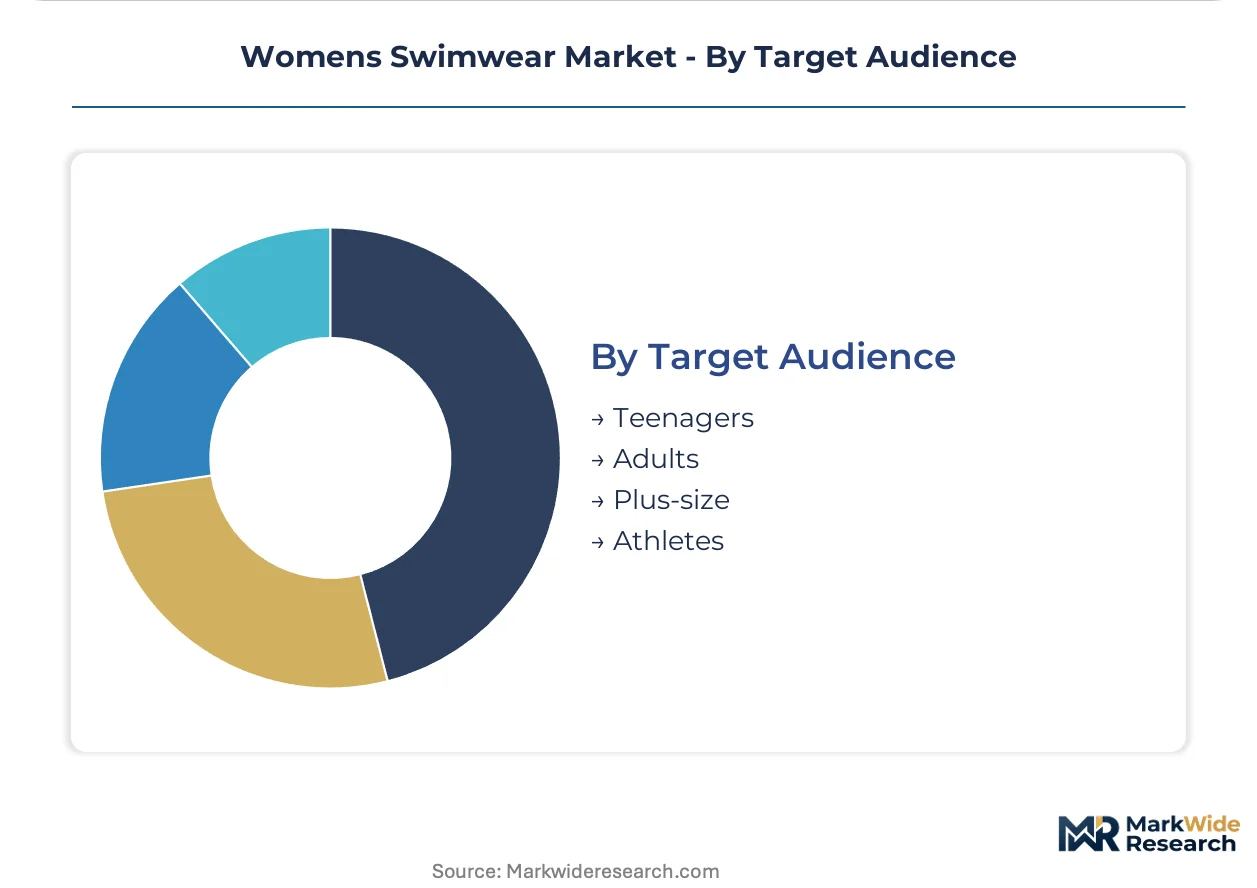
Target Audience:
Age-correlated sizing requirements and activity-level segmentation determine fit engineering complexity and distribution channel selection.
- Teenagers:Tankini and high-waisted bikini silhouettes with adjustable strap configurations for growth accommodation. Back-to-school seasonal purchasing and social media discovery patterns concentrate demand in direct-to-consumer digital channels.
- Adults:Full size-range coverage from athletic to resort applications with the broadest style diversification.
- Plus-size:Extended sizing with reinforced underwire support and strategic compression paneling.
- Athletes:FINA-compliant competition wear with hydrodynamic surface treatments and biometric pattern engineering. Technical certification timelines and polymer laboratory partnerships in Switzerland and Germany create supplier qualification barriers.
Established infrastructure serves Adults across all channels. Athletes represent the steepest expansion trajectory as competitive swimming participation climbs in Brazil and East Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's SUDENE tax incentive zone concentrates textile manufacturing in the Northeast, drawing swimwear producers toward Recife and Fortaleza with subsidized industrial land and duty exemptions on imported elastane inputs.
Brazil
Beach culture normalization in Rio de Janeiro and São Paulo sustains year-round domestic consumption, while export demand from Argentina and Chile climbs. ANVISA textile safety standards align with Mercosur technical regulations, simplifying cross-border certification. Manufacturing clusters in São Paulo state's ABC region now integrate digital knitting equipment from European suppliers to serve cruise-line procurement contracts.
United States
California's masters swimming demographic and Florida's resort corridor concentrate premium demand, with direct-to-consumer brands capturing teenager segments through social media channels. EPA chemical regulations under the Toxic Substances Control Act restrict certain dye intermediates, pushing reformulation toward compliant alternatives. Miami's Design District hosts emerging swimwear studios serving Caribbean hospitality procurement platforms with rapid-turn capsule collections.
Germany
Competitive swimming federation procurement and technical apparel engineering capabilities anchor demand in Bavaria and North Rhine-Westphalia. REACH Annex XVII enforcement through ECHA compels dyestuff substitution across supply chains, filtering smaller finish houses from qualification pools. Polymer laboratories in Baden-Württemberg partner with sportswear brands to develop chlorine-resistant elastomer formulations for FINA-certified competition wear.
China
Zhejiang and Guangdong provinces concentrate nylon and polyester precursor production, with Ningbo and Shenzhen serving as export manufacturing hubs for North American and European brands. GB standards for textile safety and dual carbon goals from MIIT accelerate recycled PET adoption in export-oriented facilities. Qianhai Shenzhen-Hong Kong Modern Service Industry Cooperation Zone offers tariff advantages for brands establishing Asia-Pacific distribution headquarters.
Australia
UV protection consciousness and coastal lifestyle density drive premium positioning in New South Wales and Queensland markets. TGA textile labeling requirements intersect with state-level consumer protection frameworks, creating multi-layer compliance obligations. Melbourne's technical apparel design studios increasingly supply biometric pattern engineering services to competitive swimwear brands targeting the masters swimming demographic across Asia-Pacific markets.
Womens Swimwear Market Competitive Environment
European producers anchor the premium tier with REACH-compliant material science capabilities; Asian fabricators hold volume positions through integrated polyester recycling infrastructure. The vendor base stratifies across three tiers: multinational sportswear conglomerates with captive R&D, mid-cap specialists with regional manufacturing depth, and private-label contractors serving hospitality procurement platforms. Dominant competitive moves include backward integration into polymer production and exclusive supply agreements with cruise-line operators.
Within the sportswear conglomerate tier, Adidas AG and Nike Inc. exemplify archetypes with materials science infrastructure navigating regulatory thresholds. Arena S.p.A occupies a specialist position in competitive-grade fabric performance, while LVMH Moet Hennessy Louis Vuitton anchors luxury verticality in controlled textile sourcing. These named entities represent strategic positioning patterns rather than exhaustive market coverage, with each exemplifying distinct responses to chemical compliance mandates and channel consolidation pressures.
| Leading Market Players |
|---|
| Adidas AG |
| Nike Inc. |
| Puma SE |
| LVMH Moet Hennessy Louis Vuitton |
| Swimwear Anywhere Inc. |
| Arena S.p.A |
| Boardriders Inc. |
| Chanel Group |
| LA Perla |
| Others |
Value Chain & Pricing Dynamics
Certification-grade performance divergence between FINA-compliant competition wear and resort fashion separates pricing power from commodity pressure, with athlete-grade products commanding sustained premiums through polymer science barriers while fashion tiers face margin compression from dye house retooling costs and spot inventory liquidation cycles.
Pricing Analysis
Lead-time premiums attach to rapid-turn capsule collections serving cruise-line procurement platforms, while extended production schedules for certified competition wear absorb reformulation investments into base pricing. Three-tier pricing structure across premium athlete certification, standard resort fashion, and economy mass-market levels reflects elastane content and chlorine resistance testing intensity. Pricing pressure stems from petroleum-derived spandex cost volatility feeding into mid-tier products where Brazilian and Argentine price sensitivity limits pass-through capacity. Resort procurement buyers exhibit lowest price elasticity given consolidated hospitality platform purchasing power.
Supply Chain Analysis
Polymer formulation chemist scarcity in Zhejiang and Guangdong manufacturing clusters constrains R&D velocity for chlorine-resistant elastomer development, forcing brands toward German and Swiss laboratory partnerships. Nylon precursor production concentrates in China, elastane feedstock in South Korea and Singapore, and digital knitting equipment supply in Germany and Italy. Raw material dependencies span petroleum-derived polyamide, recycled PET flake, and spandex fiber subject to crude oil benchmark fluctuations. Single-region disruption risk from energy rationing or logistics bottlenecks in Guangdong exposes brands without diversified sourcing. Distribution runs through hospitality procurement platforms consolidating cruise-line and resort volume, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EU Green Deal compliance investments is filtering price-competing entrants from European distribution channels, advantaging incumbents with captive materials science infrastructure and forcing mid-cap brands toward acquisition or exit.
For Market Incumbents: Deepen backward integration into recycled PET flake processing to control input costs and satisfy sustainability procurement criteria from retail partners. Anchor positioning through exclusive supply agreements with cruise-line operators capturing direct-to-resort distribution margins, while accelerating polymer laboratory partnerships in Baden-Württemberg to defend against emerging technical certification competitors.
For New Entrants and Emerging Players: Masters swimming demographic in California and Florida presents underserved white-space demand for biometric pattern-engineered competition wear with UPF 50+ ratings. Brazilian domestic manufacturing clusters offer regional production footholds for Mercosur export expansion with ANVISA-aligned compliance pathways. Direct-to-consumer digital channels with social media discovery optimization capture teenager segment purchasing outside incumbent wholesale relationships.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists possessing regional manufacturing depth and REACH-compliant dye house infrastructure given extended producer responsibility tailwinds from France's AGEC law and emerging EU textile EPR frameworks. Long-term viability favors targets with closed-loop collection infrastructure and FINA certification partnerships. Watch chlorine-resistant recycled polyester breakthrough announcements as inflection indicators for competitive swimwear application viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | Captive recycled PET flake supply secures margin control against petroleum feedstock volatility. |
| Direct-to-Resort Distribution Expansion | Bypassing wholesale intermediaries captures hospitality procurement platform margins and exclusive placement. |
| FINA Certification Partnership Investment | Technical barrier creation defends athlete segment positioning against reformulation-capable entrants. |
| Closed-Loop Collection Infrastructure Buildout | AGEC law compliance positions first-mover advantage in EU extended producer responsibility frameworks. |
| Digital Knitting Technology Adoption | 3D seamless construction eliminates seam failure points and collapses sampling-to-production timelines. |
Study Parameters
Multi-period observation of elastane cost volatility, REACH enforcement timelines, and hospitality procurement platform consolidation anchored the trend analysis, supplemented by interviews with brand materials science directors, resort procurement managers, polymer laboratory R&D leads, and Brazilian textile cluster operations heads. Secondary validation drew from customs trade data, EU ECHA regulatory filings, cruise-line annual procurement disclosures, and SEC 10-K filings of publicly traded sportswear conglomerates. Bottom-up channel volume estimates triangulated against top-down category spending analysis.
Segment-weighting across product type, material composition, style tier, and target audience dimensions structured the analytical framework across the analysis window. CAGRs derived from regression analysis of historical volume trajectories adjusted for regulatory compliance cost absorption and channel shift elasticity. Industry-specific forecast inputs incorporated polymer science talent pipeline constraints and digital knitting equipment deployment rates in São Paulo state manufacturing clusters.
Revisions become necessary when REACH Annex XVII enforcement intensity exceeds modeled timelines, when petroleum-derived spandex pricing breaks established crude oil correlation bands, or when hospitality procurement platform consolidation accelerates beyond cruise-line and resort corridor concentration. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Boot Market
Apparel & Footwear
Official Football Kits Market
Apparel & Footwear
Golf Apparel Market
Apparel & Footwear
Loungewear Market
Apparel & Footwear
Men's Underwear Market
Apparel & Footwear
Sports Apparel Market
Apparel & Footwear
India Denim Jeans Market
Apparel & Footwear
Women's Tights and Leggings Market
Apparel & Footwear
Rugby Apparel Market
Apparel & Footwear
Europe Second-Hand Apparel Market
Apparel & Footwear
Sports Apparel Embellishment Market
Apparel & Footwear
Global Luxury Underwear Market
Apparel & Footwear
Streetwear Market
Apparel & Footwear
Brazil Pet Clothing Market
Apparel & Footwear
Women's Sports and Swimwear Market
Apparel & Footwear
Global Shirt Market