
 Rugby Apparel Market | 2026-2036
Rugby Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Rugby Apparel Market Intelligence
The bundling of on-field kits with off-field supporter wear and training apparel is recalibrating consumer purchasing patterns. This strategy allows brands to capture a larger share of enthusiast spending. Adidas AG leverages its extensive global marketing infrastructure to capitalize on major tournament cycles. In contrast, specialists like Canterbury of New Zealand and Gilbert Rugby focus on high-durability jerseys and equipment for elite-level contact.
Rugby apparel consists of garments engineered for the high-impact nature of the sport, incorporating features like reinforced collar stitching and sublimated grip-assisting textures. These products primarily use high-denier polyester blends for tear resistance, flexibility, and moisture management. Polyester-based fabrics dominate the material segment, prized for performance and sublimation printing compatibility. While the Men's end-user segment is largest, the Women's category represents the fastest-growing demographic.
Product safety and composition are governed by a complex set of international frameworks. The EU's REACH directive restricts chemical substances in textiles, while the US FTC mandates accurate fiber content and origin labeling. Additionally, ISO standards for textile strength and colorfastness are critical for securing supply contracts with professional leagues. Navigating the dual demands of performance innovation and circular economy principles will define competitive differentiation for all apparel makers.
Market Dynamics
The central force shaping the rugby apparel market is the tension between the functional demands of a high-impact sport and the escalating pressure for sustainable manufacturing. This dynamic compels innovation in materials like recycled polyesters that must deliver elite-level tear resistance and moisture management while also meeting circular economy goals.
Growth Catalysts
- Emerging Market Participation:The expansion of rugby's popularity in non-traditional nations, particularly in Japan and the United States, is creating new consumer bases for team kits and supporter merchandise, driving incremental volume growth.
- Advanced Fabric Technology:Innovations in high-denier polyester blends and recycled fabrics offer enhanced durability, flexibility, and moisture-wicking properties, encouraging replacement cycles as amateur and professional teams upgrade their kits for performance gains.
- Major Tournament Cycles:Global events like the Rugby World Cup and the Six Nations Championship stimulate significant spikes in demand for national team jerseys and related apparel, creating predictable and highly valuable sales windows.
Market Restraints
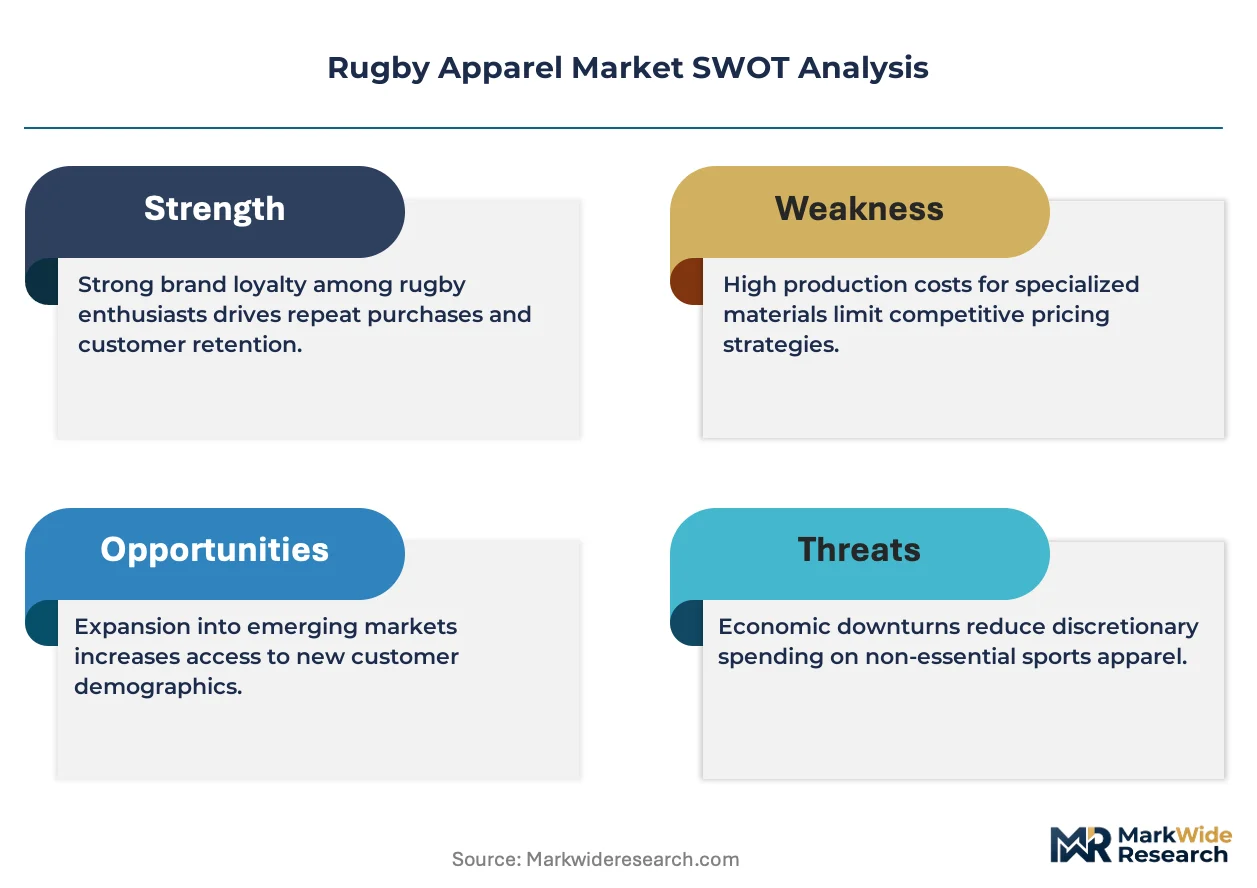
- Raw Material Price Volatility:The market's heavy reliance on polyester, a petroleum derivative, exposes manufacturers to price fluctuations in crude oil markets, which can compress margins or necessitate price increases passed on to consumers.
- Stringent Chemical Regulations:Compliance with directives like the EU's REACH framework adds significant cost and complexity to the supply chain, requiring rigorous testing and documentation for chemical substances used in dyes and fabric treatments.
- Niche Sport Status:Outside of a few core countries, rugby remains a niche sport compared to soccer or basketball, limiting the overall addressable market size and the scale of media rights and sponsorship deals that fuel apparel sales.
Strategic Opportunities
- Women's Rugby Expansion:The women's game is the sport's fastest-growing segment, presenting a significant opportunity to develop and market specifically designed apparel lines that cater to female athletes' performance needs and fit preferences.
- Smart Apparel Integration:Incorporating wearable biometric sensors directly into jerseys offers a new frontier for product differentiation, providing players and coaches with real-time performance data on exertion, impact, and recovery.
- US Market Penetration:With the United States set to host the men's and women's Rugby World Cups in the future, there is a substantial opportunity to build brand presence and capture new fans in a large, underdeveloped market.
Industry Challenges
- Complex Licensing Agreements:Securing apparel contracts with professional leagues and national unions involves navigating complex and often expensive intellectual property and licensing negotiations, creating high barriers to entry for smaller brands.
- Circular Supply Chain Verification:Establishing and auditing a truly circular supply chain for recycled polyester is a major operational challenge, requiring traceability from post-consumer waste collection to final garment production to prevent greenwashing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rugby Apparel Market |
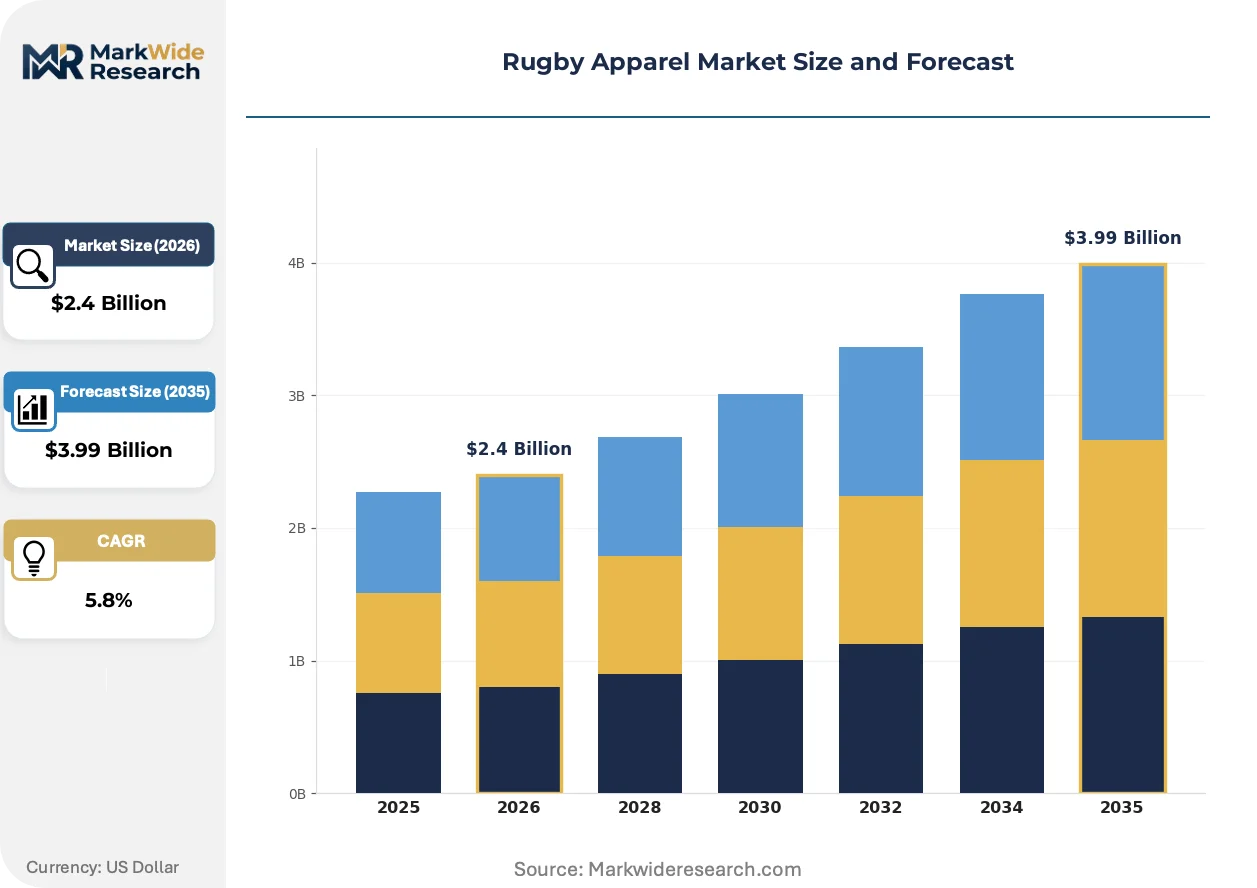
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jerseys, Shorts, Socks, Jackets Material: Polyester, Cotton, Nylon, Spandex End User: Men, Women, Youth, Teams Distribution Channel: Online, Sporting Goods Stores, Specialty Retailers, Others |
| Companies Covered | Decathlon SA, Under Armour Inc., Adidas AG, Kooga Australia, Gilbert Rugby, Nike Inc., Macron S.p.A, O'Neills Irish International Sports Co. Ltd., Canterbury of New Zealand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rugby Apparel Market Strategic Shifts & Innovations
Material science and changing consumer values are jointly steering product development. The focus is on creating apparel that performs under extreme physical stress while aligning with demands for environmental responsibility. This evolution is evident in fabric composition, integrated technology, and new retail strategies.
Sublimated grip-assisting textures applied directly to jersey surfaces provide a functional advantage in ball handling and retention during contact. Professional and elite-level teams are the primary adopters, seeking any competitive edge that equipment can provide. This embedded feature is rewriting performance expectations for contact-specific apparel, integrating grip as an intrinsic garment property.
Implementation of the EU's REACH directive is forcing a significant shift in textile production chemistry. This regulation restricts harmful substances in finished goods, compelling manufacturers to re-engineer their dyeing and finishing processes for products sold in Europe. Consequently, suppliers targeting this lucrative region prioritize sourcing from vendors who can provide certified, compliant materials.
Bundling on-field kits with off-field supporter wear and training apparel is recalibrating consumer purchasing patterns. This strategy moves beyond single-item transactions, encouraging fans to invest in a complete brand ecosystem. This trend is most pronounced in established European rugby nations like France and Ireland, where club identity drives merchandise sales year-round.
Rugby Apparel Market Segmentation
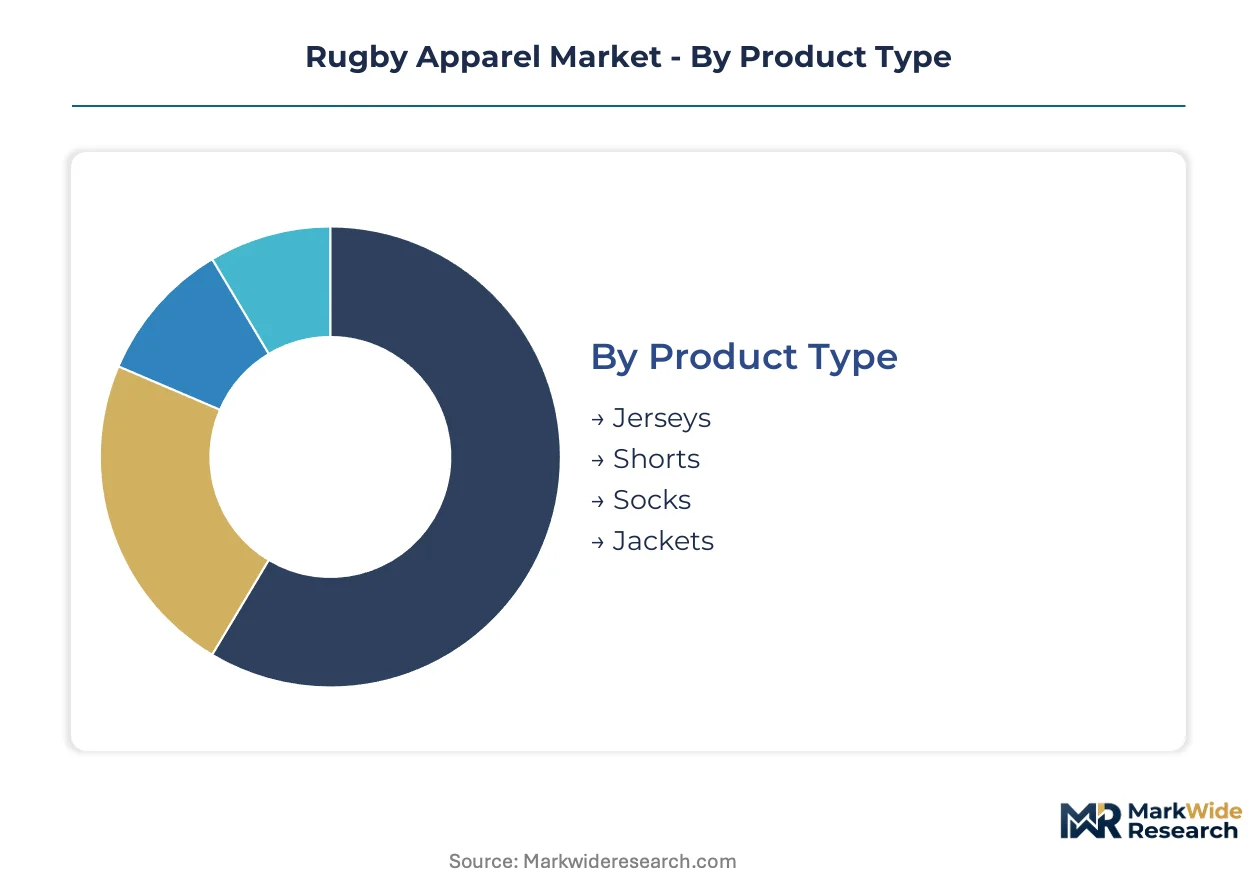
Understanding market segmentation in rugby apparel is crucial for identifying specific consumer needs and tailoring product development. This analysis dissects the market into distinct categories, revealing varied purchasing patterns and growth trajectories across different product types, materials, end-users, and distribution channels. Brands leverage this granular view to refine their offerings and capture specific market opportunities.
Product Type:
The product type segmentation informs how frequently consumers upgrade or replace their rugby apparel, driven by performance needs and wear-and-tear. Innovations in fabric technology and design encourage regular replacement cycles for both amateur and professional players seeking a competitive edge.
- Jerseys:These garments incorporate reinforced collar stitching and sublimated grip-assisting textures, engineered from high-denier polyester blends for tear resistance. Demand concentrates among professional teams and during major tournament cycles, driven by the desire for elite-level performance and national identity.
- Shorts:Constructed from tear-resistant, flexible, and moisture-wicking fabrics, rugby shorts provide essential durability and comfort during play. Demand is significant among amateur players and for general training apparel, where longevity and freedom of movement are paramount.
- Socks:Rugby socks often feature compression elements and reinforced areas to support muscle recovery and enhance player comfort during matches.
- Jackets:Designed for warmth and weather protection, these are primarily used for training sessions, pre-match warm-ups, or off-field supporter wear.
Jerseys sits at the top of the volume ranking, with Jackets climbing the fastest.
Material:
Material choice directly influences the performance characteristics and durability required for high-impact rugby play. Manufacturers prioritize materials that offer specific functional benefits, impacting both product efficacy and consumer satisfaction.
- Polyester:High-denier polyester blends dominate this segment, prized for their tear resistance, moisture-wicking capabilities, and compatibility with sublimation printing. Demand is strong for elite performance apparel and team kits, where these functional properties are non-negotiable.
- Spandex:These elastic fibers are integrated into apparel to provide enhanced flexibility, a form-fitting silhouette, and muscle support. Demand is concentrated in base layers and specialized training wear, where unrestricted movement is critical for athletic performance.
- Nylon:Known for its exceptional strength and abrasion resistance, nylon is frequently blended with other fibers to improve the overall durability of rugby apparel.
- Cotton:Primarily utilized in casual supporter wear or off-field lifestyle apparel, cotton offers natural comfort and breathability for non-playing activities.
Polyester dominates the material segment by volume, while Spandex-blended fabrics command higher price points for specialized performance.
End User:
The end-user segmentation highlights distinct purchasing motivations, ranging from professional performance to fan merchandise. Each demographic presents unique requirements for fit, function, and aesthetic appeal, influencing product design.
- Men:This segment represents the largest consumer base, driven by established participation rates in professional leagues and extensive amateur club structures. Demand concentrates on on-field kits and supporter wear in traditional rugby nations like the United Kingdom and France.
- Women:The women's category is the fastest-growing demographic, necessitating apparel specifically designed for female athletes' unique performance needs and fit preferences. Demand is expanding rapidly with new team formations and increased media visibility for the women's game.
- Youth:This segment focuses on entry-level kits, training gear, and scaled-down apparel, largely driven by grassroots development programs and school sports.
- Teams:Encompassing bulk purchases for entire squads, this segment includes professional, amateur, school, and university-level organizations requiring customized kits.
The Men's segment accounts for the largest share of rugby apparel consumption, with the Women's category exhibiting the most rapid expansion.
Distribution Channel:
Distribution channels determine product accessibility and influence brand reach across diverse consumer touchpoints. Strategic channel selection is vital for maximizing sales and engaging with target audiences effectively.
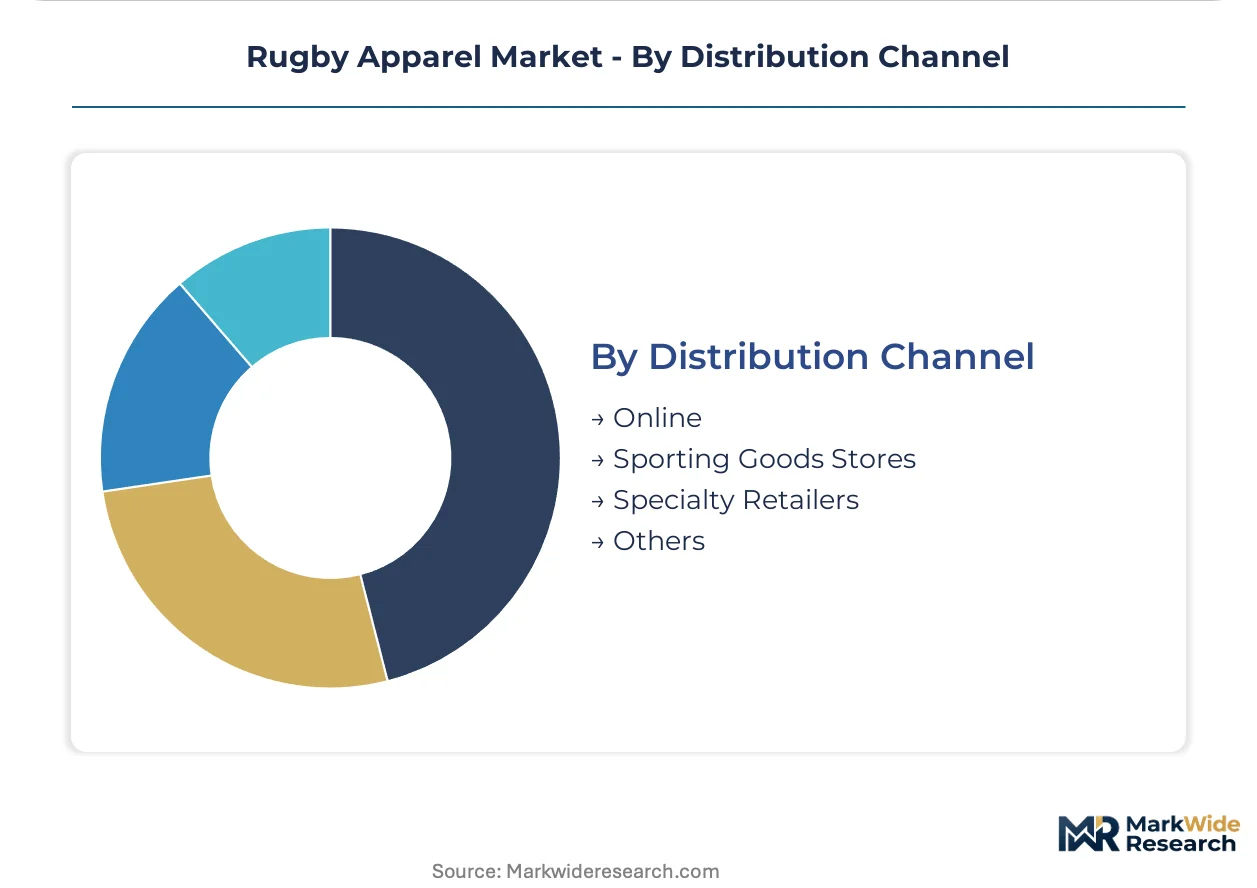
- Online:This channel offers extensive product ranges, global reach, and direct-to-consumer sales capabilities for brands and retailers. Demand concentrates on individual purchases and access to niche products, driven by convenience and broader selection.
- Sporting Goods Stores:These physical retail outlets provide opportunities for product trials, immediate purchase, and interaction with knowledgeable staff. Demand is strong for team bulk orders and general sportswear, especially in major urban centers.
- Specialty Retailers:These stores focus on curated rugby-specific products, often providing expert advice, community engagement, and exclusive merchandise.
- Others:This category includes direct sales at major tournaments, club-specific shops, and custom apparel providers catering to unique team requirements.
Online channels are gaining significant market penetration, while Sporting Goods Stores maintain a critical role for tactile consumer interaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Historical lineage in rugby apparel traces significantly to nations where the sport holds deep cultural roots. These established markets, alongside emerging regions, collectively shape demand for performance gear and supporter merchandise. Expansion into new territories drives volume growth, while traditional strongholds maintain consistent consumption.
United Kingdom
Demand for rugby apparel in the United Kingdom stems from a robust professional league structure and widespread amateur participation. The EU's REACH directive influences material sourcing for textiles sold there. London serves as a central hub for major brand showrooms and retail distribution, facilitating rapid product uptake.
France
French consumer purchasing patterns are recalibrated by strong club identity and national team fervor, particularly during major tournaments. Compliance with EU regulations, including REACH, dictates textile chemical composition for all apparel sold in the market. Toulouse, a prominent rugby city, concentrates specialized retail and team kit suppliers.
Australia
Australian demand for rugby apparel is propelled by strong national team support and a vibrant domestic competition. The country's consumer protection laws require accurate labeling of fiber content and origin. Sydney's sports retail landscape features numerous outlets catering to both professional teams and grassroots clubs.
Japan
Japan's rugby apparel market experiences significant growth due to increasing sport popularity and hosting major international events. METI guidelines for product safety and quality influence local manufacturing standards. Tokyo's sports retail districts showcase premium rugby brands, attracting both players and enthusiastic supporters.
United States
The United States market offers substantial growth opportunities, spurred by rising participation and future Rugby World Cup hosting. The US FTC mandates accurate fiber content and origin labeling for textile products. New York City, with its diverse sports culture, sees rising interest in rugby merchandise and team wear.
Rugby Apparel Market Key Industry Players
The competitive structure tilts toward a tiered system, balancing global sportswear giants with specialized rugby apparel manufacturers. This market features both highly consolidated segments for mass-market appeal and fragmented niches for performance-specific gear. Strategic archetypes include diversified athletic wear conglomerates and dedicated rugby equipment specialists. Dominant competitive moves involve leveraging extensive global marketing infrastructure and focusing on high-durability product innovation.
Within the diversified athletic wear conglomerate tier, Adidas AG anchors a significant market presence, leveraging its global brand recognition and extensive distribution networks. Specialists in high-durability rugby equipment, such as Canterbury of New Zealand, exemplify a focus on elite-level contact performance and technical fabric innovation. Gilbert Rugby also occupies a strong position among dedicated rugby equipment specialists, emphasizing reinforced apparel and specialized gear for professional and amateur players. These companies collectively shape product development and distribution strategies across various consumer segments.
| Leading Market Players |
|---|
| Decathlon SA |
| Under Armour Inc. |
| Adidas AG |
| Kooga Australia |
| Gilbert Rugby |
| Nike Inc. |
| Macron S.p.A |
| O'Neills Irish International Sports Co. Ltd. |
| Canterbury of New Zealand |
| Others |
Cost & Logistics Intelligence
Brent Crude Futures, as a key petroleum derivative benchmark, directly influence polyester raw material costs, which then cascade through the rugby apparel supply chain, impacting pricing tiers for various product types. This commodity price volatility creates a dynamic tension for manufacturers balancing performance specifications with cost control.
Pricing Analysis
A three-tier pricing structure across premium, standard, and economy levels characterizes the rugby apparel market. Price differentiation stems from material quality, such as advanced high-denier polyester blends, and brand equity, with customization for team kits adding value. Pricing softness emerges from intense competition and raw material price volatility, particularly for polyester. Professional teams exhibit lower price sensitivity, prioritizing performance, while amateur clubs and youth segments are highly price-sensitive.
Supply Chain Analysis
Workforce availability in key manufacturing hubs like China, Vietnam, and Bangladesh underpins rugby apparel production. The supply chain relies heavily on polyester and spandex fibers, alongside specialized dyes and fabric treatments. A structural risk involves compliance with stringent chemical regulations such as the EU's REACH directive, adding complexity and cost. Distribution runs through a hybrid model, combining direct online sales with physical sporting goods stores and specialty retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rugby apparel market presents as a stable compounder, with consistent expansion driven by the increasing global participation in the sport, particularly within the women's category. This sustained interest assures predictable demand across various segments.
For Market Incumbents: Anticipate evolving consumer preferences for sustainable products by investing heavily in recycled polyester fabric research and development. Secure long-term licensing agreements with major leagues and national unions to defend market share against emerging brands. Channel control through expanding direct-to-consumer platforms mitigates margin pressure from traditional retail. This strategy also counters potential greenwashing accusations from environmental advocacy groups.
For New Entrants and Emerging Players: Enter via the rapidly expanding women's rugby category, focusing on apparel specifically designed for female athletes' unique fit and performance needs. Target the underdeveloped US market, leveraging future Rugby World Cup hosting to build brand presence among new fans. A strong go-to-market angle involves offering performance-specific designs integrated with verifiable circular economy principles. This approach allows differentiation from established brands.
For Investors and Strategic Acquirers: Asymmetric upside sits with niche specialists demonstrating verifiable circular supply chains or advanced smart apparel integration. The long-term viability of the market remains robust, supported by consistent grassroots development and predictable major tournament cycles. Target innovative mid-cap companies focused on material science breakthroughs or data-driven performance insights. The signal to watch is the increasing adoption of wearable biometric sensors in elite-level rugby kits.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Recycled Polyester R&D | Drives sustainability goals and meets EU REACH directive compliance for textile composition. |
| Expand Women's Apparel Lines | Captures growth from the fastest-growing demographic in rugby, enhancing brand loyalty. |
| Secure Major Tournament Licensing | Capitalizes on predictable demand spikes during global events like the Rugby World Cup. |
| Develop Smart Apparel Integration | Offers real-time performance data to players and coaches, creating product differentiation. |
| Penetrate US Market Aggressively | Leverages future Rugby World Cup hosting to build new consumer bases and brand presence. |
Research Approach
Coverage spans Europe, North America, Oceania, and Asia, with primary inputs from each region informing data collection. This approach combines in-depth interviews with apparel brand executives, team managers, sports retailers, and material scientists. Secondary validation drew from industry association reports, government trade data, company annual filings, and academic textile journals. Both bottom-up and top-down triangulation methods were applied to ensure data accuracy.
Rate-of-change decomposition informed the analytical framework across the analysis window. Segmentation dimensions modeled included product type, material, end-user, distribution channel, and regional rugby participation rates. Compound annual growth rates were derived from historical trends, identified market drivers, and projected adoption curves. Key forecast inputs included global rugby participation statistics and major tournament schedules.
Inputs from publicly available financial disclosures and regulatory databases were available through the study window; gaps in real-time supply chain cost data introduce uncertainty bands. Forecasts reflect assumptions concerning geopolitical stability and raw material supply. Practitioners should monitor global sporting event scheduling changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Ballet Pointe Shoes Market
Apparel & Footwear
Smart Wardrobe Market
Apparel & Footwear
Gym Apparel Market
Apparel & Footwear
Thimbles Market
Apparel & Footwear
Women's Socks Market
Apparel & Footwear
Headwear Market
Apparel & Footwear
Chest Bags Market
Apparel & Footwear
Bra Cups Market
Apparel & Footwear
Mexico Denim Jeans Market
Apparel & Footwear
Global Silk Pajamas Market
Apparel & Footwear
Global Women Pajamas Suits Market
Apparel & Footwear
Football Jerseys Market
Apparel & Footwear
Fitness Apparel Market
Apparel & Footwear
Women's Shirts and Blouses Market
Apparel & Footwear
US Fanny Packs Market
Apparel & Footwear
Outdoor Sports Apparel Market