
 Athletic and Sports Socks Market | 2026-2036
Athletic and Sports Socks Market Size, Share, and Industry Trends Forecast 2026-2036
Athletic and Sports Socks Market Outlook
ISO 14001 environmental management certification is reorganizing supplier qualification protocols across the athletic and sports socks supply chain. Nike, Inc. leverages its vertically integrated manufacturing network to control material sourcing and dyeing processes. Adidas AG anchors its competitive stance through advanced knitting technologies that reduce seam bulk and enhance arch support. Under Armour, Inc. differentiates via proprietary moisture transport systems developed through sustained R&D investment in synthetic fiber engineering.
Athletic and sports socks are engineered textile garments constructed from blended yarns incorporating cotton, polyester, spandex, or merino wool with functional specifications including cushioning density measured in grams per square meter, arch compression measured in millimeters of mercury, and moisture vapor transmission rates exceeding baseline cotton benchmarks. Crew socks occupy the dominant volume position across mass retail channels while compression socks command premium positioning within medical and elite athletic segments due to graduated pressure engineering. The material dimension reveals polyester-spandex blends capturing share from pure cotton constructions as durability and shape retention requirements intensify among frequent users.
The US Federal Trade Commission enforces textile labeling rules under the Textile Fiber Products Identification Act, compelling accurate fiber content disclosure that shapes consumer trust and brand accountability. The EU REACH regulation restricts certain chemical substances in textile finishing processes, directly affecting dye and antimicrobial treatment choices for socks distributed across European markets. OEKO-TEX Standard 100 certification has emerged as a voluntary but increasingly expected threshold for market access in premium distribution channels. Stakeholders must monitor evolving chemical restriction schedules and certification adoption rates to anticipate which suppliers will retain shelf space in regulated environments.
Market Dynamics
Graduated compression engineering is restructuring athletic sock value chains as medical-grade specifications migrate into mass-market performance segments. This technical elevation requires knitting equipment upgrades and recalibrates supplier qualification thresholds across North American and European procurement offices.
Growth Catalysts
- REACH chemical restrictions:EU REACH substance limitations on textile dyes and antimicrobial finishes are accelerating OEKO-TEX Standard 100 adoption, which premium retailers now mandate for shelf access.
- Moisture-wicking synthetic blends:Polyester-spandex constructions with engineered vapor transmission rates are capturing share from cotton in marathon running and CrossFit training applications.
- United States:Organized youth sports participation and specialty running store density in cities like Boston and Austin sustain replacement-cycle compression for performance sock volumes.
Market Restraints
- Petrochemical input volatility:Spandex and polyester yarn costs fluctuate with crude oil derivatives, compressing margin buffers for mid-tier manufacturers without captive polymer supply.
- East Asian knitting equipment concentration:Advanced seamless toe machines and computerized jacquard systems concentrate production tooling in Taiwan and South Korea, creating import dependency for Western brands.
- Graduated pressure calibration limits:Medical-grade compression sock manufacturing requires millimeter-precise mercury gradient control that mass-market knitting lines cannot replicate without capital-intensive retooling.
Strategic Opportunities
- India:Underpenetrated organized retail and rising marathon participation in Mumbai and Bangalore create whitespace for premium performance sock distribution through e-commerce platforms.
- Sustainable dyeing convergence:Waterless supercritical CO2 dyeing technology combined with recycled polyester feedstock addresses regulatory and consumer pressure simultaneously.
- Direct-to-consumer subscription:Replenishment models for athletic socks bypass wholesale margin compression and capture lifetime value from CrossFit box members and trail running clubs.
Industry Challenges
- ISO 14001 auditor scarcity:Environmental management certification for supplier qualification requires trained third-party assessors, creating bottlenecks in factory audit scheduling.
- Legacy ERP integration:Knitting floor sensors for real-time quality monitoring must interface with decades-old textile mill management systems, delaying Industry 4.0 deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Athletic and Sports Socks Market |
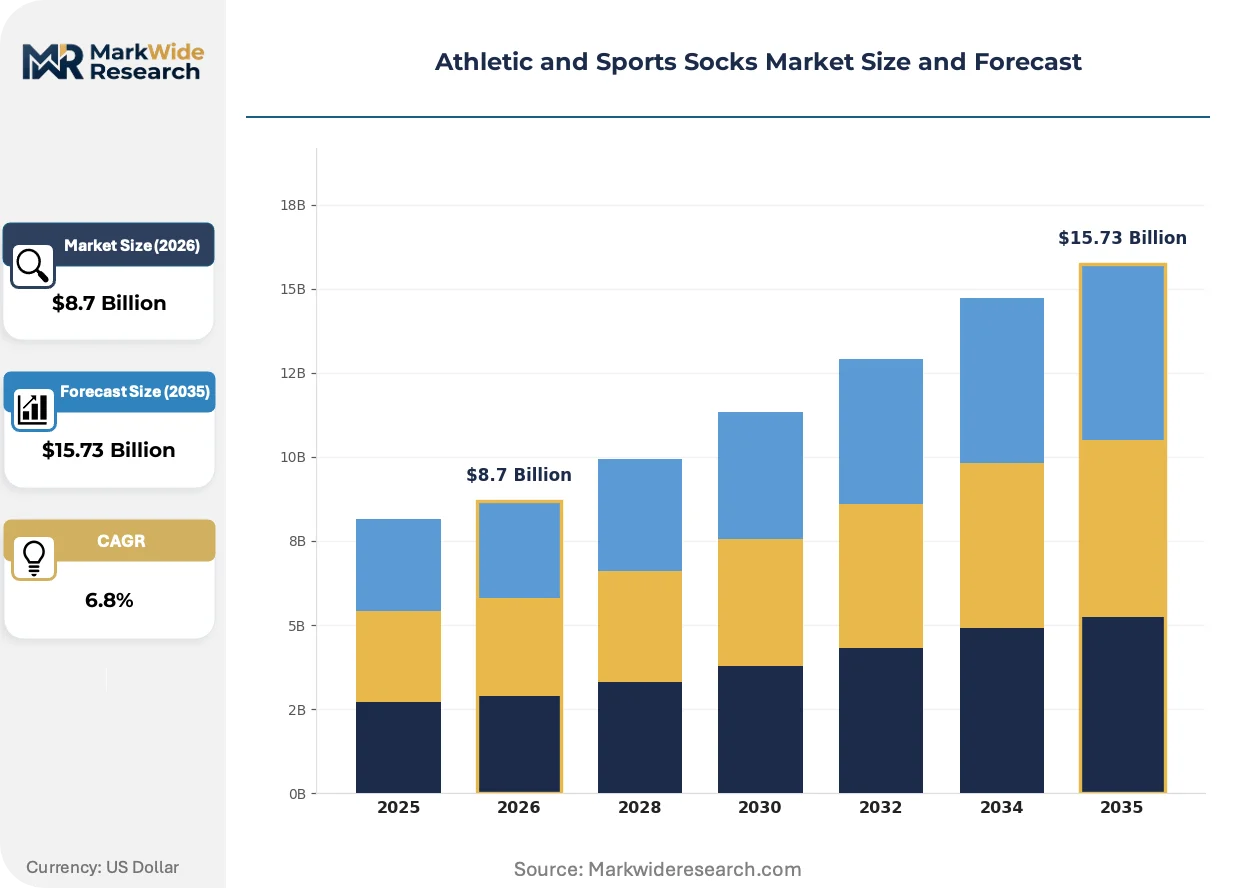
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crew Socks, Ankle Socks, Compression Socks, Knee-High Socks Material: Cotton, Polyester, Spandex, Merino Wool End User: Men, Women, Kids, Athletes Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Sports Apparel Shops |
| Companies Covered | Nike, Inc., Adidas AG, Under Armour, Inc., New Balance Athletics, Inc., PUMA SE, ASICS Corporation, Stance Inc., Balega International, Thorlos, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Athletic and Sports Socks Market Strategic Shifts
Material science advances and regulatory chemical restrictions are converging to redefine performance specifications and manufacturing processes. These forces compress traditional product lifecycles while elevating certification requirements.
Seamless toe closure technology is displacing conventional Rosso linking in performance athletic socks. Elite marathoners and ultrarunners now reject any seam bulk in toe boxes, forcing brands to adopt Santoni circular knitting machines for true seamless construction. This equipment shift is displacing older Italian and Japanese machinery still common in contract manufacturing facilities.
EU REACH Annex XVII restrictions on azo dyes and nickel-releasing components are tightening enforcement across textile finishing operations. German and French market surveillance authorities now conduct random sock sampling at retail, with non-compliant lots facing immediate withdrawal. Medical compression segments face the steepest compliance burden due to prolonged skin contact classification.
Certification-driven purchasing now governs procurement decisions for university athletic departments and municipal recreation programs. Buyers require OEKO-TEX or bluesign documentation before contract award, replacing price-only evaluation. This specification elevation is most visible in California and New York public school systems with mandatory sustainable purchasing directives.
Athletic and Sports Socks Market Segmentation
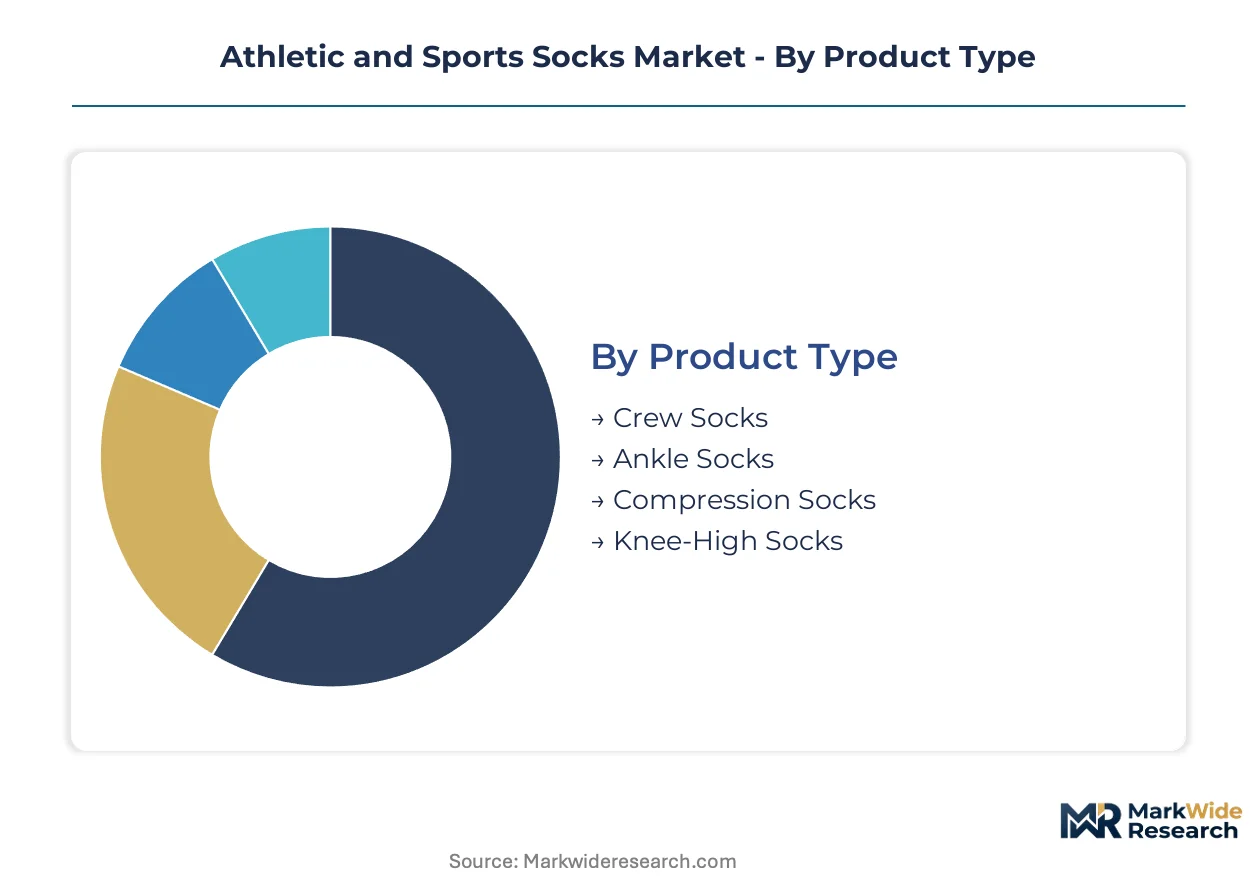
Athletic sock procurement decisions now pivot on certification thresholds and performance specifications rather than commodity pricing. Segmentation clarity enables suppliers to align knitting capacity and dyeing investments with the precise technical requirements of each buyer category.
Product Type:
EU REACH chemical restrictions and OEKO-TEX Standard 100 adoption rates diverge sharply across construction formats, with medical-adjacent segments facing steeper compliance burdens.
- Crew Socks:Mid-calf constructions with cushioning density measured in grams per square meter dominate mass retail replenishment cycles. United States specialty running stores in Boston and Austin sustain replacement-cycle compression for this format as organized youth sports participation broadens.
- Compression Socks:Graduated pressure engineering measured in millimeters of mercury requires Santoni circular knitting machines for precise mercury gradient control. Medical-grade specifications migrating into mass-market performance segments recalibrate supplier qualification thresholds across North American and European procurement offices.
- Ankle Socks:Low-profile designs with minimal cuff height target CrossFit training and indoor court sports where equipment bulk interferes with movement mechanics.
- Knee-High Socks:Extended coverage constructions serve cycling and team sports with uniform compliance requirements, though volume concentrates in institutional purchasing channels.
Established volume favors Crew Socks; emerging adoption favors Compression Socks.
Material:
Cost tier stratification separates premium fiber investments from commodity yarn sourcing, with petrochemical input volatility compressing margin buffers for synthetic-dependent manufacturers.
- Polyester:Engineered vapor transmission rates exceeding baseline cotton benchmarks now define marathon running and CrossFit training applications. Polyester-spandex constructions are capturing share from pure cotton as durability requirements intensify among frequent users.
- Spandex:Elastane content between 3-8% provides arch compression and shape retention critical for performance positioning. Crude oil derivative costs for this input fluctuate without captive polymer supply, forcing mid-tier manufacturers toward backward integration or supplier consolidation.
- Cotton:Natural fiber constructions retain price-sensitive volume in developing markets though moisture management limitations constrain athletic adoption.
- Merino Wool:Temperature-regulating properties command premium positioning in trail running and outdoor segments where odor resistance extends wear cycles between washes.
Polyester and Spandex blends gain share fastest; Cotton retains the largest installed base.
End User:
Customer type determines performance specification intensity, with institutional procurement elevating certification requirements above individual purchasing decisions.
- Athletes:Elite and amateur competitors demand seamless toe closure technology and moisture-wicking synthetic blends with millimeter-precise fit calibration. California and New York public school systems now mandate OEKO-TEX or bluesign documentation before contract award for this segment.
- Men:Volume concentration in mass retail channels sustains replenishment models, though specification elevation is compressing price-only evaluation frameworks.
- Women:Targeted arch support and graduated compression designs address biomechanical differences in foot structure and exercise participation patterns.
- Kids:Growth-driven replacement cycles and organized youth sports participation in the United States sustain volume, with durability requirements exceeding adult segments due to rougher usage patterns.
Athletes drive specification elevation; Men anchor absolute volume.
Distribution Channel:
Supply concentration in East Asian knitting equipment creates import dependency that shapes channel economics, with advanced seamless toe machines concentrating production tooling in Taiwan and South Korea.
- Specialty Stores:Staffed fitting expertise and brand curation justify premium positioning for compression and merino wool constructions. Cities like Boston and Austin with dense specialty running store networks sustain replacement-cycle compression for performance sock volumes.
- Online Retail:Direct-to-consumer subscription models for athletic socks bypass wholesale margin compression and capture lifetime value from CrossFit box members and trail running clubs.
- Sports Apparel Shops:Coordinated merchandising with footwear and athletic wear drives attachment rates, though certification documentation requirements are rising for institutional buyers.
- Supermarkets:Price-driven volume for basic cotton and cotton-blend constructions faces margin pressure from petrochemical input volatility.
Specialty Stores command premium positioning; Online Retail expands fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH chemical restrictions and OEKO-TEX Standard 100 certification mandates are reorganizing supplier qualification protocols across major consumption centers. National textile regulators in developed markets now conduct random retail sampling, with non-compliant lots facing immediate withdrawal. This regulatory elevation concentrates procurement power among certified manufacturers.
United States
Organized youth sports participation and specialty running store density in Boston and Austin sustain replacement-cycle compression for performance sock volumes. The FTC enforces textile labeling rules under the Textile Fiber Products Identification Act, compelling accurate fiber content disclosure. California and New York public school systems mandate OEKO-TEX or bluesign documentation before contract award.
Germany
Marathon participation rates and cycling club membership drive demand for graduated compression engineering with medical-grade specifications. ECHA REACH Annex XVII restrictions on azo dyes tighten enforcement through random sock sampling at retail by market surveillance authorities. The Baden-Württemberg textile cluster hosts advanced knitting equipment suppliers serving premium athletic brands.
China
Domestic fitness participation expansion and rising trail running adoption in Chengdu and Hangzhou create volume growth for moisture-wicking synthetic blends. GB standards for textile safety and MIIT industrial policy guide manufacturing quality benchmarks. The Yangtze River Delta concentration of circular knitting machine producers supplies seamless toe technology to Western brands.
India
Underpenetrated organized retail and rising marathon participation in Mumbai and Bangalore create whitespace for premium performance sock distribution. BIS textile quality standards and DGFT import policies shape competitive access for international brands. The Tiruppur knitwear cluster in Tamil Nadu supplies cotton-blend athletic socks to Middle Eastern and African markets.
Japan
Precision-oriented consumers demand millimeter-precise fit calibration and seamless toe closure technology in marathon and ultrarunning applications. METI industrial standards and JIS textile specifications govern product quality claims. The Osaka-Kobe manufacturing corridor retains specialized knitting capacity for compression sock production.
Athletic and Sports Socks Market Competitive Environment
Player mix skews toward diversified sportswear conglomerates with captive sock divisions rather than pure-play specialists. Market structure concentrates volume among vertically integrated apparel groups possessing in-house synthetic fiber engineering and controlled distribution networks. Three archetypes dominate: technology-led performance innovators, scale-driven mass-market suppliers, and niche compression specialists. Competitive moves center on seamless knitting equipment upgrades and direct-to-consumer subscription model deployment.
Within the technology-led tier, Nike, Inc. and Adidas AG exemplify archetypes leveraging advanced material science and controlled manufacturing networks. Nike's vertically integrated structure enables direct oversight of dyeing processes and fiber sourcing. Adidas anchors positioning through precision knitting technologies that reduce seam bulk. Under Armour, Inc. occupies a distinct position emphasizing proprietary moisture transport systems developed through sustained synthetic fiber engineering investment.
| Leading Market Players |
|---|
| Nike, Inc. |
| Adidas AG |
| Under Armour, Inc. |
| New Balance Athletics, Inc. |
| PUMA SE |
| ASICS Corporation |
| Stance Inc. |
| Balega International |
| Thorlos, Inc. |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day yarn procurement lead times for spandex and polyester feedstock concentrate pricing power with East Asian polymer suppliers and compress margin buffers for Western brands lacking backward integration. This inventory exposure ties directly to crude oil derivative volatility, forcing mid-tier manufacturers toward supplier consolidation or captive polymer arrangements to defend position.
Pricing Analysis
Certification level creates the primary spread across the athletic sock market, with OEKO-TEX Standard 100 and bluesign documentation commanding 15-25% premiums over uncertified alternatives in California and New York institutional procurement. Three-tier pricing structure across premium performance, standard athletic, and economy cotton-blend levels stratifies by moisture-wicking capability and compression engineering intensity. Cost compression in the economy tier intensifies because petrochemical input volatility erodes already thin margins, while specialty running store buyers show least price sensitivity due to staff fitting expertise and brand curation value.
Supply Chain Analysis
Strategic stockpile preferences dominate raw material planning as Taiwan and South Korean seamless knitting equipment makers face order backlogs stretching twelve to eighteen months. Geographic supply concentration centers on China's Yangtze River Delta for circular knitting machines, Vietnam and Bangladesh for cut-and-sew finishing, and Germany's Baden-Württemberg for precision compression calibration systems. Raw material dependencies draw from crude oil derivatives for spandex, recycled PET flake for sustainable polyester, and Australian merino wool for temperature-regulating segments. Single-source vulnerability in Santoni machine procurement creates bottleneck risk. Distribution runs through specialty running stores in Boston and Austin, direct-to-consumer subscription platforms, and institutional procurement offices with mandatory certification documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from direct-to-consumer subscription models that bypass wholesale margin structures and capture lifetime value through automated replenishment cycles.
For Market Incumbents: Consolidate knitting capacity through acquisition of certified suppliers in Portugal and Turkey to reduce East Asian equipment dependency and accelerate OEKO-TEX documentation coverage. Backward integration into recycled polyester feedstock insulates margin structures from petrochemical volatility while meeting California sustainable purchasing mandates.
For New Entrants and Emerging Players: Lead with waterless supercritical CO2 dyeing technology as a regulatory-compliant differentiator in EU markets where REACH Annex XVII enforcement tightens. Target India's underpenetrated organized retail in Mumbai and Bangalore through e-commerce platforms, leveraging the Tiruppur cluster for cotton-blend production and local logistics partnerships.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because regulatory elevation concentrates procurement power among OEKO-TEX and bluesign-certified manufacturers while disqualifying legacy suppliers. Acquisition focus centers on mid-tier knitting facilities with installed Santoni seamless capacity and pending environmental certification. The signal to watch is EU market surveillance authority sampling frequency and withdrawal rates for non-compliant lots.
| Strategic Initiative | Industry Significance |
|---|---|
| Seamless Knitting Equipment Upgrade | Santoni circular machines eliminate toe-box seams that marathoners now reject entirely. |
| Direct-to-Consumer Subscription Launch | Automated replenishment captures lifetime value from CrossFit box members and trail runners. |
| Recycled Polyester Feedstock Integration | rPET sourcing addresses EU REACH restrictions and California sustainable purchasing mandates simultaneously. |
| OEKO-TEX Certification Acceleration | Standard 100 documentation unlocks institutional procurement in New York and California school systems. |
| Waterless Dyeing Technology Deployment | Supercritical CO2 systems eliminate wastewater compliance burdens in European manufacturing. |
Study Parameters
The analysis maps crew sock replenishment cycles, compression sock medical-grade specifications, seamless toe technology adoption, and sustainable dyeing convergence, each validated through procurement directors at specialty running stores, brand managers at diversified sportswear conglomerates, knitting equipment sales engineers, and textile certification auditors. Primary fieldwork combined structured interviews with secondary validation through customs records, SEC apparel company filings, OEKO-TEX certification databases, and EU REACH restriction schedules. Bottom-up volume builds from individual SKU-level replenishment rates triangulated against top-down brand revenue disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeled by product construction format, material blend composition, end-user athlete type, and distribution channel concentration. CAGRs derived from fitted growth curves applied to certified versus uncertified supplier capacity expansion rates, with inputs including marathon participation trajectories in target cities, specialty retail store density metrics, and institutional procurement mandate adoption timelines.
The analysis sits within stated boundaries; outcomes outside sustained EU REACH enforcement intensity, stable crude oil derivative pricing, and continued youth sports participation growth would require recalibration. Forecasts reflect documented assumptions regarding certification adoption curves and equipment upgrade cycles. Revision becomes warranted when East Asian knitting equipment order backlogs exceed twenty-four months or when US public school sustainable purchasing mandates expand beyond California and New York.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Women's Tights and Leggings Market
Apparel & Footwear
Children's Dresses and Skirts Market
Apparel & Footwear
France Denim Jeans Market
Apparel & Footwear
Europe Jeans Market
Apparel & Footwear
Football Jerseys Market
Apparel & Footwear
Women's Blazer Market
Apparel & Footwear
School Shoes Market
Apparel & Footwear
Hats Market
Apparel & Footwear
Australia Denim Jeans Market
Apparel & Footwear
Luxury Fashion Market
Apparel & Footwear
Women's Coats and Jackets Market
Apparel & Footwear
Women Apparel Market
Apparel & Footwear
Mister Cap Market
Apparel & Footwear
India Denim Jeans Market
Apparel & Footwear
Europe Headwear Market
Apparel & Footwear
Outdoor Apparel Market