
 Sailing Jackets Market | 2026-2036
Sailing Jackets Market Size, Share, and Industry Trends Forecast 2026-2036
Sailing Jackets Market Intelligence
The sailing jackets category is consolidating around a sharp split between premium offshore-grade garments with laminated membrane construction and commoditized inshore shells with basic DWR coatings. Helly Hansen leverages its Scandinavian heritage and professional skiwear R&D pipeline to sustain technical credibility at the top end. Musto anchors its position through deep ties to competitive sailing circuits and British maritime institutions. Gill Marine differentiates via specialized race-wear geometries developed with Olympic and America's Cup crews.
Sailing jackets are technical outerwear engineered for marine environments, combining hydrostatic head ratings above 10,000 mm with moisture vapor transmission rates exceeding 15,000 g/m²/24hr through multi-layer ePTFE or PU membranes, primarily to protect wearers from hypothermia, spray impact, and wind chill during prolonged water exposure. The waterproof segment leads volume as coastal cruisers prioritize storm-ready protection over packability, while the breathable feature tier captures margin concentration as athletes and professionals demand active-comfort engineering. Gore-Tex material formulations occupy the premium price band through proprietary membrane durability, whereas nylon constructions compete on cost efficiency in youth and entry-level recreational channels.
REACH in Europe restricts perfluorinated chemical treatments, forcing reformulation of durable water repellents across supply chains, while ISO 12402 personal flotation compatibility standards shape design integration in competitive and professional end-use tiers. The US Coast Guard's recreational boating safety guidelines indirectly influence jacket visibility and color-coding requirements for domestic waters. Stakeholders must monitor membrane chemistry transitions and certification convergence between sailing-specific and broader outdoor-industry standards to anticipate compliance costs and product architecture shifts.
Market Dynamics
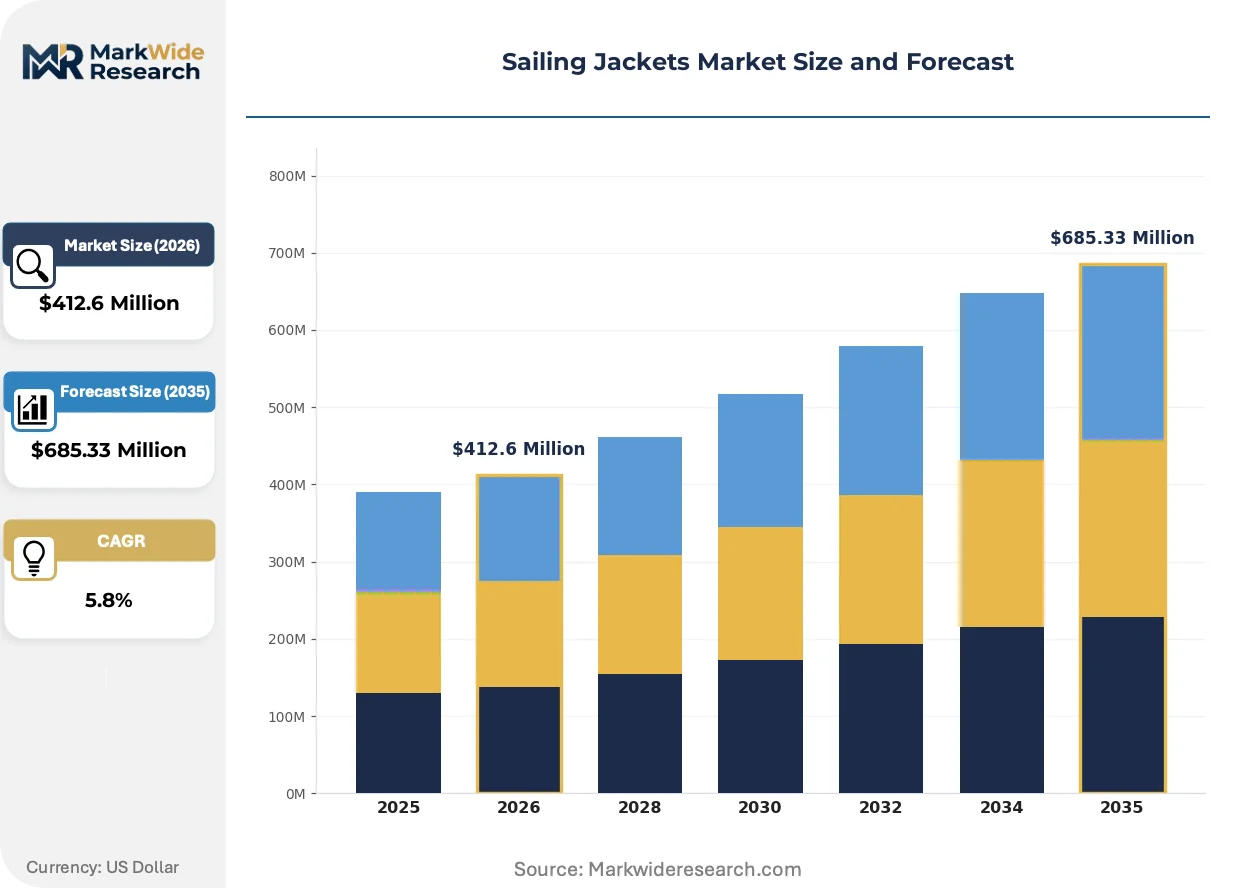
The sailing jackets market is bifurcating around membrane chemistry transitions, as REACH restrictions on perfluorinated compounds force wholesale DWR reformulation while Gore-Tex and ePTFE alternatives compete for technical credibility in offshore-grade segments.
Growth Catalysts
- Coastal tourism expansion:Recreational sailing participation in Mediterranean and British coastal clusters is generating sustained replacement demand for entry-level and mid-tier waterproof shells.
- REACH compliance deadlines:European chemical regulations are accelerating R&D investment in fluorine-free durable water repellents, creating first-mover advantages for suppliers with certified alternatives.
- Laminated membrane advances:Multi-layer ePTFE construction with hydrostatic head ratings exceeding 15,000 mm is penetrating amateur racing segments previously served by basic PU coatings.
Market Restraints
- Petrochemical input volatility:Nylon 6,6 and polyester yarn prices fluctuate with crude oil indices, compressing margin stability for mid-tier manufacturers without long-term supply contracts.
- Membrane supplier concentration:Premium waterproof-breathable film production concentrates among three specialized chemical firms, creating bottleneck risk for brands seeking offshore-grade certification.
- Technical performance ceilings:Moisture vapor transmission rates above 20,000 g/m²/24hr remain elusive without sacrificing hydrostatic head durability, limiting comfort gains in high-exertion racing applications.
Strategic Opportunities
- Asia-Pacific recreational expansion:Marina development in Thailand, Australia, and New Zealand is cultivating first-time sailing participation with attendant outerwear purchase requirements.
- ISO 12402 integration:Personal flotation compatibility standards create design specifications that specialist sailing brands can leverage against generalist outdoor apparel competitors.
- Direct-to-crew digital channels:America's Cup and Olympic sailing teams now procure race-wear through dedicated portals, bypassing traditional retail markup structures.
Industry Challenges
- Pattern engineering talent scarcity:Specialized marine garment construction requiring articulation for winch handling and harness integration faces limited trained technician supply.
- Dual certification timelines:Simultaneous pursuit of ISO 12402 flotation compatibility and CE marking for spray-tight integrity extends product development cycles by eight to fourteen months.
- Legacy inventory obsolescence:C8 fluorocarbon-based DWR treatments in existing channel stock face accelerated write-down risk as retailer sustainability policies tighten.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sailing Jackets Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Insulated, Waterproof, Windproof, Lightweight Material: Gore-Tex, Nylon, Polyester, Softshell End User: Professionals, Recreational Sailors, Youth, Competitors Feature: Breathable, Reflective, Adjustable Cuffs, Packable |
| Companies Covered | Helly Hansen, Musto, Gill Marine, Henri Lloyd, Zhik, SLAM, Marinepool, Sail Racing, Burke Marine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sailing Jackets Market Strategic Shifts & Innovations
Membrane chemistry, regulatory compliance architecture, and procurement channel structure are simultaneously transforming how sailing outerwear is specified, certified, and acquired across recreational and professional tiers.
Fluorine-free durable water repellent formulations derived from hyperbranched polymers and plant-based wax emulsions are electrifying the mid-tier waterproof segment. Coastal cruising sailors in the United Kingdom and Netherlands are adopting these alternatives at accelerating rates as retailer sustainability mandates harden. This chemistry transition is compressing technical differentiation between premium and standard price bands, forcing membrane suppliers to compete on breathability metrics rather than legacy hydrophobic performance.
REACH Annex XVII restrictions on perfluorooctanoic acid and related compounds are eliminating long-chain fluorocarbon treatments from European supply chains. Manufacturers must reformulate DWR finishes and revalidate hydrostatic head performance under accelerated aging protocols. The offshore racing segment, where spray-tight integrity carries safety-critical weight, is absorbing the steepest compliance costs and extending product validation timelines.
Club and team procurement officers are consolidating annual outerwear purchases through centralized digital platforms with embedded size-scanning and customization tools. Traditional chandlery retail in British and Australian sailing clusters is losing volume to these specialized B2B portals. This channel migration is most pronounced among competitive dinghy and keelboat programs with standardized crew kit requirements.
Sailing Jackets Market Segmentation
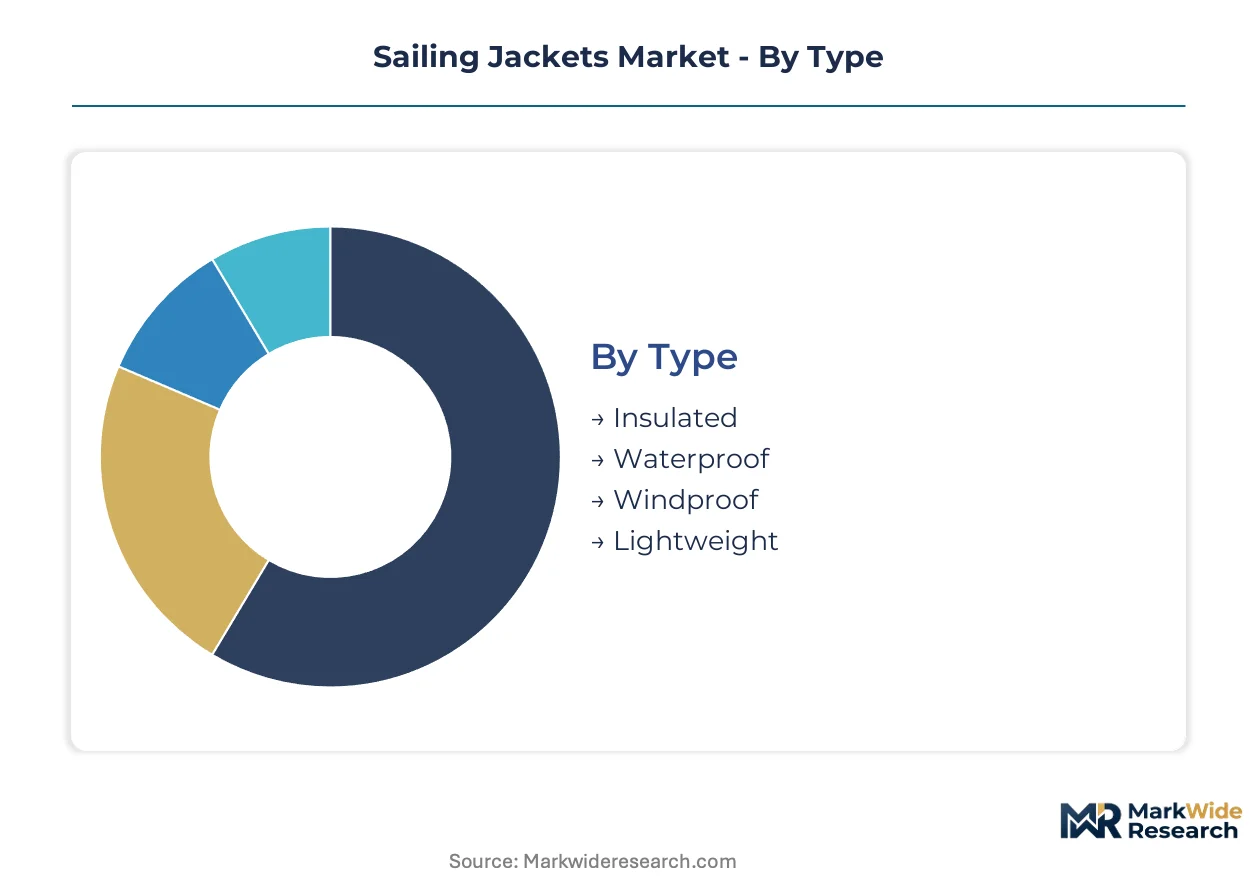
Sailing jackets serve distinct functional roles across thermal management, environmental protection, and mobility requirements. Segmentation reveals how membrane technologies, user expertise levels, and activity-specific features create divergent value propositions and margin structures within marine outerwear.
Type:
Standalone thermal solutions dominate cold-water cruising while integrated weather protection systems serve layered configurations across temperate sailing clusters.
- Insulated:PrimaLoft and synthetic down fill constructions maintain core temperature in North Sea and Baltic conditions. British offshore cruisers and Norwegian coastal fleets drive replacement cycles as hydrostatic head degradation accelerates in salt-spray environments.
- Waterproof:Multi-layer ePTFE membranes with fully taped seams achieve hydrostatic head ratings exceeding 15,000 mm. Mediterranean charter operators and Solent weekend sailors prioritize storm-ready protection over packability, anchoring volume concentration in United Kingdom and French Atlantic ports.
- Windproof:Densely woven nylon face fabrics with DWR treatment block convective heat loss without waterproof breathability overhead. Spring and autumn inshore racing in Netherlands and Denmark sustains steady demand for this intermediate protection tier.
- Lightweight:Packable 2.5-layer constructions compress to sub-liter volumes for emergency deployment. Dinghy sailors and coastal day-trippers in Australia and New Zealand adopt these as backup layers against sudden weather shifts.
Volume placements concentrate in Waterproof; the faster expansion belongs to Lightweight.
Material:
Membrane chemistry and face fabric construction determine price tier positioning and regulatory compliance pathways across European and Asia-Pacific supply chains.
- Gore-Tex:Proprietary expanded polytetrafluoroethylene membranes deliver validated durability across 10,000+ hour offshore exposures. America's Cup syndicates and Volvo Ocean Race crews specify Gore-Tex Pro Shell for its abrasion resistance against deck hardware.
- Nylon:High-tenacity 6,6 yarns provide tear strength at reduced fabric weight versus polyester. Entry-level cruising jackets from Chinese and Vietnamese manufacturing bases compete on cost efficiency for charter fleet provisioning.
- Polyester:Hydrolysis-resistant polymers suit tropical UV exposure better than nylon alternatives. Thai marina retail and Australian chandlery channels stock polyester-dominant lines for recreational sailors in high-irradiance climates.
- Softshell:Bonded fleece-membrane laminates prioritize mobility over waterproof integrity. Inshore racing crews in Cowes and Hamble favor softshell mid-layers for winch handling agility in moderate conditions.
Revenue gravity centers on Gore-Tex at the premium tier; polyester constructions are climbing the fastest among first-time recreational buyers.
End User:
Expertise gradients and safety-critical requirements fragment demand across certification standards, durability expectations, and procurement channel preferences.
- Professionals:Commercial fishermen, maritime pilots, and search-and-rescue operators require ISO 12402-compatible flotation integration. Norwegian Sea pilot services and British RNLI crews mandate visibility-compliant colorways with spray-tight collar architectures.
- Recreational Sailors:Coastal cruisers and weekend keelboat owners represent the broadest addressable base. Cowes Week participants and Solent sailing club members generate replacement demand through social fleet standardization pressures.
- Youth:Sizing adaptations and growth-accommodating features dominate product specification. UK RYA training centers and Australian Tackers programs procure durable entry-level shells with reinforced knee and seat panels.
- Competitors:Olympic, America's Cup, and offshore racing crews demand anatomical patterning for harness and trapeze compatibility. New Zealand's Emirates Team New Zealand and British INEOS Britannia drive technical co-development partnerships with specialist marine apparel brands.
Unit economics favor Recreational Sailors for absolute volume; Competitors command the steepest per-garment margins through customization premiums.
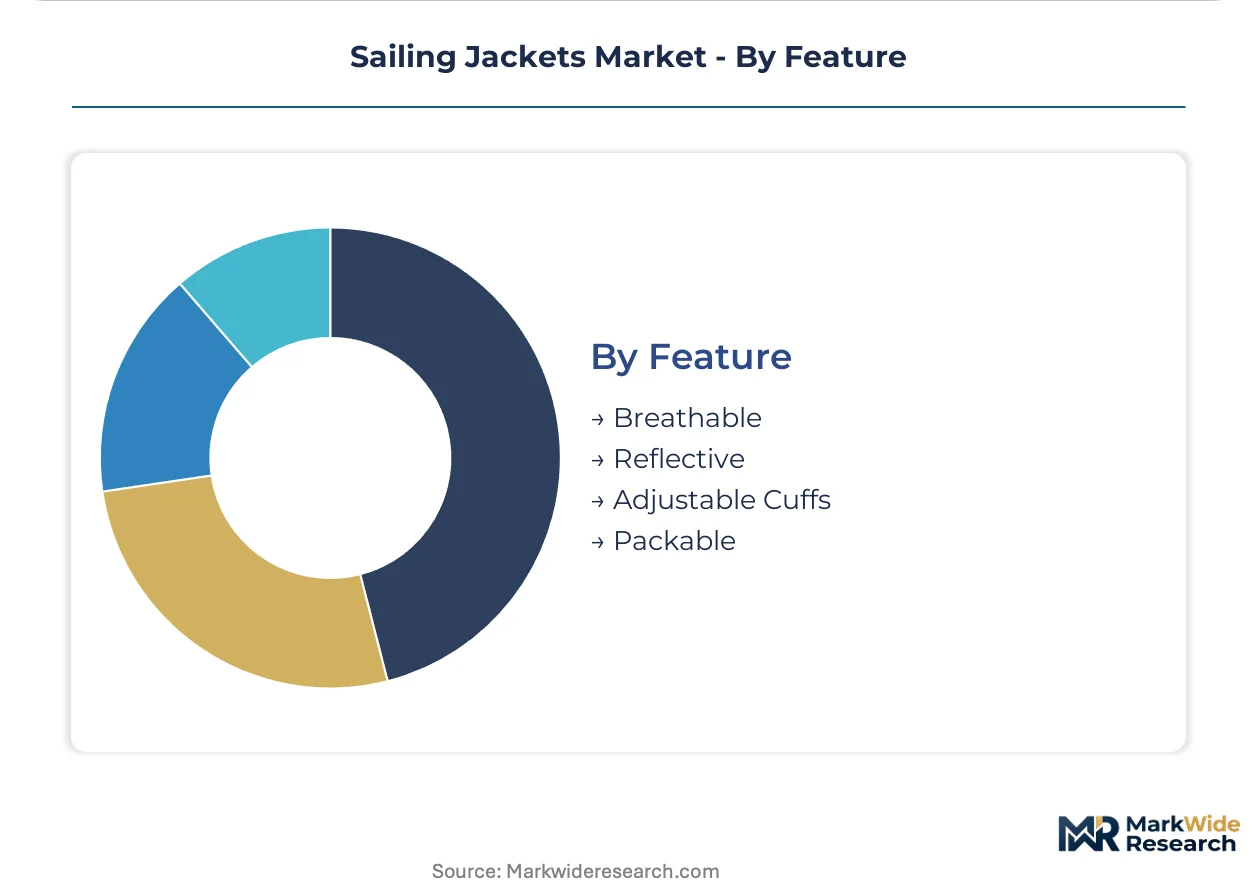
Feature:
Functional priorities diverge between passive protection requirements and active-comfort engineering for high-exertion sailing disciplines.
- Breathable:Moisture vapor transmission rates above 15,000 g/m²/24hr prevent condensation buildup during aerobic deck work. Dinghy racers in Sydney Harbour and Portsmouth prioritize breathability over absolute waterproofing for hiking and trapeze maneuvers.
- Reflective:Retroreflective tape placement meets SOLAS visibility standards for night passages and rescue scenarios. Channel Island cruisers and Scottish west coast sailors specify reflective accents for fog-prone navigation zones.
- Adjustable Cuffs:Neoprene and Velcro wrist closures prevent water ingress during wave impact. Offshore racing crews in Fastnet and Sydney-Hobart events demand cuff systems compatible with glove layering and watch access.
- Packable:Self-stowing pockets and compression straps enable emergency layer deployment without deck locker storage. Mediterranean flotilla sailors and Caribbean bareboat charterers value packability for luggage-constrained travel.
Feature prioritization clusters on Breathable for racing applications; Packable functionality is gaining share fastest among fly-to-sail tourism segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Solent sailing cluster around Cowes and Portsmouth sustains the United Kingdom's dominant position in sailing jacket demand through year-round racing calendars and institutional fleet procurement.
United Kingdom
Cowes Week and the RYA training network drive replacement cycles for waterproof-breathable shells. REACH compliance deadlines from ECHA force DWR reformulation across British brands. The Hamble-Warsash corridor concentrates specialist marine apparel R&D and pattern engineering talent.
United States
Coastal cruising expansion in Chesapeake Bay and Pacific Northwest generates mid-tier demand for storm-ready protection. US Coast Guard recreational boating safety guidelines influence visibility and color-coding specifications. Newport, Rhode Island anchors competitive sailing procurement through America's Cup syndicate relationships.
Australia
Sydney Harbour racing and Melbourne's offshore passage-making sustain technical outerwear adoption. TGA-equivalent standards for personal flotation compatibility shape product integration requirements. The Cruising Yacht Club of Australia drives crew kit standardization for Sydney-Hobart participants.
France
Mediterranean charter fleets and Atlantic offshore racing create dual demand tiers for coastal and offshore-grade jackets. CE marking requirements under EU marine equipment directives govern spray-tight integrity certification. Lorient and La Rochelle host technical sailing apparel manufacturing for competitive circuits.
New Zealand
Emirates Team New Zealand and Olympic sailing programs anchor high-performance outerwear development. The country's maritime safety regulator mandates flotation compatibility for commercial and competitive applications. Auckland's Viaduct Harbour concentrates elite sailing team procurement and technical co-development partnerships.
Sailing Jackets Market Key Industry Players
Premium-margin players sit above commodity-margin players across membrane technology and certification depth, creating a tiered structure where technical credibility separates price bands. The market consolidates around heritage marine specialists with professional sailing circuit ties and diversified outdoor apparel groups leveraging cross-category R&D. Three archetypes dominate: Scandinavian-origin technical outerwear houses, British sailing heritage brands, and Asia-Pacific race-wear specialists. Competitive moves concentrate on fluorine-free chemistry transitions and direct-to-team digital procurement channel development.
Among heritage British specialists, Musto and Gill Marine exemplify the professional sailing circuit anchor archetype, while Helly Hansen represents Scandinavian technical outerwear diversification into marine applications. These three occupy positions where competitive sailing credibility translates into premium pricing authority across offshore-grade and inshore racing segments.
| Leading Market Players |
|---|
| Helly Hansen |
| Musto |
| Gill Marine |
| Henri Lloyd |
| Zhik |
| SLAM |
| Marinepool |
| Sail Racing |
| Burke Marine |
| Others |
Cost & Logistics Intelligence
Competitive sailing team procurement officers concentrate annual outerwear purchases through direct digital portals, anchoring value-based pricing to ISO 12402 certification tiers and membrane durability metrics rather than commodity fabric costs. This buyer archetype's technical specifications cascade downward through recreational channels, compressing margin structures for mid-tier suppliers without offshore-grade credibility.
Pricing Analysis
Offshore survival ratings serve as the value-based pricing anchor, with hydrostatic head thresholds above 15,000 mm and CE spray-tight certification commanding substantial premiums over inshore-grade alternatives. Price differentiation rests on membrane chemistry pedigree and professional sailing circuit validation. Cost compression in entry-level nylon constructions is intensifying as Chinese manufacturing bases expand capacity, while premium Gore-Tex formulations resist erosion through limited supplier concentration. Charter fleet operators exhibit highest price sensitivity; America's Cup syndicates demonstrate lowest.
Supply Chain Analysis
Container freight volatility from Vietnamese and Chinese manufacturing hubs to European chandlery networks has amplified landed cost uncertainty for mid-tier brands without regional fulfillment infrastructure. Membrane production concentrates in Japan, USA, and Germany; face fabric weaving draws from Taiwan, South Korea, and Italy. Single-source vulnerability pervades ePTFE film supply, with three specialized chemical firms controlling offshore-grade certification pathways. Distribution runs through British and Australian chandlery clusters, though direct-to-team digital portals are capturing competitive sailing volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sailing jackets market sits in a chemistry-transition phase, with fluorine-free durable water repellent formulations displacing legacy C8 fluorocarbon treatments across European supply chains.
For Market Incumbents: Hedge membrane supplier concentration risk through dual-source qualification of hyperbranched polymer DWR alternatives before REACH Annex XVII deadlines harden. Secure pattern engineering talent in the Hamble-Warsash corridor through apprenticeship pipelines, as technical construction expertise faces scarcity against generalist outdoor apparel competitors. Prioritize ISO 12402 flotation compatibility certification to defend against generalist brands encroaching from hiking and ski categories. For New Entrants and Emerging Players: The mid-tier price-point gap between Gore-Tex premium formulations and basic PU-coated entry-level shells offers white-space for fluorine-free membrane alternatives with validated breathability metrics. Target Mediterranean charter fleet provisioning through B2B digital platforms with embedded crew-sizing tools, bypassing established chandlery relationships. Pursue technical co-development partnerships with Olympic sailing programs to fast-track credibility without legacy retail infrastructure. For Investors and Strategic Acquirers: The window for entry favors specialist marine apparel brands with professional sailing circuit relationships and captive pattern engineering capabilities. Long-term viability hinges on chemistry-transition execution and direct procurement channel penetration rather than retail footprint scale. Watch for consolidation signals when dual certification timelines compress smaller players' product development bandwidth beyond sustainable thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Chemistry Transition | REACH Annex XVII compliance eliminates legacy C8 treatments, rewarding first-mover reformulation investments. |
| Direct-to-Team Digital Platform Launch | America's Cup and Olympic syndicates bypass retail markup through dedicated procurement portals. |
| ISO 12402 Certification Investment | Personal flotation compatibility standards create defensive moats against generalist outdoor apparel entrants. |
| Pattern Engineering Talent Acquisition | Specialized marine garment construction expertise concentrates in British Solent clusters facing scarcity. |
| Asia-Pacific Manufacturing Footprint Expansion | Thai and Australian marina development cultivates first-time sailing participation with attendant outerwear demand. |
Research Approach
Independent corroboration across brand product managers, chandlery procurement directors, and competitive sailing team equipment officers underwrites the qualitative findings on membrane technology transitions and channel migration patterns. Secondary validation draws from ECHA regulatory filings, customs trade data for marine apparel categories, and professional sailing circuit technical specifications. Bottom-up segment sizing triangulates against top-down market value estimates derived from manufacturer capacity disclosures and regional participation statistics.
Comparable historical periods across membrane chemistry transitions in adjacent outdoor apparel categories anchored the forecast window's growth trajectory assumptions. The analytical framework models segmentation across jacket type, membrane material, end-user expertise tier, and functional feature prioritization, with CAGRs derived from regression against coastal tourism indices and sailing participation surveys. Input variables include REACH compliance cost absorption rates and professional sailing team procurement cycle timing.
Inputs from brand technical directors and regulatory affairs specialists were available through the study window; gaps in real-time DWR formulation performance data under accelerated aging protocols introduce uncertainty bands around hydrostatic head degradation curves. Forecasts reflect documented assumptions regarding fluorine-free chemistry adoption velocity and digital procurement channel penetration rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Ballet Pointe Shoes Market
Apparel & Footwear
Gym Apparel Market
Apparel & Footwear
Secondhand Apparel Market
Apparel & Footwear
Streetwear Market
Apparel & Footwear
Fitness Apparel Market
Apparel & Footwear
Apparel Re-Commerce Market
Apparel & Footwear
Denim Jeans Market
Apparel & Footwear
Bathrobe Market
Apparel & Footwear
Ethnic Wear Market
Apparel & Footwear
Global Apparel and Footwear Market
Apparel & Footwear
Boot Market
Apparel & Footwear
Multiple Toe Socks Market
Apparel & Footwear
North America Jeans Market
Apparel & Footwear
Smart Heating Scarf Market
Apparel & Footwear
Football Jerseys Market
Apparel & Footwear
Custom Cycling Clothing Market