
 Press-To-Close Zippers Market | 2026-2036
Press-To-Close Zippers Market Size, Share, and Industry Trends Forecast 2026-2036
Press-To-Close Zippers Market Analytics
ISO 9001 quality management certification is reorganizing competitive tiers among press-to-close zipper suppliers, elevating vendors with documented process controls above commodity producers. Amcor plc leverages its integrated film-to-zipper manufacturing footprint across multiple continents to sustain cost advantages. Sonoco Products Company anchors its position through specialized R&D in resealable packaging formats for perishable goods. Flexico Group differentiates via European production sites that compete on lead-time reliability for just-in-time apparel supply chains.
Press-to-close zippers are mechanical fastening devices consisting of interlocking profile elements, typically extruded from polyethylene or polypropylene, that engage through finger pressure and separate via pull-tab action; they seal packages against moisture and contaminants while enabling repeated access. Plastic zippers dominate volume due to lower unit costs and compatibility with flexible film substrates, though water-resistant zippers command premium positioning in outdoor gear applications where submersion protection determines product performance. The application split reveals luggage as a mature segment with stable replacement demand, while household items represent an expanding category as consumers seek resealable storage solutions beyond traditional food packaging.
FDA food-contact substance regulations govern material composition for zipper elements used in US-packaged consumables, while REACH restrictions on phthalates and heavy metals constrain European formulation choices; both frameworks elevate testing burdens that favor suppliers with dedicated compliance laboratories. China's GB standards for plastic packaging safety add a third compliance layer for exporters sourcing from domestic manufacturers. Stakeholders must monitor evolving extended producer responsibility mandates, as packaging waste regulations in multiple jurisdictions threaten to impose cost recovery obligations on zipper-integrated flexible packaging systems.
Market Dynamics
Flexible packaging converters in China and Southeast Asia are consolidating purchasing power through cooperative procurement alliances, squeezing margin structures for mid-tier zipper suppliers while elevating certified manufacturers with documented traceability systems.
Growth Catalysts
- FDA Food-Contact Substance Notifications:US packaged food manufacturers face mandatory material documentation requirements that favor zipper suppliers with dedicated compliance laboratories and pre-submitted FCN dossiers.
- Outdoor Gear Waterproofing Standards:IPX-rated zippers for submersible dry bags and technical apparel command 3-4x unit premiums over standard polyethylene profiles, pulling extrusion capacity toward performance grades.
- EU Extended Producer Responsibility Mandates:Packaging waste directives in France, Germany, and Italy now assign cost-recovery obligations to flexible packaging systems, creating procurement preference for mono-material zipper constructions that simplify recycling streams.
Market Restraints
- Polypropylene Feedstock Volatility:Propylene monomer prices tied to naphtha cracking economics expose zipper extruders to margin compression when oil benchmarks swing beyond 15% quarterly bands.
- REACH Phthalate Restrictions:ECHA's evolving SVHC candidate list forces continuous plasticizer reformulation in European-sourced zipper elements, extending qualification timelines for new material batches.
- Mechanical Slider Substitution:Traditional coil zippers with metal sliders retain cost advantages in heavy-duty luggage applications above 15kg load ratings, limiting press-to-close penetration in premium baggage segments.
Strategic Opportunities
- India FSSAI Packaging Safety Notifications:India's 2023 plastic packaging regulations create first-mover advantage for zipper suppliers establishing local extrusion and testing infrastructure ahead of full enforcement.
- Pharmaceutical Compliance-Grade Zippers:USP Class VI and ISO 10993 biocompatibility certifications open medical device pouches and diagnostic kit packaging as adjacent revenue pools with 40-60% gross margin profiles.
- Digital Print-to-Package Integration:Inline zipper application systems coupled with HP Indigo and Xeikon presses enable lot-size-one customization for craft food brands, collapsing minimum order quantities from 50,000 to 5,000 units.
Industry Challenges
- ISO 9001:2015 Transition Audits:Small and mid-cap extruders in China's Zhejiang and Guangdong provinces face 12-18 month certification gaps as notified bodies clear pandemic backlogs, freezing access to multinational brand supplier lists.
- Interoperability with Legacy Form-Fill-Seal Lines:Retrofitting 1990s-era Hayssen and Bosch packaging equipment for press-to-close zipper integration requires mechanical redesigns that extend commissioning timelines and strain maintenance technician availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Press-To-Close Zippers Market |
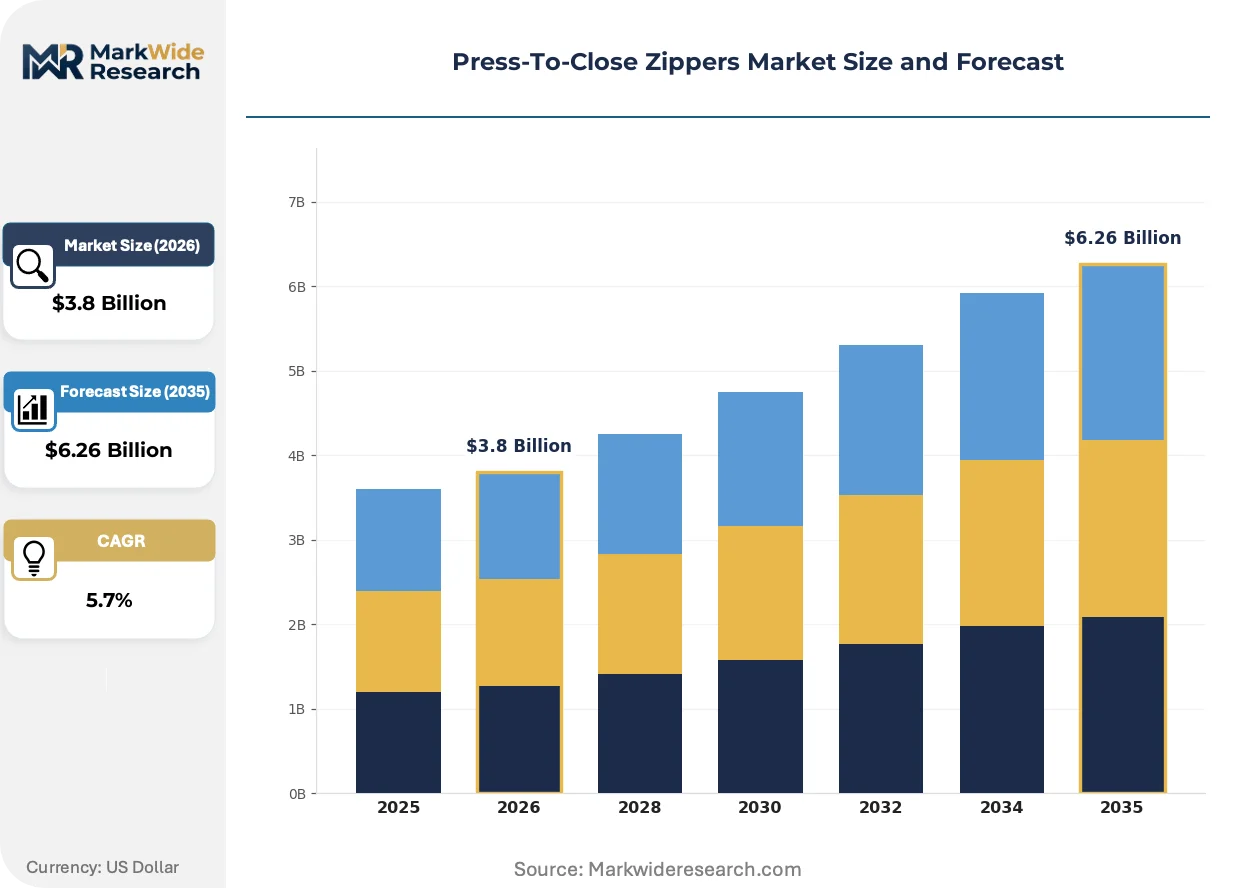
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Zippers, Metal Zippers, Water-Resistant Zippers, Decorative Zippers Application: Apparel, Outdoor Gear, Luggage, Household Items End User: Manufacturers, Retailers, Consumers, Designers Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Zip-Pak, Sealed Air Corporation, Sonoco Products Company, Amcor plc, Flexico Group, Reynolds Consumer Products Inc, Mondi Group, Huhtamaki Oyj, Glenroy Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Press-To-Close Zippers Market Evolving Landscape
Material science advances and regulatory pressure on recyclability are compressing product development cycles while fragmenting the supplier base into specialized tiers defined by certification depth rather than scale alone.
Biodegradable zipper profiles incorporating polylactic acid and PBAT blends are fragmenting the conventional polyethylene market as European food brands face 2025 single-use plastic reduction targets. Nestlé and Unilever procurement teams now require zipper suppliers to submit third-party compostability certifications from TÜV or DIN CERTCO as table stakes for contract renewal. This materials shift is fragmenting extruder capabilities into PLA-certified specialists versus commodity polyolefin producers facing stranded asset risk.
REACH Annex XVII restrictions on intentionally added microplastics will prohibit non-biodegradable loose plastic elements in consumer products sold across the EU from 2027. Zipper slider assemblies and pull tabs under 5mm dimension thresholds face reformulation mandates or design elimination. German and Dutch packaging engineers are responding with integrated pull-loop designs molded directly into zipper profiles, eliminating detachable components.
Brand-direct sourcing platforms are collapsing traditional distributor layers in North American flexible packaging procurement. Small-batch food startups in Austin, Brooklyn, and Portland now specify zipper specifications through web-based configurators that bypass regional packaging distributors. This channel compression is most visible in the specialty coffee and pet treat segments, where 10,000-unit pilot runs with custom-printed press-to-close pouches have become standard new product launch protocol.
Press-To-Close Zippers Market Segmentation
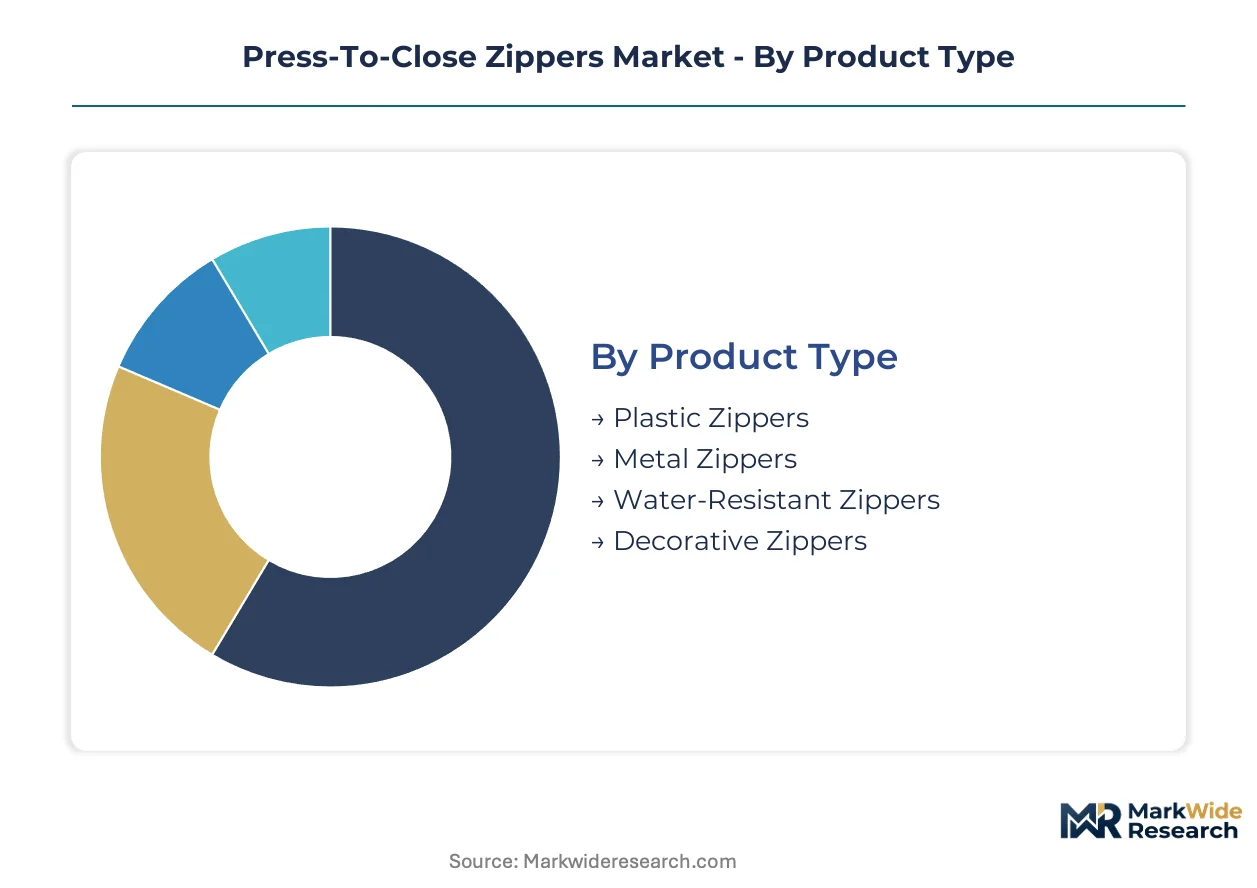
Segmentation in press-to-close zippers reveals how material science, end-use performance requirements, and channel economics split demand across incompatible supplier capabilities. Each category exposes distinct margin structures and certification barriers that reshape competitive positioning.
Product Type:
Plastic zippers dominate domestic consumption in food packaging clusters across China and the United States, while water-resistant grades concentrate in export-led outdoor gear supply chains serving European and Japanese technical apparel brands.
- Plastic Zippers:Extruded polyethylene and polypropylene profiles constitute the volume base, with formulation flexibility enabling rapid color matching and custom width production. Chinese converters in Zhejiang province consume the majority for domestic flexible food packaging, though FDA food-contact compliance requirements now filter supplier qualification lists for US-bound exports.
- Water-Resistant Zippers:Coated or co-extruded profiles with welded seam compatibility command premium positioning in submersible dry bags and alpine outerwear. Demand clusters in Germany and Japan where IPX-rated performance specifications determine brand supplier selection; REACH-compliant material documentation extends qualification cycles.
- Metal Zippers:Aluminum and brass coil constructions retain niche positioning in heavy-duty luggage above 15kg load ratings where mechanical sliders outperform press-to-close fatigue limits.
- Decorative Zippers:Custom-colored and textured profiles serve fashion-forward apparel segments in Italy and France where aesthetic differentiation justifies unit cost premiums over commodity alternatives.
Plastic zippers hold the largest share; momentum sits with water-resistant grades climbing the fastest on technical outdoor gear specification upgrades.
Application:
Cost tier stratification separates mature replacement-driven categories from emerging resealable convenience applications where zipper integration enables packaging format premiums.
- Apparel:Casual and activewear segments in Bangladesh and Vietnam drive polyethylene zipper consumption for cost-optimized fast fashion production. European sustainable fashion mandates are shifting procurement toward mono-material zipper constructions that simplify garment recycling streams.
- Outdoor Gear:Technical backpacks, tents, and protective cases require submersible-grade sealing performance. Japanese and German brands specify TPU-laminated zipper tapes with hydrostatic head ratings above 10,000mm; suppliers without dedicated testing laboratories face exclusion.
- Luggage:Replacement demand stabilizes volume as product lifecycles extend and repair culture gains traction in Nordic markets; coil zippers with metal sliders retain cost advantages in premium baggage segments.
- Household Items:Resealable storage bags and organizational pouches represent the steepest expansion trajectory as US and UK consumers adopt zipper-equipped solutions beyond traditional food packaging for closet and garage storage applications.
Luggage commands established volume; household items are gaining share fastest on convenience-driven consumer behavior shifts.
End User:
Customer type determines order scale, specification complexity, and certification burden in ways that fragment supplier targeting strategies.
- Manufacturers:Flexible packaging converters and apparel contractors in China's Pearl River Delta purchase zippers in roll form for inline application; ISO 9001 certification has become a mandatory supplier list filter for multinational brand compliance programs.
- Retailers:Private label packaging programs at US and UK grocery chains specify custom-printed zipper pouches with lot-size-one flexibility requirements that favor digital print-to-package integration investments.
- Consumers:Direct-to-consumer zipper replacement kits and repair services constitute a fragmented long-tail channel concentrated in North American and Western European e-commerce marketplaces.
- Designers:Independent fashion and accessory creators in Brooklyn, London, and Tokyo source small-batch decorative zippers through brand-direct sourcing platforms that collapse traditional distributor markups.
Manufacturers represent the dominant procurement volume; designers are expanding most quickly on brand-direct platform adoption.
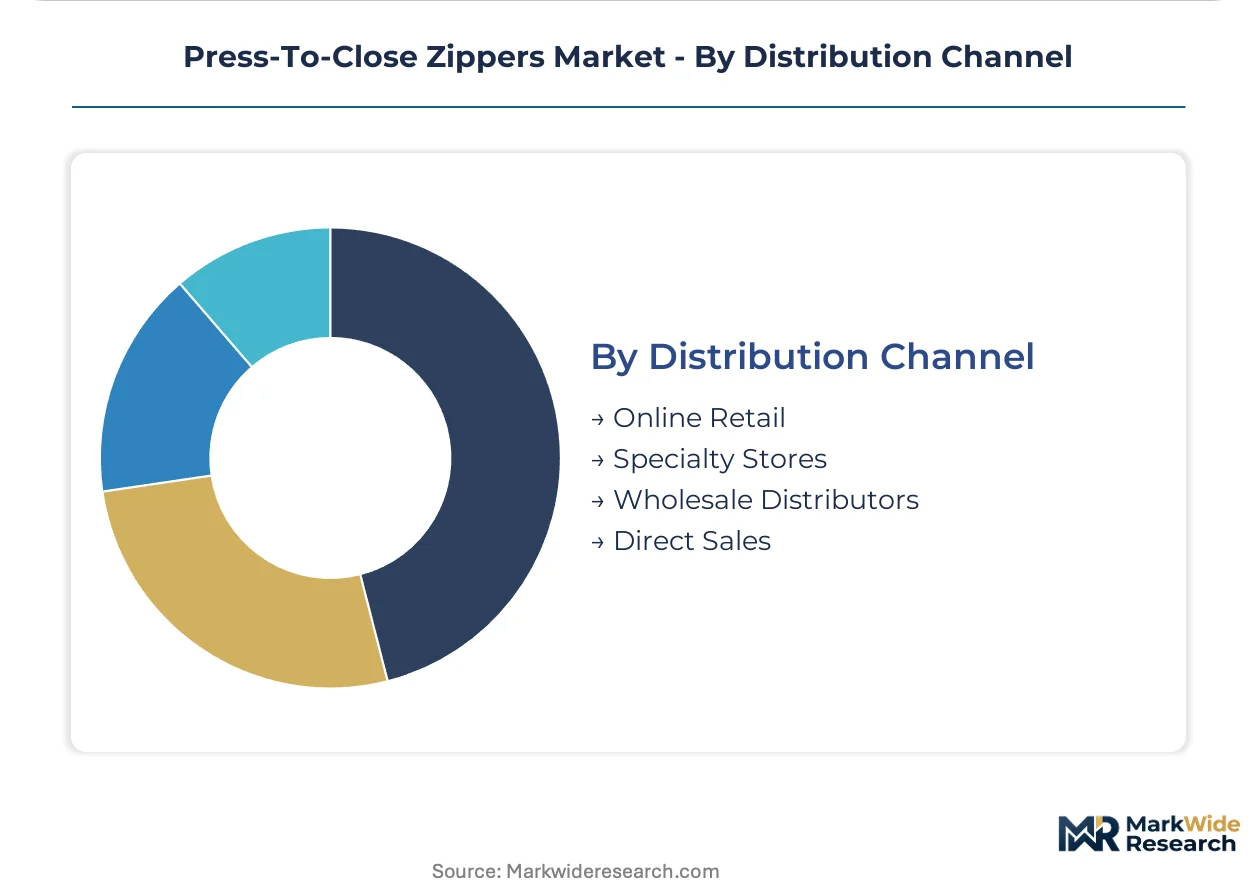
Distribution Channel:
Channel configuration varies sharply by geography, with developed markets showing faster e-commerce penetration than export-manufacturing clusters dependent on wholesale distributor relationships.
- Online Retail:Alibaba and domestic B2B platforms serve China's packaging converter base with spot purchasing flexibility; Amazon Business and specialized packaging marketplaces gain traction among US and European small-batch buyers seeking reduced minimum order quantities.
- Specialty Stores:Regional packaging supply houses in Italy and France maintain inventory depth for fashion industry rush orders where color matching and rapid sample turnaround determine supplier relationships.
- Wholesale Distributors:Traditional layered distribution retains dominance in Southeast Asian manufacturing corridors where credit terms and consolidated logistics outweigh price transparency advantages of direct sourcing.
- Direct Sales:Amcor and Sonoco field organizations bypass intermediaries for multinational food brand accounts with dedicated technical service requirements and annual volume commitments.
Wholesale distributors retain the largest share; online retail is climbing the fastest on platform-enabled procurement fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flexible packaging converters in China's Pearl River Delta and Zhejiang province purchase press-to-close zippers at the highest volumes globally. FDA food-contact compliance requirements now filter supplier qualification lists for US-bound exports from these manufacturing clusters.
China
Export-oriented packaging clusters in Wenzhou and Cangzhou supply global apparel and outdoor gear brands with polyethylene zipper profiles. GB standards for plastic packaging safety add compliance layers for domestic manufacturers serving multinational accounts. Zhejiang province hosts the densest concentration of mid-cap extruders facing ISO 9001:2015 certification backlogs.
United States
Packaged food manufacturers in Chicago and New Jersey metro areas drive demand for FDA-compliant zipper-integrated flexible pouches. FCN dossier requirements favor suppliers with dedicated compliance laboratories and pre-submitted material notifications. California's extended producer responsibility mandates create procurement preference for mono-material zipper constructions.
Germany
Technical outdoor gear brands in Bavaria and Baden-Württemberg specify REACH-compliant water-resistant zippers with hydrostatic head ratings above 10,000mm. ECHA's SVHC candidate list forces continuous plasticizer reformulation in zipper elements. The country's national packaging regulator implements cost-recovery obligations under EU extended producer responsibility frameworks.
India
FSSAI packaging safety notifications from 2023 create first-mover advantage for zipper suppliers establishing local extrusion infrastructure. Maharashtra and Gujarat industrial corridors attract investment ahead of full enforcement. Mumbai-based flexible packaging converters consolidate purchasing power through cooperative procurement alliances.
Japan
IPX-rated zipper demand from Tokyo and Osaka outdoor gear manufacturers commands 3-4x unit premiums over standard profiles. METI industrial standards influence technical specification development across Asia-Pacific supply chains. Nagoya-area apparel contractors source decorative zippers for fashion-forward segments requiring aesthetic differentiation.
Press-To-Close Zippers Market Competitive Landscape
Player mix skews toward integrated flexible packaging conglomerates with captive zipper manufacturing capabilities. Tier-one suppliers leverage continental production footprints to sustain cost advantages and lead-time reliability. Two strategic archetypes dominate: film-to-zipper integrators competing on vertical scope, and specialized extruders competing on certification depth and custom formulation agility. Dominant competitive moves include geographic expansion through greenfield extrusion facilities and technology licensing partnerships for digital print-to-package integration systems.
Within the integrated packaging tier, Amcor plc and Sonoco Products Company exemplify scale-driven positioning through multi-continent manufacturing footprints. Flexico Group occupies a specialist position among European production sites competing on lead-time reliability for just-in-time apparel supply chains. These three companies represent contrasting archetypes: the global integrator, the diversified packaging conglomerate, and the regional specialist.
| Leading Market Players |
|---|
| Zip-Pak |
| Sealed Air Corporation |
| Sonoco Products Company |
| Amcor plc |
| Flexico Group |
| Reynolds Consumer Products Inc |
| Mondi Group |
| Huhtamaki Oyj |
| Glenroy Inc. |
| Others |
Value Network & Pricing Analysis
FDA food-contact substance notifications gate both supplier qualification lists and price differentiation tiers simultaneously, forcing extruders with dedicated compliance laboratories to capture premium positioning over commodity producers lacking FCN dossiers. This regulatory threshold compresses margin structures for mid-tier suppliers while elevating certified manufacturers with documented traceability systems.
Pricing Analysis
Long-term offtake contracts with naphtha-indexed polypropylene feedstock clauses dominate procurement between Chinese extruders and multinational packaging converters. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant water-resistant grades from FDA-certified food-contact profiles and commodity polyethylene constructions. Cost compression in standard-grade segments is intensifying because flexible packaging converters in Southeast Asia are consolidating purchasing power through cooperative procurement alliances. Small-batch craft food brands show least price sensitivity due to lot-size-one customization requirements and digital print-to-package integration premiums.
Supply Chain Analysis
China and Vietnam anchor global press-to-close zipper extrusion, with Zhejiang province hosting the densest concentration of mid-cap producers and Bangladesh emerging as a secondary hub for apparel-integrated zipper consumption. Raw material dependencies draw from Saudi Arabian and South Korean propylene monomer supply, TPU coating resins from German and Japanese chemical specialists, and color masterbatches from domestic Chinese compounders. Single-source vulnerability concentrates in FDA-compliant food-contact additive formulations where pre-qualified supplier lists extend qualification timelines. Distribution runs through wholesale distributor networks in Southeast Asian manufacturing corridors, with direct sales organizations bypassing intermediaries for multinational accounts with dedicated technical service requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
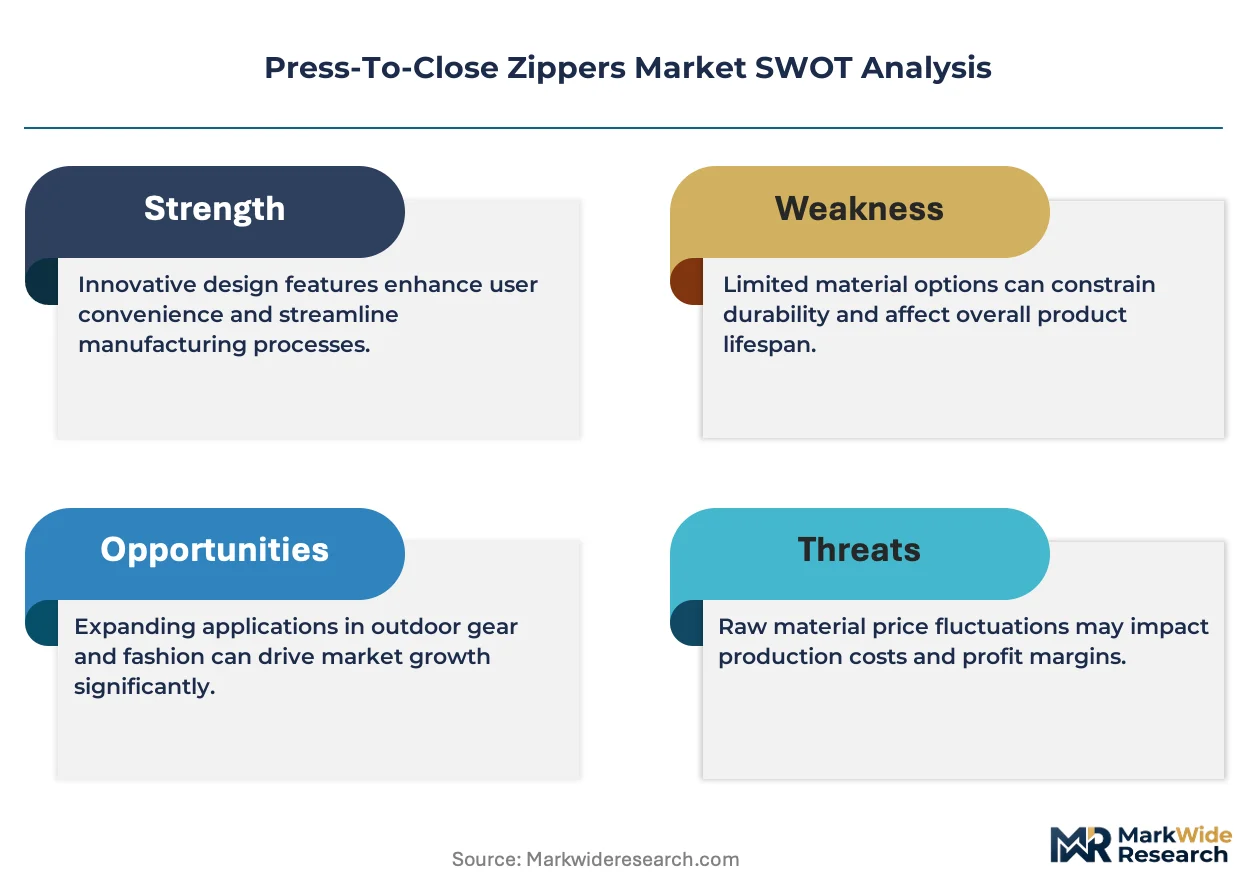
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA and REACH compliance investments create switching costs that lock multinational brand accounts into established supplier relationships.
For Market Incumbents: Secure backward integration into polypropylene compounding to defend margin position against feedstock volatility, while expanding ISO 10993 biocompatibility certification capabilities to capture pharmaceutical packaging adjacencies. Capacity addition in Maharashtra and Gujarat industrial corridors captures first-mover advantage ahead of full FSSAI enforcement. Threat of mechanical slider substitution in heavy-duty luggage above 15kg load ratings limits press-to-close penetration in premium baggage segments. For New Entrants and Emerging Players: Small-batch digital print-to-package integration services represent the most penetrable white-space where incumbent film-to-zipper integrators under-serve craft food startups in Austin, Brooklyn, and Portland. Target India's emerging flexible packaging converter base with local extrusion infrastructure ahead of full FSSAI packaging safety notification enforcement. Go-to-market angle: web-based configurator platforms that collapse minimum order quantities from 50,000 to 5,000 units with inline zipper application systems. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European extruders with REACH-compliant water-resistant specialization and stranded Chinese commodity producers facing ISO 9001:2015 certification backlogs. Long-term viability favors mono-material zipper construction capabilities as extended producer responsibility mandates propagate across EU member states. Signal to watch: Nestlé and Unilever procurement teams requiring third-party compostability certifications from TÜV or DIN CERTCO as table stakes for contract renewal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Compounding | Captive feedstock supply insulates margin structures from naphtha cracking volatility exposure. |
| ISO 10993 Biocompatibility Certification Investment | USP Class VI credentials open medical device pouches with 40-60% gross margin profiles. |
| Greenfield Extrusion Facility in Maharashtra | Local FSSAI-compliant infrastructure captures procurement consolidation by Mumbai-based converters. |
| Digital Print-to-Package Integration Partnership | Inline zipper application with HP Indigo presses collapses minimum order quantities for craft brands. |
| Mono-Material Zipper Construction Development | Simplified recycling streams align with EU extended producer responsibility cost-recovery obligations. |
Research Methodology
Operator-level perspectives from extrusion plant managers, flexible packaging procurement leads at multinational food brands, regulatory affairs specialists at FDA-compliant suppliers, and aftermarket distribution channel partners anchored the qualitative base. Primary interview insights combined with secondary validation from customs and trade data, SEC 10-K filings of integrated packaging conglomerates, FCN submission databases, and ECHA SVHC candidate list updates. Bottom-up volume modeling across product type, application, end user, and distribution channel dimensions triangulated against top-down macroeconomic drivers.
Sensitivity analysis tested forecast robustness across propylene monomer price bands, certification backlog durations, and extended producer responsibility implementation timelines over the projection horizon. Segmentation dimensions modeled include material grade tier, end-use performance specification, regional regulatory cluster, and channel procurement scale. CAGRs derived from historical trajectory analysis adjusted for structural shifts in compliance burden and materials substitution toward biodegradable PLA-PBAT blends. Industry-specific inputs incorporated FSSAI enforcement phasing and IPX-rated outdoor gear specification upgrade cycles.
Material uncertainties — polypropylene feedstock volatility beyond 15% quarterly bands, REACH Annex XVII microplastic restriction implementation, and ISO 9001:2015 certification backlog clearance rates — sit outside the modeled envelope. Forecasts reflect assumptions regarding cooperative procurement alliance formation and digital print-to-package adoption curves. Recalibration cycles align with material shifts in regulatory enforcement timelines and brand-direct sourcing platform penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Secondhand Apparel Market
Apparel & Footwear
Smart Heating Scarf Market
Apparel & Footwear
North America E-Commerce Apparel Market
Apparel & Footwear
South Africa Denim Jeans Market
Apparel & Footwear
Apparel and Leather Products Market
Apparel & Footwear
Asia Pacific Swimwear Market
Apparel & Footwear
Premium Denim Jeans Market
Apparel & Footwear
Thermal Underwear Market
Apparel & Footwear
Sports Apparel Market
Apparel & Footwear
Maternity Activewear Market
Apparel & Footwear
Global Pickleball Clothing and Apparel Market
Apparel & Footwear
Golf Apparel Market
Apparel & Footwear
US Fanny Packs Market
Apparel & Footwear
Online Apparel Market
Apparel & Footwear
Fast Fashion Apparel Market
Apparel & Footwear
Rugby Apparel Market