
 Official Football Kits Market | 2026-2036
Official Football Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Official Football Kits Market Insights
Capital-intensity divergence between fully integrated manufacturers and outsourced apparel specialists is bifurcating competitive dynamics in official football kits. Nike leverages vertical integration from fiber innovation to direct-to-consumer channels across North America and Western Europe. Adidas sustains R&D intensity through its Speedfactory-adjacent prototyping networks and premium national-team sponsorships. Puma anchors its position via aggressive pricing and emerging-market club partnerships, particularly in Africa and Latin America.
Official football kits comprise standardized match and training apparel ensembles—jerseys, shorts, and socks—engineered from moisture-wicking knitted fabrics, typically 100% recycled or virgin polyester with elastane blends for compression zones, produced through sublimation or heat-transfer printing to achieve lightweight, breathable performance. Home kits and away kits constitute the mature revenue core, while third kits generate disproportionate margin through limited-edition scarcity and collector-driven online retail velocity. Goalkeeper kits represent a smaller addressable pool but command premium positioning due to specialized padding requirements and lower substitution rates within squad rotations.
REACH restrictions on azo dyes and perfluorinated chemicals, plus the EU Green Deal's textile sustainability requirements, are elevating compliance costs and favoring suppliers with certified recycled supply chains. The US Federal Trade Commission's Green Guides enforce substantiation standards for environmental marketing claims on kit labeling. Stakeholders must monitor how evolving extended producer responsibility frameworks in the European Union reshape material sourcing obligations and retail pricing power across the value chain.
Market Dynamics
REACH azo-dye restrictions and the EU Green Deal's textile sustainability mandates are forcing kit suppliers to re-engineer supply chains around certified recycled polyester and waterless dyeing infrastructure, compressing margins for non-compliant producers.
Growth Catalysts
- Brazilian domestic league licensing:Copa América merchandising cycles and local club partnerships drive volume concentration in Latin America's largest football economy.
- REACH chemical compliance:European regulatory pressure on perfluorinated chemicals accelerates supplier migration toward certified recycled supply chains with traceability documentation.
- Academy kit refresh expansion:Youth development programs and amateur clubs are shortening replacement cycles from biennial to annual patterns.
Market Restraints
- Recycled polyester input volatility:Ocean-bound plastic feedstock pricing fluctuates with coastal collection infrastructure capacity in Southeast Asia.
- Dyeing equipment concentration:Waterless sublimation machinery suppliers cluster in Germany and Italy, creating single-source vulnerability for scale-up.
- Perfluorinated chemical substitution limits:Current fluorine-free water-repellent treatments degrade faster under match-day laundering protocols.
Strategic Opportunities
- Collector-driven third kit channels:Limited-edition scarcity models through direct-to-consumer platforms capture premium margin from enthusiast segments.
- African federation partnerships:Underpenetrated national team licensing agreements in Nigeria, Morocco, and Senegal offer first-mover positioning.
- EU Green Deal compliance services:Extended producer responsibility frameworks create demand for lifecycle assessment and take-back program infrastructure.
Industry Challenges
- Sublimation technician scarcity:Specialized color-matching expertise for heat-transfer printing requires 18-24 month training pipelines that outpace workforce expansion.
- Legacy sizing standard fragmentation:Federation-specific fit specifications complicate inventory pooling across multiple national team contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Official Football Kits Market |
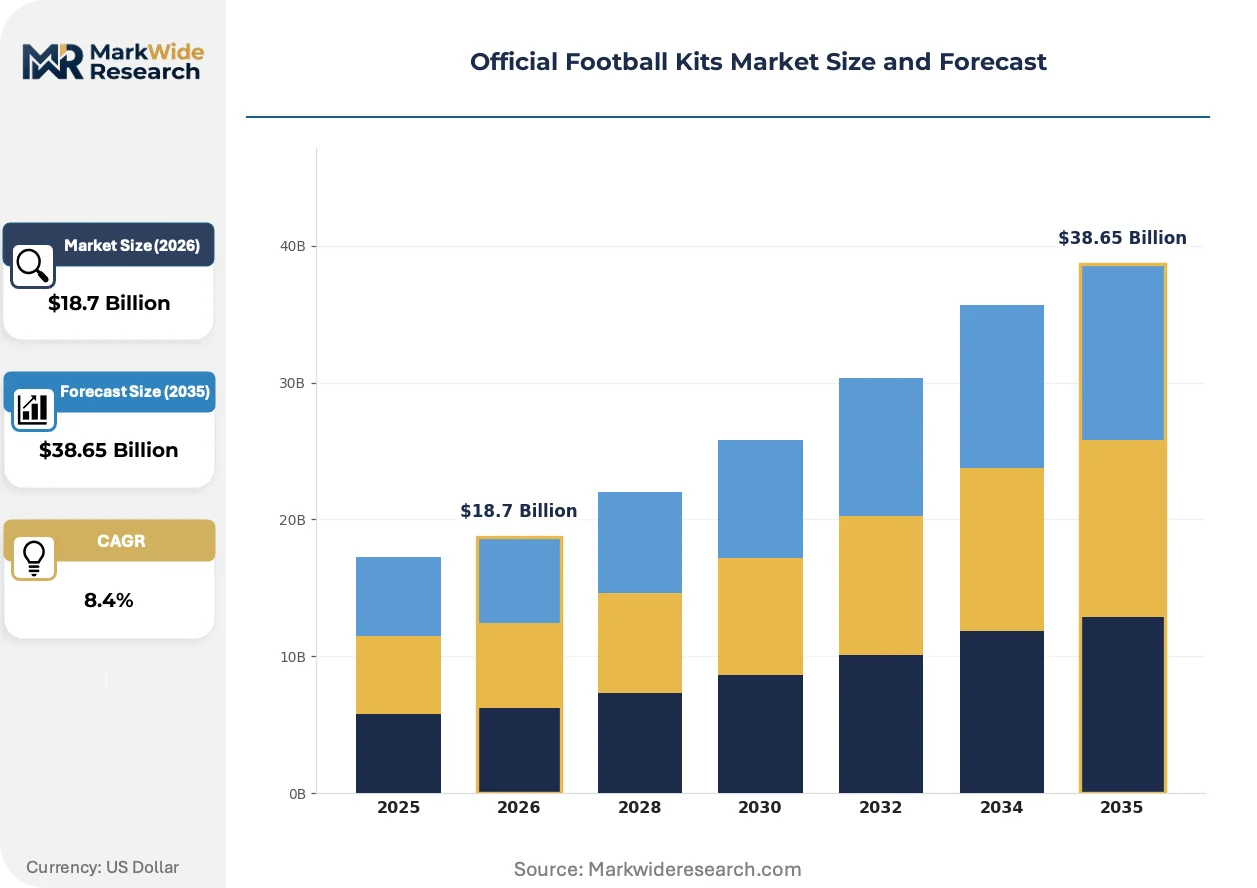
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Kits, Away Kits, Third Kits, Goalkeeper Kits Material: Polyester, Cotton, Nylon, Spandex Distribution Channel: Online Retail, Sporting Goods Stores, Team Shops, Specialty Stores Team Type: Professional Teams, Amateur Teams, National Teams, Youth Teams |
| Companies Covered | Nike, Adidas, Puma, Under Armour, New Balance, Umbro, Kappa, Macron, Hummel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Official Football Kits Market Trends and Innovations
Material science breakthroughs and regulatory compliance architectures are converging to redefine kit performance standards and supply chain accountability across manufacturing tiers.
Sublimation printing with dispersed dye inks is supplanting traditional screen-printed crest applications in premium kit segments. National team suppliers and top-tier club licensors are adopting this technology at accelerated procurement cycles. The shift is compressing lead times from 16-week production windows to 6-week drops, enabling mid-season design pivots for viral moment capture.
EU Green Deal textile sustainability requirements are mandating recycled content minimums and carbon footprint disclosure at the product level. Manufacturers serving European markets must now maintain blockchain-traceable fiber provenance and waterless dyeing certifications. Kit suppliers with Speedfactory-adjacent prototyping capabilities are absorbing compliance costs through automated cutting and on-demand production models.
Direct-to-consumer pre-order campaigns for limited third kits are displacing traditional wholesale club shop distribution. Collector segments in Japan, the United Kingdom, and the United States are driving sell-through velocity through authenticated resale platforms. This channel rotation is compressing inventory risk for licensors while fragmenting retail margin capture across secondary market intermediaries.
Official Football Kits Market Segmentation
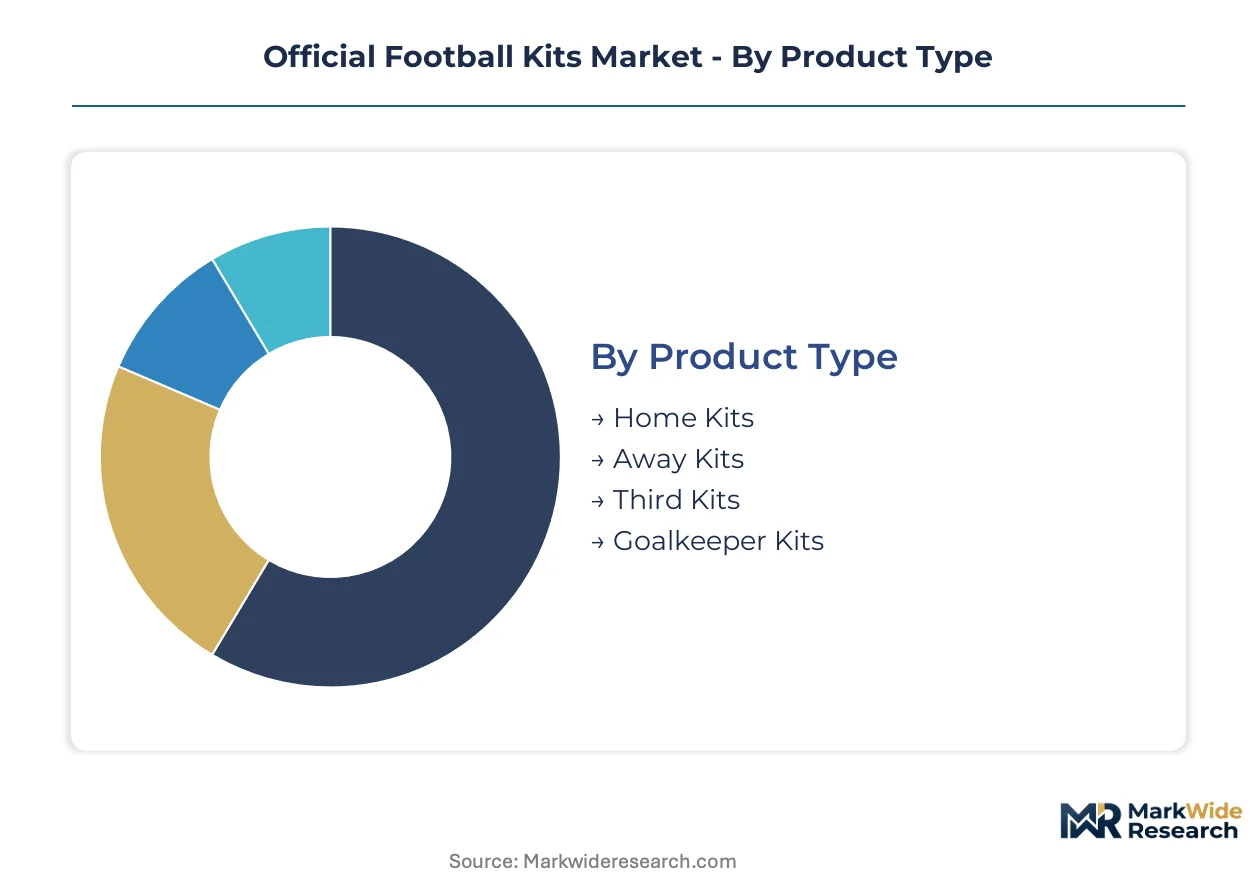
Segmentation in official football kits reveals distinct margin architectures and sourcing requirements across product tiers, material specifications, and channel configurations. Understanding these divisions exposes where compliance costs concentrate and where scarcity-driven pricing power emerges.
Product Type:
Home kits and away kits anchor domestic league supply contracts across Europe and Latin America, while third kits and goalkeeper kits disproportionately serve export-led collector markets in Japan and the United States.
- Home Kits:Traditional colorways with federation-mandated crest specifications dominate stadium retail and season-ticket holder fulfillment. Demand concentrates in Brazil's Série A and England's Premier League, where annual refresh cycles now compress to single-season drops.
- Away Kits:Contrasting designs for visibility regulations in broadcast environments carry higher design iteration costs. European clubs leverage these for mid-season viral marketing pivots through six-week sublimation production windows.
- Third Kits:Limited-edition scarcity models command premium positioning through authenticated resale platforms in collector segments.
- Goalkeeper Kits:Specialized padding requirements and lower squad substitution rates restrict addressable volume despite premium unit economics.
Home kits hold the largest share; momentum sits with third kits.
Material:
Cost tier stratification separates performance-grade synthetics from cotton blends, with recycled polyester commanding compliance-driven premiums under EU Green Deal frameworks.
- Polyester:Moisture-wicking knitted fabrics with elastane compression zones constitute the performance standard. REACH-certified recycled supply chains with blockchain traceability now dominate European procurement specifications.
- Cotton:Training-wear and lifestyle extensions absorb dyeing volatility through conventional screen-printing compatibility. Demand clusters in North American amateur leagues with less stringent performance requirements.
- Nylon:Reinforced abrasion resistance serves lower-division kit durability needs in semi-professional tiers.
- Spandex:Compression zone integration requires specialized knitting machinery concentrated in Italian manufacturing clusters.
Polyester commands volume leadership; recycled variants are climbing the fastest.
Distribution Channel:
Volume concentration tilts toward sporting goods chains for mass-market club licensing, while direct-to-consumer platforms capture margin in limited-release segments.
- Online Retail:Pre-order campaigns for third kits displace traditional wholesale through authenticated resale infrastructure. Collector velocity in Japan and the United Kingdom drives sell-through fragmentation across secondary market intermediaries.
- Sporting Goods Stores:Multi-brand assortments depend on inventory pooling across federation-specific sizing standards, complicating logistics for suppliers holding multiple national team contracts.
- Team Shops:Stadium-adjacent retail maintains match-day impulse purchase capture with higher staffing costs.
- Specialty Stores:Curated collector boutiques in urban centers serve authenticated vintage and limited-edition segments.
Online retail shows steepest expansion trajectory; sporting goods stores retain the largest share.
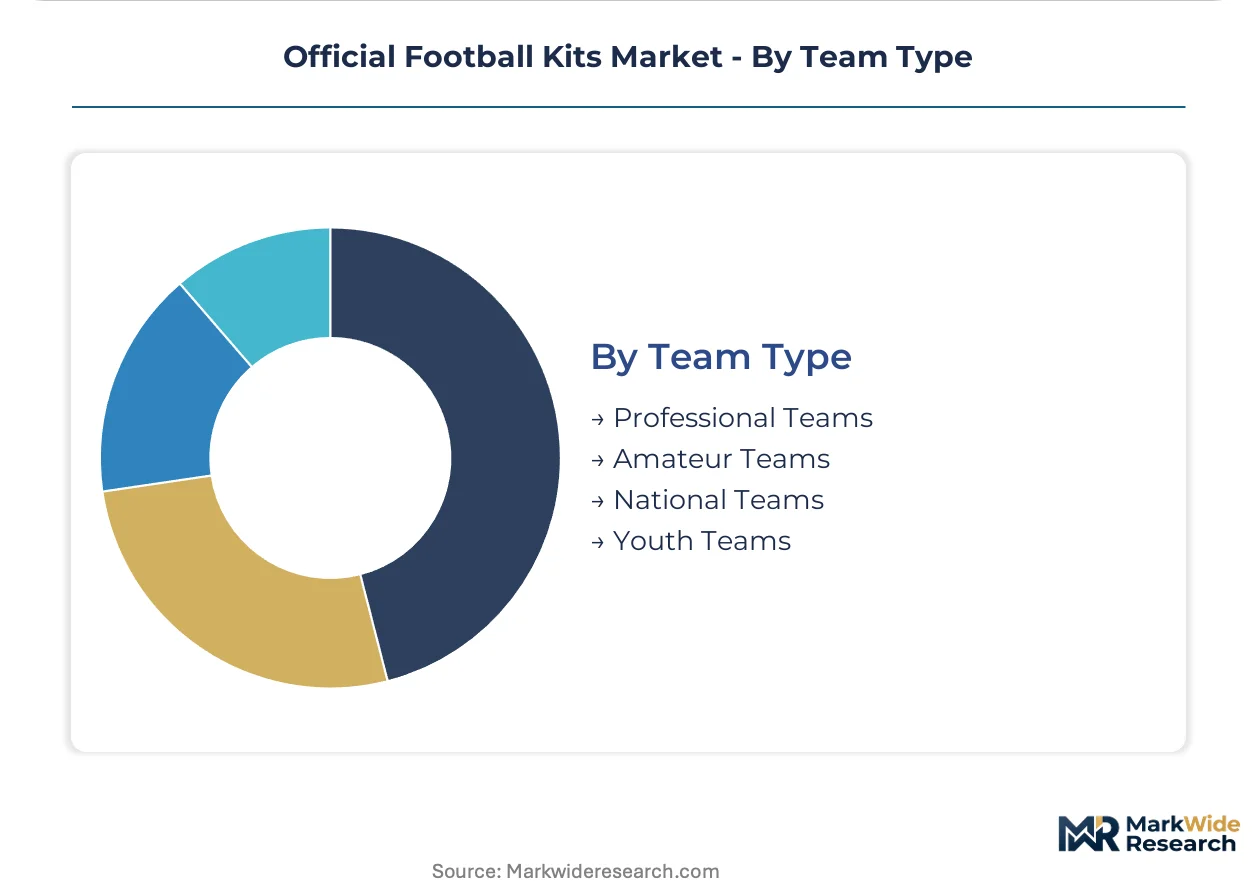
Team Type:
Customer type segmentation separates high-volume professional procurement from academy-led refresh cycles that are shortening replacement patterns.
- Professional Teams:Top-tier club and federation contracts specify sublimation color-matching tolerances and 18-24 week technician training pipelines. Supply concentrates with manufacturers maintaining Speedfactory-adjacent prototyping networks.
- National Teams:Tournament-cycle merchandising around Copa América and continental championships drives concentrated demand spikes in host geographies.
- Youth Teams:Academy kit refresh expansion from biennial to annual patterns creates volume growth in development program supply.
- Amateur Teams:Price-sensitive bulk procurement tolerates longer lead times and standardized sizing without federation-specific fit specifications.
Professional teams hold the largest share; youth teams are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium kit pricing power concentrates in Western Europe while volume manufacturing gravitates toward Brazil and Southeast Asia, creating a structural asymmetry that shapes supplier margin capture across the value chain.
Brazil
Domestic league licensing and Copa América merchandising cycles drive concentrated kit demand in Latin America's largest football economy. ANVISA, the national health surveillance agency, enforces textile chemical safety standards that parallel REACH restrictions. São Paulo-based manufacturing clusters absorb sublimation printing capacity for both local club contracts and export-bound collector segments.
Germany
Speedfactory-adjacent prototyping networks and premium national-team sponsorships anchor kit innovation infrastructure. ECHA administers REACH compliance documentation for azo-dye and perfluorinated chemical restrictions. Bavarian industrial clusters around Herzogenaurach concentrate R&D intensity for automated cutting and waterless dyeing certification.
United States
Collector-driven resale velocity in third kit segments and youth academy refresh expansion shorten procurement cycles. The FTC Green Guides enforce substantiation standards for environmental marketing claims on kit labeling. California and New York metro areas host authenticated resale platform infrastructure that fragments retail margin capture.
United Kingdom
Premier League annual refresh cycles and stadium-adjacent retail maintain match-day impulse purchase capture. The UK's post-Brexit regulatory alignment with EU textile sustainability requirements preserves REACH-equivalent compliance obligations. Greater Manchester and London logistics hubs coordinate inventory pooling across federation-specific sizing standards.
Japan
Enthusiast collector segments drive authenticated resale platform sell-through for limited-edition third kits. METI oversees national standards for textile labeling and recycled content verification. Osaka-based knitting machinery clusters supply specialized elastane compression zone integration for premium kit tiers.
Official Football Kits Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the official football kits market, with vertically integrated fiber innovators competing against outsourced apparel specialists for federation and club contracts. The vendor base consolidates around three strategic tiers: premium licensors with captive R&D infrastructure, mid-market challengers with aggressive emerging-market partnerships, and regional specialists with federation-specific fit expertise. Dominant competitive moves include backward integration into recycled polyester supply chains and strategic partnerships with African and Latin American federations.
Among vertically integrated sportswear conglomerates, Nike, Adidas, and Puma exemplify divergent competitive positioning archetypes. Nike occupies a position representing North American and Western European premium market dominance through fiber-to-consumer control. Adidas exemplifies European R&D intensity through prototyping network proximity to manufacturing clusters. Puma anchors the emerging-market challenger archetype with price-competitive positioning in African and Latin American club partnerships.
| Leading Market Players |
|---|
| Nike |
| Adidas |
| Puma |
| Under Armour |
| New Balance |
| Umbro |
| Kappa |
| Macron |
| Hummel |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal textile sustainability requirements gate both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb compliance premiums for recycled polyester certification and waterless dyeing infrastructure before accessing premium-tier contracts with European clubs and federations.
Pricing Analysis
Configured-to-order pricing for limited-edition third kits commands spreads of three-to-five multiples above standard home and away kit pricing, driven by scarcity positioning and authenticated resale platform velocity. Three-tier pricing structure across premium, standard, and economy levels separates federation-grade sublimation with blockchain traceability from amateur-league screen-printed alternatives. Price differentiation rests on certification grade and customization level, with REACH-compliant recycled supply chains capturing margin premiums. Cost compression in economy tiers is intensifying because ocean-bound plastic feedstock volatility in Southeast Asia squeezes input costs. Amateur clubs and youth academies exhibit highest price sensitivity, while collector segments in Japan and the United States show lowest elasticity.
Supply Chain Analysis
Brazil and Germany anchor kit manufacturing, with São Paulo-based clusters absorbing sublimation printing capacity for Latin American club contracts and Bavarian industrial zones around Herzogenaurach concentrating Speedfactory-adjacent prototyping networks. Raw material dependencies draw from certified recycled polyester feedstock, waterless dyeing machinery concentrated in Italian and German supplier bases, and elastane compression zone inputs from Osaka-based knitting equipment. Single-source vulnerability in waterless sublimation machinery creates bottleneck risk for scale-up capacity. Distribution runs through authenticated resale platforms for collector segments, sporting goods chains for mass-market volume, and direct-to-consumer pre-order campaigns for limited-release third kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Authenticated resale platform economics are inflecting toward interoperability with federation licensing systems, creating new margin capture mechanisms through verified provenance and secondary market royalty structures.
For Market Incumbents: Shield premium positioning by deepening backward integration into certified recycled polyester supply chains and securing exclusive waterless dyeing machinery allocations from German and Italian equipment suppliers. Counter emerging direct-to-consumer challengers by controlling federation-specific fit specification databases that complicate inventory pooling for new entrants. For New Entrants and Emerging Players: Lifecycle assessment and take-back program infrastructure services represent an under-served layer where incumbents lack dedicated compliance-as-a-service capabilities. Target African federation partnerships in Nigeria, Morocco, and Senegal as the most penetrable geography, using price-competitive positioning against premium licensors' cost structures. Go-to-market through EU Green Deal compliance consulting bundled with kit supply contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across waterless dyeing certification and blockchain-traceable fiber provenance systems, favoring scaled manufacturers over fragmented regional specialists. Long-term viability over a five-to-ten year window hinges on captive supply of recycled inputs and federation contract concentration. Acquisition target archetype: mid-tier suppliers with African or Latin American federation relationships and pending REACH compliance certification. Signal to watch: ANVISA alignment with EU chemical safety standards accelerating Brazil's regulatory convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Polyester Supply | Captures margin compression from ocean-bound plastic feedstock volatility in Southeast Asia. |
| Waterless Dyeing Certification Investment | Unlocks European federation contracts under ECHA-administered REACH compliance frameworks. |
| African Federation Partnership Expansion | Secures first-mover positioning in underpenetrated national team licensing in Nigeria and Senegal. |
| Authenticated Resale Platform Integration | Captures secondary market velocity from collector segments in Japan and the United Kingdom. |
| EU Green Deal Compliance Service Launch | Monetizes extended producer responsibility frameworks through lifecycle assessment infrastructure. |
Research Methodology
Cross-validation between federation procurement officers and sporting goods retail category managers anchors the qualitative findings, supplemented by technical directors at sublimation printing facilities and sustainability compliance leads at major licensors. Secondary sources include customs and trade data for polyester fiber imports, ECHA REACH compliance documentation, ANVISA textile safety filings, and federation licensing contract disclosures. Bottom-up triangulation across kit volume by club tier and top-down validation against aggregate apparel trade flows ensures methodological consistency.
Sensitivity analysis around recycled feedstock pricing volatility and regulatory compliance cost trajectories informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material specification, distribution channel configuration, and team tier classification. CAGRs derive from regression against historical kit refresh cycle compression and federation contract renewal patterns. Industry-specific forecast inputs incorporate Copa América tournament merchandising cycles and academy-led procurement expansion rates.
Forecasts assume regulatory continuity in EU Green Deal textile sustainability mandates and REACH chemical restrictions; material policy shifts in ECHA enforcement intensity or ANVISA alignment would require re-modeling. Specific risks that could revise projections include perfluorinated chemical substitution failures degrading match-day performance, sublimation technician training pipeline bottlenecks, and legacy sizing standard fragmentation complicating inventory pooling. Recalibration cycles align with material shifts in federation contract award timing and major tournament merchandising windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Heated Jacket Market
Apparel & Footwear
Surfing Apparel and Accessory Market
Apparel & Footwear
Ethnic Wear Market
Apparel & Footwear
Smart Heating Scarf Market
Apparel & Footwear
Denim Jeans Market
Apparel & Footwear
Outdoor Jacket Market
Apparel & Footwear
Golf Outfit Market
Apparel & Footwear
School Shoes Market
Apparel & Footwear
Football Jerseys Market
Apparel & Footwear
Swimwear and Beachwear Market
Apparel & Footwear
Golf Apparel Market
Apparel & Footwear
Thermal Underwear Market
Apparel & Footwear
Global Pickleball Clothing and Apparel Market
Apparel & Footwear
Gym Apparel Market
Apparel & Footwear
Rugby Apparel Market
Apparel & Footwear
France Denim Jeans Market