
 Loungewear Market | 2026-2036
Loungewear Market Size, Share, and Industry Trends Forecast 2026-2036
Loungewear Market Outlook
Direct-to-consumer digital storefronts is reconfiguring how loungewear brands build repeat purchase loops and capture first-party data. Victoria's Secret & Co leverages its established intimates infrastructure to cross-sell coordinated loungewear collections through owned e-commerce channels. Hanesbrands Inc anchors mass-market volume through deep wholesale relationships with big-box retailers while sustaining manufacturing scale across multiple continents. Ralph Lauren Corporation competes at the premium tier by extending its heritage casualwear positioning into elevated home-residence apparel.
Loungewear encompasses relaxed-fit garments engineered for domestic and casual environments, typically constructed from knit fabrics with stretch recovery between 15% and 30% and garment weights ranging from 180 to 320 gsm for year-round versatility; its commercial purpose centers on bridging sleepwear functionality with presentable social acceptability for remote work and informal outings. Modal and bamboo fiber blends now command margin premiums in the material dimension as consumers prioritize moisture-wicking and biodegradability credentials over basic cotton-polyester compositions. The women's segment dominates current revenue pools, though unisex sizing is accelerating fastest as gender-neutral design language reshapes product development cycles across leading labels.
The U.S. Federal Trade Commission's Textile Fiber Products Identification Act mandates accurate fiber-content labeling that shapes how brands communicate sustainability claims to American consumers, while the EU Green Deal's forthcoming textile waste directives will force reformulation of synthetic-heavy supply chains serving European buyers. OEKO-TEX Standard 100 certification has become a baseline market-access requirement for mid-tier and premium distribution channels across both regions. Stakeholders must decide whether to absorb the capital costs of vertically integrated recycling infrastructure or outsource compliance through certified third-party material suppliers.
Market Dynamics
Hybrid work permanence is compressing the traditional boundaries between sleepwear, casualwear, and office-appropriate attire, forcing brands to engineer garments that satisfy multiple use-cases within single SKUs.
Growth Catalysts
- EU Green Deal textile directives:Mandates for circular design and recycled content thresholds are accelerating certified material adoption across European supply chains, creating compliance-driven demand for sustainable fiber innovations.
- Modal and bamboo fiber blends:These cellulose-based materials deliver superior moisture management and biodegradability credentials that command price premiums from environmentally conscious buyer segments.
- Remote-work professionals:This demographic cohort has normalized all-day comfort apparel as professional dress codes, expanding addressable market scope beyond traditional sleepwear categories.
Market Restraints
- Organic cotton input cost volatility:Certified organic fiber carries 20-40% price premiums over conventional cotton, compressing margin structures for mid-tier brands without premium pricing power.
- Synthetic-heavy supply chain concentration:Polyester and nylon dependency in existing manufacturing infrastructure creates stranded asset risk as biodegradability mandates tighten across major economies.
- FTC fiber-content labeling enforcement:The U.S. Federal Trade Commission's strict accuracy requirements for sustainability claims create litigation exposure for brands with overstated environmental credentials.
Strategic Opportunities
- Unisex sizing acceleration:Gender-neutral design language is reshaping product development cycles and opening incremental revenue pools beyond historically women-dominated category conventions.
- Direct-to-consumer digital storefronts:Owned e-commerce channels enable first-party data capture and repeat purchase loop engineering that wholesale-dependent competitors cannot replicate.
- OEKO-TEX Standard 100 certification:This baseline market-access requirement for premium distribution channels creates differentiation leverage for early certifiers against uncertified mass-market rivals.
Industry Challenges
- Recycling infrastructure capex requirements:Vertically integrated recycling capabilities demand substantial capital deployment that mid-cap brands must weigh against outsourced certified material procurement.
- Stretch recovery engineering talent scarcity:Technical expertise in knit fabric construction with 15-30% stretch recovery specifications concentrates among legacy apparel engineering hubs, constraining rapid product iteration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loungewear Market |
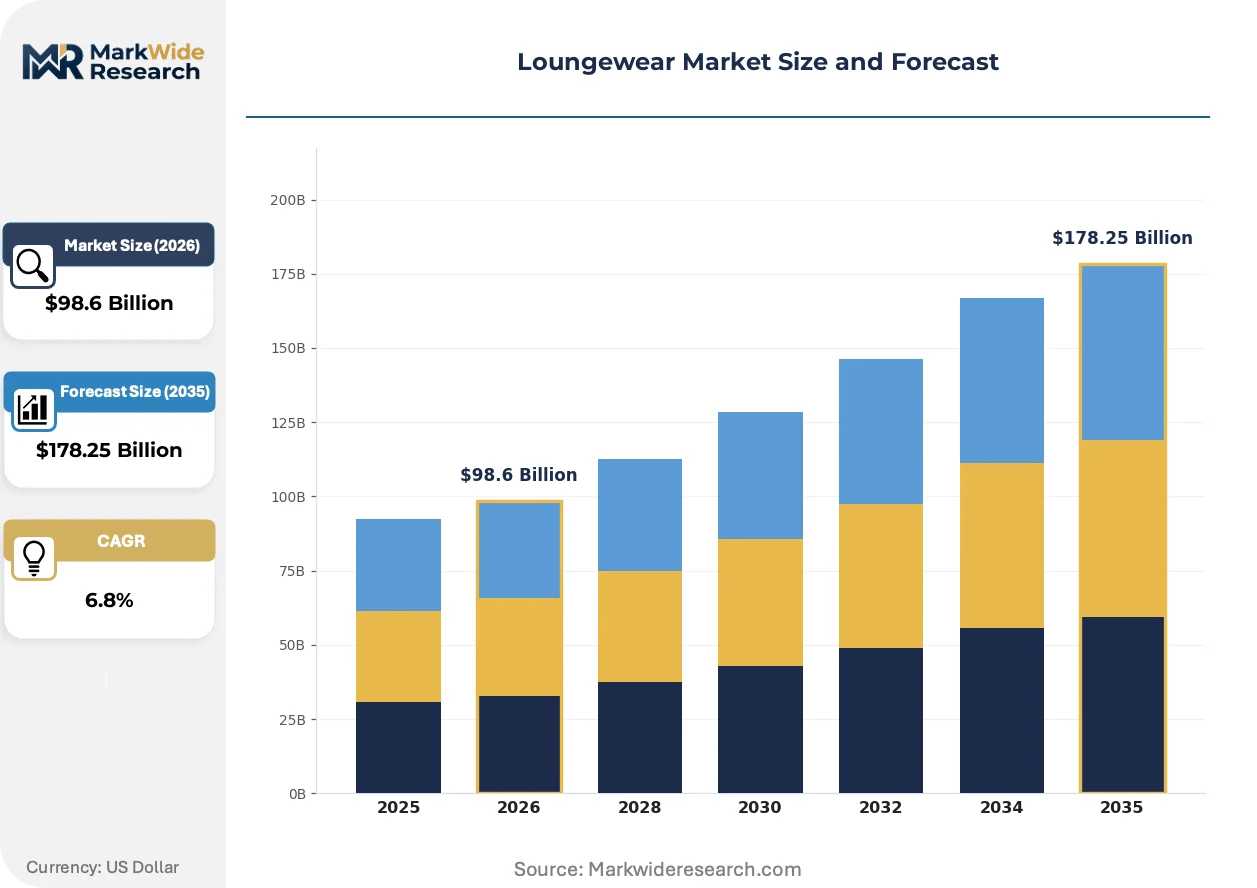
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pants, Shorts, Tops, Sets Material: Cotton, Polyester, Bamboo, Modal Target Audience: Men, Women, Kids, Unisex Distribution Channel: Online, Retail, Wholesale, Direct |
| Companies Covered | Victoria's Secret & Co, Hanesbrands Inc, H&M Group, PVH Corp, Ralph Lauren Corporation, Authentic Brands Group LLC, Jockey International Inc, American Eagle Outfitters Inc, Urban Outfitters Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loungewear Market Strategic Shifts
Digital integration across design, manufacturing, and retail channels is collapsing traditional seasonality and enabling on-demand production models that reduce inventory risk.
3D knitting technology is digitizing garment construction by enabling seamless body-mapping and zero-waste pattern engineering. Premium loungewear labels are adopting these systems to compress sampling cycles from weeks to days. This capability is digitizing how brands prototype fit and scale limited drops without minimum order quantity constraints.
The EU Green Deal's forthcoming textile waste directives are forcing reformulation of synthetic-heavy supply chains serving European buyers. Manufacturers must redesign products for recyclability or face extended producer responsibility fees. Apparel brands with significant EU revenue exposure are accelerating certified organic cotton and recycled polyester sourcing to preempt compliance deadlines.
Buyers are consolidating wardrobe purchases around versatile, multi-scenario garments that bridge home, work, and social contexts. This pattern is displacing occasion-specific sleepwear and formal casualwear as separate categories. The United States exhibits the most pronounced concentration of this behavior, where hybrid work policies have normalized all-day comfort apparel as professional dress.
Loungewear Market Segmentation
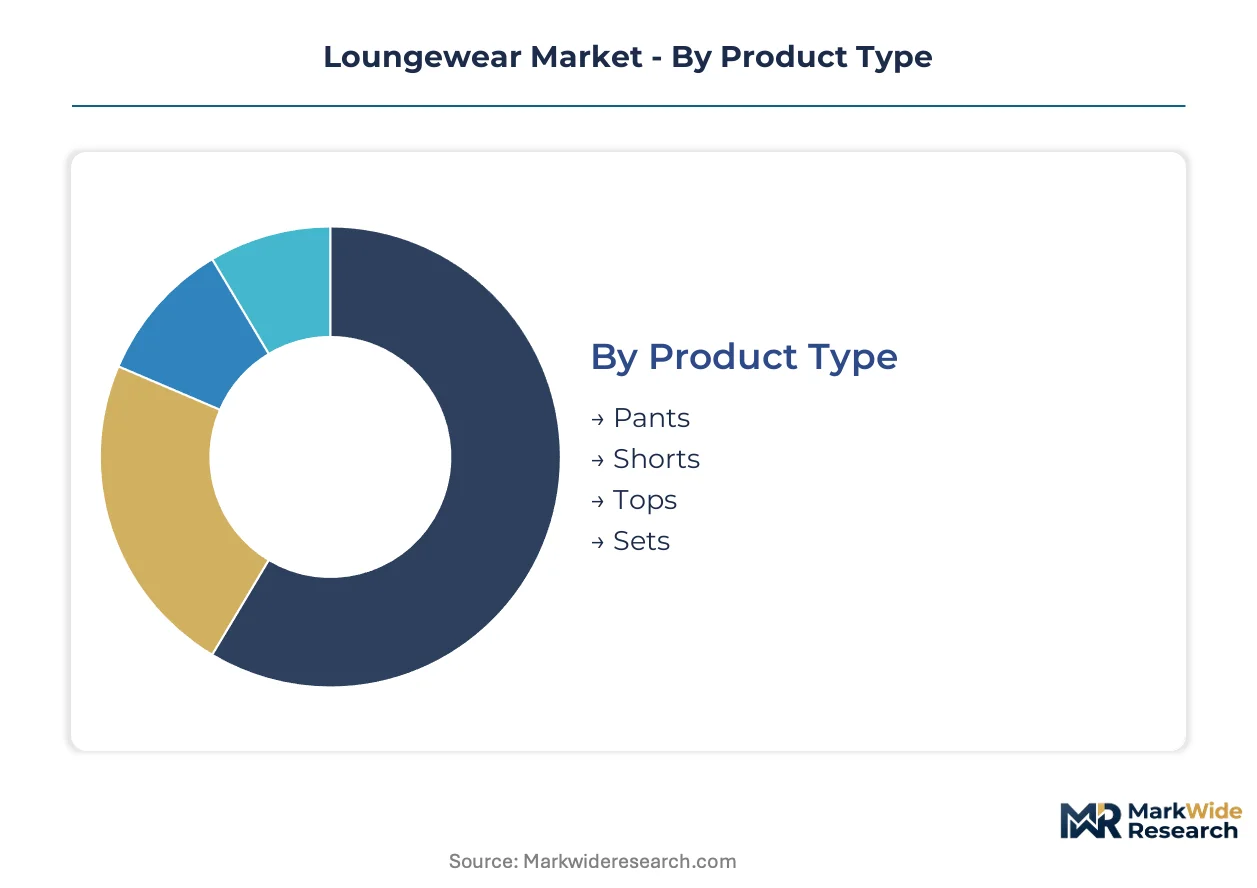
Loungewear segmentation reveals how hybrid work permanence and sustainability mandates are fragmenting demand across technical specifications and channel preferences. Material composition and sizing architecture now determine margin capture more decisively than traditional style differentiation.
Product Type:
Mature categories anchor volume while emerging formats reshape development cycles around multi-scenario functionality.
- Sets:Coordinated top-bottom combinations engineered with matching stretch recovery specifications between 15% and 30% dominate remote-work professional wardrobes. United States demand concentrates here as hybrid policies normalize all-day coordinated comfort as acceptable professional dress.
- Tops:Knit fabric constructions ranging from 180 to 320 gsm bridge sleepwear functionality with video-call presentability. Modal and bamboo fiber blends command margin premiums in this segment as moisture-wicking credentials outweigh basic cotton-polyester compositions.
- Pants:Relaxed-fit bottoms with elasticized waistbands and tapered ankles serve domestic and casual environments.
- Shorts:Seasonal variants targeting warmer climates and sleep-to-lounge transitions.
Sets retain volume leadership; Tops hold the steepest expansion curve as consumers prioritize mix-and-match versatility over fixed combinations.
Material:
Cost tier stratification separates certified sustainable inputs from commodity synthetics facing regulatory pressure.
- Modal:Cellulose-based fiber derived from beech trees delivers superior moisture management and biodegradability credentials. EU Green Deal textile directives are accelerating certified material adoption across European supply chains, creating compliance-driven demand for this input.
- Cotton:Conventional and certified organic grades remain the baseline for mass-market accessibility. Certified organic cotton carries 20-40% price premiums over conventional fiber, compressing margin structures for mid-tier brands without premium pricing power.
- Bamboo:Rapidly renewable grass-based cellulose fiber with natural antimicrobial properties.
- Polyester:Synthetic staple facing stranded asset risk as biodegradability mandates tighten across major economies.
Modal captures the fastest price-premium expansion; Cotton maintains absolute volume dominance across all distribution tiers.
Target Audience:
Customer type evolution shows gender-neutral design language displacing historically women-dominated category conventions.
- Unisex:Gender-neutral sizing architectures with extended measurement ranges reshape product development cycles. This segment is accelerating fastest as remote-work professionals normalize all-day comfort apparel regardless of traditional gendered merchandising.
- Women:Historically dominant revenue pool with established size grading and styling conventions. United States demand concentrates most visibly here where hybrid work policies have expanded at-home wardrobe purchases.
- Men:Growing acceptance of dedicated loungewear beyond traditional sleepwear or athletic wear.
- Kids:Size-scaled variants prioritizing durability and ease of care for high-turnover children's wardrobes.
Women retain volume leadership; Unisex holds the steepest expansion curve as gender-neutral design language reshapes product development.
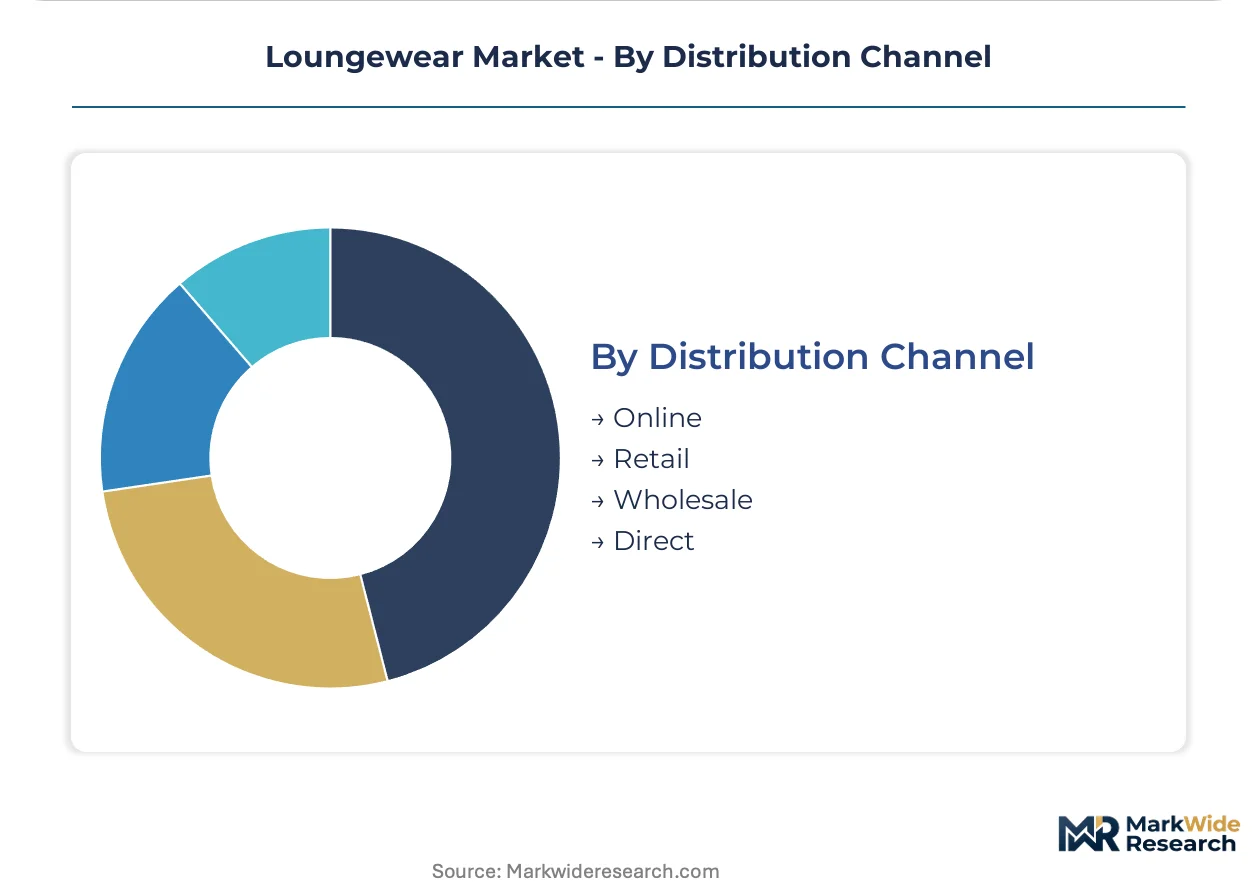
Distribution Channel:
Channel margin structures separate first-party data capture from wholesale-dependent volume plays.
- Online:Direct-to-consumer digital storefronts enable repeat purchase loop engineering and first-party data capture that wholesale competitors cannot replicate. Remote-work professionals increasingly default to this channel for replenishment and discovery.
- Direct:Owned retail and brand-operated channels with highest margin capture potential. OEKO-TEX Standard 100 certification creates differentiation leverage here against uncertified mass-market rivals.
- Retail:Third-party brick-and-mortar placement with immediate try-on and tactile evaluation.
- Wholesale:Big-box and department store relationships anchoring mass-market volume through deep inventory commitments.
Online retains volume leadership; Direct holds the steepest expansion curve as brands prioritize margin capture over scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in the United States where hybrid work policies normalize all-day comfort apparel, while European markets trade margin for compliance-driven certified material adoption under EU Green Deal directives.
United States
Remote-work professionals in the United States anchor global demand for coordinated loungewear sets engineered with 15-30% stretch recovery specifications. The FTC's Textile Fiber Products Identification Act mandates strict fiber-content accuracy for sustainability claims, reshaping how brands communicate environmental credentials. Los Angeles and New York City host the densest concentrations of direct-to-consumer digital storefronts capturing first-party data from repeat purchase loops.
Germany
German consumers prioritize OEKO-TEX Standard 100 certification as a baseline market-access requirement, driving compliance investment across mid-tier and premium distribution channels. The EU Green Deal's textile waste directives force reformulation of synthetic-heavy supply chains serving European buyers. Munich and Hamburg anchor the country's premium loungewear retail infrastructure with elevated brand positioning.
China
Domestic demand for modal and bamboo fiber blends accelerates as moisture-wicking and biodegradability credentials command price premiums from environmentally conscious buyer segments. The country's dual carbon goals pressure manufacturers toward recycled polyester sourcing and circular design principles. Guangdong Province hosts the largest concentration of knit fabric engineering capacity with stretch recovery technical expertise.
United Kingdom
British hybrid work policies expand at-home wardrobe purchases beyond traditional sleepwear categories into presentable social acceptability for remote work. The UK's post-Brexit regulatory alignment with EU textile sustainability requirements maintains certified organic cotton and recycled material standards. London concentrates direct-to-consumer brand headquarters leveraging owned e-commerce channels for margin capture.
India
Domestic loungewear consumption grows as remote-work professionals normalize all-day comfort apparel across metropolitan professional classes. The Bureau of Indian Standards enforces textile labeling requirements that shape how domestic and imported brands communicate fiber content to consumers. Maharashtra and Gujarat host expanding manufacturing clusters for cotton-based loungewear targeting mass-market accessibility.
Loungewear Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with certified material supply. The vendor base separates between mass-market volume players anchored in wholesale big-box relationships and premium-tier labels capturing margin through direct-to-consumer digital storefronts. Three strategic archetypes dominate: heritage casualwear extenders, intimates infrastructure cross-sellers, and sustainability-certified direct brands. Competitive moves concentrate on OEKO-TEX certification acquisition and unisex sizing architecture expansion.
Within the heritage casualwear extender tier, Ralph Lauren Corporation occupies a position bridging elevated home-residence apparel with established brand equity. Among intimates infrastructure players, Victoria's Secret & Co exemplifies cross-selling coordination through owned e-commerce channels leveraging existing customer data assets. At the mass-market scale end, Hanesbrands Inc anchors volume through deep wholesale relationships while sustaining manufacturing scale across multiple continents.
| Leading Market Players |
|---|
| Victoria's Secret & Co |
| Hanesbrands Inc |
| H&M Group |
| PVH Corp |
| Ralph Lauren Corporation |
| Authentic Brands Group LLC |
| Jockey International Inc |
| American Eagle Outfitters Inc |
| Urban Outfitters Inc |
| Others |
Value Chain & Pricing Dynamics
Guangdong Province's knit fabric engineering clusters anchor global stretch recovery expertise, concentrating technical talent for 15-30% elasticity specifications and feeding margin pools downstream to brands with OEKO-TEX certification leverage.
Pricing Analysis
Configured-to-order pricing for custom modal blends commands 25-35% premiums over standard cotton-polyester SKUs. Three-tier pricing structure across premium, standard, and economy levels separates certified organic lines from mass-market synthetics facing EU Green Deal compliance costs. Pricing pressure stems from organic cotton's 20-40% input premiums, compressing mid-tier margins. Remote-work professionals show lowest price sensitivity for moisture-wicking credentials, while mass-market wholesale buyers resist pass-through of fiber cost volatility.
Supply Chain Analysis
Upstream feedstock for cellulose-based fibers draws from beech tree plantations in Austria and China, with bamboo pulp sourcing concentrated in Sichuan and Zhejiang provinces. Raw material dependencies span certified organic cotton from India, recycled polyester from Taiwan, and modal pulp from Lenzing's integrated Austrian operations. Single-source vulnerability concentrates in stretch recovery engineering talent pools. Distribution runs through direct-to-consumer digital storefronts for premium tiers and big-box wholesale for mass-market volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward remote-work professionals consolidating wardrobe purchases around multi-scenario garments, fragmenting demand across unisex sizing architectures and compressing margins for undifferentiated wholesale-dependent players.
For Market Incumbents: Insulate margin position by accelerating OEKO-TEX Standard 100 certification across core SKUs before EU Green Deal textile waste directives tighten. Prioritize backward integration into certified organic cotton sourcing to offset input cost volatility threatening mid-tier profitability. Channel control through owned e-commerce infrastructure defends against wholesale buyer consolidation.
For New Entrants and Emerging Players: Pursue white-space opportunity in unisex sizing architectures where gender-neutral design language is displacing historically women-dominated category conventions. Target the premium direct-to-consumer channel with modal and bamboo fiber blends commanding moisture-wicking premiums. Launch through digital-native storytelling around biodegradability credentials to bypass wholesale gatekeepers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer brands that have scaled first-party data capture but lack manufacturing scale. Long-term viability favors acquirers who can bridge digital customer relationships with certified material supply chain control. Watch for EU Green Deal compliance deadline acceleration as inflection signal for stranded synthetic-heavy assets.
| Strategic Initiative | Industry Significance |
|---|---|
| OEKO-TEX Standard 100 Certification | Baseline market-access requirement for premium distribution channels across EU and US markets. |
| Direct-to-Consumer Channel Expansion | Owned e-commerce enables first-party data capture that wholesale competitors cannot replicate. |
| Modal and Bamboo Fiber Sourcing | Cellulose-based materials command price premiums from environmentally conscious buyer segments. |
| Unisex Sizing Architecture Development | Gender-neutral design language opens incremental revenue pools beyond women-dominated conventions. |
| Backward Integration into Organic Cotton | Certified fiber sourcing defends margins against 20-40% input cost premiums over conventional cotton. |
Study Parameters
Initial hypotheses were tested against primary input from brand merchandising directors, knit fabric engineers, and retail category buyers and refined through secondary validation. Primary interviews engaged supply chain planners at vertically integrated manufacturers, sustainability compliance officers at mid-tier labels, and procurement managers at big-box retailers. Secondary sources included customs trade data for fiber imports, OEKO-TEX certification registries, and SEC filings from publicly traded apparel companies. Bottom-up SKU-level demand modeling was triangulated against top-down category spend estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material composition, target audience, and distribution channel, with stretch recovery specifications and gsm weight classes as industry-specific technical tiers. CAGRs were derived from regression analysis against remote-work penetration rates and certified fiber adoption curves. Forecast inputs incorporated EU Green Deal implementation timelines and FTC labeling enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices or cotton futures volatility would shift the trajectory. Forecasts reflect assumptions around hybrid work permanence and regulatory compliance deadlines. Cross-checking against Bureau of Labor Statistics remote-work adoption data and fiber price indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Men Shirts Market
Apparel & Footwear
Outdoor Apparel and Accessories Market
Apparel & Footwear
Asia Pacific Hats Market
Apparel & Footwear
Luxury Vegan Men's Fashion Market
Apparel & Footwear
Maternity Intimate Wear Market
Apparel & Footwear
Sports Bras Market
Apparel & Footwear
Apparel Re-Commerce Market
Apparel & Footwear
Ballet Pointe Shoes Market
Apparel & Footwear
Golf Outfit Market
Apparel & Footwear
Apparel and Leather Products Market
Apparel & Footwear
Fitness Apparel Market
Apparel & Footwear
Rugby Apparel Market
Apparel & Footwear
Outdoor Apparel Market
Apparel & Footwear
Global Women Pajamas Suits Market
Apparel & Footwear
Athletic and Sports Socks Market
Apparel & Footwear
Online Apparel Market