
 Air Cushion Machine Market | 2026-2036
Air Cushion Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Air Cushion Machine Market Outlook
Consolidation among third-party logistics providers is repositioning procurement power toward volume buyers who negotiate machine-plus-film bundles. Sealed Air leverages its film chemistry expertise to sustain captive demand for proprietary consumables. Ranpak competes through paper-based void-fill alternatives that challenge conventional air cushion positioning. Storopack anchors European manufacturing scale with localized production cells near automotive clusters.
An air cushion machine produces inflated protective packaging on demand from rollstock film, typically operating at speeds of 10-25 meters per minute with heat-sealing or cold-sealing mechanisms to form chambers that absorb shock during transit. The equipment eliminates pre-inflated inventory, cutting warehouse cube requirements by generating cushions only when orders process. Inflatable bags dominate unit volume across logistics and e-commerce verticals where dimensional consistency matters, while void fillers capture faster growth in hybrid deployment configurations that blend on-premises hardware with cloud-based job scheduling. Small and medium machine sizes concentrate margin pools as mid-market warehouses replace manual packing stations with semi-automated cushioning cells.
The US EPA guides sustainable packaging mandates through recycled content benchmarks that push manufacturers toward mono-material films. The EU F-Gas Regulation and REACH compliance frameworks constrain film additive chemistries, filtering market access for imported equipment. FDA oversight touches pharmaceutical shippers who validate cushion machines for cleanroom-compatible operations. Stakeholders must monitor how California's extended producer responsibility legislation and Germany's VerpackG amendment reshape total cost of ownership calculations for cross-border fleet deployments.
Market Dynamics
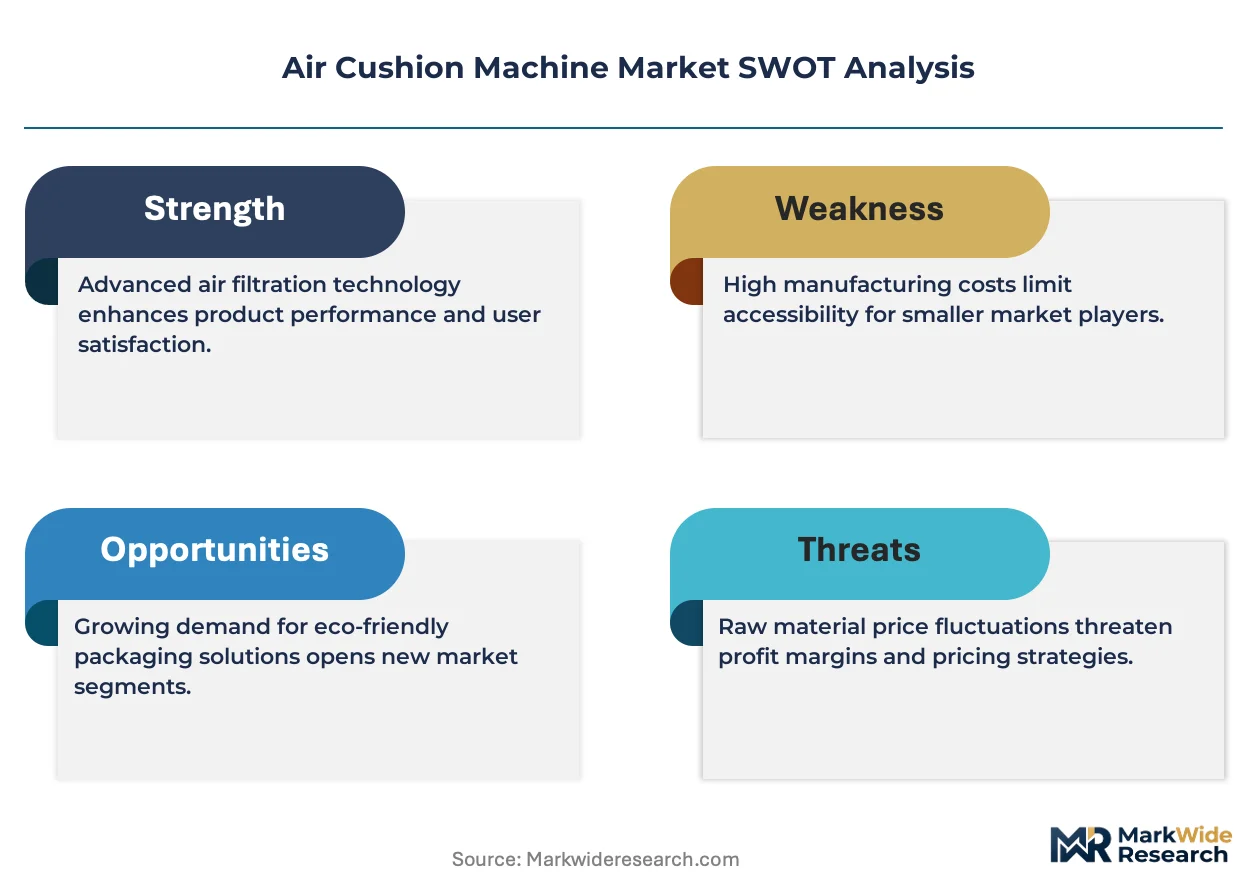
Third-party logistics consolidation concentrates procurement power among volume buyers who negotiate bundled machine-plus-film contracts, squeezing standalone equipment margins while favoring integrated solution providers with captive consumable streams.
Growth Catalysts
- E-commerce fulfillment automation:Warehouse operators deploy on-demand cushioning cells to eliminate pre-inflated inventory and recover floor space. Germany leads industrial packaging automation investment ahead of regional peers.
- EU Packaging and Packaging Waste Regulation:Tightened material recovery targets force shippers toward mono-material films compatible with mechanical recycling streams. Compliance investments drive equipment refresh cycles.
- Cold-sealing technology diffusion:Heat-free sealing mechanisms reduce energy draw and expand film substrate compatibility. Food and pharmaceutical shippers adopt these systems for temperature-sensitive product protection.
Market Restraints
- Film chemistry concentration:Proprietary resin formulations lock buyers into single-source consumable supply, inflating lifetime ownership costs beyond equipment depreciation.
- REACH additive constraints:ECHA restrictions on plasticizers and stabilizers limit imported film compatibility, fragmenting equipment-film matching across European borders.
- Paper void-fill substitution:Ranpak and competitors advance kraft-based alternatives that bypass plastic film dependencies entirely, threatening air cushion volume in premium unboxing segments.
Strategic Opportunities
- Cloud-connected job scheduling:Hybrid deployment configurations blend on-premises hardware with SaaS-based order orchestration. Mid-market warehouses upgrade from manual stations to semi-automated cells.
- Automotive cluster proximity:Localized production cells near Stuttgart, Wolfsburg, and Munich assembly plants reduce film logistics costs and enable just-in-sequence cushioning delivery.
- FDA cleanroom validation:Pharmaceutical shippers seek cushion machines certified for ISO 14644-compliant operations. Equipment vendors capture premium positioning through contamination-control documentation.
Industry Challenges
- Retrofit integration complexity:Legacy warehouse management systems require custom API development to sync cushion generation with order-picking workflows. Implementation timelines stretch 8-14 months.
- Multi-material film certification lag:Laboratory validation of recycled-content films for seal integrity runs 6-9 months, delaying product launches behind regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Cushion Machine Market |
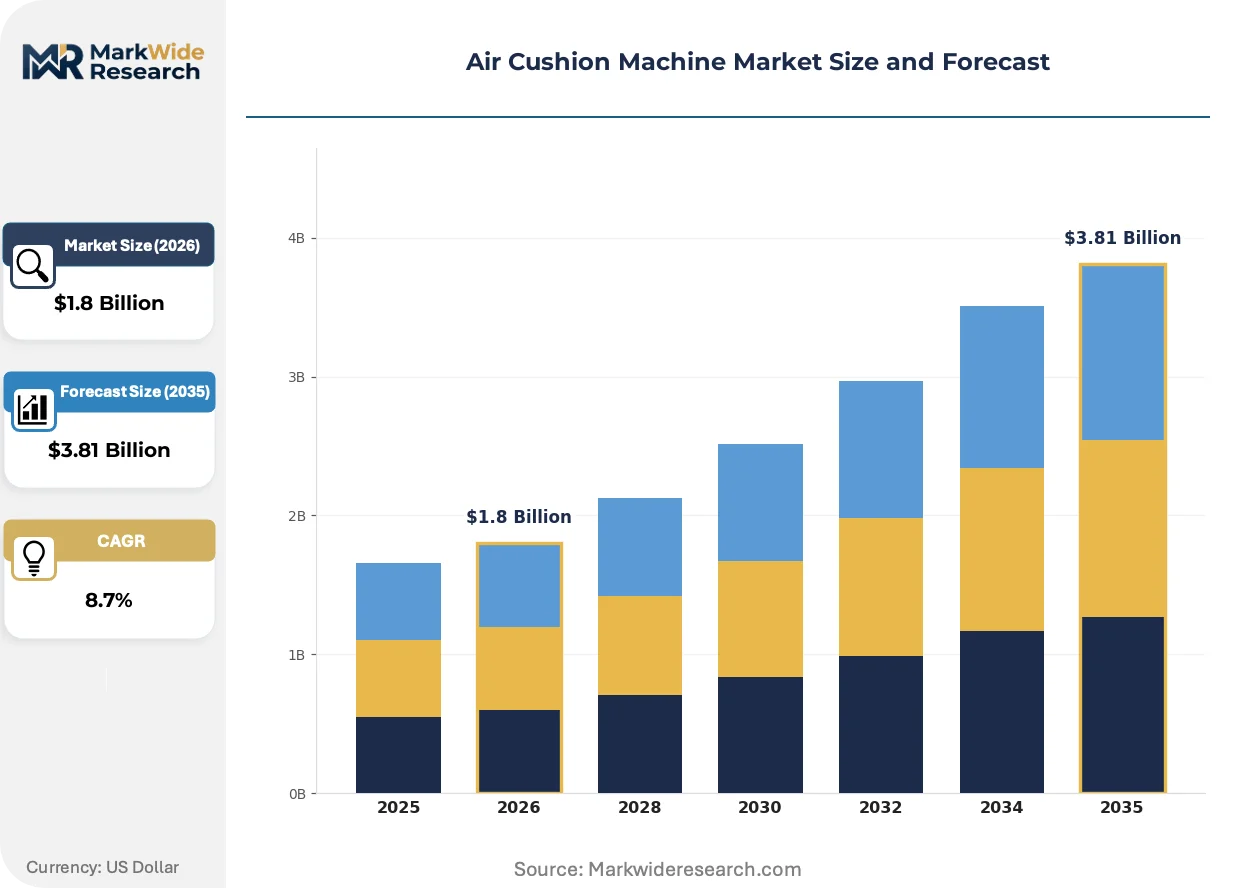
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable Bags, Air Pouches, Bubble Wrap, Void Fillers Industry Vertical: Logistics, E-Commerce, Manufacturing, Packaging Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Size: Small, Medium, Large, Custom |
| Companies Covered | Sealed Air, Pregis, Storopack, Ranpak, Smurfit Kappa Group, FP International, Automated Packaging Systems, Airspeed, Inflatable Packaging Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Cushion Machine Market Strategic Shifts
Equipment architecture is fragmenting into configurable subsystems that let operators swap sealing modules, film path components, and control interfaces without full machine replacement. This modularity compresses upgrade cycles and extends asset lifespans.
Modular machine design is modularizing the traditional monolithic equipment category. Mid-market 3PLs and regional e-commerce operators adopt component-swappable systems to phase capital deployment across budget cycles. The technology is modularizing vendor revenue models from unit sales toward recurring upgrade and module subscription streams.
REACH and the EU F-Gas Regulation jointly constrain film additive portfolios, forcing reformulation of seal-layer chemistries. Equipment manufacturers must recalibrate heat-sealing parameters for each compliant film variant. German automotive shippers face the tightest compliance windows as VerpackG amendments phase in extended producer responsibility fees.
Buyer consolidation among mega-3PLs concentrates specification authority into procurement teams who unbundle hardware from consumable supply. Volume buyers demand open-architecture machines accepting third-party film. This pattern concentrates in the Netherlands and Belgium, where DHL and Kuehne+Nagel operate superhub fulfillment networks.
Air Cushion Machine Market Segmentation
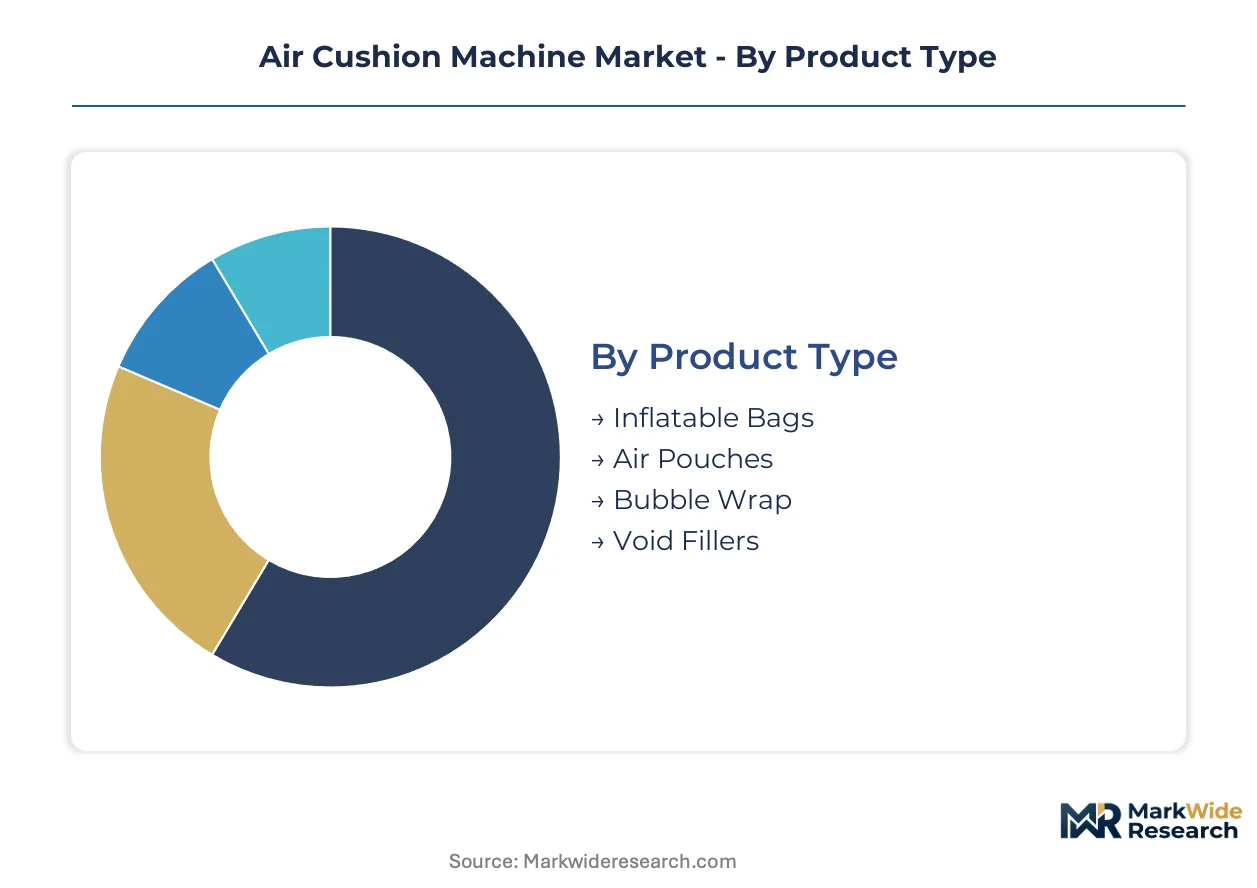
Segmentation in the air cushion machine market reveals how equipment specifications align with operational scale and film chemistry requirements. Procurement patterns diver sharply between high-volume automated lines and semi-automated cells serving mid-market warehouses.
Product Type:
Supply concentration in film resin formulations shapes competitive positioning across cushion formats, with proprietary seal-layer chemistries locking buyers into specific equipment-consumable pairings.
- Inflatable Bags:Heat-sealed chambers formed from LDPE or HDPE rollstock deliver consistent dimensional protection for electronics and automotive components. German automotive clusters near Stuttgart and Wolfsburg deploy these systems for just-in-sequence parts delivery, though REACH additive constraints force ongoing film reformulation cycles.
- Void Fillers:On-demand generation of loose-fill air cushions eliminates pre-inflated inventory while adapting to irregular package geometries. E-commerce fulfillment centers in the Netherlands and Belgium favor these systems for mixed-SKU operations where dimensional variability exceeds 40%.
- Air Pouches:Pre-sized cushion formats suit pharmaceutical shippers requiring FDA-validated cleanroom compatibility.
- Bubble Wrap:Legacy format retains presence in manual packing stations despite automation migration.
Inflatable bags absorb the bulk of installed capacity; void fillers are expanding most quickly.
Industry Vertical:
Cost tier differentiation separates capital-intensive automated deployments from semi-automated cells where payback periods stretch across multiple budget cycles.
- E-Commerce:Order volatility drives adoption of cloud-connected cushion cells that scale output with demand spikes. DHL and Kuehne+Nagel superhubs in Belgium negotiate machine-plus-film bundles that squeeze standalone equipment margins.
- Logistics:Third-party consolidation concentrates procurement authority among volume buyers who specify open-architecture machines accepting third-party film. Cold-sealing technology diffusion accelerates in temperature-sensitive freight corridors.
- Manufacturing:Automotive OEMs near Munich require localized production cells with sub-24-hour film replenishment.
- Packaging:Contract packers face EU Packaging and Packaging Waste Regulation compliance deadlines driving equipment refresh.
E-commerce commands the largest equipment installed base; logistics is climbing the fastest as 3PL consolidation accelerates.
Deployment:
Volume concentration in hybrid configurations reflects mid-market warehouses phasing capital deployment across budget cycles while preserving upgrade pathways.
- Hybrid:On-premises hardware integrated with SaaS-based job scheduling enables dynamic cushion generation synchronized with order-picking workflows. Retrofit integration complexity stretches implementation timelines 8-14 months for legacy warehouse management systems.
- On-Premises:Standalone machines without cloud connectivity dominate smaller operations with limited IT infrastructure.
- Cloud-Based:Full SaaS orchestration suits multi-site operators seeking centralized production monitoring.
- Mobile:Battery-powered units serve pop-up fulfillment and seasonal capacity surges.
Hybrid deployments capture the majority of new installations; mobile units are gaining share fastest in seasonal operations.
Size:
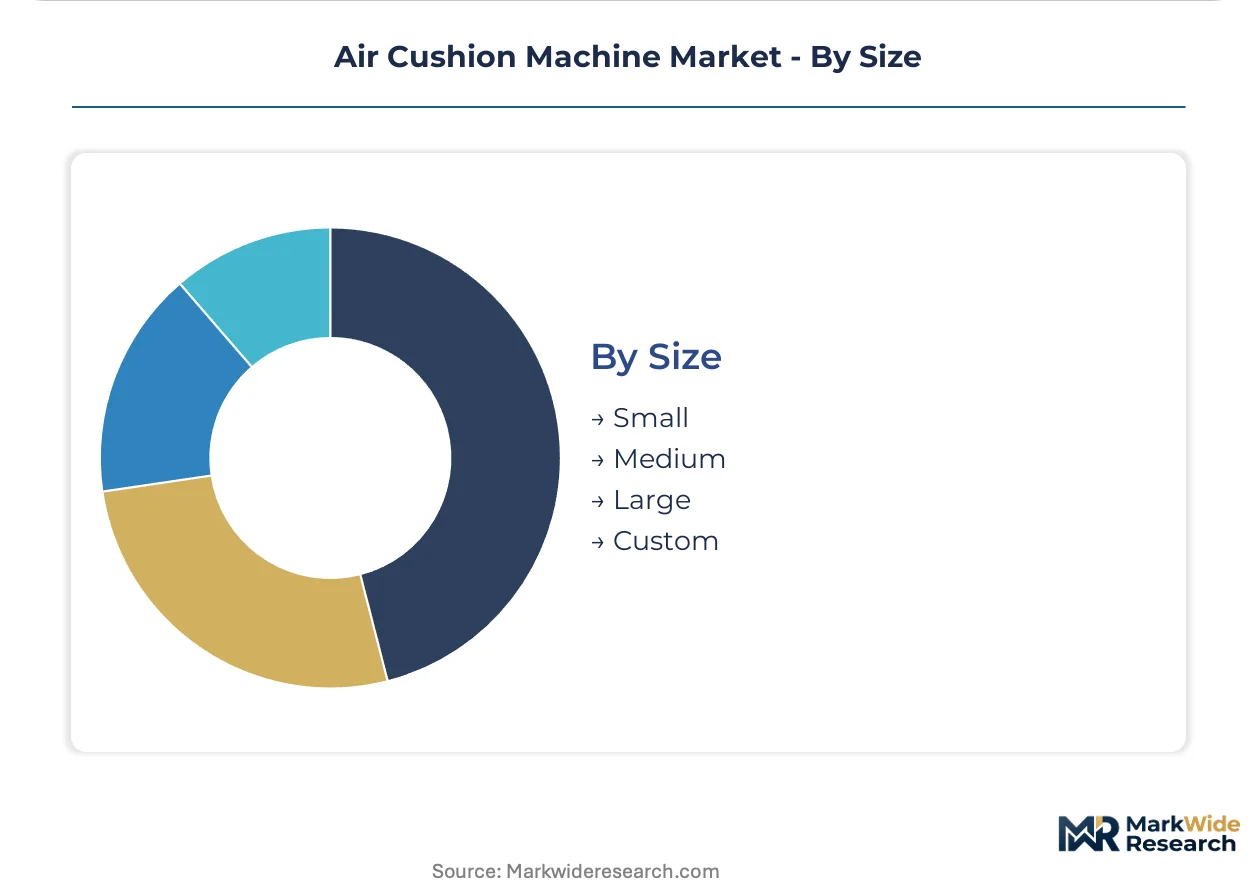
Margin concentration in small and medium formats reflects mid-market warehouse automation trends, while large machines serve dedicated high-throughput lines.
- Medium:Semi-automated cells operating at 15-20 meters per minute replace manual packing stations in regional 3PL networks. Modular subsystem architecture allows sealing module swaps without full machine replacement.
- Small:Compact footprint machines suit e-commerce startups and satellite fulfillment nodes where floor space constraints exceed throughput requirements.
- Large:Continuous-duty systems exceed 25 meters per minute for automotive and electronics OEMs.
- Custom:Engineered solutions for pharmaceutical cleanroom validation and FDA-compliant operations.
Medium-sized machines hold the largest installed base; small formats are expanding most quickly as micro-fulfillment proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for air cushion machines clusters in industrialized logistics corridors where e-commerce fulfillment density intersects with automotive manufacturing scale. Germany absorbs the largest share of European equipment installations, while the United States and China concentrate automated warehousing investment.
United States
E-commerce fulfillment centers in Ohio, Pennsylvania, and Texas drive equipment procurement for on-demand cushioning cells. The EPA guides sustainable packaging mandates through recycled content benchmarks that push manufacturers toward mono-material films. Chicago and Dallas logistics corridors host DHL and Amazon superhub networks negotiating machine-plus-film bundles.
Germany
Automotive OEMs near Stuttgart, Wolfsburg, and Munich require localized production cells with sub-24-hour film replenishment cycles. VerpackG amendments phase in extended producer responsibility fees that reshape total cost of ownership calculations. The Stuttgart automotive cluster deploys just-in-sequence cushioning systems for precision parts delivery.
China
Cross-border e-commerce platforms in Shenzhen and Hangzhou scale automated packaging lines to match export volume surges. The country's national packaging standards authority tightens mechanical recycling compatibility requirements for film substrates. Yangtze River Delta fulfillment hubs integrate cloud-connected cushion cells with warehouse management systems.
Netherlands
Rotterdam and Venlo logistics superhubs concentrate procurement power among volume buyers who specify open-architecture machines. REACH restrictions on plasticizers and stabilizers limit imported film compatibility, fragmenting equipment-film matching. The Randstad corridor hosts Kuehne+Nagel and DHL facilities driving hybrid deployment adoption.
Japan
Pharmaceutical shippers in Osaka and Tokyo seek cushion machines certified for ISO 14644-compliant cleanroom operations. METI efficiency standards accelerate cold-sealing technology diffusion in temperature-sensitive freight corridors. The Kansai region anchors precision electronics packaging demand where dimensional consistency matters.
Air Cushion Machine Market Competitive Environment
German producers anchor one tier; US specialists hold integrated solution positioning. The vendor base splits between captive consumable providers and open-architecture equipment fabricators. Three archetypes dominate: film-chemistry-integrated multinationals, modular subsystem specialists, and paper-based void-fill challengers. Competitive moves concentrate on M&A for regional production cells and technology licensing for cold-sealing modules.
Within the captive consumable tier, Sealed Air and Pregis exemplify film-chemistry-integrated positioning that locks buyers into proprietary resin formulations. Ranpak occupies a position as the paper-based alternative anchor, challenging conventional air cushion positioning through kraft-based void-fill systems. Storopack anchors European manufacturing scale with localized production cells, representing the regional proximity archetype near automotive clusters.
| Leading Market Players |
|---|
| Sealed Air |
| Pregis |
| Storopack |
| Ranpak |
| Smurfit Kappa Group |
| FP International |
| Automated Packaging Systems |
| Airspeed |
| Inflatable Packaging Inc. |
| Others |
Value Chain & Pricing Dynamics
LDPE and HDPE resin costs transmit directly from petrochemical feedstocks through machine-plus-film bundles to end-user pricing tiers, with German automotive clusters absorbing premium positioning while mid-market 3PLs in the Netherlands and Belgium negotiate volume discounts on standardized equipment configurations.
Pricing Analysis
Volume buyers at DHL and Kuehne+Nagel superhubs extract margin through machine-plus-film bundles, while standalone equipment vendors face compression. Price differentiation rests on certification grade—FDA-validated cleanroom systems command premiums against standard warehouse configurations. Cost compression in mid-market semi-automated cells intensifies as cloud-connected job scheduling becomes table stakes. E-commerce startups show highest price sensitivity; pharmaceutical shippers demonstrate lowest.
Supply Chain Analysis
Workforce availability constraints in Germany, China, and the United States shape manufacturing capacity allocation for precision sealing modules and control interfaces. Film resin formulations draw from petrochemical complexes in the US Gulf Coast, Middle East, and Northeast Asia. Single-source vulnerability concentrates in proprietary seal-layer chemistries that lock buyers into captive consumable streams. Distribution runs through OEM-direct channels for large automotive accounts and distributor networks for mid-market warehouses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Film chemistry capacity bottlenecks at specialized resin compounders prop equipment pricing premiums, constraining rapid supply response to demand surges in e-commerce fulfillment corridors.
For Market Incumbents: Deploy modular subsystem architecture to extend asset lifespans and capture recurring upgrade revenue. Incumbents must secure backward integration into seal-layer resin production to defend against open-architecture challengers. Ranpak's paper-based void-fill systems threaten volume in premium unboxing segments; counter with cold-sealing technology diffusion for temperature-sensitive applications.
For New Entrants and Emerging Players: Cloud-native job scheduling platforms offer a technology-first wedge into mid-market warehouses running legacy warehouse management systems. Target pharmaceutical cleanroom validation as the most penetrable premium tier, where FDA compliance documentation barriers deter generalist competitors. Lead with SaaS-based orchestration to bypass capital-intensive hardware manufacturing.
For Investors and Strategic Acquirers: REACH additive restriction announcements from ECHA are the leading indicator that equipment-film matching complexity will favor integrated solution providers over standalone fabricators. Long-term viability centers on recurring consumable revenue streams rather than unit equipment sales. Monitor modular subsystem specialists with established automotive cluster proximity as acquisition candidates.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Sealing Module Licensing | Heat-free sealing expands film substrate compatibility for food and pharmaceutical temperature-sensitive corridors. |
| Regional Production Cell Expansion | Localized manufacturing near Stuttgart and Wolfsburg automotive clusters reduces film logistics costs. |
| Cloud-Connected Platform Integration | SaaS-based job scheduling synchronizes cushion generation with order-picking workflows in hybrid deployments. |
| FDA Cleanroom Validation Investment | ISO 14644-compliant contamination-control documentation captures premium positioning in pharmaceutical shipping. |
| Backward Integration into Film Resin | In-house seal-layer chemistry production locks buyers into proprietary consumable supply streams. |
Study Parameters
Multi-period observation of equipment procurement patterns, film chemistry reformulation cycles, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with warehouse operations directors, packaging automation engineers, 3PL procurement leads, and automotive logistics coordinators. Secondary validation drew from EPA sustainable packaging guidance, ECHA REACH restriction updates, EU Packaging and Packaging Waste Regulation filings, and customs trade data on LDPE/HDPE resin flows. Bottom-up triangulation across regional installation counts and top-down cross-check against equipment manufacturer revenue disclosures ensured consistency.
Input-output matrix modeling connected film substrate availability, sealing technology diffusion rates, and end-use vertical demand patterns across the projection horizon. Segmentation dimensions included product type, deployment configuration, machine size tier, and industry vertical. CAGRs derived from curve-fitting historical adoption trajectories against regulatory deadline impacts. Forecast inputs incorporated e-commerce fulfillment center buildout pipelines and automotive OEM packaging automation budgets.
Several conditions sit outside the modeled scope, including sudden tariff disruptions on Chinese-manufactured control components and unannounced ECHA additive bans. Forecasts reflect documented assumptions on resin price stability and cloud platform adoption curves. Material deviation in REACH enforcement intensity or VerpackG fee implementation schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Auger Powder Filling Machines Market
Packaging Machinery
Envelope Sealing Machines Market
Packaging Machinery
Global Form Fill Seal Machines Market
Packaging Machinery
Vertical Injection Molding Machine Market
Packaging Machinery
Polyester Strapping Machines Market
Packaging Machinery
Tube Filling Machine Market
Packaging Machinery
Meal Tray Sealing Machines Market
Packaging Machinery
Flow Wrap Machines Market
Packaging Machinery
Automatic Auger Fillers Market
Packaging Machinery
Piston Fillers Market
Packaging Machinery
Foil Embossing Machine Market
Packaging Machinery
Tamper Evidence Machinery Market
Packaging Machinery
Emboss Coding Machine Market
Packaging Machinery
Case Packing Machines Market
Packaging Machinery
Tubular Form Fill and Seal Machines Market
Packaging Machinery
Cling Wrap Machine Market