
 App Uninstall Software Market | 2026-2036
App Uninstall Software Market Size, Share, and Industry Trends Forecast 2026-2036
App Uninstall Software Market Insights
The gap between premium enterprise-grade uninstall suites and free consumer utilities is realigning around security certification and centralized policy management. IObit Uninstaller leverages deep registry scanning capabilities to sustain its position among power users seeking thorough removal traces. Revo Uninstaller anchors the mid-market segment with portable deployment options that appeal to IT service technicians. Geek Uninstaller competes on speed and minimal footprint, occupying a niche among users prioritizing lightweight execution.
App uninstall software comprises specialized utilities engineered to detect, terminate, and eradicate application files, registry entries, and residual configuration data beyond native operating system removal functions. These tools typically integrate with Windows Installer APIs, macOS bundle identifiers, or Linux package managers while executing recursive dependency mapping to prevent system instability. System Optimizers command the largest revenue pool as organizations bundle uninstall capabilities with broader endpoint performance management. Cleanup Utilities represent the fastest-expanding category as privacy-conscious consumers seek granular control over telemetry remnants. Cloud-Based deployment models are gaining structural momentum among distributed enterprises requiring unified software inventory governance across hybrid workforces.
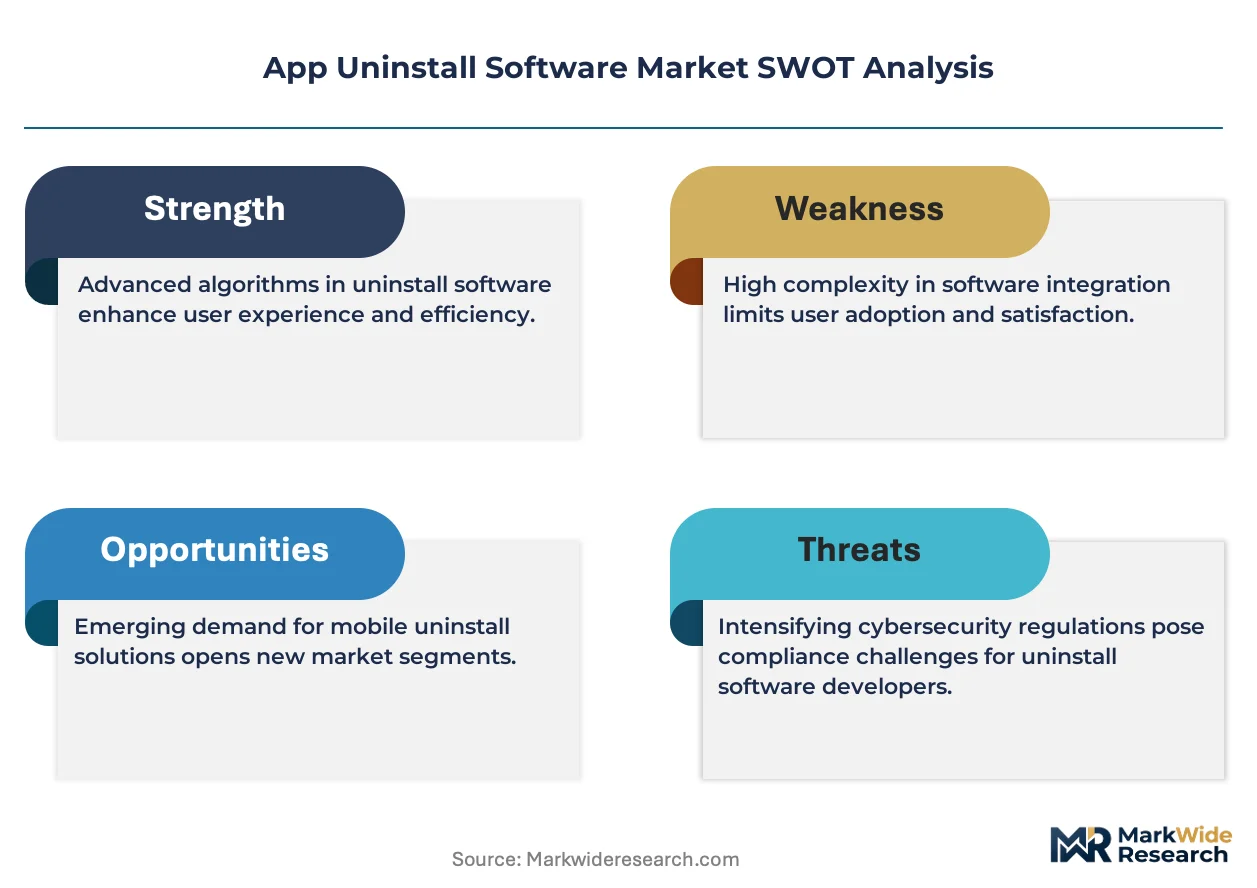
The EU GDPR and the California Consumer Privacy Act impose strict data erasure mandates that elevate uninstall software from convenience to compliance infrastructure. The US Federal Trade Commission actively monitors deceptive claims about data deletion completeness, pressuring vendors toward verifiable removal certifications. ISO 27001-aligned enterprises increasingly require audit trails of software removal events to satisfy third-party security assessments. Stakeholders must weigh whether to build uninstall capabilities into existing endpoint platforms or maintain standalone procurement relationships as zero-trust architectures redefine software lifecycle boundaries.
Market Dynamics
Zero-trust security architectures are redefining endpoint hygiene requirements, forcing organizations to treat software removal as a continuous compliance activity rather than episodic cleanup. This structural shift elevates uninstall utilities from discretionary tools to mandated infrastructure components within enterprise security stacks.
Growth Catalysts
- GDPR Article 17 Mandates:The EU's right-to-erasure provisions require demonstrable data deletion from decommissioned applications, driving enterprise procurement of certified removal tools.
- Remote Workforce Expansion:Distributed IT teams require centralized software inventory governance across unmanaged home devices and corporate endpoints.
- Orphaned Application Risk:Security teams in financial services and healthcare sectors prioritize complete eradication of unsupported software to reduce attack surface exposure.
Market Restraints
- Native OS Capability Improvement:Microsoft and Apple have strengthened built-in uninstall functions, compressing differentiation space for third-party utilities in consumer segments.
- Freeware Saturation:The abundance of no-cost alternatives with adequate basic functionality constrains pricing power in individual user markets.
- Platform Dependency:Windows-centric tool architectures face adaptation costs as macOS and Linux gain enterprise desktop share.
Strategic Opportunities
- ISO 27001 Audit Trail Integration:Vendors can embed tamper-proof removal logging to capture compliance-driven enterprise budgets.
- Telemetry Scrubbing Specialization:Privacy-conscious consumers seek granular control over residual data traces left by cloud-connected applications.
- Managed Service Provider Channels:IT service technicians represent an underserved segment requiring portable, scriptable deployment options.
Industry Challenges
- Registry Integrity Expertise:Deep Windows subsystem knowledge is scarce among developers, constraining thorough removal capability development.
- False Positive Management:Aggressive scanning algorithms risk destabilizing systems, requiring extensive quality assurance investment.
- Cross-Platform Standardization:Divergent package management architectures across operating systems fragment development resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | App Uninstall Software Market |
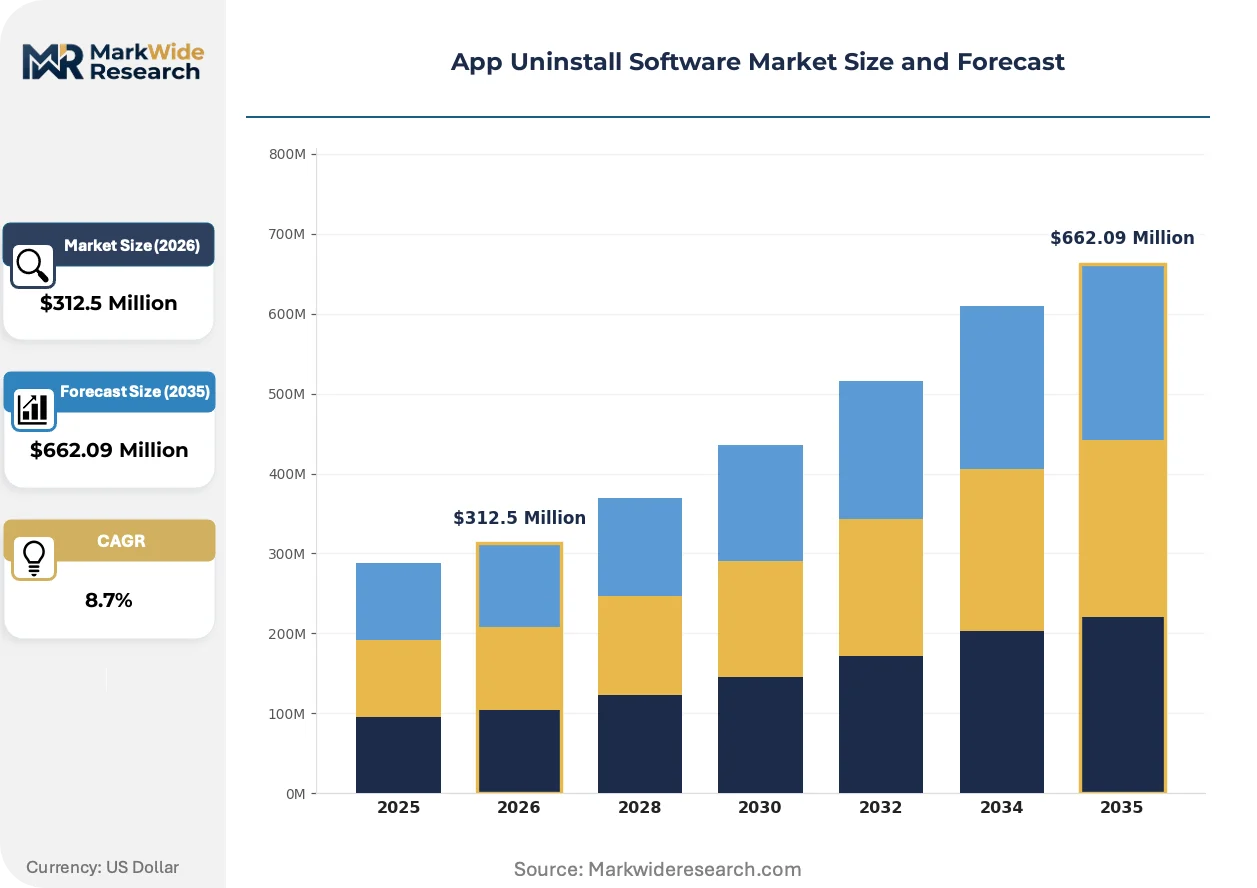
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uninstaller Tools, System Optimizers, Cleanup Utilities, Mobile Management Apps End User: Individual Users, Enterprises, Software Developers, IT Administrators Functionality: Batch Removal, Disk Space Management, Privacy Protection, System Performance Enhancement Deployment Model: On-Premises, Cloud-Based, Hybrid Solutions, Portable Applications |
| Companies Covered | Revo Uninstaller, IObit Uninstaller, Bulk Crap Uninstaller, Geek Uninstaller, HiBit Uninstaller, Wise Program Uninstaller, Total Uninstall, Uninstall Tool, CleanMyMac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
App Uninstall Software Market Trends and Innovations
Artificial intelligence is penetrating endpoint management tools, enabling predictive identification of software redundancy before security exposure materializes. This intelligence layer is compressing reaction times and expanding the functional boundary of traditional uninstall utilities.
Behavioral analysis engines are converging with uninstall software architectures to map application interdependencies before removal execution. Enterprise security teams in the United States are piloting these capabilities to prevent cascade failures from premature component deletion. The structural consequence is a shift from reactive cleanup to proactive software lifecycle orchestration.
The EU AI Act's risk classification framework is imposing algorithmic transparency requirements on automated decision-making tools, including endpoint management systems. Vendors must now document how removal recommendations are generated and provide human override mechanisms. European enterprise procurement committees are prioritizing certified tools that satisfy these explainability mandates.
Subscription-based licensing is displacing perpetual purchase models across mid-market and enterprise segments. IT asset managers prefer predictable operational expenditure aligned with seat-count fluctuations rather than capital-intensive upfront commitments. Germany and Japan exhibit the fastest migration toward recurring revenue structures in endpoint hygiene software procurement.
App Uninstall Software Market Segmentation
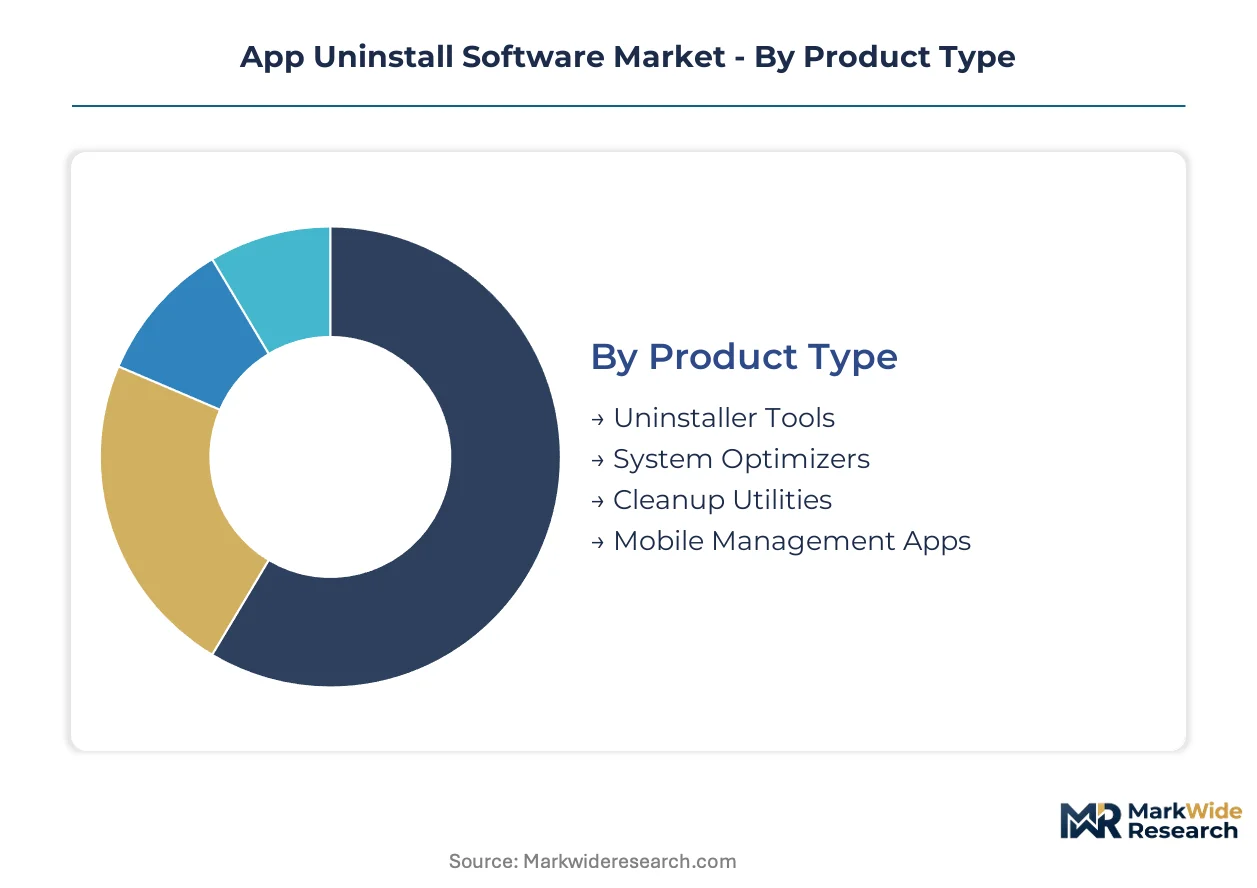
Segmentation in app uninstall software reflects divergent capital requirements across product architectures and deployment modes. Enterprise-grade solutions demand substantial upfront engineering investment in registry analysis engines and compliance logging infrastructure, while consumer utilities prioritize lean distribution models.
Product Type:
Capital intensity concentrates in system optimizers requiring integrated performance monitoring subsystems and enterprise telemetry pipelines.
- Uninstaller Tools:Core utilities execute deep registry scanning and recursive dependency mapping to eradicate residual configuration data beyond native OS functions. Demand clusters among power users in Germany and Japan seeking forensic-level removal completeness for GDPR and APPI compliance scenarios.
- System Optimizers:Bundled suites combine uninstall capabilities with broader endpoint performance management, requiring continuous development of heuristic analysis engines. Financial services institutions in the United States prioritize these tools for ISO 27001-aligned software asset lifecycle governance.
- Cleanup Utilities:Specialized modules target telemetry remnants and privacy traces from cloud-connected applications.
- Mobile Management Apps:Lightweight variants address iOS and Android application removal with constrained system access permissions.
Most installed capacity flows through System Optimizers. Expansion is steepest in Cleanup Utilities.
End User:
Customer type determines pricing architecture, with enterprises accepting subscription premiums for centralized policy orchestration that individual users reject.
- Enterprises:IT departments procure seat-based licenses with mandatory audit trail generation and tamper-proof removal logging for third-party security assessments. Regulatory enforcement in the European Union and California elevates these tools from discretionary to mandated infrastructure.
- IT Administrators:Technical operators require scriptable deployment options and portable execution for unmanaged device fleets. Managed service providers in Japan represent an underserved channel seeking lightweight, technician-grade utilities.
- Individual Users:Price-sensitive consumers gravitate toward freeware with adequate basic functionality, compressing vendor margins.
- Software Developers:Niche demand for testing environment reset tools and clean-slate deployment verification.
Revenue concentration sits with Enterprises. User count expansion is climbing fastest among IT Administrators.
Functionality:
Engineering resource allocation skews toward privacy protection modules as regulatory data erasure mandates proliferate across jurisdictions.
- Privacy Protection:Granular control over telemetry remnants and cloud synchronization traces requires continuous adaptation to evolving application architectures. GDPR Article 17 and CCPA deletion mandates in the European Union and California drive procurement of certified removal tools with demonstrable completeness.
- System Performance Enhancement:Integrated optimization engines identify software redundancy before security exposure materializes, compressing reaction times for enterprise security teams. Pilot programs in United States financial services are validating predictive identification capabilities.
- Batch Removal:Automated queue processing for enterprise software inventory governance across distributed workforces.
- Disk Space Management:Storage reclamation targeting orphaned application files and temporary data accumulation.
Development bandwidth concentrates in Privacy Protection. Commercial traction is gaining fastest in System Performance Enhancement.
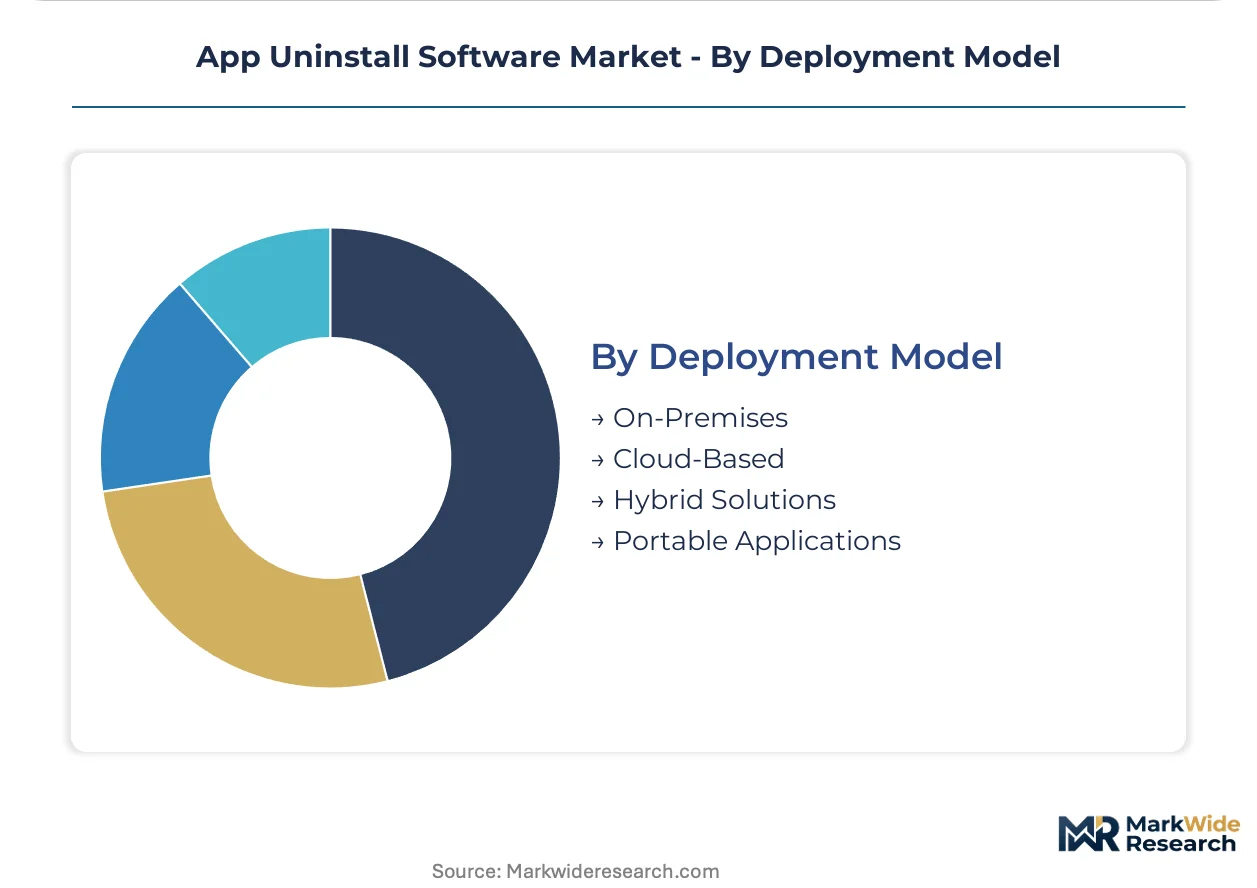
Deployment Model:
Cloud infrastructure investment requirements are reshaping competitive entry barriers as distributed enterprises demand unified governance.
- Cloud-Based:Centralized policy management and real-time software inventory visibility across hybrid workforces necessitate persistent backend architecture and encryption pipelines. German and Japanese enterprises exhibit the fastest migration toward recurring revenue structures for endpoint hygiene procurement.
- Portable Applications:Zero-install execution appeals to IT service technicians requiring rapid deployment without administrative privileges. Technician workflows in field service environments prioritize minimal footprint and USB-boot compatibility.
- On-Premises:Air-gapped installations for classified or regulated environments with data sovereignty constraints.
- Hybrid Solutions:Mixed architectures balancing local execution with cloud policy synchronization.
Seat deployment runs predominantly through Cloud-Based models. Adoption velocity is highest in Portable Applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise software density in Germany exceeds that of Japan, yet both markets exhibit parallel compliance-driven procurement patterns for endpoint hygiene tools. Regulatory enforcement intensity varies substantially across jurisdictions, with the United States, Germany, and Japan commanding disproportionate vendor attention due to concentrated IT spending and stringent data protection mandates.
United States
Financial services institutions in New York and Chicago drive demand for ISO 27001-aligned audit trail capabilities within uninstall software procurement. The FTC actively monitors vendor claims about data deletion completeness, pressuring suppliers toward verifiable removal certifications. Silicon Valley technology clusters pilot AI-enhanced behavioral analysis engines for predictive software redundancy identification.
Germany
GDPR Article 17 enforcement has elevated uninstall utilities from discretionary tools to mandated compliance infrastructure across Mittelstand enterprises. The Federal Office for Information Security (BSI) publishes technical guidelines that shape procurement specifications for federal and critical infrastructure operators. Bavarian automotive manufacturers require tamper-proof removal logging to satisfy supply chain security assessments from OEM partners.
Japan
APPI amendments and METI cybersecurity frameworks compel enterprises in Tokyo and Osaka toward rigorous endpoint hygiene practices for software asset lifecycle management. Managed service providers represent an underserved channel seeking portable, technician-grade deployment options. Nagoya manufacturing clusters prioritize complete eradication of unsupported software to reduce industrial control system attack surface exposure.
United Kingdom
Post-Brexit data protection alignment with GDPR-equivalent standards sustains enterprise demand for certified removal tools in London financial services and Manchester technology corridors. The Information Commissioner's Office issues enforcement notices that elevate demonstrable data erasure from best practice to legal obligation. Edinburgh fintech clusters require centralized policy orchestration across hybrid workforces with distributed software inventory governance.
India
IT service exporters in Bangalore and Hyderabad expand adoption of uninstall tools to manage software asset lifecycles across global client delivery centers. The Digital Personal Data Protection Act imposes emerging data erasure obligations that vendors are positioning to address. Mumbai financial institutions pilot cloud-based deployment models for unified endpoint governance across geographically dispersed operations.
App Uninstall Software Market Competitive Landscape
Top-tier vendors anchor the enterprise compliance segment, while freeware utilities and technician-grade portable tools populate lower tiers with minimal differentiation. Market structure exhibits moderate concentration around vendors with security certification capabilities and centralized policy management infrastructure. Three strategic archetypes dominate: registry-deep removal specialists, speed-optimized lightweight utilities, and bundled system optimization suites. Competitive moves center on M&A activity targeting behavioral analysis engine capabilities and strategic partnerships with managed service provider distribution channels.
Within the portable utility tier, Geek Uninstaller and HiBit Uninstaller exemplify minimal-footprint execution priorities that appeal to field service technicians requiring rapid deployment without administrative privileges. Revo Uninstaller occupies a mid-market position representing bundled deployment flexibility. IObit Uninstaller anchors the registry-scanning specialist archetype with deep Windows subsystem capabilities. These three vendors collectively illustrate the segmentation between speed, thoroughness, and integration breadth that defines competitive positioning across price tiers.
| Leading Market Players |
|---|
| Revo Uninstaller |
| IObit Uninstaller |
| Bulk Crap Uninstaller |
| Geek Uninstaller |
| HiBit Uninstaller |
| Wise Program Uninstaller |
| Total Uninstall |
| Uninstall Tool |
| CleanMyMac |
| Others |
Pricing and Supply Chain Analysis
Deep Windows registry engineering expertise concentrates in Eastern Europe and South Asia, where labor-cost differentials between Warsaw and Bangalore development centers widen pricing-tier spreads between forensic-level enterprise suites and lightweight consumer utilities.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across the App Uninstall Software Market. Subscription-based SaaS tiers dominate enterprise procurement, with ISO 27001-certified audit trail capabilities and centralized policy orchestration commanding premium positioning against freeware alternatives. Price differentiation rests on certification grade and after-sales service depth, with GDPR-compliant removal logging justifying substantial seat-based premiums. Pricing pressure stems from Microsoft and Apple native OS capability improvements compressing third-party differentiation space. Individual users exhibit highest price sensitivity, while financial services institutions demonstrate lowest sensitivity due to compliance mandate urgency.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand from IT departments and managed service providers, while digital distribution platforms serve price-sensitive consumer segments. Engineering talent concentrates in Poland, India, and Ukraine, with these regions anchoring development operations for registry analysis engines and behavioral analysis modules. Raw material dependencies center on cloud infrastructure services, encryption pipeline technologies, and Windows Installer API documentation access. Supply chain risk hinges on single-source vulnerability for deep Windows subsystem expertise, where qualified developers remain scarce relative to demand. Distribution runs through OEM bundling agreements, MSP channel partnerships, and direct-to-consumer digital storefronts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The App Uninstall Software Market offers margin-expansion pathways through cloud-based deployment model premiums and telemetry scrubbing specialization, where recurring revenue structures displace perpetual licensing and compliance-driven procurement reduces price elasticity.
For Market Incumbents: Anticipate native OS capability improvements from Microsoft and Apple by deepening vertical integration into behavioral analysis engine development and securing ISO 27001-aligned certification investments. Prioritize MSP channel control through scriptable deployment tooling and portable execution architectures that field service technicians require for unmanaged device fleets. For New Entrants and Emerging Players: AI-enhanced predictive redundancy identification represents the most penetrable technology-first wedge for market entry. Target technician-grade portable utilities for Japanese MSPs and privacy-conscious cleanup utilities for GDPR-triggered European procurement. Pursue direct digital distribution with minimal footprint execution as the primary go-to-market angle against established bundled suites. For Investors and Strategic Acquirers: Endpoint security platform vendors are the most active acquirer in this space, seeking uninstall capabilities to complete zero-trust architecture stacks. Long-term viability favors vendors with tamper-proof removal logging infrastructure and cross-platform adaptation capacity beyond Windows-centric architectures. Watch for FTC enforcement actions on data deletion completeness claims as an inflection indicator for certification-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Behavioral Analysis Specialist | Endpoint security vendors gain predictive redundancy identification capabilities piloted in US financial services. |
| ISO 27001 Audit Trail Certification | German Mittelstand enterprises mandate tamper-proof removal logging for supply chain security assessments. |
| MSP Channel Partnership Expansion | Japanese managed service providers seek portable, scriptable deployment options for field technician workflows. |
| Cross-Platform Architecture Development | macOS and Linux enterprise desktop share gains force adaptation beyond Windows-centric tool foundations. |
| Telemetry Scrubbing Module Launch | GDPR Article 17 and CCPA deletion mandates elevate privacy protection modules to compliance infrastructure. |
Research Methodology
Multiple input streams — primary interviews with IT asset managers and endpoint security directors, secondary validation through SEC filings and hyperscaler capex disclosures, and customs records for software licensing flows — were reconciled to construct market estimates. Conversations with CTOs, IT procurement officers, platform engineers, and MSP operations heads informed demand-side dynamics. Secondary sources included enterprise software procurement databases, channel partner surveys, and regulatory filing repositories. Bottom-up seat-count modeling and top-down IT spending allocation analysis provided triangulation checks across the analysis window.
Data-stream reconciliation anchored the forecast framework across deployment models, organization sizes, vertical sectors, integration complexity tiers, and regional adoption patterns. CAGRs were derived from segmented growth rate reconciliation against aggregate IT security spending trajectories. Modeled inputs included remote workforce expansion rates, GDPR enforcement intensity indices, and native OS capability improvement curves.
The model holds under sustained regulatory enforcement and distributed workforce normalization; deviation in platform dependency shifts or freeware capability improvements would shift trajectory. Forecasts reflect documented assumptions about enterprise subscription migration velocity and compliance budget allocation priorities. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Human Capital Management (HCM) Saas Market
Software & Services
Global Press Release Distribution Software Market
Software & Services
Driver Updater Software Market
Software & Services
Europe Digital Signage Software Market
Software & Services
Game Development Software Market
Software & Services
Global Trade Promotion Management Software Market
Software & Services
Global Cloud Enterprise Resource Planning Market
Software & Services
Period-Tracking Software Market
Software & Services
Global Reference Check Software Market
Software & Services
Africa Financial Services Software Market
Software & Services
Global Cloud Based Collaboration Software Market
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
Global Recipe Apps Market
Software & Services
Document-Centric Collaboration Software Market
Software & Services
Global Chromatography Software Market
Software & Services
Servicenow Tech Services Market