
 Test Management Software Market | 2026-2036
Test Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Test Management Software Market Outlook
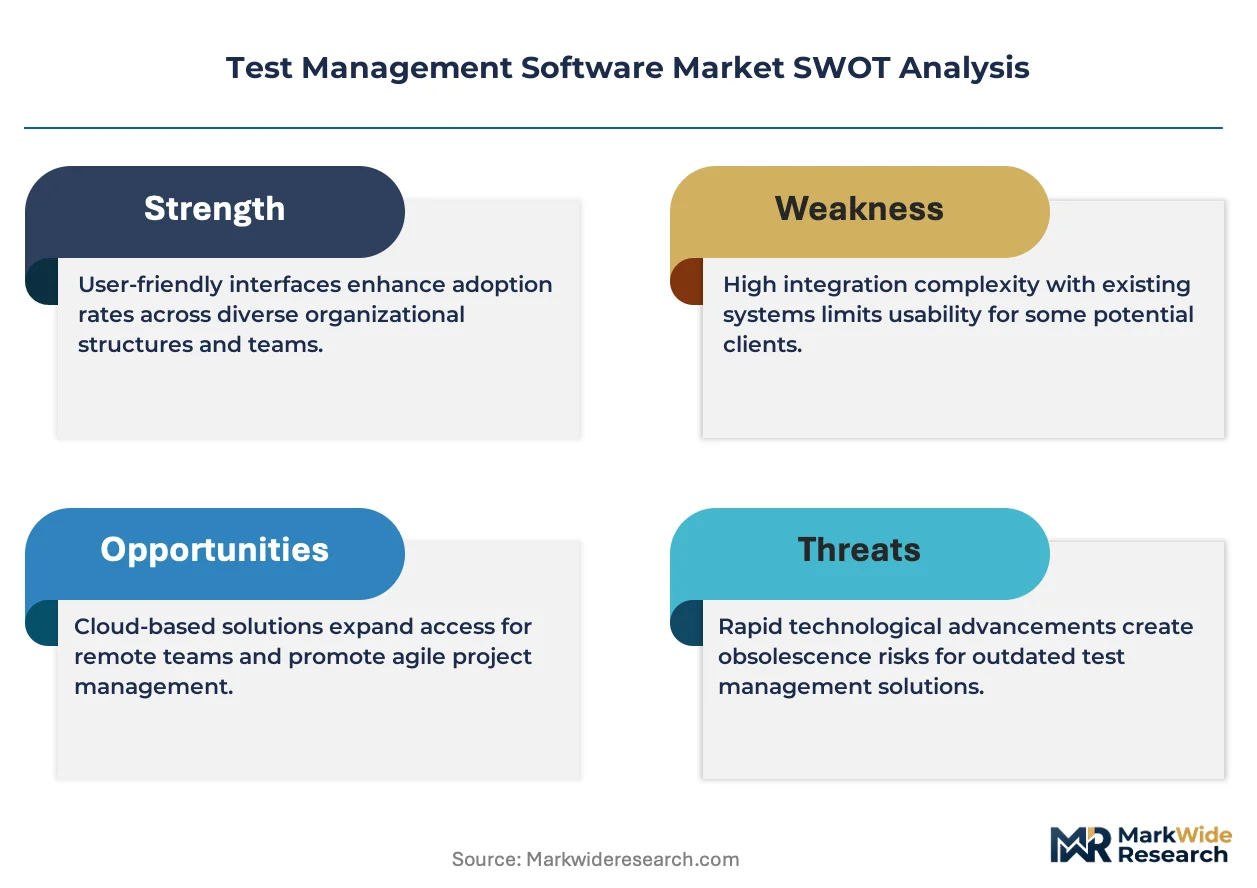
EU AI Act compliance obligations across automated decision systems is expanding the addressable base for governance-ready test platforms. SmartBear Software leverages its API testing heritage to anchor enterprise contracts in regulated sectors. PractiTest competes through flexible SaaS delivery that accommodates multi-jurisdictional audit trails. Xray specializes in native JIRA integration, dominating Atlassian-centric development shops across Europe.
Test management software orchestrates the full lifecycle of software quality assurance, from test case authoring through execution scheduling, defect triage, and compliance reporting, typically supporting parallel test runs across distributed environments with traceability matrices linking requirements to outcomes. Its primary commercial purpose is to reduce escaped defects in production systems while maintaining auditable records for regulated industries. Cloud-based deployment leads segment economics due to lower infrastructure overhead and faster onboarding cycles, while hybrid configurations capture margin pools from enterprises with data residency constraints. Integration with CI/CD tools represents the fastest-growing functionality dimension as DevOps maturation demands seamless pipeline embedding.
FDA validation requirements for medical device software enforce structured test documentation that shapes product design priorities for vendors serving healthcare. EMA's evolving guidance on software as a medical device extends similar accountability to diagnostic algorithms, while ISO 27001 certification has become a baseline procurement filter across European enterprise buyers. Stakeholders must weigh whether to build in-house compliance modules or partner with platforms that pre-certify against multiple regulatory frameworks.
Market Dynamics
EU AI Act algorithmic accountability mandates are restructuring procurement criteria for automated testing pipelines, forcing vendors to embed governance-by-design architectures into core product roadmaps.
Growth Catalysts
- EU AI Act Compliance Mandates:Automated decision systems in financial services and healthcare now require auditable test trails, expanding demand for governance-ready platforms across German automotive and French banking sectors.
- DevOps Pipeline Maturation:CI/CD tool integration has become a non-negotiable procurement filter as enterprise software teams compress release cycles and demand seamless test orchestration.
- Medical Device Software Proliferation:FDA validation requirements for SaMD (Software as a Medical Device) enforce structured test documentation, pulling healthcare technology vendors toward specialized test management procurement.
Market Restraints
- Cloud Infrastructure Concentration:Hyperscaler dominance in EU data residency zones creates vendor lock-in risks for enterprises requiring sovereign test data storage.
- Specialized Talent Scarcity:Shortage of engineers conversant in both test automation frameworks and multi-jurisdictional compliance documentation slows enterprise deployment timelines.
- Legacy System Entrenchment:Mainframe-dependent financial institutions in Germany and Switzerland face technical debt barriers when migrating test workflows to API-native platforms.
Strategic Opportunities
- EMA Software as Medical Device Guidance:Evolving diagnostic algorithm accountability standards create whitespace for test platforms offering pre-validated documentation templates.
- ISO 27001 Certification Arbitrage:Vendors achieving concurrent ISO 27001 and SOC 2 Type II certifications capture procurement preference among European enterprise buyers with dual compliance obligations.
- Edge Computing Test Orchestration:Distributed manufacturing IoT deployments in German industrial corridors require localized test execution nodes, opening hybrid deployment revenue streams.
Industry Challenges
- Multi-Framework Certification Overhead:Engineering teams must maintain parallel documentation standards for FDA, EMA, and ISO 13485 simultaneously, fragmenting platform development resources.
- API Versioning Complexity:Rapid CI/CD tool evolution forces continuous integration maintenance costs as test platforms chase compatibility with shifting pipeline standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Test Management Software Market |
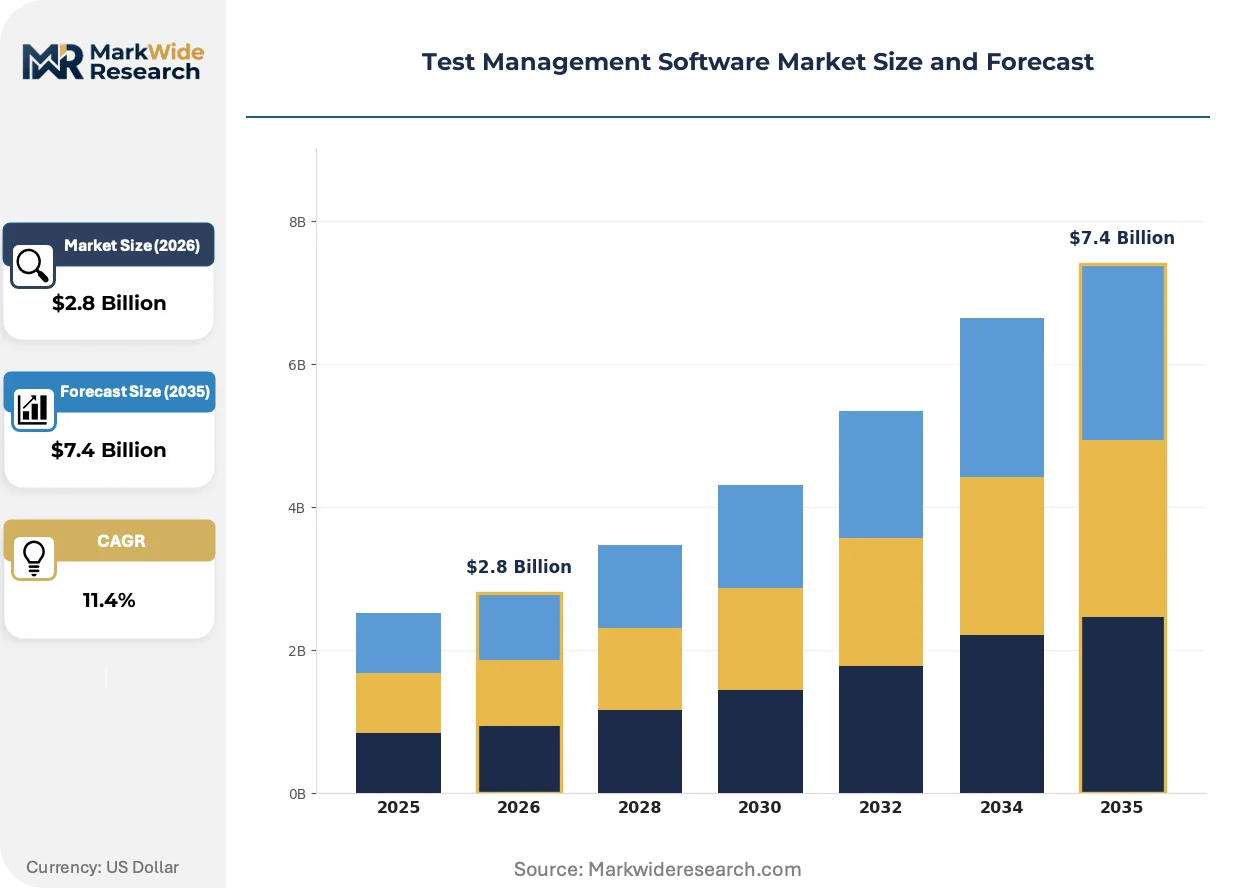
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: IT Departments, QA Teams, Software Development, Project Management Functionality: Test Planning, Test Execution, Defect Tracking, Reporting Integration: JIRA, CI/CD Tools, Version Control, Automation Tools |
| Companies Covered | TestRail, Zephyr, PractiTest, Xray, qTest, BrowserStack, Testmo, SmartBear Software, QMetry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Test Management Software Market Strategic Shifts
Agentic AI systems are penetrating test case generation workflows, compressing manual scripting cycles while introducing new validation requirements for machine-generated test artifacts.
Generative AI models trained on historical defect repositories are automating edge-case identification for financial services payment systems. Tier-one banks in London and Frankfurt are deploying these tools within regulated sandbox environments. The technology is automating regression test suite expansion that previously required manual business analyst review.
EU AI Act risk classification tiers are mandating algorithmic impact assessments for high-risk automated testing decisions in credit scoring and diagnostic imaging. Medical device manufacturers must now maintain version-controlled test evidence for each model iteration. German notified bodies are developing sector-specific audit protocols for AI-enabled quality assurance systems.
Subscription fatigue among mid-market software vendors is driving preference for consumption-based pricing tied to actual test execution minutes rather than seat licenses. Channel partners in the Netherlands and Nordics are unbundling implementation services from platform fees. This shift is most visible among Series B SaaS companies seeking to align quality assurance costs with release velocity.
Test Management Software Market Segmentation
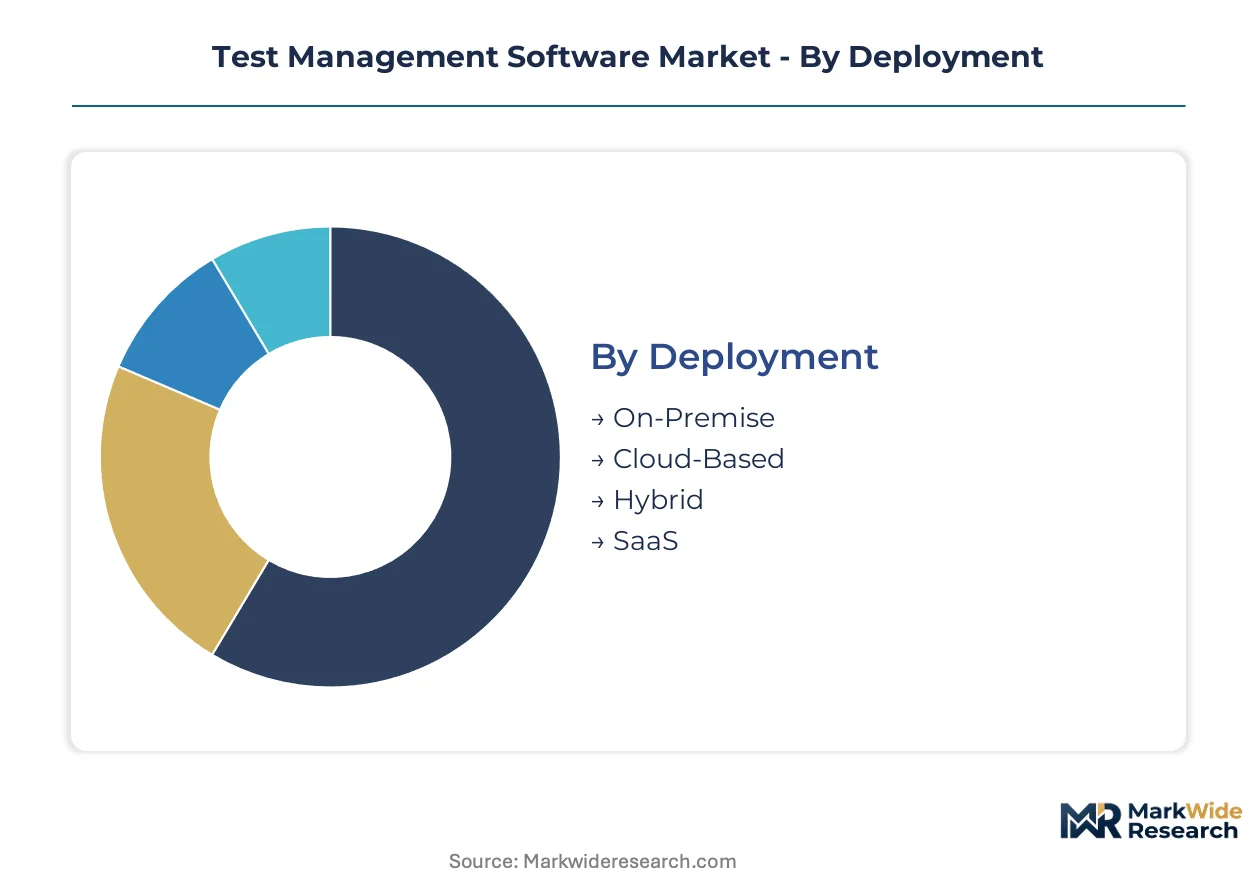
Test management software procurement patterns diverge sharply across deployment architectures and functional requirements. Enterprise buyers weight data residency obligations against DevOps velocity demands when selecting platform configurations.
Deployment:
Technical architecture determines infrastructure overhead, compliance posture, and integration flexibility for quality assurance workflows.
- Cloud-Based:Multi-tenant architectures eliminate server maintenance burdens while enabling elastic scaling for parallel test execution. German automotive suppliers and French banking consortia are migrating legacy suites to EU-sovereign cloud zones to satisfy GDPR and EU AI Act data localization mandates without sacrificing pipeline velocity.
- SaaS:Subscription delivery models compress procurement cycles through pre-configured environments and automatic feature updates. Mid-market software vendors in the Netherlands and Nordics favor consumption-based billing tied to actual test execution minutes rather than seat licenses.
- On-Premise:Dedicated hardware installations persist in Swiss private banking and German defense contracting where air-gapped environments are non-negotiable.
- Hybrid:Split configurations segment sensitive test data on-premises while pushing non-critical execution to cloud nodes.
Mature deployment sits with On-Premise configurations in regulated financial and defense sectors. Newer deployment is concentrated in Cloud-Based architectures among SaaS-native enterprises.
End User:
Organizational function shapes feature prioritization, with technical depth and compliance exposure varying across buyer personas.
- QA Teams:Specialized quality engineers demand granular traceability matrices, defect triage workflows, and audit-ready documentation templates. Medical device manufacturers in Ireland and Germany staff dedicated validation teams to satisfy FDA and EMA software as medical device requirements.
- Software Development:Engineering organizations prioritize API-native integrations, CI/CD pipeline embedding, and shift-left automation capabilities. London and Frankfurt tier-one banks deploy generative AI-assisted test generation within developer sandboxes.
- IT Departments:Infrastructure-focused buyers emphasize security certifications, single sign-on architectures, and cross-functional license administration.
- Project Management:Non-technical coordinators value dashboard consolidation, resource scheduling, and executive reporting without requiring deep test scripting knowledge.
Feature depth concentrates with QA Teams. User base expansion is climbing the fastest among Software Development organizations adopting DevOps maturation practices.
Functionality:
Core capability modules align with discrete phases of the quality assurance lifecycle, from initial planning through post-release verification.
- Test Execution:Distributed run orchestration across containerized environments enables parallel validation at scale. German industrial IoT deployments leverage edge-localized execution nodes to reduce latency for manufacturing quality gates.
- Defect Tracking:Bidirectional requirement-to-failure traceability supports root cause analysis and regulatory audit trails. Healthcare technology vendors maintain version-controlled defect repositories for each algorithmic iteration under EU AI Act risk classification protocols.
- Test Planning:Resource allocation and scheduling modules coordinate cross-functional team capacity.
- Reporting:Compliance documentation generators produce structured evidence packages for external auditor review.
Procurement priority sits with Test Execution capabilities. Investment acceleration is gaining share fastest in Defect Tracking as algorithmic accountability mandates expand.
Integration:
Connectivity architecture determines platform utility within existing toolchain ecosystems, with compatibility breadth influencing renewal rates.
- CI/CD Tools:Native pipeline embedding enables automated test triggering on code commits, with results feeding directly into deployment gates. Jenkins, GitLab, and Azure DevOps connectors have become non-negotiable procurement filters for enterprise DevOps maturation.
- JIRA:Native Atlassian ecosystem integration dominates European development shops, with bidirectional issue synchronization between test failures and backlog items. Xray and similar platforms capture market position through deep JIRA alignment.
- Automation Tools:Selenium, Cypress, and Playwright compatibility extends platform reach into browser and API testing frameworks.
- Version Control:Git repository linking enables test case versioning alongside application code branches.
Integration maturity sits with JIRA connectivity. Capability expansion is steepest in CI/CD Tools as release cycle compression demands seamless pipeline embedding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Test management software production concentrates in US and European technology corridors, while consumption spreads across financial centers and automotive manufacturing belts seeking algorithmic compliance infrastructure.
United States
FDA validation requirements for medical device software and SEC algorithmic trading audits drive procurement in Boston's medtech cluster and Manhattan's fintech towers. HIPAA-compliant test documentation templates dominate healthcare technology vendor selection criteria. San Francisco's enterprise SaaS companies embed CI/CD-native platforms to accelerate release velocity.
Germany
KBA automotive software mandates and EU AI Act risk classification protocols reshape quality assurance spending across Stuttgart's OEM engineering centers and Munich's industrial IoT corridors. ISO 13485 certification filters procurement for diagnostic algorithm developers. Frankfurt's tier-one banks deploy governance-ready test trails for credit scoring automation.
United Kingdom
FCA operational resilience requirements and EMA software as medical device guidance expand addressable demand in London's insurance technology district and Cambridge's biotech corridor. GDPR audit trail specifications influence cloud deployment architecture decisions. Edinburgh's fintech scale-ups favor consumption-based pricing tied to test execution minutes.
France
ANSM software lifecycle documentation rules and CNIL algorithmic accountability standards tighten procurement criteria for Parisian banking consortia and Lyon's medical imaging specialists. CE marking alignment with MDR extends test evidence requirements to diagnostic AI systems. Toulouse's aerospace software suppliers maintain air-gapped validation environments.
India
CDSCO software as medical device notifications and RBI digital payment security guidelines accelerate structured test adoption across Bangalore's health-tech parks and Mumbai's financial services hubs. BIS quality management standards shape enterprise platform selection. Hyderabad's pharmaceutical software exporters maintain FDA-aligned documentation repositories.
Test Management Software Market Competitive Environment
The competitive structure tilts toward specialized SaaS platforms with deep ecosystem integration capabilities. Vendor concentration remains moderate, with tier-one incumbents defending enterprise contracts through compliance certification bundles while mid-scale challengers capture share via consumption-based pricing. Two strategic archetypes dominate: API-native pipeline specialists and governance-ready regulated sector platforms. M&A activity targets CI/CD toolchain connectivity assets, while geographic expansion focuses on EU sovereign cloud zones.
Within the ecosystem-anchored tier, SmartBear Software occupies a position leveraging API testing heritage, while Xray exemplifies native JIRA integration dominance across European development shops. PractiTest represents flexible SaaS delivery accommodating multi-jurisdictional audit requirements. These three anchors illustrate how compliance-ready architecture and toolchain embedding determine procurement preference in regulated verticals.
| Leading Market Players |
|---|
| TestRail |
| Zephyr |
| PractiTest |
| Xray |
| qTest |
| BrowserStack |
| Testmo |
| SmartBear Software |
| QMetry |
| Others |
Value Chain & Pricing Dynamics
EU AI Act algorithmic accountability mandates gate qualified supply for test management platforms serving financial services and healthcare sectors, restricting premium-tier pricing access to vendors with pre-certified compliance architectures. Procurement officers at Frankfurt tier-one banks and Stuttgart automotive OEMs now filter bids through governance-ready documentation requirements that compress margin pools for uncertified challengers.
Pricing Analysis
Consumption-based pricing anchored to test execution minutes is displacing seat-license models across mid-market SaaS vendors in the Netherlands and Nordics. Price differentiation separates ISO 27001-certified platforms from uncertified alternatives, with FDA-aligned medical device documentation commanding additional premiums. Pricing pressure stems from subscription fatigue among Series B software companies seeking cost alignment with release velocity. Mid-market buyers exhibit highest price sensitivity, while German defense contractors and Swiss private banks show minimal elasticity for air-gapped deployments.
Supply Chain Analysis
Freight costs for on-premise hardware installations remain negligible given software-dominant delivery, though data residency compliance adds localization overhead for EU sovereign cloud zones. Engineering talent concentrates in Germany, Ireland, and India, with Bangalore health-tech parks and Hyderabad pharmaceutical software exporters feeding specialized validation teams. Supply chain risk centers on single-source vulnerability for CI/CD pipeline connectors as Jenkins, GitLab, and Azure DevOps evolve incompatible API versions. Distribution runs through direct enterprise sales supplemented by Netherlands-based channel partners unbundling implementation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as incumbents pursue backward integration into compliance documentation templates to capture EMA software as medical device procurement cycles.
For Market Incumbents: To counter generative AI-assisted test generation tools deployed by London and Frankfurt tier-one banks, SmartBear Software and Xray must deepen native CI/CD pipeline embedding while acquiring ISO 13485 certification capabilities for healthcare verticals. Defensive consolidation should prioritize EMA-aligned documentation template libraries that accelerate diagnostic algorithm validation timelines. For New Entrants and Emerging Players: Series B SaaS companies in Edinburgh and Nordic capitals represent an underserved buyer archetype seeking consumption-based pricing without enterprise implementation overhead. White-space concentration sits with hybrid deployment configurations for German industrial IoT corridors requiring edge-localized test execution nodes. Go-to-market positioning should emphasize unbundled professional services separated from platform licensing fees. For Investors and Strategic Acquirers: M&A activity targeting CI/CD toolchain connectivity assets is the leading indicator that platform differentiation is shifting from core test management to pipeline embedding depth. Long-term viability favors vendors achieving concurrent ISO 27001 and SOC 2 Type II certifications that capture dual-compliance procurement preference. Acquisition targets should display pre-validated FDA and EMA documentation templates with established German notified body relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native CI/CD pipeline embedding satisfies Jenkins and GitLab compatibility requirements for DevOps-mature enterprises. |
| Acquisition of Specialist Firm | CI/CD toolchain connectivity assets accelerate pipeline embedding capabilities for regulated sector vendors. |
| Geographic Expansion | EU sovereign cloud zone presence satisfies GDPR and EU AI Act data localization mandates for German automotive suppliers. |
| Product Launch | Agentic AI test case generation tools compress manual scripting cycles for tier-one banks in sandbox environments. |
| Strategic Partnership | Channel partner networks in Netherlands and Nordics enable unbundled implementation service delivery. |
Study Parameters
Document review covered SEC filings from publicly traded software vendors, EU regulatory guidance repositories including EMA and EU AI Act implementation texts, and healthcare technology procurement databases, complemented by interviews with quality assurance directors at German automotive OEMs, compliance officers at Frankfurt financial institutions, platform engineers at CI/CD toolchain providers, and channel partners in Netherlands-based implementation consultancies. Secondary validation drew from FDA 510(k) submission databases, ISO certification registries, and enterprise SaaS pricing disclosure patterns. Bottom-up segment sizing triangulated against top-down market aggregation across deployment models and vertical applications.
Model outputs projected value expansion across cloud, SaaS, on-premise, and hybrid deployment architectures, segmented by end-user function spanning QA teams, software development organizations, IT departments, and project management offices. Integration complexity tiers and regional adoption patterns informed the analytical framework. CAGRs were derived from regression analysis against DevOps maturation indices and regulatory compliance spending trajectories, with inputs including medical device software proliferation rates and EU AI Act enforcement timelines.
Revisions become necessary when FDA validation requirements shift, EMA software as medical device guidance evolves, or hyperscaler API versioning disrupts CI/CD pipeline compatibility. Forecasts reflect documented assumptions regarding compliance certification adoption curves and enterprise cloud migration velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Meditation Management Apps Market
Software & Services
Global UIUX Software Market
Software & Services
Email Applications Market
Software & Services
Global Translation Software Market
Software & Services
Cemetery Management Software Market
Software & Services
Enterprise Mobility Software Market
Software & Services
Sales Force Automation Software Market
Software & Services
IT Services Market
Software & Services
Scanning and Migration Software Market
Software & Services
Clustering Software Market
Software & Services
Global Campaign Management Software Market
Software & Services
Global Java Web Frameworks Software Market
Software & Services
Global Polling Software Market
Software & Services
Global Plumbing Software Market
Software & Services
Full Screen Website Screenshot Software Market
Software & Services
Global Gamification Software Market