
 Email Applications Market | 2026-2036
Email Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Email Applications Market Analysis
Mid-market enterprises are unwinding the dominance of legacy on-premises email systems in favor of cloud-native alternatives. Gmail leverages its integration with Google Workspace to anchor productivity-suite bundling across education and startup segments. ProtonMail differentiates through end-to-end encryption architecture that appeals to privacy-conscious government and healthcare buyers. HubSpot competes by embedding email automation within broader CRM workflows, reducing standalone email procurement.
Email applications are software platforms that manage electronic message transmission, storage, and retrieval through protocols including SMTP, IMAP, and POP3, with modern iterations adding API-driven orchestration for bulk and triggered communications. Their primary commercial purpose is to enable person-to-person correspondence, marketing outreach, and automated transactional notifications at scale. Cloud-based deployment leads volume adoption due to lower infrastructure overhead and faster provisioning, while on-premises installations retain traction in sectors with strict data residency mandates. Security-focused feature sets command premium pricing, whereas basic automation modules have commoditized across mid-tier vendors.
FDA oversight of email systems in healthcare contexts, alongside HIPAA requirements for protected health information transmission, shapes product development for US-facing vendors. EMA-aligned data governance in Europe and GDPR consent-tracking obligations force architecture changes for marketing email platforms serving EU recipients. Stakeholders must monitor how AI Act risk-classification rules affect automated email content generation before committing to multi-year platform contracts.
Market Dynamics
Cloud-native email architectures are displacing on-premises infrastructure across enterprise segments, driven by zero-trust security mandates and API-first integration requirements that compress deployment timelines from quarters to weeks.
Growth Catalysts
- EU AI Act risk-classification:Automated content generation tools in email platforms face new compliance thresholds, creating demand for audit-ready systems among EU-facing enterprises.
- SMB cloud migration:Small and mid-sized businesses are abandoning legacy Exchange servers for subscription-based alternatives, reducing capital expenditure and IT headcount requirements.
- Zero-trust architecture adoption:Federal agencies and defense contractors mandate continuous authentication protocols, accelerating procurement of security-hardened email gateways.
Market Restraints
- Data residency mandates:Russia, China, and Turkey require local server presence, fragmenting vendor infrastructure and raising operational complexity.
- SMTP relay concentration:Three cloud providers control bulk transactional email routing, creating single-point-of-failure risk for high-volume senders.
- End-to-end encryption limitations:Key escrow requirements in Australia and UK impede deployment of zero-access architectures for government clients.
Strategic Opportunities
- Healthcare workflow integration:HIPAA-compliant email APIs that embed directly into EHR systems remain underdeveloped outside the United States.
- Carbon-aware infrastructure:EU Green Deal reporting obligations create preference for email platforms with renewable-energy data center certifications.
- Voice-to-email transcription:Converging NLP and edge computing enables hands-free email composition for field-service technicians and logistics operators.
Industry Challenges
- Legacy system integration:Mainframe-based email archives in financial services resist API extraction, prolonging hybrid-environment maintenance costs.
- Cryptographic agility:Post-quantum algorithm migration requires re-encryption of stored messages, demanding substantial compute resources and downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Email Applications Market |
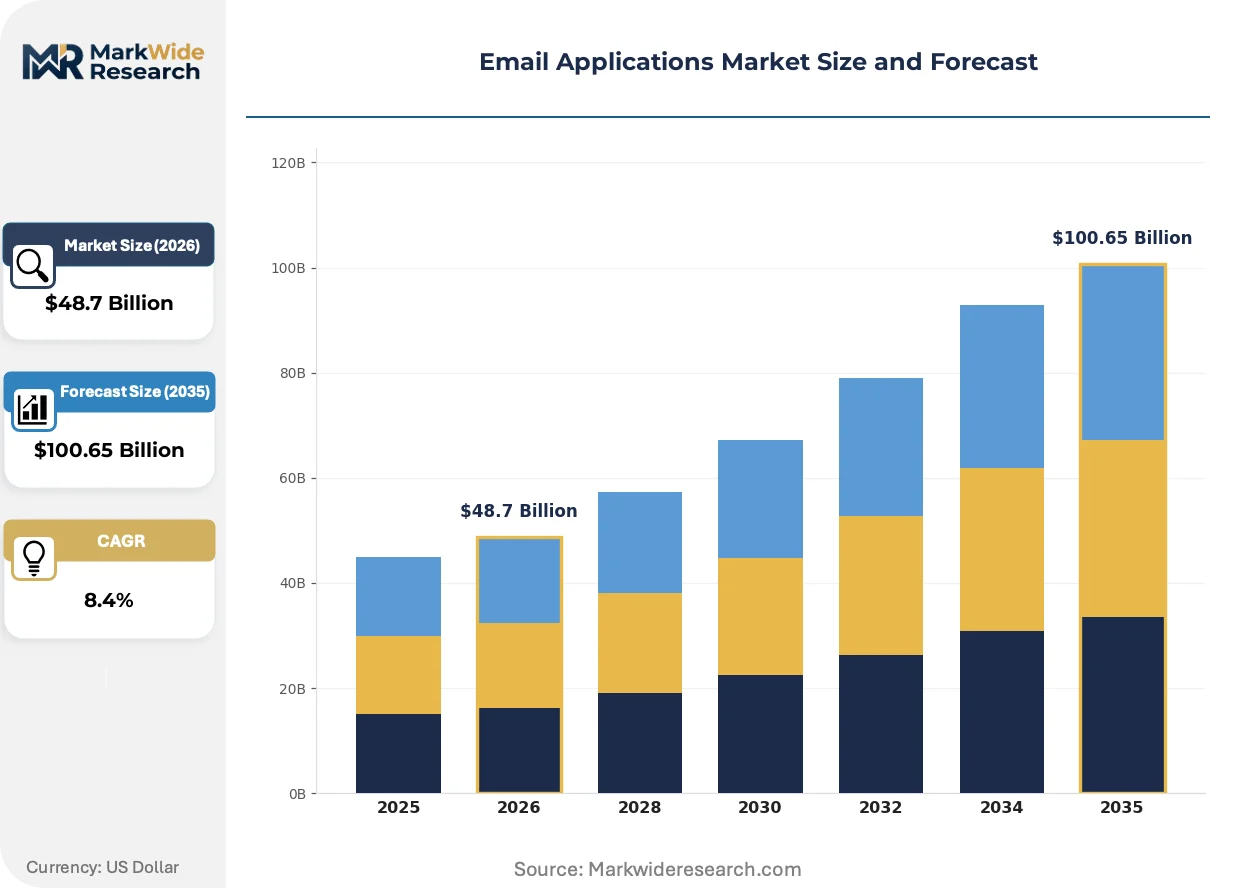
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Personal, Business, Marketing, Transactional Deployment Model: Cloud-based, On-premises, Hybrid, Web-based End User: Individuals, Small Enterprises, Large Enterprises, Government Feature Set: Automation, Analytics, Security, Integration |
| Companies Covered | Gmail, Apple Mail, Outlook, Yahoo Mail, Mailchimp, HubSpot, ProtonMail, Zoho Mail, Superhuman Mail, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Email Applications Market Emerging Trajectories
Artificial intelligence is embedding into every layer of email infrastructure, from predictive send-time optimization to real-time phishing detection, compressing the gap between raw communication utility and intelligent workflow orchestration.
Edge-deployed AI inference engines for spam and malware detection are miniaturizing hardware requirements for on-premises email security appliances. Regional banks and hospital networks with strict data localization rules are adopting these compact systems to retain message content within facility boundaries. The shift is miniaturizing the traditional secure email gateway form factor from rack-mounted servers to appliance units suitable for branch office closets.
GDPR Article 25 data-protection-by-design mandates are forcing email marketing platforms to rebuild consent-tracking architectures from session-based cookies to server-stored preference records. This regulatory pressure is elevating procurement weight toward vendors with EU-based engineering teams capable of rapid compliance iteration. German and French enterprise buyers now require proof of data-protection impact assessments before contract execution.
Subscription fatigue among mid-market IT buyers is compressing standalone email procurement into bundled productivity-suite decisions. Procurement committees increasingly evaluate email as a component of broader collaboration contracts rather than a discrete software category. This pattern is most pronounced in United States education technology budgets, where Google Workspace and Microsoft 365 bundling has nearly eliminated best-of-breed email evaluations.
Email Applications Market Segmentation
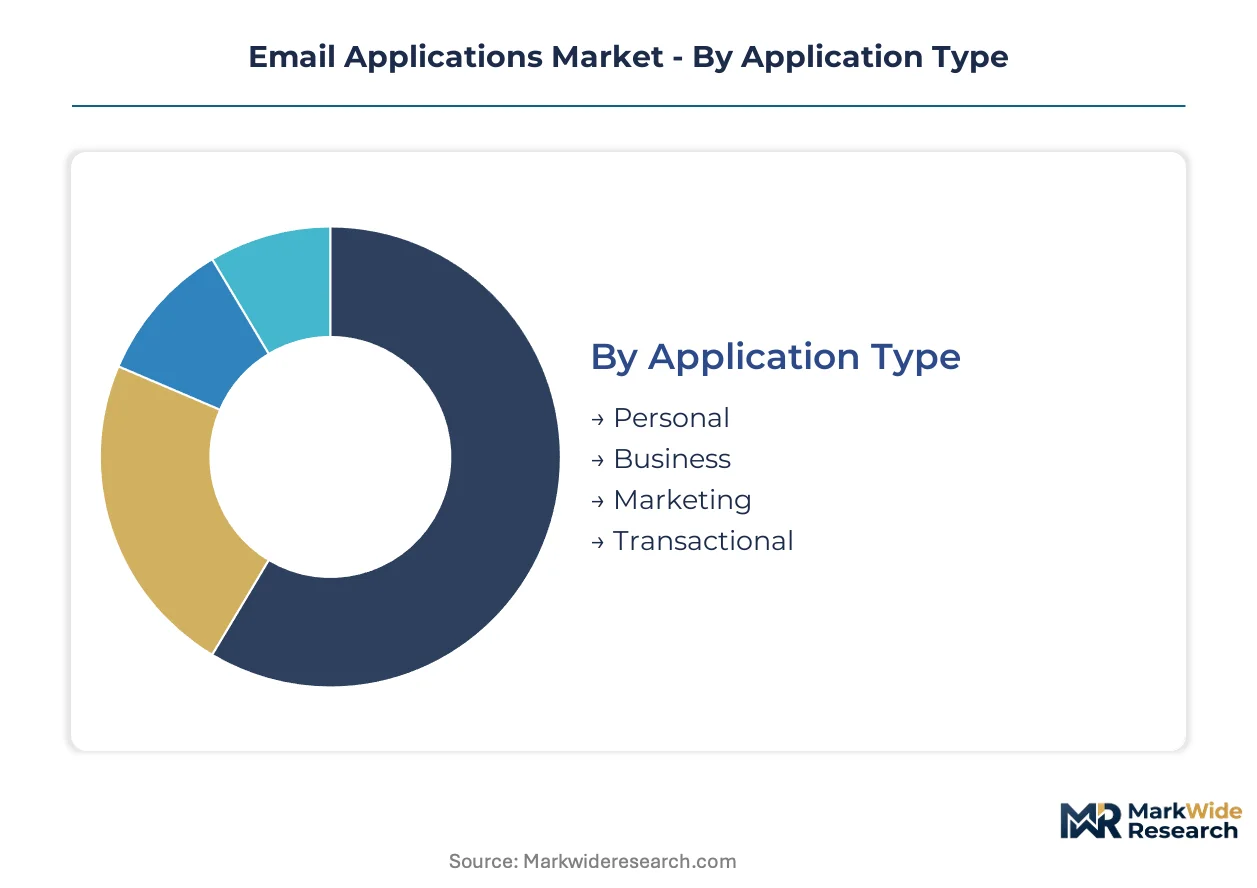
Email applications serve divergent operational requirements across personal correspondence, enterprise workflows, and automated system communications. Segmentation reveals how deployment constraints, user scale, and functional priorities reshape vendor product architecture and pricing architecture. Understanding these divisions exposes where platform specialization creates defendable margin pools versus commoditized competition.
Application Type:
Margin concentration tilts toward use cases requiring compliance certification and API throughput guarantees rather than basic send-receive functionality.
- Business:Enterprise-grade platforms supporting SMTP/IMAP orchestration with SLA-backed uptime commitments. Procurement concentrates among US federal contractors and EU-regulated financial institutions where audit trails and retention policies command 40-60% price premiums over consumer alternatives.
- Transactional:High-volume automated notification systems for e-commerce order confirmations, password resets, and shipping alerts. Demand clusters with digital-native retailers and fintech platforms in Germany, the United Kingdom, and Singapore where millisecond delivery latency directly impacts conversion metrics.
- Personal:Individual correspondence with advertising-supported or freemium monetization. Gmail and Outlook dominate through ecosystem lock-in rather than feature differentiation.
- Marketing:Campaign orchestration with A/B testing, segmentation, and deliverability optimization. HubSpot and Mailchimp compete through CRM integration depth rather than standalone email capability.
The dominant share belongs to Business applications, while Transactional is closing the gap fastest as real-time commerce infrastructure expands.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises installations from operational-expense cloud subscriptions, with hybrid configurations capturing price-sensitive regulated entities.
- Cloud-based:Multi-tenant SaaS architectures with automatic scaling and zero infrastructure maintenance. Google Workspace and Microsoft 365 anchor procurement among US education systems and mid-market professional services firms seeking rapid provisioning without IT headcount expansion.
- Hybrid:Split architectures retaining sensitive message storage on-premises while routing through cloud gateways. German automotive manufacturers and French healthcare networks adopt this model to satisfy GDPR data-localization requirements without sacrificing mobile access.
- On-premises:Dedicated server installations with full administrative control. Russian banks and Turkish government agencies mandate this configuration under national data sovereignty laws that prohibit cross-border message transit.
- Web-based:Browser-accessible interfaces without native application installation. Developing-market small enterprises and gig-economy workers in India and Brazil favor this lightweight access mode.
Cloud-based deployment holds the revenue majority, though Hybrid configurations are expanding most quickly as data residency enforcement tightens across the European Union.
End User:
Customer type determines feature bundling depth, with government and large enterprise segments demanding security hardening that smaller entities reject as cost-prohibitive.
- Large Enterprises:Global organizations with 10,000-plus seats requiring identity federation, e-discovery, and advanced threat protection. US defense contractors and pharmaceutical multinationals drive procurement of FedRAMP-authorized and HIPAA-aligned platforms with dedicated customer success management.
- Government:Federal, state, and municipal agencies with classified or sensitive communications mandates. The US Department of Defense and UK Cabinet Office specify zero-trust architecture compliance and domestic data center presence as non-negotiable requirements.
- Small Enterprises:Organizations with under 500 employees prioritizing cost predictability over customization. Subscription fatigue is compressing standalone email evaluations into bundled productivity-suite decisions.
- Individuals:Single-user accounts with basic storage and mobile synchronization needs. Monetization relies on advertising or premium tier upselling rather than direct subscription.
Large Enterprises contribute the greatest revenue per seat, yet Government verticals are gaining share fastest as zero-trust mandates proliferate through NATO-aligned procurement standards.
Feature Set:
Technology maturity separates commoditized automation modules from premium security and integration capabilities that retain pricing power.
- Security:End-to-end encryption, phishing detection, data loss prevention, and post-quantum cryptographic preparation. ProtonMail and Tutanota capture privacy-conscious segments in Switzerland, Germany, and Nordic countries where GDPR enforcement creates preference for zero-access architectures.
- Integration:API connectivity with CRM, ERP, and collaboration platforms. Salesforce-embedded email workflows and Slack notification routing command implementation fees that standalone email vendors cannot replicate.
- Automation:Triggered sequences, drip campaigns, and behavioral routing. This capability has commoditized across mid-tier vendors with minimal differentiation.
- Analytics:Open-rate tracking, engagement scoring, and deliverability diagnostics. Marketing-focused platforms bundle this as table stakes rather than premium upsell.
Security features command the highest margin premiums, while Integration capabilities are climbing fastest as API-first architecture becomes standard for enterprise software procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based cloud providers export email infrastructure services to enterprises across Germany, the United Kingdom, and Japan, while EU data localization rules redirect intra-regional traffic toward domestic hosting centers.
United States
Federal agencies and defense contractors drive procurement of zero-trust email gateways with FedRAMP authorization. HIPAA requirements from the FDA reshape product development for healthcare-facing vendors. The Washington DC-to-Boston corridor concentrates security-cleared engineering teams serving classified communications mandates.
Germany
Automotive manufacturers and industrial Mittelstand firms demand GDPR-compliant hybrid deployments with on-premises message retention. The EU AI Act risk-classification rules force audit-ready architectures for automated content generation. Stuttgart and Munich anchor engineering clusters developing data-protection-by-design email systems.
United Kingdom
Financial services firms in the City of London require e-discovery and retention capabilities aligned with FCA record-keeping rules. Key escrow requirements under national security legislation impede zero-access encryption deployment for government clients. The Thames Valley corridor hosts cybersecurity vendors adapting to post-Brexit data transfer frameworks.
Japan
Large enterprises prioritize integration with legacy groupware systems and local ERP platforms. METI guidelines on data governance influence cloud migration timelines for manufacturing conglomerates. Tokyo and Osaka metropolitan areas concentrate demand for bilingual email automation serving regional headquarters operations.
India
Digital-native startups and IT services exporters drive cloud-based email adoption for cost predictability. TRAI regulations on data localization intersect with RBI guidelines for fintech communications. Bangalore and Hyderabad clusters generate demand for API-first email orchestration embedded in SaaS product workflows.
Email Applications Market Vendor Landscape
Player mix skews toward productivity-suite bundlers with adjacent collaboration tools, creating a tiered structure where standalone security specialists occupy premium niches. The competitive terrain separates consolidated platform vendors from privacy-focused encryption architects and marketing-automation embedders. Dominant competitive moves include API-first integration expansion and zero-trust security hardening for regulated verticals.
Within the productivity-suite tier, Gmail and Outlook exemplify ecosystem-lock-in strategies that compress standalone email procurement into broader collaboration contracts. ProtonMail occupies a position among privacy-architecture specialists serving GDPR-sensitive European enterprises and healthcare compliance buyers. These three anchors demonstrate how vendor archetypes map to divergent customer priorities around convenience, integration depth, and cryptographic assurance.
| Leading Market Players |
|---|
| Gmail |
| Apple Mail |
| Outlook |
| Yahoo Mail |
| Mailchimp |
| HubSpot |
| ProtonMail |
| Zoho Mail |
| Superhuman Mail |
| Others |
Supply Flow & Price Mechanics
Subscription-based capacity reservation contracts lock enterprise buyers into multi-year SaaS commitments that stabilize vendor revenue visibility while constraining switching flexibility for regulated healthcare and government segments. These arrangements tether pricing predictability to data residency guarantees and FedRAMP authorization tiers that fragment procurement committees across compliance-sensitive verticals.
Pricing Analysis
Current-generation cloud-native platforms command 40-60% premiums over prior-generation on-premises licenses, while next-generation AI-embedded orchestration tools are pricing at experimental value-based models. The dominant structure stratifies across premium FedRAMP-authorized tiers, standard GDPR-compliant mid-market bundles, and economy freemium personal tiers. Price differentiation rests on certification grade and API throughput volume rather than core send-receive functionality. Cost compression in the standard tier is intensifying because HubSpot and Google Workspace bundling collapses standalone email procurement into broader collaboration contracts. Small enterprises exhibit highest price sensitivity, while US defense contractors accept premium positioning for zero-trust architecture mandates.
Supply Chain Analysis
The United States and Ireland anchor hyperscale data center infrastructure for cloud-native email platforms, while Germany and Switzerland host privacy-architecture specialists serving GDPR-sensitive European enterprises. Raw material dependencies center on semiconductor components for edge-deployed security appliances, renewable energy certifications for EU Green Deal compliance, and cryptographic hardware modules for zero-access encryption. Single-source vulnerability concentrates in SMTP relay routing where three cloud providers control bulk transactional delivery. Distribution runs through direct enterprise sales teams for regulated verticals and self-service web provisioning for mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as zero-trust mandates and data residency rules splinter procurement into compliance-specialized niches that resist platform consolidation. GDPR Article 25 obligations and EU AI Act risk-classification create defendable positioning for vendors with EU-based engineering capacity.
For Market Incumbents: Fortify API-first integration depth against HubSpot and Salesforce embedment strategies that collapse email into CRM workflows. Prioritize FedRAMP authorization investment for US federal contractor retention, and deepen zero-trust architecture certification to defend against ProtonMail privacy encroachment in European healthcare segments. Channel control through managed service provider networks offers defensive leverage against direct-to-enterprise disintermediation. For New Entrants and Emerging Players: Lead with HIPAA-compliant email APIs embedded directly into EHR systems, a white-space target underdeveloped outside US hospital networks. German automotive Mittelstand firms present penetrable demand for hybrid deployment models satisfying GDPR data-localization without sacrificing mobile workforce access. Go-to-market positioning through regional system integrators with existing healthcare credentials accelerates trust formation faster than direct sales buildout. For Investors and Strategic Acquirers: The market sits at a compliance-divergence phase that favors privacy-architecture specialists with EU engineering presence and zero-access encryption IP. Long-term viability over the coming decade hinges on post-quantum cryptographic agility and carbon-aware infrastructure certification. Acquisition target archetype: mid-scale vendors with FedRAMP authorization progress and established German or French enterprise reference accounts. The signal to watch is EU AI Act enforcement intensity against automated content generation tools, which would accelerate audit-ready platform procurement and compress experimental vendor timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Certification | FedRAMP authorization unlocks US defense contractor procurement with 40-60% price premiums. |
| API-First Platform Integration | CRM embedment through Salesforce and HubSpot workflows collapses standalone email evaluations. |
| Post-Quantum Cryptographic Migration | Re-encryption of stored messages demands compute resources that favor well-capitalized incumbents. |
| Carbon-Aware Infrastructure Certification | EU Green Deal reporting obligations create preference for renewable-energy data center operations. |
| Healthcare EHR Workflow Embedment | HIPAA-compliant APIs integrated directly into Epic and Cerner systems capture hospital procurement. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC SaaS vendor filings, hyperscaler capex disclosures, and EU regulatory guidance documents. Primary interviews engaged CTOs at mid-market enterprises, IT procurement officers in regulated healthcare networks, platform engineers at email infrastructure vendors, and integration specialists at CRM ecosystem partners. Secondary validation drew from FDA 510(k) submissions for healthcare-facing tools, EMA data governance guidance, FedRAMP authorization databases, and GDPR enforcement case records. Bottom-up seat-count modeling triangulated against top-down addressable market sizing across deployment models and vertical segments.
Segmentation dimensions modeled include deployment architecture, organization scale tier, vertical regulatory sensitivity, integration complexity level, and regional data residency pattern. CAGR derivation applied historical migration velocity from on-premises Exchange to cloud-native alternatives, weighted by zero-trust mandate acceleration among NATO-aligned government procurement frameworks. Industry-specific inputs incorporated SMTP relay volume telemetry and API call frequency benchmarks from e-commerce and fintech platform disclosures.
The analysis sits within stated boundaries; outcomes outside sustained EU AI Act enforcement, stable hyperscaler infrastructure investment, and unfragmented SMTP routing concentration would require recalibration. Forecasts assume continuity in current regulatory trajectories and cloud migration patterns. Recalibration cycles align with material shifts in zero-trust mandate proliferation, post-quantum algorithm standardization, and EU Green Deal reporting obligation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Blogger Outreach Software Market
Software & Services
HR Tech Market
Software & Services
Radio Propagation Software Market
Software & Services
Chatbot Builder Software Market
Software & Services
France Digital Marketing Software Market
Software & Services
Trading Software Market
Software & Services
Backend-As-A-Service Market
Software & Services
RFP Software Market
Software & Services
Global Retail Inventory Management Software Market
Software & Services
Sales Performance Management (SPM) Software Market
Software & Services
Middle East and Africa Automotive Software Market
Software & Services
Global Permit Management Software Market
Software & Services
Global Professional Service Automation (PSA) Software Market
Software & Services
Global Neural Network Software Market
Software & Services
API Testing Market
Software & Services
Library Management Software Market