
 Temporary Road Covers Market | 2026-2036
Temporary Road Covers Market Size, Share, and Industry Trends Forecast 2026-2036
Temporary Road Covers Market Analytics
Equipment rental channels for temporary road covers is narrowing as national rental fleets consolidate specification standards. United Rentals controls North American fleet deployment through centralized procurement protocols. Oxford Plastic Systems leverages composite engineering expertise to dominate specification-driven municipal tenders. Signature Systems anchors event-sector demand with rapid-deployment modular platforms.
Temporary road covers are engineered surface protection panels, typically fabricated from HDPE, composite resins, or steel alloys, designed to distribute vehicular and pedestrian loads over excavations, trenches, or sensitive subgrade during infrastructure work. Composite covers lead product-type demand where corrosion resistance and manual handling requirements favor non-metallic construction. HDPE material grades capture expanding share in utility applications due to dielectric properties and chemical inertness. Contractor end-users represent the deepest margin pool through recurring fleet replenishment cycles.
The EU Construction Products Regulation mandates CE marking and declared performance values for temporary works equipment across member states, while OSHA trench safety standards in the United States enforce protective system deployment in excavation zones. Germany's Worksite Safety Ordinance and the United Kingdom's Health and Safety Executive guidance notes further calibrate load-rating verification protocols. Stakeholders must monitor evolving composite recycling mandates and polymer content disclosure rules as circular economy frameworks extend into temporary infrastructure procurement criteria.
Market Dynamics
Municipal procurement departments are consolidating vendor qualification criteria around CE-marked composite platforms, compressing supplier margins while elevating specification-engineering capabilities as the primary competitive barrier.
Growth Catalysts
- EU Construction Products Regulation:CE marking mandates for temporary works equipment are standardizing performance declarations across member states, creating uniform demand for certified composite and HDPE covers in utility corridors.
- Urban excavation frequency:Aging water and gas distribution networks in Germany, France, and the United Kingdom are driving recurring deployment of rapid-installation road protection systems.
- Composite resin formulations:Advanced fiber-reinforced polymers with corrosion resistance and manual-handling advantages are displacing steel alloys in coastal and chemically exposed environments.
Market Restraints
- Petrochemical feedstock volatility:HDPE resin prices fluctuate with crude oil benchmarks, compressing margins for manufacturers without long-term supply contracts.
- Load-bearing certification complexity:Germany's Worksite Safety Ordinance and divergent national test protocols create fragmented compliance costs for pan-European suppliers.
- Steel cover residual value:Scrap metal recovery economics sustain competitive pressure from recyclable metal alternatives in heavy-haul applications.
Strategic Opportunities
- Circular economy procurement criteria:France's extended producer responsibility frameworks and polymer content disclosure rules are creating first-mover advantage for recyclable composite platforms.
- Event infrastructure rental channels:Modular rapid-deployment systems are penetrating music festivals and sporting venues as secondary revenue streams beyond utility contracting.
- Dielectric HDPE grades:Electrical inertness properties are opening transmission corridor applications where metallic covers pose grounding hazards.
Industry Challenges
- Composite recycling infrastructure:Fiber-resin separation capabilities remain concentrated in specialized facilities, creating end-of-life liability exposure for fleet operators.
- Load-rating verification timelines:Third-party testing laboratory capacity constraints in the United Kingdom are extending product launch cycles for new cover geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temporary Road Covers Market |
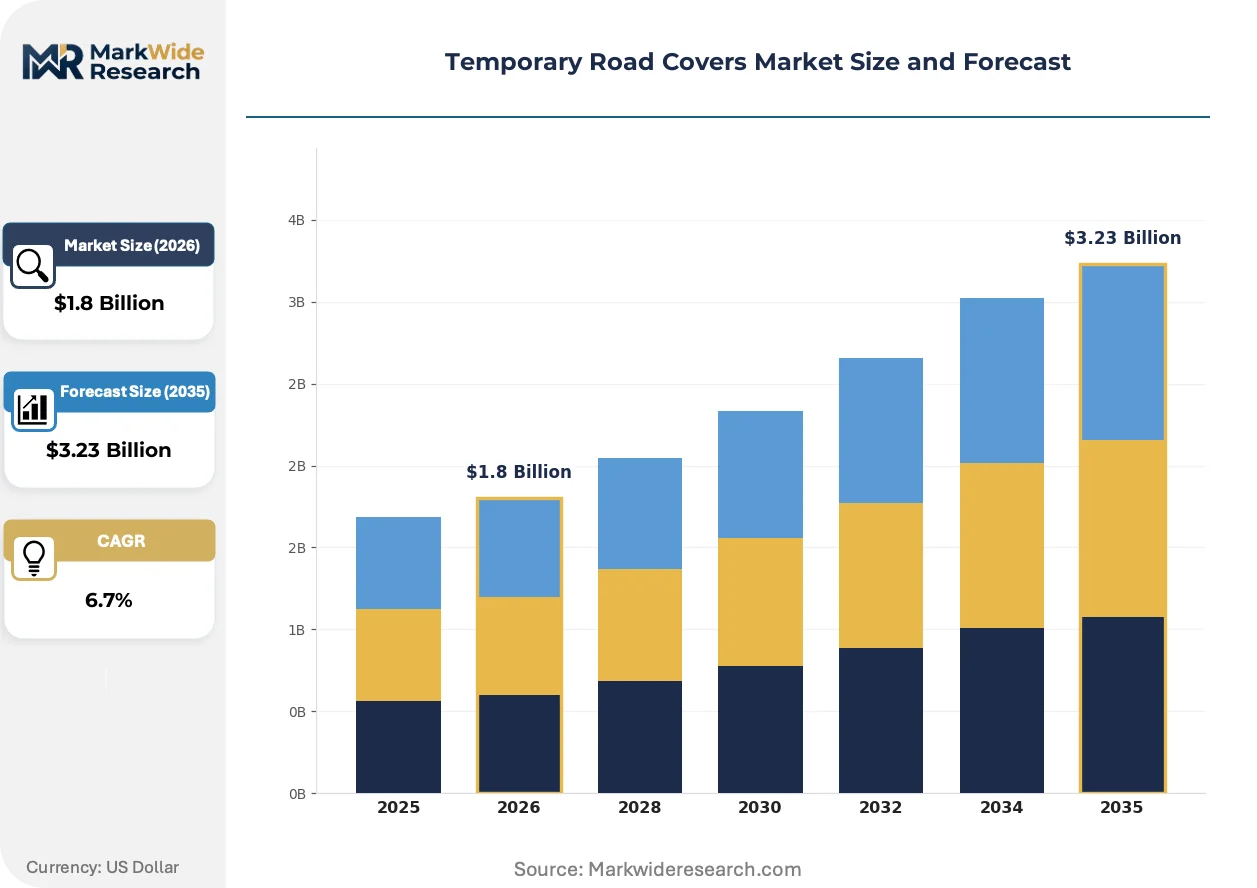
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Covers, Plastic Covers, Steel Covers, Rubber Covers Application: Construction Sites, Road Maintenance, Events, Utilities End User: Contractors, Event Organizers, Municipalities, Utility Providers Material: HDPE, PVC, Steel, Aluminum |
| Companies Covered | Oxford Plastic Systems, Fibrelite, Signature Systems, TPA Portable Roadways, United Rentals, Prime Composites Australia, Crescent Foundry, Ducast Factory, Polieco Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temporary Road Covers Market Evolving Landscape
Material science advances and procurement digitization are restructuring how temporary road protection systems are specified, financed, and deployed across infrastructure value chains.
Modular composite platforms are migrating from steel-reinforced concrete alternatives in municipal trench applications. German utility contractors are specifying these systems for corrosion resistance in chemically aggressive soil conditions. The technology is migrating from premium niche positioning toward standard procurement catalogs as lifecycle cost models gain traction with public works departments.
REACH polymer registration requirements and the EU Green Deal's embodied carbon disclosure mandates are reshaping material selection protocols. Composite manufacturers must now document supply chain chemical footprints and recyclability pathways to maintain CE marking validity. Municipal tender boards in the Netherlands and Belgium are weighting environmental product declarations alongside mechanical performance in award criteria.
Rental fleet standardization is consolidating buyer power around national procurement frameworks. United Rentals and European equivalents are deploying centralized specification protocols that disqualify non-certified suppliers from multi-year framework agreements. This concentration is most visible in North American utility corridors where consolidated rental channels now dictate cover geometry and load-rating tiers to manufacturers.
Temporary Road Covers Market Segmentation
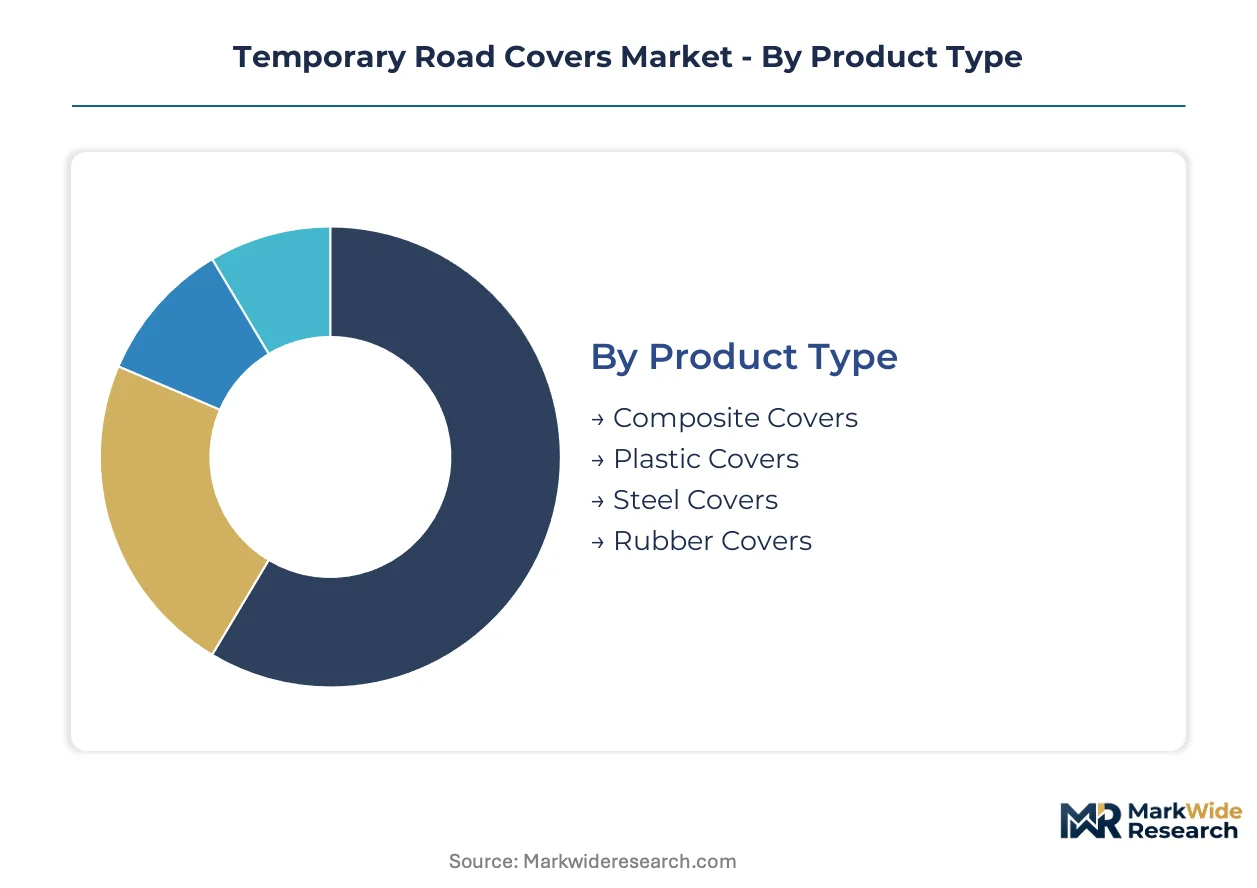
Segmentation in temporary road covers reveals how material specifications, deployment contexts, and procurement authority reshape competitive positioning. Each dimension exposes distinct margin structures and compliance burdens that determine supplier viability across infrastructure value chains.
Product Type:
Cost tier differentiation separates premium-engineered systems from commodity alternatives based on load-bearing certification and lifecycle durability.
- Composite Covers:Fiber-reinforced polymer matrices deliver corrosion resistance and manual-handling advantages in chemically aggressive environments. Municipal procurement in Germany and France concentrates specification-driven demand where CE marking and declared performance values are mandatory under EU Construction Products Regulation.
- Plastic Covers:Injection-molded HDPE and PVC formulations dominate high-frequency utility maintenance corridors. Dielectric properties open transmission corridor applications where metallic covers pose grounding hazards, particularly in Netherlands and Belgium distribution networks.
- Steel Covers:Cast and fabricated steel alloys retain foothold in heavy-haul construction zones where scrap metal recovery economics sustain residual value propositions.
- Rubber Covers:Elastomeric compounds serve temporary pedestrian pathways and noise-sensitive event infrastructure with lower structural load requirements.
Composite covers command the established base. The steepest expansion runs through plastic covers.
Application:
Deployment context dictates installation speed requirements, surface load specifications, and regulatory oversight intensity.
- Construction Sites:Trench protection systems under OSHA and national worksite safety ordinances require rapid-installation platforms with verified load distribution. German contractors specify modular composite systems for excavation corridors in urban utility networks.
- Road Maintenance:Highway agencies deploy temporary surfaces during resurfacing and bridge deck repairs. UK Health and Safety Executive guidance notes calibrate load-rating verification protocols for traffic-bearing applications.
- Events:Music festivals and sporting venues demand rapid-deployment modular platforms with aesthetic surface finishes. Rental fleet standardization concentrates buyer power around national procurement frameworks.
- Utilities:Water, gas, and electrical distribution operators represent recurring fleet replenishment cycles with deepest margin pools. Aging infrastructure in France and United Kingdom drives excavation frequency for network rehabilitation.
Construction sites anchor volume concentration. Events deliver the fastest margin expansion trajectory.
End User:
Customer type determines procurement sophistication, specification authority, and replacement cycle predictability.
- Contractors:Fleet operators prioritize rental availability and standardized geometries that integrate with existing deployment equipment. Centralized procurement protocols at national rental chains disqualify non-certified suppliers from multi-year framework agreements.
- Municipalities:Public works departments consolidate vendor qualification criteria around CE-marked composite platforms with environmental product declarations. Netherlands and Belgium tender boards weight embodied carbon disclosure alongside mechanical performance.
- Utility Providers:Electrical transmission and distribution operators specify dielectric-grade HDPE covers for corridor maintenance where metallic alternatives create grounding risks.
- Event Organizers:Secondary revenue stream buyers prioritize rapid installation logistics and surface aesthetics over structural certification depth.
Municipalities drive specification standardization. Contractors generate the highest replenishment frequency.
Material:
Raw material selection governs dielectric performance, chemical resistance, recyclability pathways, and exposure to petrochemical feedstock volatility.
- HDPE:High-density polyethylene grades capture expanding share in utility applications due to electrical inertness and chemical resistance. REACH polymer registration requirements and EU Green Deal mandates force supply chain chemical footprint documentation.
- Steel:Alloy formulations retain position in heavy-haul temporary roadways where load concentration exceeds polymer structural limits. Scrap recovery infrastructure sustains circular economy positioning.
- PVC:Lower-cost thermoplastic alternative for light-duty pedestrian and event applications with reduced load-bearing requirements.
- Aluminum:Lightweight metallic option for rapid-manual-deployment scenarios where corrosion resistance and weight reduction justify premium positioning over steel.
HDPE dominates new specification adoption. Steel retains the replacement base in heavy-duty segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr industrial corridor generates sustained demand for temporary road covers as aging gas distribution networks undergo systematic rehabilitation. The country's dense utility infrastructure and strict worksite safety protocols create a template for specification-driven procurement across adjacent markets.
Germany
Urban excavation frequency in Berlin, Munich, and Hamburg drives recurring fleet deployment for water and gas network maintenance. The Worksite Safety Ordinance mandates load-bearing certification that elevates composite platform specifications in municipal tenders. Bavarian utility contractors specify fiber-reinforced polymer systems for corrosion resistance in chemically aggressive soil conditions.
United Kingdom
Thames Water and National Grid rehabilitation programs generate concentrated demand in Greater London and the Southeast. Health and Safety Executive guidance notes calibrate load-rating verification protocols for traffic-bearing applications. Manchester and Birmingham utility corridors see accelerated composite cover adoption as local authorities consolidate vendor qualification criteria.
France
Île-de-France utility networks drive procurement volume for rapid-installation trench protection systems. Extended producer responsibility frameworks under circular economy mandates create first-mover advantage for recyclable composite platforms. Lyon and Marseille public works departments weight environmental product declarations alongside mechanical performance in award criteria.
Netherlands
Amsterdam-Rotterdam-The Hague utility corridors specify dielectric-grade HDPE covers for electrical distribution maintenance where metallic alternatives pose grounding hazards. REACH polymer registration requirements force supply chain chemical footprint documentation from manufacturers. Dutch tender boards integrate embodied carbon disclosure into procurement scoring matrices.
United States
OSHA trench safety standards enforce protective system deployment across Texas, California, and Northeast utility corridors. United Rentals controls fleet deployment through centralized procurement protocols that dictate cover geometry and load-rating tiers. Chicago and Atlanta metropolitan areas concentrate contractor demand for rapid-deployment modular platforms.
Temporary Road Covers Market Competitive Landscape
On the supply side, the industry is consolidating around specification-engineering capabilities as the primary competitive barrier. Municipal procurement departments compress supplier margins while elevating CE marking and declared performance values as mandatory entry criteria. Three archetypes dominate: composite engineering specialists, rental fleet operators with centralized procurement protocols, and foundry-based metal fabricators serving heavy-haul construction zones. Strategic moves concentrate on capacity expansion in fiber-reinforced polymer formulations and geographic diversification into event infrastructure rental channels.
Among UK-based composite engineering specialists, Oxford Plastic Systems exemplifies the specification-driven municipal tender archetype through its fiber-reinforced polymer expertise. Signature Systems occupies a position within rapid-deployment modular platforms for event-sector applications. United Rentals anchors the rental fleet consolidation vector in North American utility corridors through centralized procurement protocols that disqualify non-certified suppliers from multi-year framework agreements.
| Leading Market Players |
|---|
| Oxford Plastic Systems |
| Fibrelite |
| Signature Systems |
| TPA Portable Roadways |
| United Rentals |
| Prime Composites Australia |
| Crescent Foundry |
| Ducast Factory |
| Polieco Group |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock volatility determines both pricing tier spreads and supply chain shape in temporary road covers, as HDPE resin fluctuations compress margins for manufacturers lacking long-term supply contracts while forcing geographic diversification of polymer sourcing.
Pricing Analysis
Volume-discount tiering structures separate municipal framework agreements from spot procurement, with CE-marked composite platforms commanding premium positioning against uncertified alternatives. Price differentiation rests on load-bearing certification grade and environmental product declaration weighting in Dutch and Belgian tender scoring. Cost compression in standard-grade HDPE covers is intensifying because rental fleet consolidation concentrates buyer power around national procurement protocols. Contractors exhibit highest price sensitivity due to recurring fleet replenishment cycles, while municipalities prioritize specification compliance over unit cost.
Supply Chain Analysis
Export-control regime angles on fiber-reinforced polymer technology remain limited, though REACH polymer registration requirements function as regulatory chokepoints constraining material flows into EU markets. Manufacturing concentrates in Germany, the United Kingdom, and the Netherlands for composite engineering, with HDPE resin production anchored in Belgium and the Netherlands. Raw material dependencies center on glass fiber rovings, epoxy resin systems, and high-density polyethylene pellets. Single-source vulnerability runs through specialized third-party testing laboratories in the United Kingdom extending product launch cycles. Distribution runs through consolidated rental fleet operators and direct municipal tender channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated rental fleets and centralized municipal procurement frameworks, compressing supplier margins while elevating specification-engineering capabilities as the primary competitive barrier.
For Market Incumbents: Harden specification authority by deepening backward integration into fiber-reinforced polymer formulation, securing captive supply of corrosion-resistant resin systems against petrochemical volatility. Fortify CE marking validity through preemptive REACH compliance documentation and embodied carbon disclosure protocols ahead of EU Green Deal mandate expansion. Channel control through multi-year framework agreements with United Rentals and European rental equivalents locks out non-certified competitors.
For New Entrants and Emerging Players: Pursue event infrastructure rental channels as white-space targets, where rapid-deployment modular platforms face lower certification barriers and aesthetic surface finishes command premium positioning. Penetrate French and Belgian municipal markets through circular economy procurement criteria, leveraging recyclable composite platforms to capture first-mover advantage under extended producer responsibility frameworks. Go-to-market angle centers on environmental product declaration weighting in tender scoring matrices.
For Investors and Strategic Acquirers: Germany's Worksite Safety Ordinance load-bearing certification tightening reshapes the acquisition landscape by elevating third-party testing infrastructure and specification-engineering talent as scarce assets. Long-term viability favors composite engineering specialists with demonstrated CE marking pathways and municipal tender track records. Acquisition target archetype: mid-cap fiber-reinforced polymer formulators with established utility contractor relationships. Signal to monitor: polymer content disclosure rule adoption rates across EU member states.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive supply of corrosion-resistant polymers insulates margins from HDPE price volatility. |
| CE Marking Pathway Investment | Declared performance values unlock access to consolidated municipal procurement frameworks. |
| Recyclable Composite Platform Development | Circular economy positioning captures French extended producer responsibility tender preferences. |
| Third-Party Testing Laboratory Partnership | UK laboratory capacity constraints create bottleneck for new product geometry launches. |
| Event Infrastructure Rental Channel Expansion | Music festival and sporting venue applications diversify revenue beyond utility contracting cycles. |
Research Methodology
Cross-validation between municipal procurement database analysis and rental fleet operator interviews anchors the qualitative findings in documented specification trends and deployment patterns. Primary fieldwork engaged utility maintenance directors, public works procurement officers, composite manufacturing plant managers, and third-party testing laboratory technical leads. Secondary sources encompassed EU Construction Products Regulation guidance documents, Health and Safety Executive technical notes, OSHA trench safety standards, and customs trade data on HDPE and glass fiber imports. Bottom-up unit economics triangulated against top-down infrastructure spending projections.
Calibration approaches linked historical procurement volumes to aging utility network rehabilitation schedules and urban excavation frequency trends across the analysis window. Segmentation dimensions modeled include material type, application context, end-user procurement authority, and regional regulatory framework clusters. CAGRs derived from slope-intercept fitting against infrastructure budget growth trajectories and fleet replacement cycle patterns. Industry-specific inputs incorporated dielectric-grade HDPE specification adoption rates and composite recycling infrastructure development timelines.
Sensitivities concentrate around petrochemical feedstock price trajectories, REACH polymer registration requirement amendments, and rental fleet consolidation pace. Forecasts reflect documented assumptions on infrastructure budget allocation shares and CE marking enforcement intensity. Material shifts in EU circular economy procurement mandate scope or composite fiber-resin separation technology breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Expandable Shelter Market
Construction and Engineering
Rivet Gun Market
Construction and Engineering
Asia Pacific Sanitaryware Market
Construction and Engineering
Germany HVAC Market
Construction and Engineering
Carbon Textile Reinforced Concrete Market
Construction and Engineering
Deburring Tool Market
Construction and Engineering
Industrial Ovens Market
Construction and Engineering
North America Industrial Duct for Dust Collection Market
Construction and Engineering
Fire Resistant Mortar Market
Construction and Engineering
Log Splitters Rental Market
Construction and Engineering
Low Clearance Loaders Market
Construction and Engineering
Rubber Tired Gantry (RTG) Crane Market
Construction and Engineering
Turkey Ceramic Tiles Market
Construction and Engineering
Push-Back Racking System Market
Construction and Engineering
Construction Aggregates Market
Construction and Engineering
Truck Mounted Loader Cranes Market