
 US Textile Processing Machinery Market | 2026-2036
US Textile Processing Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
US Textile Processing Machinery Market Insights
Technical textile industries is realigning procurement priorities toward automated finishing systems as defense and medical end-use contracts expand. Pellerin Milnor Corporation leverages its industrial laundry heritage to anchor high-capacity processing lines for technical fabric producers. Alliance Laundry Systems LLC sustains R&D intensity across CNC-controlled dyeing platforms. G.A. Braun Inc. specializes in thermal finishing equipment for specialty fabric applications in the Southeast manufacturing belt.
US Textile Processing Machinery encompasses mechanical and electromechanical systems engineered to transform raw fibers into finished textile substrates through specified tension, temperature, and chemical parameters, typically operating at speeds exceeding 1,000 meters per minute in continuous processing configurations. Spinning machines and finishing equipment command the dominant installed base, though knitting machines represent the fastest-growing category as seamless garment construction gains traction among apparel manufacturers. Automatic technology segments capture the deepest margin pools as labor scarcity across North Carolina and Georgia mills accelerates capital substitution for manual operations.
OSHA mandates machine guarding and noise exposure limits that elevate equipment compliance costs, while EPA effluent guidelines under the Clean Water Act restrict chemical discharge from dyeing and bleaching operations. The Department of Commerce enforces Buy American provisions on federal textile contracts that favor domestic machinery sourcing. Stakeholders must monitor how NHTSA technical fabric specifications for automotive airbag substrates redirect finishing equipment requirements toward precision coating capabilities.
Market Dynamics
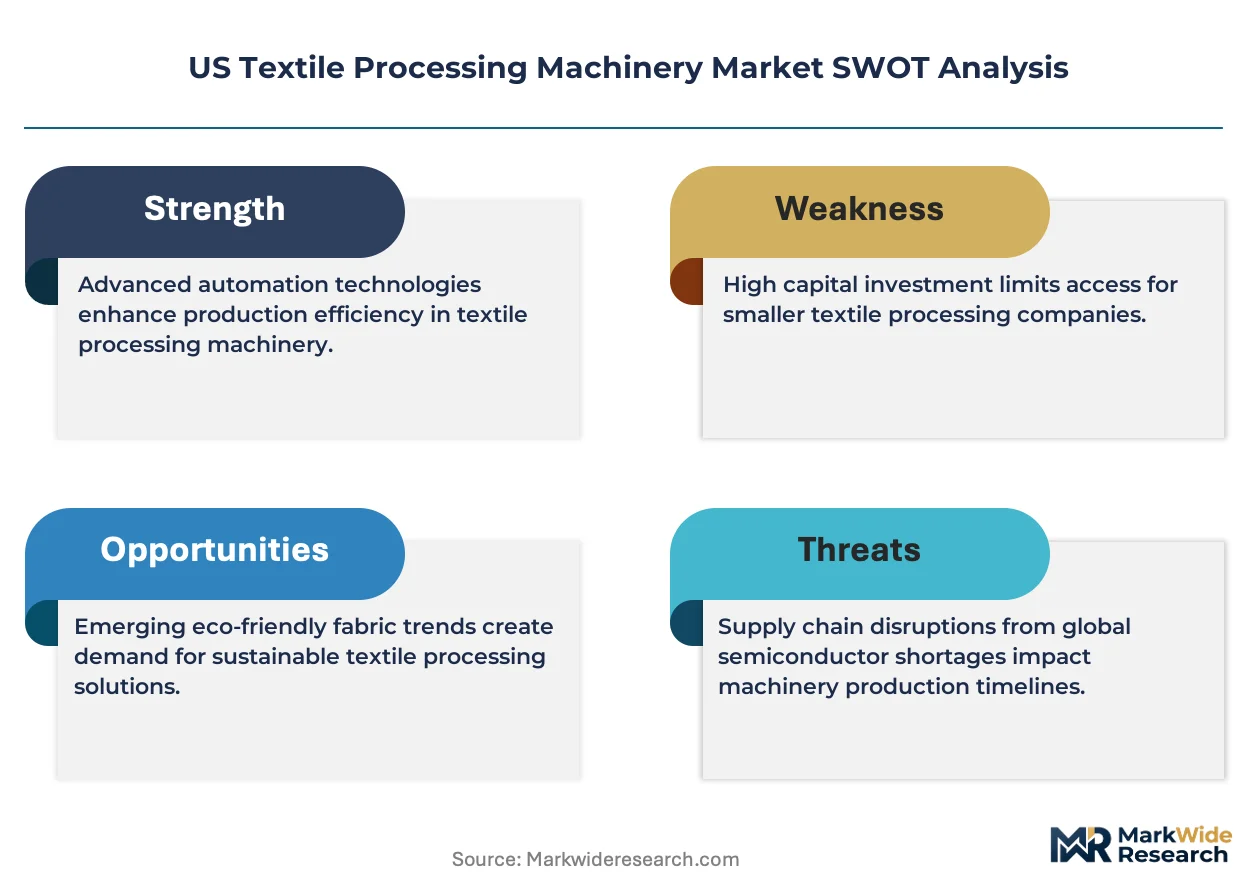
Domestic textile reshoring is compressing equipment replacement cycles as Southeast mills accelerate capital deployment to meet defense and medical contract specifications. OSHA machine guarding mandates and EPA effluent rules are simultaneously elevating compliance costs and reshaping supplier qualification criteria.
Growth Catalysts
- Defense procurement mandates:Department of Commerce Buy American provisions on federal technical textile contracts are redirecting machinery sourcing toward domestic OEM channels.
- EPA Clean Water Act enforcement:Tightening effluent guidelines on dyeing and bleaching operations are forcing equipment upgrades toward closed-loop water recycling systems.
- Carolina-Georgia manufacturing corridor:Concentrated technical textile investment across North Carolina, South Carolina, and Georgia is generating localized demand clustering for high-capacity finishing lines.
Market Restraints
- Specialized component supply concentration:Precision servo drives and CNC control modules for textile machinery concentrate among a limited supplier base in Germany and Japan.
- Steel alloy input volatility:Equipment frames and processing rollers require specialty stainless grades subject to commodity price swings.
- Technical labor scarcity:Electromechanical maintenance technicians with textile-specific expertise remain scarce across the Southeast manufacturing belt.
Strategic Opportunities
- Automotive airbag substrate specifications:NHTSA technical fabric standards are redirecting finishing equipment requirements toward precision coating capabilities.
- Seamless garment construction adoption:Apparel manufacturers are expanding circular knitting machine procurement for body-mapping athletic wear.
- IRA clean manufacturing incentives:Energy-efficient thermal finishing equipment qualifies for federal tax credits accelerating replacement demand.
Industry Challenges
- Multi-standard certification complexity:Equipment must simultaneously satisfy OSHA machine guarding, EPA emissions, and NHTSA material specifications extending validation timelines.
- Legacy system integration friction:New automated dyeing platforms face interoperability barriers with existing mill-wide SCADA infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Textile Processing Machinery Market |
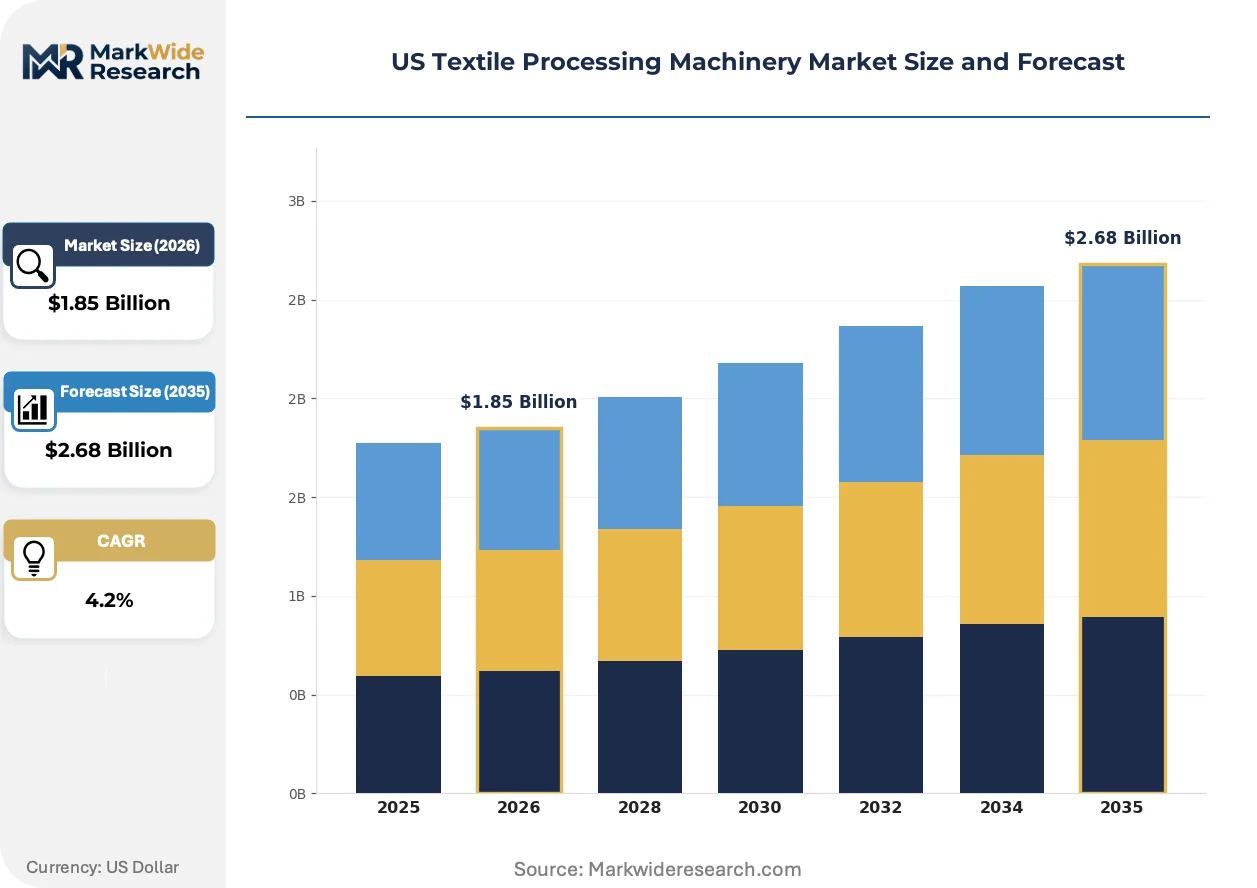
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spinning Machines, Weaving Machines, Knitting Machines, Finishing Equipment End User: Apparel Manufacturers, Home Textile Producers, Technical Textile Industries, Nonwoven Fabric Producers Technology: Automatic, Semi-Automatic, Manual, CNC Application: Woven Fabrics, Knitted Textiles, Nonwoven Materials, Specialty Fabrics |
| Companies Covered | G.A. Braun Inc., Pellerin Milnor Corporation, Alliance Laundry Systems LLC, Leonard Automatics, Wolfe Dye & Bleach Works Inc., Continental Girbau, B&C Technologies, Lapauw USA LLC, Kusters Calico, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Textile Processing Machinery Market Trends and Innovations
Continuous processing architectures are displacing batch configurations as technical textile producers chase throughput advantages. Digital thread control and predictive maintenance modules are embedding intelligence directly into finishing line operations.
Digital twin simulation platforms are expanding into textile processing equipment design and commissioning workflows. North Carolina-based technical fabric producers are adopting virtual commissioning to compress installation timelines for multi-million dollar finishing lines. This capability is expanding into aftermarket service contracts as OEMs monetize remote diagnostics.
OSHA machine guarding standards under 29 CFR 1910.212 are mandating interlocked safety enclosures on high-speed spinning and knitting equipment. Equipment retrofit costs are compressing margins for machinery refurbishers while favoring new equipment purchases. Georgia and South Carolina mills are prioritizing OEMs with integrated safety engineering capabilities.
Technical textile buyers are consolidating vendor relationships around full-line system integrators capable of single-source accountability. Discrete equipment purchasing through regional distributors is contracting as defense and medical contract holders demand unified performance guarantees. This consolidation is most visible across the Carolina Piedmont manufacturing cluster.
US Textile Processing Machinery Market Segmentation
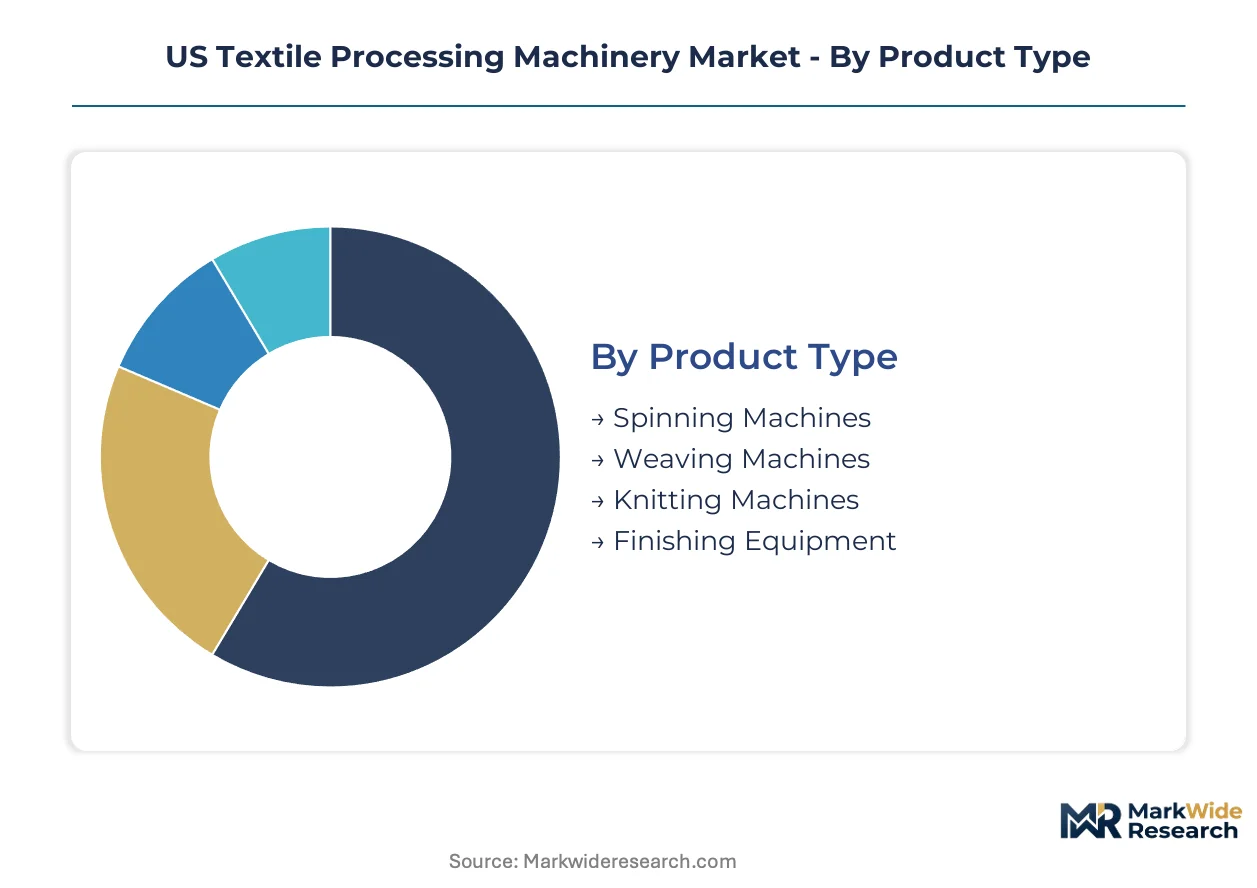
Segmentation in US textile processing machinery reveals how capital deployment priorities diverge across automation tiers and end-use specifications. Defense contractors and medical fabric producers are compressing procurement cycles for high-throughput systems while apparel manufacturers balance labor substitution against equipment payback periods.
Product Type:
Volume procurement concentrates in established mechanical systems while premium deployment targets electromechanical platforms with integrated digital controls.
- Spinning Machines:Ring spinning and open-end rotor systems transform staple fibers into continuous yarn through controlled drafting and twisting mechanisms. Carolina Piedmont mills are replacing legacy frames with automated doffing systems to meet technical yarn specifications for automotive airbag substrates. OSHA machine guarding mandates under 29 CFR 1910.212 are accelerating replacement demand across Georgia and South Carolina facilities.
- Finishing Equipment:Thermal processing lines, coating systems, and chemical treatment baths modify fabric hand, appearance, and functional properties through precise temperature and tension control. Technical textile producers in North Carolina are prioritizing precision coating capabilities to satisfy NHTSA material specifications for defense and medical end-use contracts.
- Weaving Machines:Air-jet and rapier looms interlace warp and weft yarns at speeds exceeding 2,000 picks per minute for high-density technical fabrics.
- Knitting Machines:Circular and flat-bed configurations produce seamless garment constructions for body-mapping athletic wear applications.
Mature deployment sits with spinning machines. Newer deployment is concentrated in finishing equipment.
End User:
Procurement scale varies sharply between commodity apparel operations and specification-driven technical textile contracts.
- Technical Textile Industries:Producers of industrial fabrics, medical textiles, and protective equipment require machinery capable of processing high-tenacity synthetic fibers and multilayer composites. Defense procurement mandates under Department of Commerce Buy American provisions are redirecting machinery sourcing toward domestic OEM channels serving Southeast manufacturing clusters.
- Apparel Manufacturers:Cut-and-sew operations and seamless garment producers balance labor substitution economics against capital intensity. Georgia and North Carolina mills are expanding circular knitting machine procurement as athletic wear brands adopt body-mapping construction techniques.
- Home Textile Producers:Bedding and upholstery fabric manufacturers prioritize high-capacity dyeing and finishing lines for cotton and synthetic blends.
- Nonwoven Fabric Producers:Spunbond, meltblown, and needlepunch operations serve filtration, hygiene, and medical applications with continuous web formation systems.
Technical textile industries command the steepest expansion trajectory. Home textile producers maintain the most stable replacement cycles.
Technology:
Automation intensity directly correlates with labor scarcity severity across Southeast manufacturing corridors.
- Automatic:Fully automated systems integrate material handling, process control, and quality monitoring with minimal operator intervention. North Carolina and Georgia mills facing electromechanical technician shortages are accelerating capital substitution for manual operations in spinning and finishing lines.
- CNC:Computer numerical control platforms enable precise pattern programming and real-time process adjustment for complex fabric specifications. Technical textile producers are embedding CNC dyeing platforms with predictive maintenance modules to compress downtime during defense contract fulfillment.
- Semi-Automatic:Hybrid configurations combine automated process control with manual loading and inspection operations.
- Manual:Operator-dependent systems persist in specialty short-run operations and legacy facility retrofits.
Automatic systems anchor current installed base expansion. CNC platforms are gaining share fastest in technical textile greenfield investments.
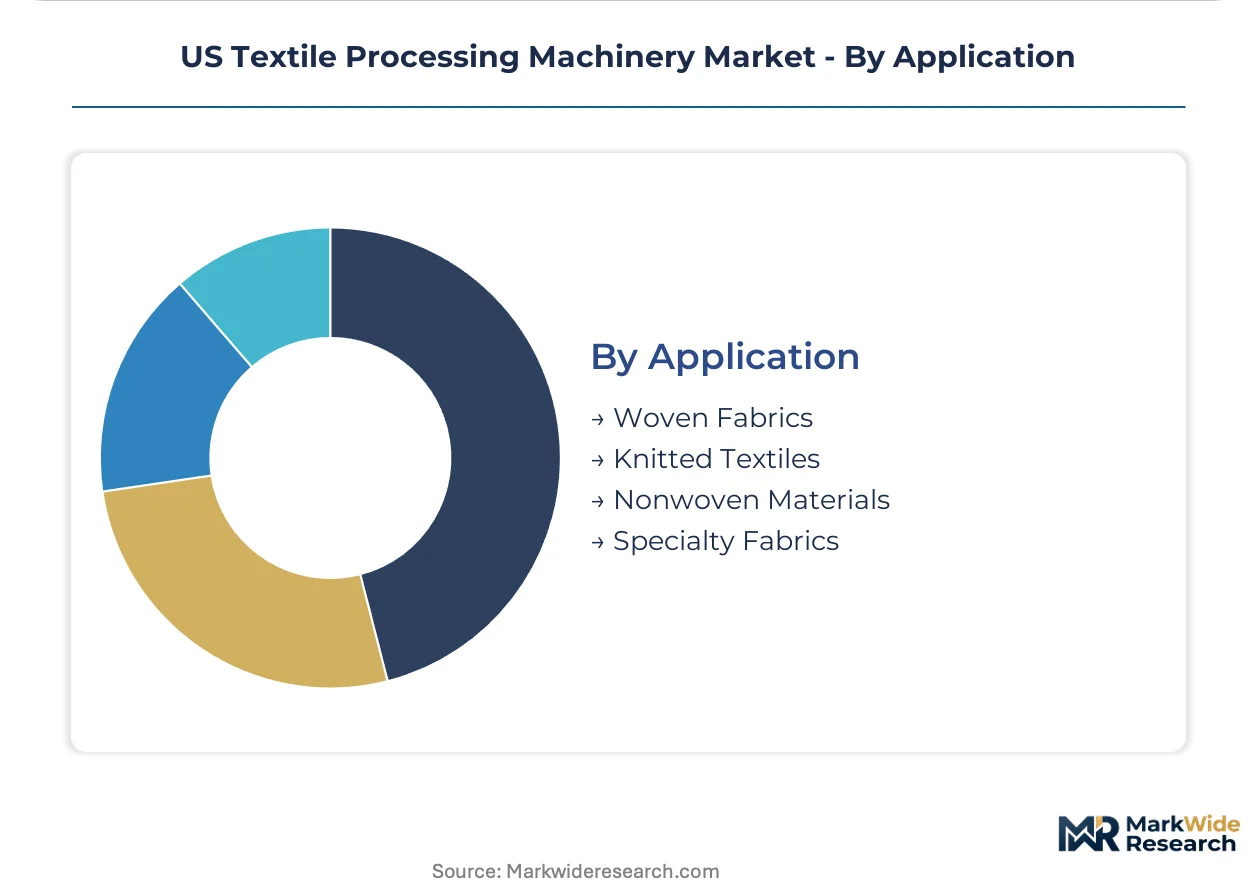
Application:
Material specifications dictate machinery configuration across woven, knitted, and nonwoven formation processes.
- Woven Fabrics:Interlaced yarn constructions produced on shuttleless looms serve industrial, apparel, and home textile applications requiring dimensional stability. Carolina-Georgia manufacturing corridor investment in high-density technical fabrics is driving air-jet and rapier loom procurement for defense and automotive supply chains.
- Nonwoven Materials:Direct web formation from fibers or polymers bypasses yarn production for filtration, hygiene, and medical applications. EPA effluent guidelines under the Clean Water Act are forcing equipment upgrades toward closed-loop water recycling systems in South Carolina nonwoven processing facilities.
- Knitted Textiles:Loop-forming constructions provide stretch and recovery properties for apparel and technical applications.
- Specialty Fabrics:Narrow fabrics, coated textiles, and composite reinforcements require customized processing equipment.
Woven fabrics dominate current capital allocation. Nonwoven materials are climbing the fastest as medical and filtration demand expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones across the Carolina-Georgia corridor concentrate federal tax incentives for textile machinery investment, drawing capital toward technical fabric production hubs. Defense procurement mandates and medical textile demand are compressing equipment deployment timelines across Southeastern manufacturing belts.
North Carolina
Technical textile producers in the Piedmont Triad are accelerating finishing line upgrades for automotive airbag substrates and medical fabrics. OSHA machine guarding standards under 29 CFR 1910.212 are forcing replacement of legacy spinning frames. The Charlotte-Concord-Gastonia metro anchors high-capacity dyeing platform installations serving defense contractors.
South Carolina
EPA Clean Water Act enforcement is redirecting capital toward closed-loop water recycling systems in Greenville-Spartanburg nonwoven facilities. The Upstate region clusters spunbond and meltblown operations for filtration and hygiene applications. Technical labor scarcity across Anderson and Oconee counties is accelerating automatic system procurement.
Georgia
Apparel manufacturers in the Atlanta-Sandy Springs-Roswell statistical area are expanding circular knitting machine fleets for body-mapping athletic wear. The state qualifies energy-efficient thermal finishing equipment for IRA clean manufacturing tax credits. Augusta-Richmond County mills prioritize OEMs with integrated safety engineering for OSHA compliance.
Virginia
Technical fabric producers in the Richmond-Petersburg corridor are retrofitting weaving operations for high-tenacity synthetic fiber processing. The Virginia Port Authority logistics infrastructure supports machinery import channels from German and Japanese component suppliers. Hampton Roads defense contractors are specifying precision coating capabilities for protective equipment contracts.
Tennessee
Carpet and flooring textile manufacturers in the Chattanooga-Cleveland-Dalton tri-state area are automating tufting and finishing lines. The state's machinery and equipment tax abatement program compresses capital recovery periods. Knoxville-area technical textile startups are piloting digital twin commissioning for multi-million dollar processing lines.
US Textile Processing Machinery Market Competitive Landscape
Top-tier vendors anchor full-line system integration, while mid-scale fabricators compete on regional service density and retrofit specialization. Market structure tilts toward consolidated vendor relationships as defense and medical contract holders demand unified performance guarantees. Three archetypes dominate: industrial laundry heritage players pivoting into technical textiles, CNC-controlled platform specialists, and thermal finishing equipment fabricators. Competitive moves concentrate on strategic partnerships for digital thread control integration and geographic expansion into the Carolina-Georgia corridor.
Within the industrial heritage tier, Pellerin Milnor Corporation and G.A. Braun Inc. represent established anchors with deep Southeast manufacturing relationships. Alliance Laundry Systems LLC exemplifies the R&D-intensive archetype pursuing CNC-controlled platform development. These three occupy positions where technical textile contract specifications are redirecting equipment requirements toward precision finishing and automated material handling capabilities.
| Leading Market Players |
|---|
| G.A. Braun Inc. |
| Pellerin Milnor Corporation |
| Alliance Laundry Systems LLC |
| Leonard Automatics |
| Wolfe Dye & Bleach Works Inc. |
| Continental Girbau |
| B&C Technologies |
| Lapauw USA LLC |
| Kusters Calico |
| Others |
Pricing and Supply Chain Analysis
Captive in-house production of precision servo drives and CNC control modules anchors supply security for domestic OEMs while insulating them from German and Japanese component pricing volatility. This backward integration choice simultaneously compresses lead times for defense contractors and supports premium pricing for technical textile finishing lines.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Carolina-Georgia defense contractors compress procurement cycles for NHTSA-certified finishing equipment. Three-tier pricing structure across premium, standard, and economy levels differentiates by OSHA compliance tier and after-sales service bundling. Cost compression in mid-tier spinning frames is intensifying because of steel alloy input volatility. Apparel manufacturers exhibit the sharpest price sensitivity, while technical textile producers prioritize specification adherence over unit economics.
Supply Chain Analysis
Department of Commerce Buy American provisions are redirecting machinery sourcing toward domestic OEM channels serving Southeast manufacturing clusters. Precision servo drives and CNC control modules draw from concentrated supplier bases in Germany and Japan, while specialty stainless steel grades for equipment frames rest on commodity markets. Single-source vulnerability in electromechanical components creates exposure to transatlantic logistics chokepoints. Distribution runs through full-line system integrators capable of unified performance guarantees for defense contract holders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning as players pursue upstream control over precision component supply to escape German and Japanese supplier concentration.
For Market Incumbents: Extend technical service capabilities into predictive maintenance modules and remote diagnostics to monetize aftermarket revenue streams. Anchor capacity addition in the Carolina Piedmont to capture defense procurement mandates. Certification investment in integrated OSHA safety engineering insulates margins from retrofit cost compression. For New Entrants and Emerging Players: Capture white-space in circular knitting machine procurement for Georgia apparel manufacturers adopting body-mapping construction. The penetrable segment sits with mid-scale technical textile producers seeking CNC-controlled dyeing platforms without full-line system integrator premiums. A go-to-market angle emphasizing digital twin commissioning compresses installation timelines for multi-million dollar finishing lines. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by industrial heritage players pivoting into technical textiles. Long-term viability over the next decade hinges on defense contract diversification and IRA clean manufacturing tax credit capture. Watch NHTSA technical fabric specification updates as the inflection indicator for precision coating capability demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Reduces exposure to German and Japanese servo drive supply concentration for domestic OEMs. |
| Digital Twin Commissioning Capability | Compresses installation timelines for North Carolina technical fabric producers. |
| Integrated Safety Engineering Investment | Satisfies OSHA 29 CFR 1910.212 mandates across Georgia and South Carolina mills. |
| Closed-Loop Water Recycling Systems | Aligns with EPA Clean Water Act enforcement in South Carolina nonwoven facilities. |
| IRA Clean Manufacturing Certification | Qualifies energy-efficient thermal finishing equipment for federal tax credits. |
Research Methodology
Multi-period observation of capital deployment cycles, regulatory enforcement intensity, and contract award patterns anchored the trend analysis, supplemented by interviews with plant engineers at Carolina-Georgia textile mills, OEM technical sales directors, defense procurement officers, EPA regional compliance staff, and aftermarket service heads. Secondary validation drew from OSHA enforcement databases, EPA effluent discharge records, Department of Commerce Buy American contract listings, and SEC filings of listed machinery manufacturers. Bottom-up equipment shipment tracking and top-down manufacturing value-add estimates were triangulated.
Input-output matrix modeling connected machinery type, automation tier, and end-use application to derive volume and value projections across the analysis window. Segmentation dimensions spanned product type, technology intensity, end-user industry, and geographic manufacturing cluster. CAGRs were synthesized from historical replacement cycle compression rates and projected reshoring capital deployment. Industry-specific forecast inputs included defense contract award velocity and NHTSA technical fabric specification evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to German and Japanese component supply disruptions, steel alloy commodity swings, and electromechanical technician availability across the Southeast. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Sewing Machine Market
Textile Machinery and Equipment
Global Textile Machinery Market
Textile Machinery and Equipment
Automatic Webbing Cutting Machines Market
Textile Machinery and Equipment
Fabric Cutting Machines Market
Textile Machinery and Equipment
Global Digital Textile Printing Machine Market
Textile Machinery and Equipment
Multifunctional Clothes Folding Machine Market
Textile Machinery and Equipment
Industrial Laundry Market
Textile Machinery and Equipment
Middle East and Africa Textile Films Market
Textile Machinery and Equipment
Global Custom T-Shirt Printing Market
Textile Machinery and Equipment
Textile Printer Market
Textile Machinery and Equipment
Global Warp Knitting Machine Market
Textile Machinery and Equipment
Asia Pacific Fabric Shavers Market
Textile Machinery and Equipment
Fabric Reversing Machines Market
Textile Machinery and Equipment
Portable Fabric Canopies Market
Textile Machinery and Equipment
Disposable Garment Bags Market
Textile Machinery and Equipment
Spools Market