
 Industrial Laundry Market | 2026-2036
Industrial Laundry Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Laundry Market Intelligence
European equipment manufacturers are restructuring their production footprints to offset energy cost volatility and align with EU Green Deal mandates. Jensen Group leverages its engineering heritage to sustain premium positioning in continuous batch washer technology. Girbau Group anchors its competitiveness through modular automation architectures that reduce floor-space requirements for mid-capacity operators. Alliance Laundry Holdings LLC extends its reach across North American institutional channels through broad distribution control and after-sales service density.
Industrial laundry encompasses the commercial-scale cleaning, finishing, and distribution of textiles using specialized equipment designed to process loads exceeding 200 kg per cycle with controlled temperature, chemistry, and mechanical action parameters. The sector serves hospitality, healthcare, and uniform rental sectors where hygiene certification and textile longevity directly affect operational compliance and cost structures. Laundry Equipment commands the largest revenue pool as hospitals and hotels replace aging washer-extractors with automated tunnel systems. Energy-efficient Machines represent the fastest-expanding technology segment as operators face carbon pricing and utility cost pressures. Software is gaining traction as a margin-rich overlay because IoT-enabled fleet management reduces downtime and optimizes chemical dosing across multi-site operations.
EPA effluent guidelines and OSHA workplace exposure standards shape equipment specifications and chemical formulations in the United States. The EU Ecodesign Directive and F-Gas Regulation drive refrigerant and heat-pump technology transitions in European finishing equipment. Stakeholders must monitor how fragmented national wastewater rules across Germany, France, and Italy fragment certification requirements and complicate pan-European equipment standardization strategies.
Market Dynamics
Centralized service contracts from hospital networks are compressing equipment procurement cycles while EPA effluent tightening forces chemistry and wastewater system redesigns across the installed base.
Growth Catalysts
- Healthcare outsourcing:Hospital networks in China are consolidating linen management into regional industrial laundry hubs, creating pull for high-capacity tunnel washer systems.
- OSHA exposure standards:Stricter workplace chemical handling rules in the United States are accelerating replacement of open-transfer washer-extractors with closed-loop automated systems.
- Heat-pump finishing:EU F-Gas Regulation phase-down is absorbing capital into refrigerant-free drying technology as operators future-proof against supply disruption.
Market Restraints
- Steel and aluminum input volatility:Equipment fabrication costs swing with commodity indexes, compressing margin visibility for mid-cap manufacturers.
- European energy price instability:German and Italian operators face 40-60% utility cost spikes, freezing expansion capex despite replacement demand.
- Water scarcity in southwestern China:Municipal rationing in Sichuan and Yunnan provinces limits throughput scaling for new centralized facilities.
Strategic Opportunities
- Indian hospital network modernization:Tier-2 and Tier-3 cities lack industrial laundry infrastructure; domestic healthcare chains present greenfield contract opportunities.
- EU Green Deal capital access:Equipment manufacturers can tap subsidized financing for heat-pump and solar-thermal integration in retrofit projects.
- IoT-chemistry convergence:Real-time dosing optimization combined with predictive maintenance creates subscription revenue streams beyond hardware sales.
Industry Challenges
- Skilled technician shortages:Maintenance of automated tunnel systems requires electro-mechanical and PLC programming competencies that vocational pipelines underproduce.
- Legacy washer-extractor integration:Hybrid fleets combining aging extractors with new tunnel lines create workflow bottlenecks and quality variance.
- Hygiene certification timelines:EN 14065 and RABC standard audits extend 6-12 months, delaying contract commencement and revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Laundry Market |
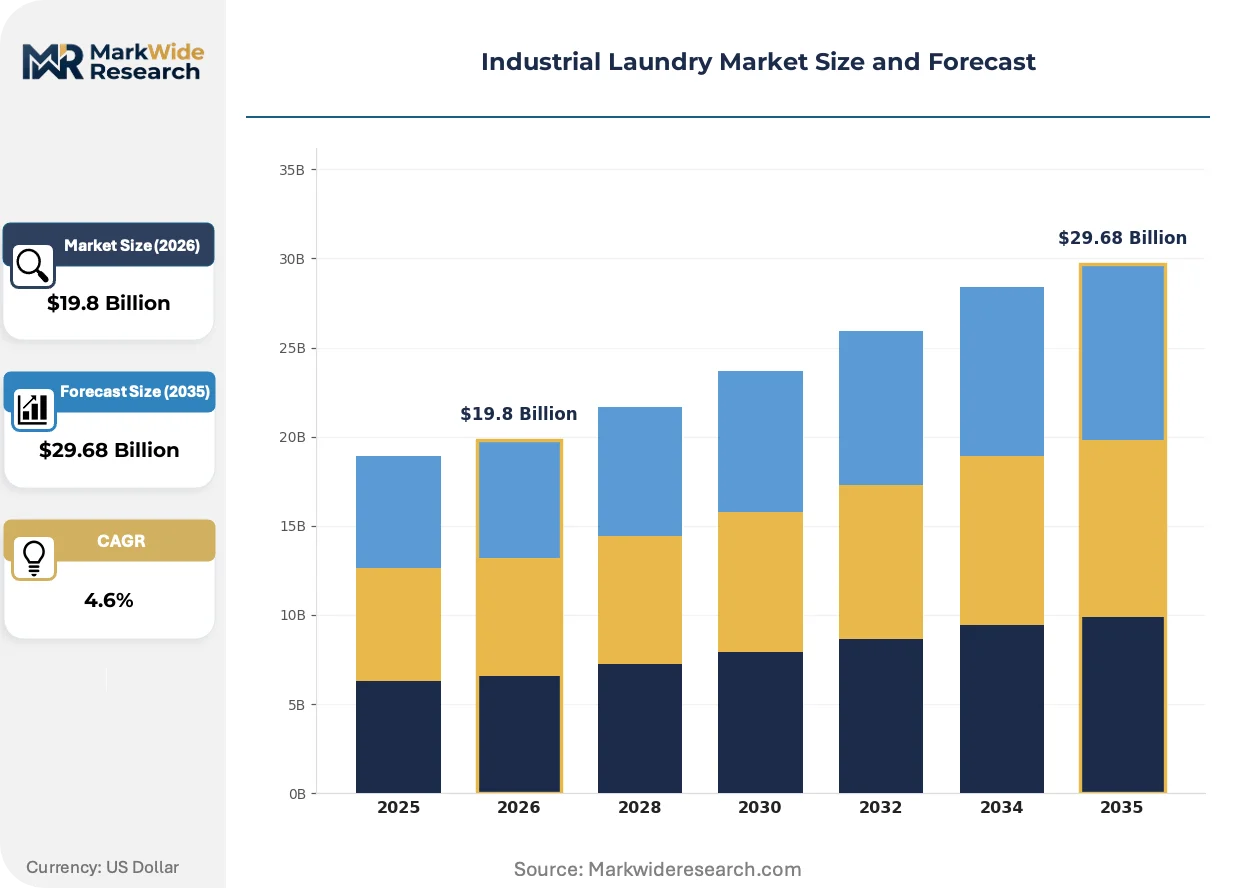
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $29.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laundry Equipment, Handling Systems, Chemicals, Software End User: Hotels, Hospitals, Restaurants, Textile Rental Service Type: Dry Cleaning, Wash-Dry-Fold, Linen Supply, Waste Management Technology: Automated Systems, Energy-efficient Machines, IoT Solutions, Traditional Methods |
| Companies Covered | Jensen Group, Girbau Group, Alliance Laundry Holdings LLC, Lindstrom Group, EVI Industries, Cintas Corporation, Herbert Kannegiesser GmbH, Ecolab Inc., Electrolux Professional Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Laundry Market Strategic Shifts & Innovations
Automation, chemistry minimization, and service-model reinvention are restructuring how industrial laundry operators deploy capital and manage fleet performance across multi-site networks.
Continuous batch washer technology is absorbing demand from conventional washer-extractors as hospital and hotel operators prioritize labor reduction and throughput consistency. Large healthcare networks in the United States and Germany are specifying tunnel systems for new-build facilities, with adoption timelines compressing from 18-month evaluation cycles to 12-month procurement windows. The technology is absorbing mid-cap operator upgrade budgets that previously fragmented across multiple extractors.
EPA effluent guideline revisions are tightening chemical oxygen demand and surfactant discharge thresholds for laundry wastewater in the United States. Equipment suppliers must now certify integrated wastewater treatment modules or risk exclusion from municipal sewer-connected installations. California and Texas healthcare laundries face the steepest compliance curves due to state-level water quality standards exceeding federal baselines.
Service unbundling is fragmenting traditional equipment-plus-maintenance contracts into separate capital, chemical supply, and telemetry subscription components. Hospitality chains with volatile occupancy patterns prefer chemical-per-kilo pricing over fixed lease commitments, compressing manufacturer financing margins. This preference shift is most visible in the United Kingdom and Netherlands where hotel groups operate centralized procurement for European property portfolios.
Industrial Laundry Market Segmentation
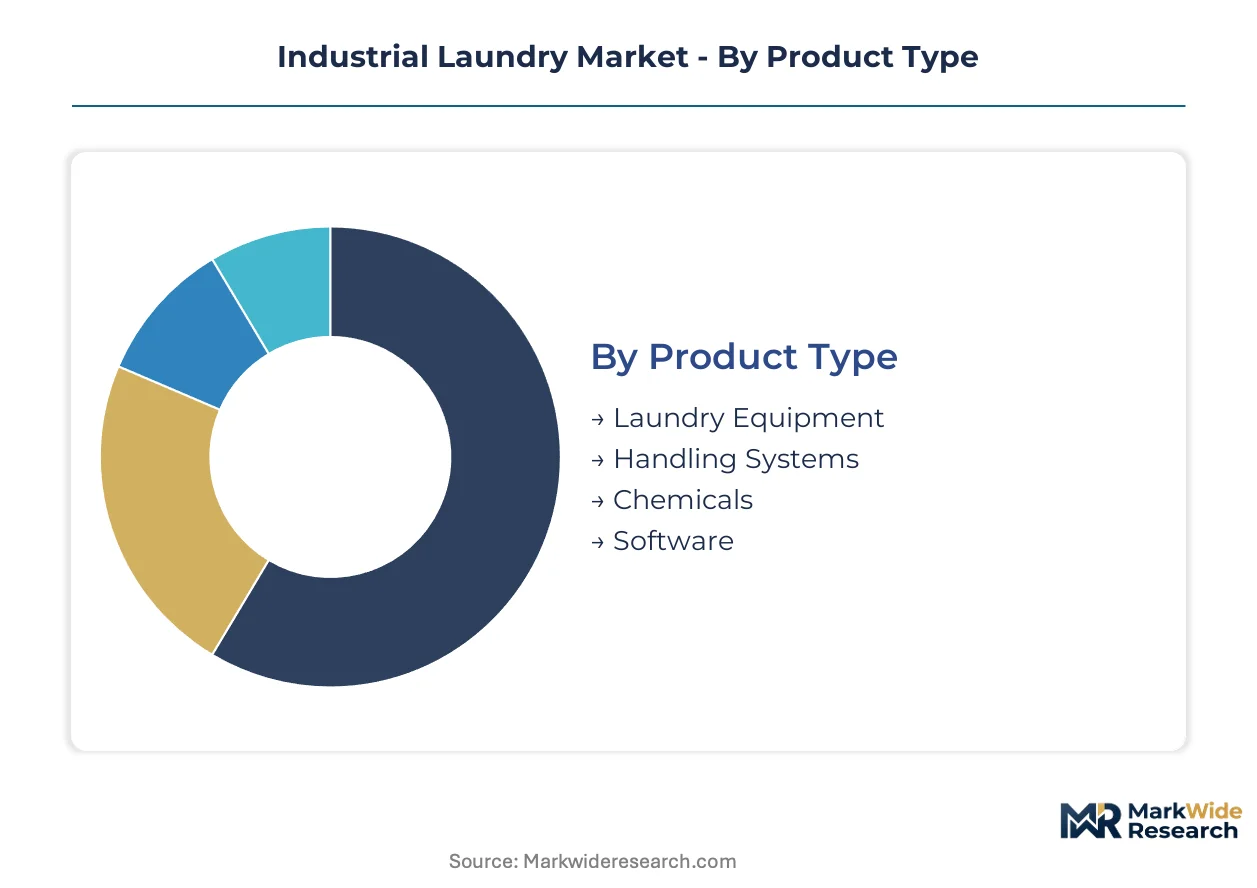
Industrial laundry operators configure procurement and compliance strategies around equipment specifications, end-use hygiene requirements, and technology maturity curves. Segmentation reveals where capital concentrates and which service models absorb regulatory burden.
Product Type:
EN 14065 and RABC certification requirements vary sharply across equipment categories, with tunnel washer systems demanding the most extensive validation protocols for healthcare deployment.
- Laundry Equipment:Tunnel washer systems and washer-extractors exceeding 200 kg capacity dominate hospital procurement, with EPA effluent compliance modules now mandatory for US municipal sewer connections. Healthcare networks in Germany and China specify continuous batch technology to reduce labor headcount and standardize throughput.
- Handling Systems:Automated conveyor and sorting architectures integrate with tunnel lines to eliminate manual transfer points. Mid-cap European operators prioritize these systems to offset technician shortages and OSHA exposure liabilities.
- Chemicals:Surfactant and bleaching formulations face tightening discharge thresholds under EPA guidelines and EU REACH restrictions.
- Software:IoT-enabled fleet management and predictive maintenance platforms command subscription margins above hardware sales.
Leading the category by volume: Laundry Equipment. Growing fastest: Software.
End User:
Cost tier stratification separates capital-intensive healthcare contracts from cyclical hospitality procurement, with hygiene certification timelines creating divergent cash conversion cycles.
- Hotels:Occupancy volatility drives preference for chemical-per-kilo pricing over fixed lease commitments, compressing manufacturer financing margins. UK and Netherlands chains centralize procurement across European portfolios.
- Hospitals:Centralized linen management contracts in China and the United States absorb high-capacity tunnel systems, with EN 14065 and RABC audits extending 6-12 months before revenue recognition.
- Restaurants:Fragmented demand across independent operators limits standardization, with equipment procurement deferring to regional distributor relationships.
- Textile Rental:Uniform and mat rental operators balance fleet refresh cycles against steel and aluminum input cost volatility.
Revenue concentrates in Hospitals. Fastest expansion trajectory: Hotels in China's tier-2 cities.
Service Type:
Margin structure varies with asset intensity, from capital-heavy linen supply to labor-dependent wash-dry-fold operations.
- Dry Cleaning:Perchloroethylene phase-out under EPA and EU restrictions accelerates hydrocarbon and wet-cleaning technology substitution.
- Wash-Dry-Fold:Labor-intensive operations face OSHA exposure standard compliance costs for chemical handling protocols.
- Linen Supply:Hospital and hotel networks outsource inventory ownership to specialized operators, consolidating regional hub capacity.
- Waste Management:Wastewater treatment and chemical recovery systems integrate with tunnel washer installations to meet municipal discharge permits.
Highest asset turnover: Wash-Dry-Fold. Steepest capital requirements: Linen Supply.
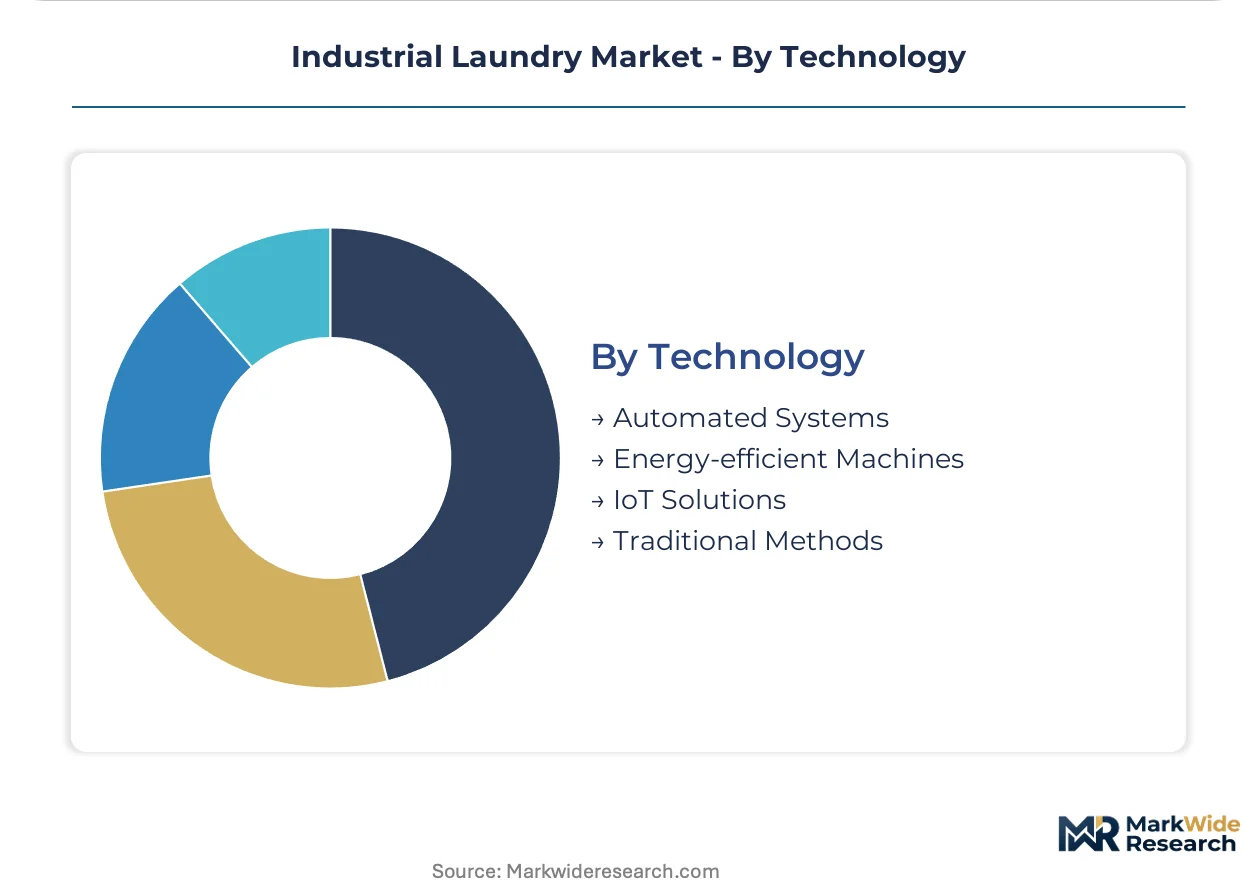
Technology:
Adoption maturity separates proven automated systems from emerging IoT overlays, with EU F-Gas Regulation forcing refrigerant technology transitions in finishing equipment.
- Automated Systems:Continuous batch washers and automated material handling reduce labor dependency and standardize quality variance across multi-site operations.
- Energy-efficient Machines:Heat-pump drying technology absorbs capital as German and Italian operators future-proof against F-Gas supply disruption and carbon pricing exposure.
- IoT Solutions:Real-time chemical dosing optimization and predictive maintenance create subscription revenue streams beyond hardware monetization.
- Traditional Methods:Open-transfer washer-extractors face replacement pressure from OSHA workplace exposure standards and effluent guideline tightening.
Installed base dominance: Traditional Methods. Gaining share fastest: Energy-efficient Machines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel and aluminum fabrication clusters in Germany, China, and the United States anchor equipment manufacturing capacity for industrial laundry systems. Regional demand patterns diverge sharply based on healthcare infrastructure maturity, energy cost structures, and regulatory stringency around chemical discharge.
United States
Hospital network consolidation in Texas and California drives centralized linen management contracts toward high-capacity tunnel systems. EPA effluent guideline revisions for chemical oxygen demand tighten discharge thresholds in municipal sewer-connected installations. The Dallas-Fort Worth metroplex hosts expanding regional laundry hubs serving multi-state healthcare systems.
Germany
Energy price volatility reaching 40-60% spikes freezes expansion capex despite replacement demand for aging washer-extractors. EU F-Gas Regulation phase-down absorbs capital into refrigerant-free heat-pump drying technology. The North Rhine-Westphalia industrial corridor concentrates equipment manufacturing and operator consolidation activity.
China
Domestic hospital networks upgrade to centralized industrial laundry services, creating pull for automated tunnel washer systems. Municipal water rationing in Sichuan and Yunnan provinces limits throughput scaling for new facilities. The Yangtze River Delta hosts the fastest-growing cluster of healthcare laundry outsourcing contracts.
India
Tier-2 and Tier-3 cities lack industrial laundry infrastructure, presenting greenfield contract opportunities for domestic healthcare chains. Central government hospital modernization programs accelerate procurement timelines for EN 14065-compliant equipment. Maharashtra and Karnataka lead hospital network expansion into outsourced linen management.
United Kingdom
Hospitality chains centralize procurement across European property portfolios, preferring chemical-per-kilo pricing over fixed lease commitments. OSHA-equivalent workplace exposure standards accelerate replacement of open-transfer systems. London and the Southeast concentrate demand for automated handling systems serving hotel networks.
Industrial Laundry Market Key Industry Players
Global majors compete with regional champions across technology tiers and service intensity dimensions. Market structure tilts toward consolidation at the premium equipment tier while mid-cap operators fragment across specialized automation niches. Three archetypes dominate: engineering-heritage European manufacturers, North American distribution-heavy conglomerates, and Asian cost-optimized fabricators. Competitive moves center on M&A for technology access and geographic expansion into hospital outsourcing growth markets.
Within the engineering-heritage tier, Jensen Group and Girbau Group exemplify premium positioning through continuous batch washer specialization and modular automation architectures respectively. Alliance Laundry Holdings LLC anchors the North American distribution-centric archetype through institutional channel density. These three occupy positions spanning European precision manufacturing and North American service-network scale.
| Leading Market Players |
|---|
| Jensen Group |
| Girbau Group |
| Alliance Laundry Holdings LLC |
| Lindstrom Group |
| EVI Industries |
| Cintas Corporation |
| Herbert Kannegiesser GmbH |
| Ecolab Inc. |
| Electrolux Professional Group |
| Others |
Cost & Logistics Intelligence
Hospital procurement consolidation into regional linen management hubs in China and the United States is forcing equipment manufacturers to absorb extended warranty obligations and telemetry subscriptions into base pricing. This shift compresses upfront hardware margins while locking suppliers into decade-long service dependencies.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium European manufacturers from Asian cost-optimized competitors. Three-tier pricing structure across premium, standard, and economy levels tracks equipment automation depth and EN 14065 certification status. Cost compression in mid-cap tunnel systems is intensifying because steel and aluminum input volatility erodes fabrication margins. Hospitality chains exhibit highest price sensitivity, while hospital networks prioritize compliance assurance over capital expenditure minimization.
Supply Chain Analysis
Skilled electro-mechanical and PLC programming labor shortages in Germany, Italy, and the United States constrain production scaling for automated tunnel systems. Equipment fabrication draws from steel mills in North Rhine-Westphalia, aluminum processors in the Yangtze River Delta, and precision component suppliers in northern Italy. Single-source vulnerability in heat-pump compressor supply from German manufacturers exposes finishing equipment lead times. Distribution runs through authorized dealer networks with captive service technician training.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where EPA effluent guideline revisions and EN 14065 certification timelines erect structural barriers that favor incumbents with established validation protocols and municipal permit relationships.
For Market Incumbents: Deepen backward integration into heat-pump compressor manufacturing to insulate margins from F-Gas Regulation supply disruption. Fortify EN 14065 audit facilitation capabilities to accelerate hospital contract commencement timelines against emerging Asian competitors lacking certification heritage.
For New Entrants and Emerging Players: The mid-tier price gap between Jensen Group premium tunnel systems and Chinese economy washer-extractors invites modular automation architectures targeting Indian tier-2 hospital networks. Penetrate through chemical-per-kilo service contracts that sidestep capital-intensive equipment financing barriers.
For Investors and Strategic Acquirers: The window for entry favors European engineering-heritage manufacturers with heat-pump drying technology and established EU Green Deal subsidy access. Monitor municipal water rationing announcements in southwestern China as inflection indicators for centralized laundry hub viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Technology Transition | Absorbs capital away from F-Gas-dependent refrigerant systems toward EU-compliant drying infrastructure. |
| IoT-Chemistry Convergence | Creates recurring subscription revenue through real-time dosing optimization across multi-site hospital networks. |
| Regional Hub Consolidation | Captures economies of scale in China and Texas healthcare markets through centralized linen management contracts. |
| EN 14065 Certification Investment | Accelerates revenue recognition timelines by pre-qualifying equipment for European hospital procurement. |
| Aftermarket Service Network Expansion | Offsets skilled technician shortages through proprietary training pipelines and predictive maintenance platforms. |
Research Approach
Document review covered EPA effluent guideline filings, EU Ecodesign Directive implementing measures, and hospital procurement database records, complemented by interviews with plant engineers at regional laundry hubs, maintenance directors overseeing tunnel system fleets, OEM procurement teams at equipment manufacturers, and aftermarket service heads managing multi-site contracts. Secondary validation drew from customs trade data, SEC 10-K equipment segment disclosures, and national wastewater discharge permit registries. Bottom-up equipment shipment analysis and top-down healthcare capital expenditure tracking were triangulated against regional energy price indices.
Historical volume trajectories were cross-referenced against panel input from equipment manufacturer sales executives and hospital supply chain directors. Segmentation modeling spanned product type, end-user hygiene tier, technology maturity, and regional regulatory cluster across the analysis window. CAGRs were derived from installed base replacement cycles and greenfield hospital construction pipelines. Forecast inputs incorporated steel price volatility bands and municipal water rationing probability assessments.
Inputs from EPA preliminary effluent rulemakings and EN 14065 audit completion databases were available through the study window; gaps in real-time hospital contract commencement data introduce uncertainty bands around revenue recognition timing. Forecasts reflect assumptions regarding F-Gas Regulation phase-down adherence and China healthcare infrastructure investment continuity. Material deviation in EPA final rule stringency or Yangtze River Delta water policy warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Yankee Dryer Market
Textile Machinery and Equipment
Fabric Reversing Machines Market
Textile Machinery and Equipment
Cloth Measuring Machine Market
Textile Machinery and Equipment
Textile Tester Market
Textile Machinery and Equipment
Mesh Tarpaulin Sheets Market
Textile Machinery and Equipment
Global Textile Machinery Market
Textile Machinery and Equipment
Sewing Machine Market
Textile Machinery and Equipment
Plasma Surface Treatment Machine for Leather Market
Textile Machinery and Equipment
Global Custom T-Shirt Printing Market
Textile Machinery and Equipment
T-Shirt Printing Machine Market
Textile Machinery and Equipment
Global Industrial Fabric Market
Textile Machinery and Equipment
Spools Market
Textile Machinery and Equipment
Textile Mill Electric Drives Market
Textile Machinery and Equipment
US Textile Processing Machinery Market
Textile Machinery and Equipment
Stringing Machines Market
Textile Machinery and Equipment
Cotton Processing Equipment Market