
 Middle East and Africa Explosion-Proof Equipment Market | 2026-2036
Middle East and Africa Explosion-Proof Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Explosion-Proof Equipment Market Foresight
Specialized distributor networks serving hazardous environments is narrowing across the Middle East and Africa as end users consolidate vendor lists to reduce compliance risk. Eaton Corporation plc leverages its regional certification depth to anchor large petrochemical contracts in Saudi Arabia and the UAE. Bartec Group competes through German-engineered flameproof assemblies that sustain premium positioning in African mining jurisdictions. R. STAHL AG differentiates via intrinsic safety expertise that dominates North Sea-equivalent offshore specifications now migrating to West African deepwater projects.
Middle East and Africa explosion-proof equipment encompasses electrical and mechanical apparatus engineered to contain or prevent ignition in atmospheres where flammable gases, vapors, dust, or fibers may be present, typically certified to temperature class T1-T6 and equipment protection level (EPL) Ga through Gc designations. Its primary industrial purpose is enabling continuous operations in hydrocarbon processing, underground extraction, and chemical synthesis without triggering catastrophic combustion events. Flameproof enclosure technology captures the largest installed base due to legacy refinery architecture across the Gulf, while intrinsic safety architectures represent the fastest-growing technology segment as digital instrumentation density rises in newbuild facilities. Control systems concentrate margin pools because integration complexity forces bundled procurement decisions that lock in long-term service relationships.
SFDA and MOHAP certification pathways in Saudi Arabia and the UAE shape product entry requirements, while IECEx and ATEX alignment remains mandatory for equipment sourced from European manufacturers. South Africa's Department of Mineral Resources and Energy enforces SANS standards that create additional testing burdens for suppliers targeting platinum and gold operations. Stakeholders must monitor divergence between Gulf national standards and IECEx harmonization timelines to avoid duplicate conformity assessment costs that erode project economics.
Market Dynamics
SFDA and MOHAP certification tightening is compressing vendor qualification timelines across Gulf petrochemical corridors, forcing procurement teams to pre-qualify explosion-proof equipment suppliers eighteen months ahead of project commissioning.
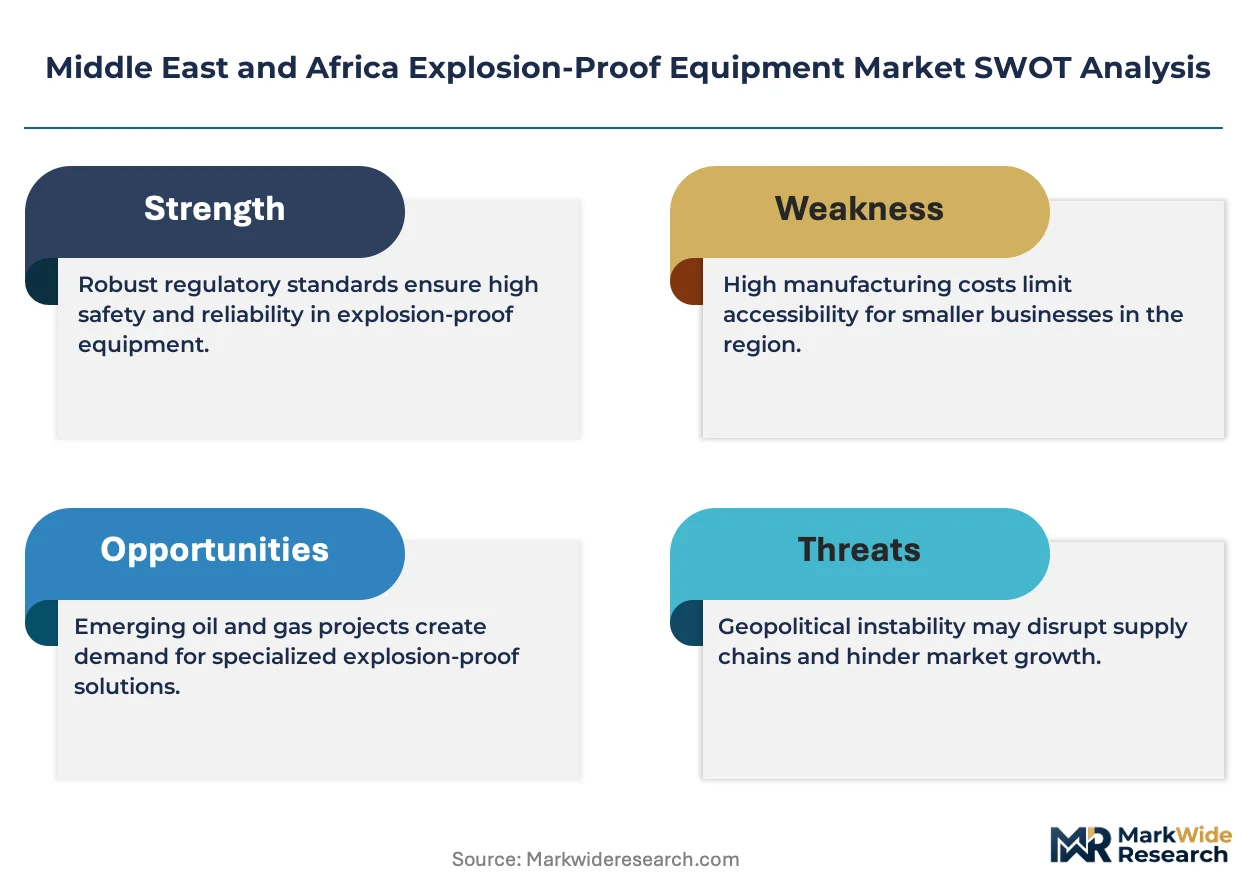
Growth Catalysts
- SFDA Certification Mandates:Saudi Arabia's hazardous area equipment standards now require third-party conformity assessment for all flameproof enclosures, eliminating self-certification pathways and locking in recurring inspection revenue streams for accredited testing bodies.
- Digital Instrumentation Density:Intrinsically safe architectures are capturing newbuild petrochemical facilities in the UAE as distributed control systems require higher sensor counts per processing unit.
- West African Deepwater Migration:North Sea-equivalent offshore specifications are transferring to Nigerian and Angolan projects, expanding addressable market for EPL Ga-rated equipment.
Market Restraints
- Copper and Aluminum Price Volatility:Enclosure manufacturing costs fluctuate with London Metal Exchange pricing, compressing margin predictability for flameproof housing fabricators.
- European Supplier Concentration:IECEx-certified component sourcing remains concentrated among German and Swiss manufacturers, exposing project timelines to single-source bottlenecks.
- Intrinsic Safety Power Limitations:IS barriers restrict available energy to instrumentation, limiting applicability in high-torque actuator applications where flameproof motors remain mandatory.
Strategic Opportunities
- Egyptian Refinery Modernization:Cairo Petroleum Refining Company expansion programs lack qualified local hazardous area equipment distributors, creating first-mover advantage for certified regional service partners.
- IECEx-SANS Harmonization:South Africa's Department of Mineral Resources and Energy is aligning explosion-proof testing protocols with international standards, reducing duplicate certification costs for suppliers targeting platinum belt operations.
- WirelessHART Convergence:Integration of wireless sensor networks with intrinsically safe power modules enables cable-free instrumentation in tank farm monitoring applications.
Industry Challenges
- Ex d to Ex i Retrofit Engineering:Aging Gulf refinery infrastructure requires complex flameproof-to-intrinsic-safety conversion design, stretching scarce hazardous area electrical engineering capacity across contractor pools.
- Multi-Jurisdiction Certification Stacking:Equipment destined for cross-border African mining projects must simultaneously satisfy SANS, IECEx, and ATEX requirements, extending type approval cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Explosion-Proof Equipment Market |
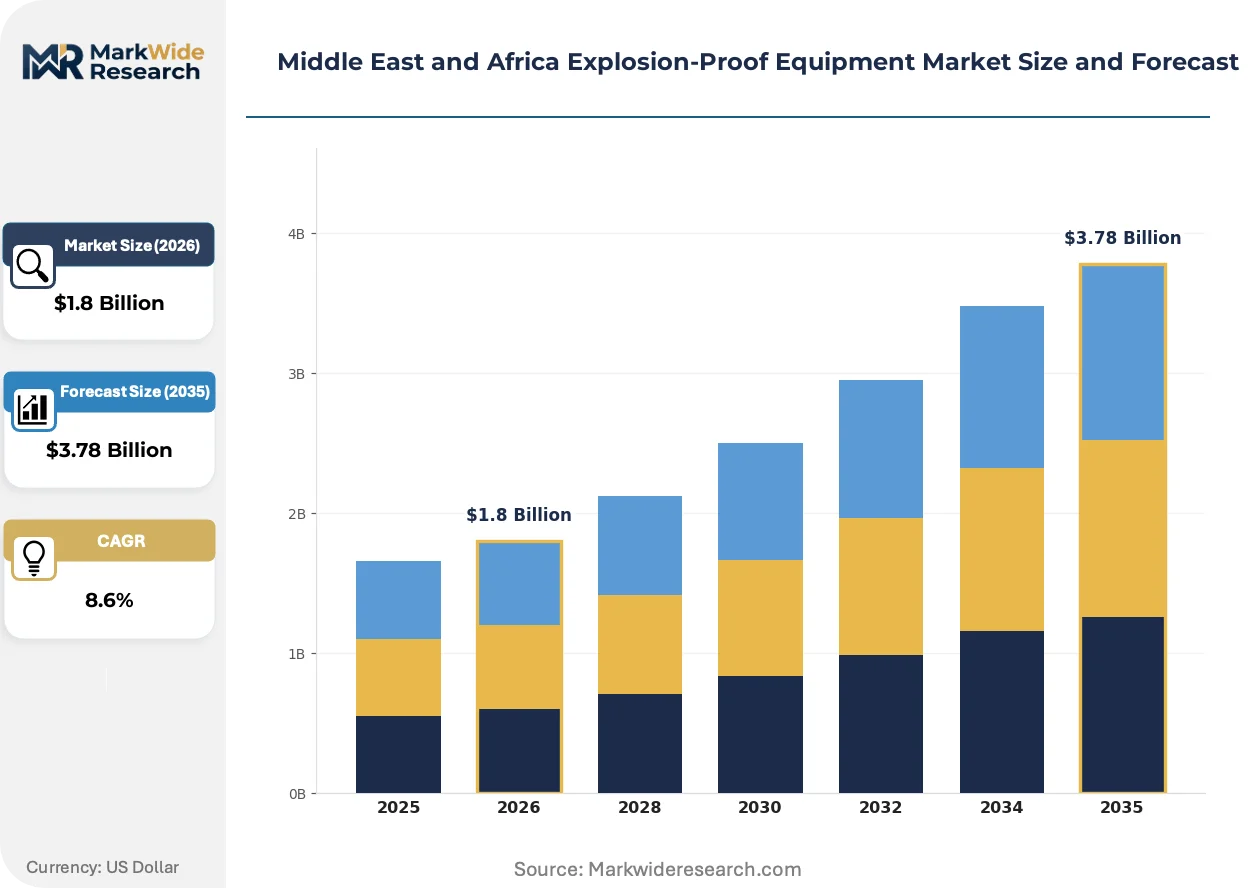
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lighting, Switches, Sensors, Control Systems Technology: Intrinsic Safety, Flameproof, Increased Safety, Non-Incendive End User: Oil & Gas, Mining, Chemicals, Pharmaceuticals Application: Hazardous Locations, Offshore Platforms, Industrial Plants, Warehouses |
| Companies Covered | ABB Ltd, Bartec Group, Eaton Corporation plc, Emerson Electric Co., Hubbell Incorporated, R. STAHL AG, Rockwell Automation, Inc., Siemens AG, Honeywell International Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Explosion-Proof Equipment Market Shifts & Advancements
Explosion-proof equipment architecture is pivoting from passive containment toward active energy limitation, compressing installation footprints and enabling modular processing skids in constrained offshore environments.
Ex ic intrinsic safety protection is migrating from laboratory instrumentation into field-deployed process analytics. Refinery operators in Saudi Arabia are specifying Ex ic barriers for chromatography and spectrometry sampling systems. This shift is eliminating pressurized conduit seals and reducing maintenance access requirements in congested process units.
MOHAP's 2024 hazardous area equipment registration rules now mandate in-country testing for all flameproof motors above 75kW. UAE petrochemical projects are absorbing six-month lead time extensions for large drive certification. European manufacturers are establishing Dubai-based test facilities to preserve market access.
Bundle procurement decisions now dominate control system selection across Gulf national oil companies. Instrumentation, enclosures, and safety barriers are sourced through single integrator contracts rather than component-level purchasing. This concentration is visible in ADNOC's recent offshore platform awards, where long-term service relationships override upfront equipment pricing.
Middle East and Africa Explosion-Proof Equipment Market Segmentation
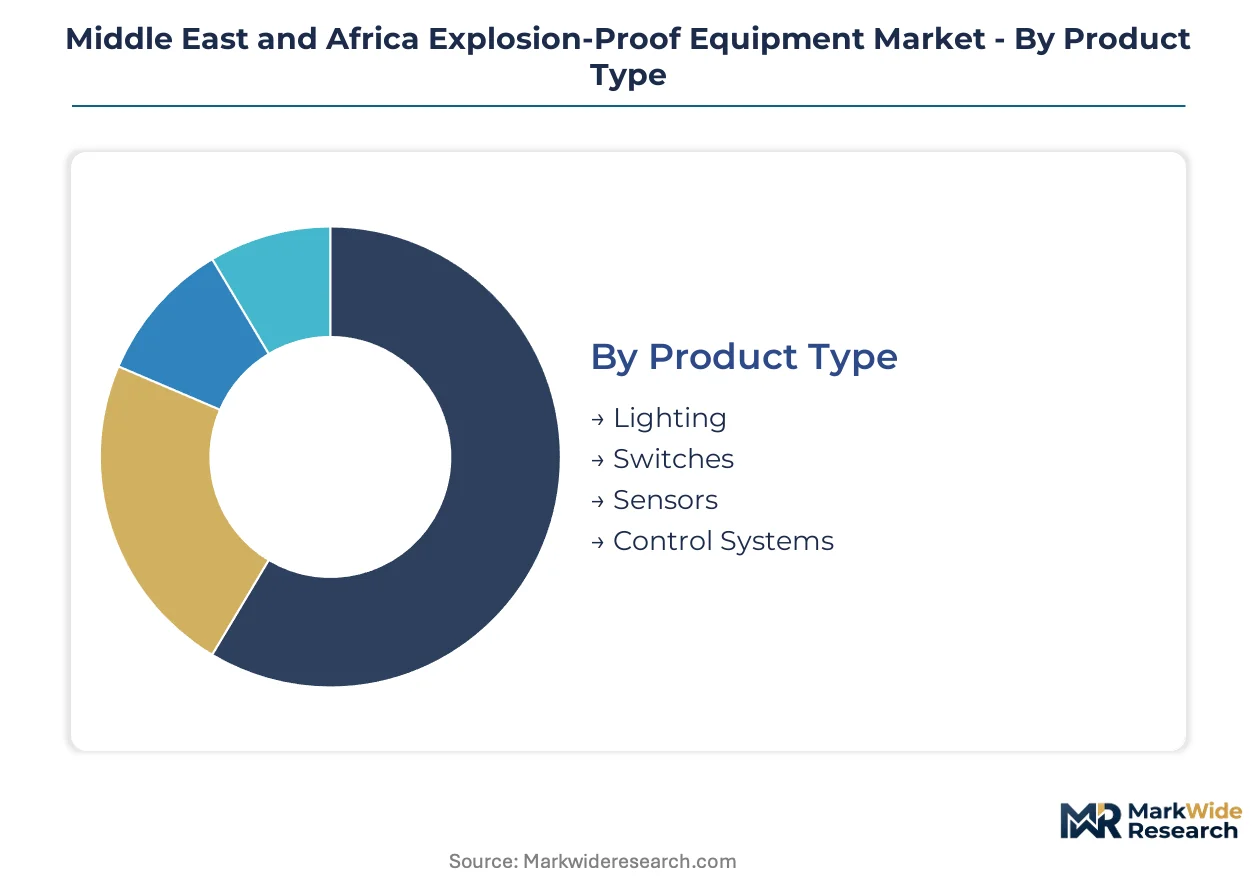
Segmentation of the Middle East and Africa explosion-proof equipment market reveals how certification requirements, facility age, and operational intensity shape procurement patterns across distinct buyer profiles. Each dimension exposes different margin structures and vendor qualification barriers that determine competitive positioning.
Product Type:
Application intensity across hazardous environments determines which product categories command procurement priority and recurring service revenue.
- Lighting:LED flameproof luminaires with T6 temperature ratings dominate retrofit programs in aging Saudi refineries. SFDA mandates for emergency egress illumination are accelerating replacement cycles in Jubail Industrial City complexes.
- Switches:Heavy-duty disconnect switches rated for Zone 1 environments concentrate in UAE petrochemical loading terminals. ADNOC bundled procurement contracts favor integrated switchgear assemblies over component sourcing.
- Sensors:Pressure and temperature transmitters with Ex ia certification are proliferating in distributed control architectures.
- Control Systems:Integrated safety instrumented systems lock in long-term vendor relationships through bundled service agreements.
Control Systems holds installed capacity. Sensors is rotating up the share rankings.
Technology:
Energy containment philosophy—passive versus active—separates legacy infrastructure compatibility from newbuild optimization potential.
- Intrinsic Safety:Ex ia and Ex ic architectures limit spark energy through barrier devices rather than heavy enclosures. Digital instrumentation density in newbuild UAE processing units is displacing flameproof alternatives where power requirements permit.
- Flameproof:Ex d enclosures withstand internal explosions without transmitting ignition to surrounding atmospheres. Saudi Aramco's aging onshore facilities maintain this installed base due to high-torque motor requirements that exceed IS power limits.
- Increased Safety:Ex e construction eliminates sparking components through enhanced construction standards rather than containment.
- Non-Incendive:Ex n protection suits Zone 2 locations where explosive atmospheres occur infrequently and persist briefly.
Flameproof retains the largest installed base. Intrinsic Safety is gaining share fastest through greenfield specification.
End User:
Operational risk profiles and regulatory scrutiny intensity create divergent certification burdens and replacement cycle velocities.
- Oil & Gas:Upstream, midstream, and downstream operations spanning Saudi Arabia, UAE, and Nigeria require continuous certification compliance across SFDA, MOHAP, and Department of Petroleum Resources jurisdictions. National oil company procurement consolidation favors vendors with multi-territory accreditation depth.
- Mining:Underground extraction in South Africa's platinum belt and West African gold operations demands SANS-compliant apparatus with enhanced dust ignition protection. Depth constraints and ventilation limitations prioritize compact intrinsic safety designs.
- Chemicals:Petrochemical synthesis and fertilizer production in the Gulf Cooperation Council corridor operate under combined pressure from process safety management and hazardous area standards.
- Pharmaceuticals:Solvent handling and powder processing facilities require specialized clean-hazardous hybrid certifications.
Oil & Gas anchors procurement volume. Mining is climbing the fastest as West African jurisdictions adopt IECEx alignment.
Application:
Physical environment constraints—space, weather exposure, and accessibility—determine enclosure specifications and maintenance regime economics.
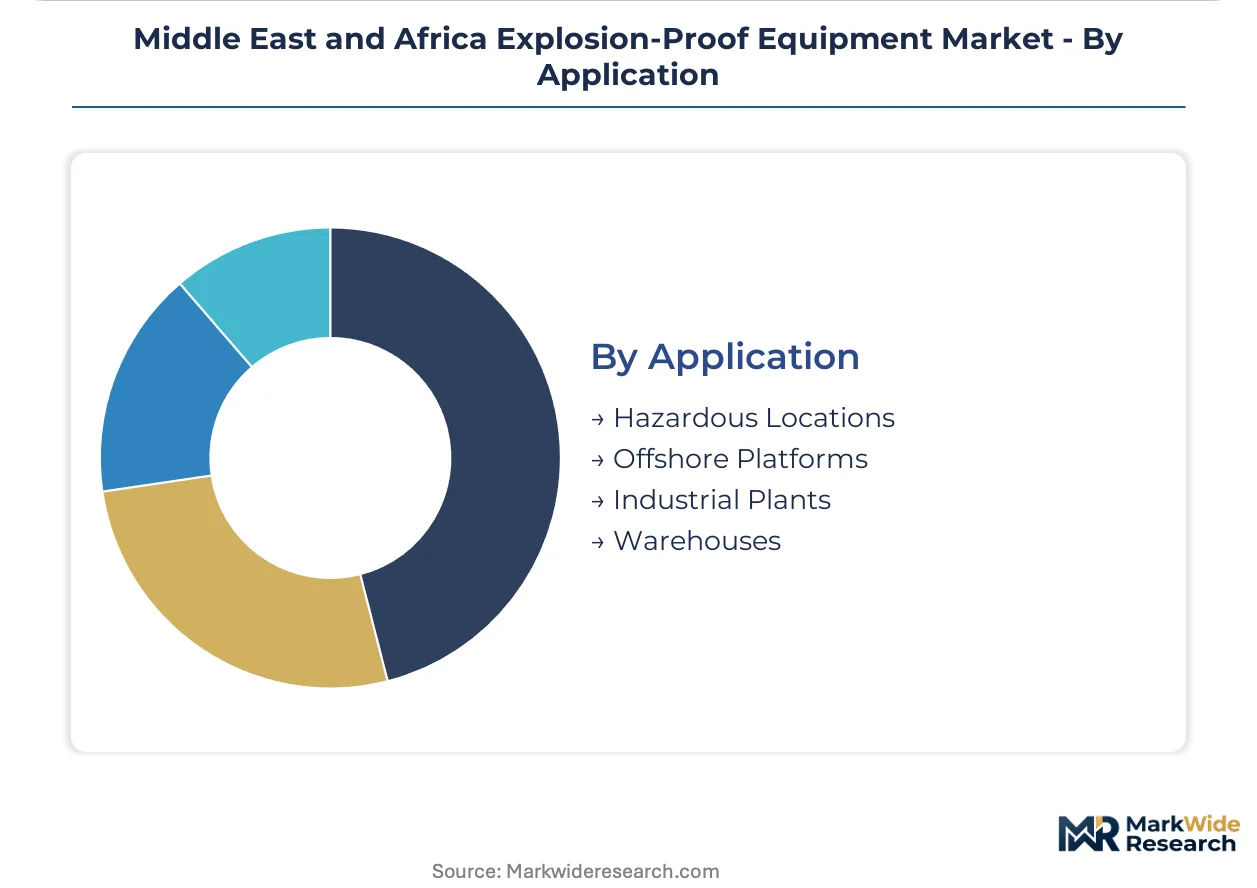
- Hazardous Locations:Zone 0, 1, and 2 classified areas across refineries and chemical plants require apparatus matched to gas group and temperature class specifications. SFDA's elimination of self-certification pathways has extended vendor qualification timelines for flameproof motors and switchgear.
- Offshore Platforms:Salt spray corrosion and space constraints on Nigerian and Angolan floating production facilities favor stainless steel Ex d enclosures with integrated heating elements to prevent condensation.
- Industrial Plants:Onshore processing complexes in Jubail, Ruwais, and Yanbu balance legacy flameproof infrastructure against incremental IS upgrades.
- Warehouses:Solvent storage and flammable liquid handling facilities in free trade zones require Zone 2-rated apparatus with simplified maintenance access.
Hazardous Locations retains dominant share. Offshore Platforms is expanding most quickly through West African deepwater project migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Gulf Cooperation Council petrochemical corridors while African mining jurisdictions absorb cost premiums from certification complexity. Saudi Arabia and the UAE command vendor attention through bundled national oil company contracts. South Africa and Nigeria represent volume expansion with margin compression from multi-standard compliance burdens.
Saudi Arabia
SFDA certification mandates for flameproof enclosures are eliminating self-certification pathways and extending vendor qualification timelines to eighteen months. The Jubail Industrial City complex drives retrofit demand for LED flameproof luminaires with T6 temperature ratings. Saudi Aramco's aging onshore processing facilities maintain flameproof infrastructure due to high-torque motor requirements exceeding intrinsic safety power limits.
United Arab Emirates
MOHAP's 2024 hazardous area equipment registration rules now mandate in-country testing for flameproof motors above 75kW, absorbing six-month lead time extensions. ADNOC's bundled procurement contracts favor integrated switchgear assemblies over component sourcing in offshore platform awards. The Ruwais petrochemical corridor concentrates newbuild specification of intrinsically safe architectures for distributed control systems.
South Africa
SANS standards enforced by the Department of Mineral Resources and Energy create additional testing burdens for platinum and gold mining suppliers. IECEx-SANS harmonization initiatives are reducing duplicate certification costs for equipment targeting the platinum belt. Johannesburg-based distributors serve underground extraction operations where depth constraints and ventilation limitations prioritize compact intrinsic safety designs.
Nigeria
Department of Petroleum Resources jurisdiction requirements overlap with IECEx alignment for offshore projects migrating North Sea-equivalent specifications. Floating production facilities in Nigerian deepwater favor stainless steel flameproof enclosures with integrated heating elements to prevent condensation. Lagos serves as the regional logistics hub for West African oilfield service procurement.
Egypt
Cairo Petroleum Refining Company expansion programs lack qualified local hazardous area equipment distributors, creating first-mover positioning for certified regional service partners. Refinery modernization across the Suez Canal zone is absorbing flameproof control systems as process safety management standards tighten. Alexandria's industrial free trade zones require Zone 2-rated apparatus with simplified maintenance access for solvent storage facilities.
Middle East and Africa Explosion-Proof Equipment Market Competitive Landscape
European engineering conglomerates and specialized hazardous area specialists split the market through divergent certification depth versus application focus. Vendor consolidation is compressing distributor networks as end users reduce compliance risk through shortened vendor lists. Three archetypes dominate: integrated electrical manufacturers with multi-territory accreditation, German-engineered flameproof assembly specialists, and intrinsic safety barrier technology leaders. Competitive positioning hardens through regional test facility establishment and long-term service contract bundling.
Within the integrated electrical manufacturer tier, Eaton Corporation plc and Siemens AG exemplify players leveraging regional certification depth to anchor large petrochemical contracts. Bartec Group occupies a position among German-engineered flameproof assembly specialists sustaining premium positioning in African mining jurisdictions. R. STAHL AG represents the intrinsic safety expertise archetype that dominates offshore specifications migrating to West African deepwater projects.
| Leading Market Players |
|---|
| ABB Ltd |
| Bartec Group |
| Eaton Corporation plc |
| Emerson Electric Co. |
| Hubbell Incorporated |
| R. STAHL AG |
| Rockwell Automation, Inc. |
| Siemens AG |
| Honeywell International Inc. |
| Others |
Supply & Pricing Matrix
Jebel Ali port freight corridors from Dubai to Lagos and Johannesburg absorb sulfur emission compliance surcharges that compound with copper and aluminum London Metal Exchange volatility, compressing margin buffers for flameproof enclosure fabricators while amplifying price spreads between IECEx-certified premium tiers and standard-grade alternatives.
Pricing Analysis
The customization-premium spread separates configured-to-order flameproof motor assemblies from standard switchgear catalogs, with project-based contract structures dominating national oil company procurement. Price differentiation hinges on SFDA/MOHAP certification tier and bundled after-sales service depth. Cost compression in standard-grade luminaires is intensifying because Saudi distributor consolidation forces volume discounts. Mid-tier petrochemical engineering contractors exhibit highest price sensitivity; offshore platform integrators show lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Upstream feedstock channels for explosion-proof equipment draw from German and Swiss IECEx component manufacturing, Chinese LED module production, and South African platinum-group metal sourcing for high-temperature gaskets. Copper casting and aluminum extrusion dependencies expose fabricators to commodity price swings. Single-source vulnerability concentrates in certified barrier device supply from Central European specialists. Distribution runs through Dubai-based regional stocking hubs serving Gulf national oil companies and Johannesburg distributors feeding platinum belt mining operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa explosion-proof equipment market represents a high-growth disruption as SFDA and MOHAP certification tightening eliminates self-certification pathways and forces eighteen-month vendor pre-qualification cycles that reshape competitive entry economics.
For Market Incumbents: Build certification moat depth through in-country test facility establishment in Riyadh and Dubai to compress MOHAP-mandated lead times for flameproof motors above 75kW. Anchor long-term service contracts with ADNOC and Saudi Aramco bundled procurement teams to lock out component-level challengers. Defend against German-engineered flameproof specialists by accelerating Ex ic intrinsic safety barrier R&D for chromatography sampling systems. For New Entrants and Emerging Players: Pursue Egyptian refinery modernization white space where Cairo Petroleum Refining Company expansion programs lack qualified local hazardous area distributors. Target West African deepwater migration as the most penetrable geography, where North Sea-equivalent EPL Ga specifications transfer without entrenched incumbent relationships. Lead with WirelessHART-integrated intrinsically safe power modules for cable-free tank farm monitoring as differentiated entry angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electrical conglomerates with under-monetized hazardous area divisions lacking regional certification depth. Long-term viability centers on vendors capturing recurring inspection revenue from SFDA third-party conformity assessment mandates. Watch IECEx-SANS harmonization progress in South Africa as signal for platinum belt margin expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| In-Country Test Facility Establishment | MOHAP's 2024 rules mandate Dubai-based certification for large flameproof motors, preserving UAE market access. |
| Intrinsic Safety Barrier R&D Investment | Ex ic architectures for Saudi Aramco chromatography systems displace legacy pressurized conduit seals. |
| Long-Term Service Contract Bundling | ADNOC offshore platform awards favor integrated instrumentation-enclosure-safety barrier procurement over component sourcing. |
| WirelessHART Convergence Development | Cable-free tank farm monitoring in UAE petrochemical corridors reduces maintenance access requirements. |
| Regional Distribution Hub Expansion | Johannesburg stocking positions capture SANS-compliant platinum belt mining demand with reduced lead times. |
Research Methodology
Desk research of IECEx certification registries, SFDA hazardous area equipment directives, and MOHAP registration databases preceded structured interviews with petrochemical procurement directors, mining maintenance engineers, and hazardous area system integrators. Primary fieldwork with plant managers at Jubail Industrial City complexes and Ruwais petrochemical corridors combined with secondary validation through national oil company tender documentation and Department of Mineral Resources and Energy SANS standard filings. Bottom-up equipment shipment analysis and top-down petrochemical capital expenditure tracking provided triangulation anchors.
Assumptions held fixed include SFDA and MOHAP regulatory trajectory, copper and aluminum price band ranges, and Gulf national oil company procurement consolidation patterns across the analysis window. Segmentation modeling spanned product type, protection technology, end-use industry, and regional regulatory cluster dimensions. CAGRs derived from equipment replacement cycle velocity and newbuild petrochemical facility commissioning schedules, with intrinsic safety penetration rates and West African offshore project migration as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in hydrocarbon capital expenditure cycles, London Metal Exchange pricing volatility, or IECEx-SANS harmonization timelines would shift the trajectory. Cross-checking against national oil company announced project pipelines and mining sector mineral resource statements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
GCC Protective Relay Market
Critical Infrastructure Protection
Europe Tank Protection Market
Critical Infrastructure Protection
Middle East and Africa Public Infrastructure Safety Market
Critical Infrastructure Protection
Global Threat Intelligence Platform Market
Critical Infrastructure Protection
Global Perimeter Protection Market
Critical Infrastructure Protection
Global Railway Platform Security Market
Critical Infrastructure Protection
Utilities Security Market
Critical Infrastructure Protection
Critical Infrastructure Protection Market
Critical Infrastructure Protection
North America Public Infrastructure Safety Market
Critical Infrastructure Protection
Asia-Pacific Public Infrastructure Safety Market
Critical Infrastructure Protection
Global Hazardous Area Equipment Market
Critical Infrastructure Protection
Tank Protection Market
Critical Infrastructure Protection
Infrastructure Protection Market
Critical Infrastructure Protection
Middle East Commercial Security Market
Critical Infrastructure Protection
Global High Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Counter Cyberterrorism Market