
 Instant Camera's Consumable Market | 2026-2036
Instant Camera's Consumable Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Camera's Consumable Market Insights
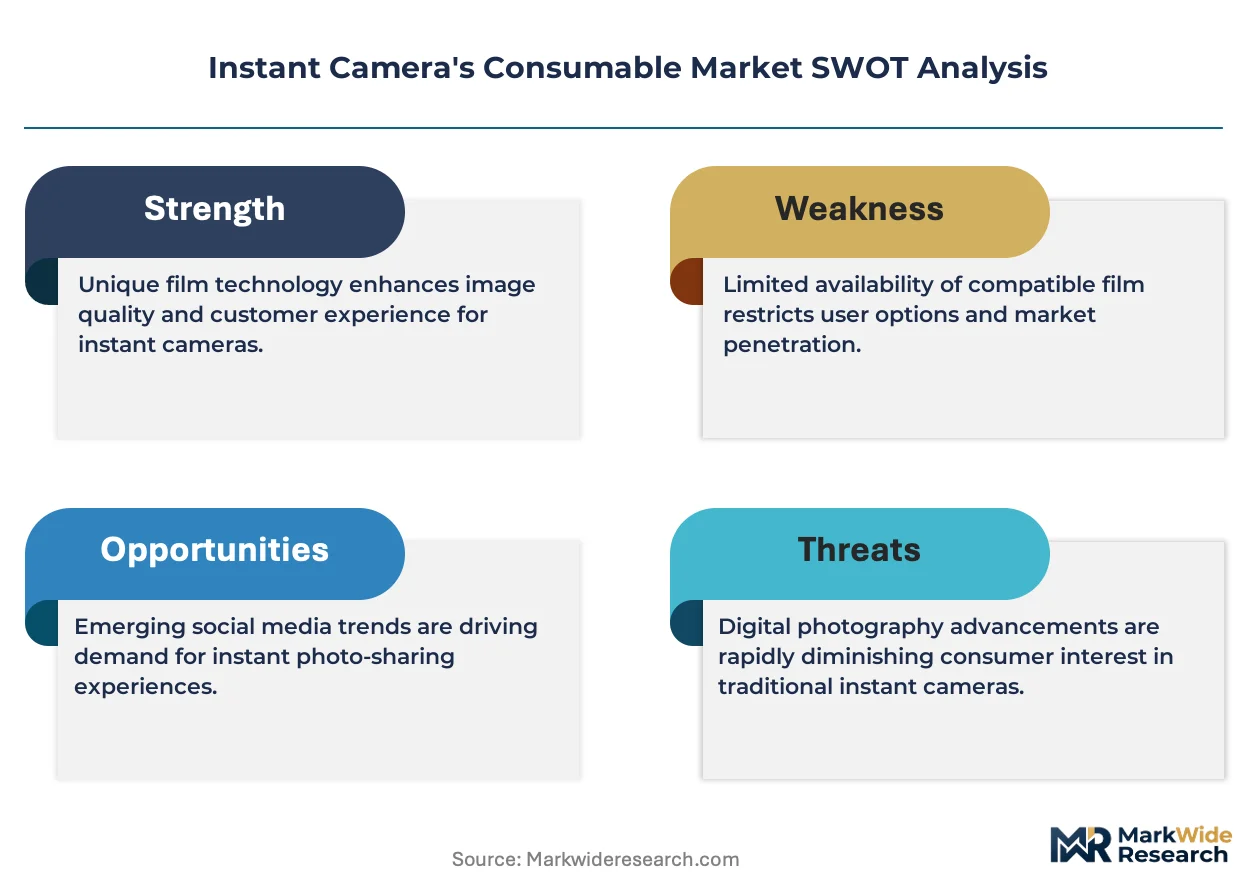
ISO 14001 environmental management certification is collapsing as a baseline qualifier for instant film suppliers seeking retail shelf space in European and North American channels. Fujifilm Holdings Corporation leverages its captive chemical synthesis capabilities to control emulsion supply from raw silver halide through finished cartridge. Polaroid Corporation anchors its position through proprietary i-Type film chemistry that blocks third-party compatibility. Kodak Alaris competes on heritage brand recognition and professional-portra film formulations.
Instant camera consumables encompass chemically treated photographic film, thermal receipt-grade paper, lithium-ion power cells, and optical lens filters engineered for dye-diffusion thermal transfer or zinc-oxide printing architectures. Film cartridges typically contain ten exposures of ISO 800 emulsion layered with developer pods activated through mechanical rollers during ejection. Film products command the dominant revenue share given per-unit premiums and repeat purchase frequency, while collector edition packaging extracts margin from limited-release collaborations with artists and fashion labels. Professional photography applications sustain the fastest expansion as studios adopt instant formats for client proofing and experiential shoots.
EPA hazardous waste rules govern silver recovery from spent film processing in the United States, while REACH compliance in Europe restricts phthalate plasticizers in cartridge housings and ECHA substance evaluations target developer chemistry alternatives. The EU F-Gas Regulation additionally pressures thermal printer refrigerant choices in instant photo kiosks. Stakeholders must monitor how evolving chemical disclosure mandates in multiple jurisdictions reshape formulation costs and whether battery-integrated cartridges face emerging e-waste take-back obligations.
Market Dynamics
EU REACH chemical disclosure mandates are forcing instant film manufacturers to reformulate developer pod chemistry and cartridge housing materials, compressing supplier margins while creating compliance differentiation among emulsion producers.
Growth Catalysts
- Professional photography adoption:Wedding studios and event agencies now procure instant film for client proofing workflows, creating recurring bulk orders that stabilize demand volatility.
- REACH alternative substance approvals:ECHA evaluations of non-phthalate plasticizers for cartridge housings are opening formulation pathways previously blocked by regulatory uncertainty.
- Japan's tangible media preference:Cultural attachment to physical photographs sustains premium consumable volumes unmatched by digital-native markets.
Market Restraints
- Silver halide supply concentration:Raw emulsion chemical synthesis clusters among three specialized suppliers, exposing film manufacturers to input price shocks.
- Thermal receipt paper substitution:Zinc-oxide printing architectures in budget instant cameras threaten dye-diffusion film volumes at the entry price tier.
- F-Gas refrigerant constraints:EU regulation of thermal printer coolants in instant photo kiosks limits equipment deployment flexibility in European retail channels.
Strategic Opportunities
- Collector edition packaging:Limited-release artist collaborations command 40-60% per-unit premiums over standard cartridges, extracting margin from scarcity-driven demand.
- Battery-integrated cartridge formats:Lithium-ion cell embedding enables all-in-one convenience for compact camera designs, differentiating against thermal paper alternatives.
- ISO 14001 certification gap:Environmental management credentials are collapsing as baseline retail requirements, creating first-mover advantage for early certifiers.
Industry Challenges
- Emulsion chemistry talent scarcity:Specialized knowledge of silver halide crystal growth and developer pod formulation concentrates among retiring chemists, constraining R&D pipeline velocity.
- Cross-jurisdiction compliance timelines:Simultaneous EPA hazardous waste rules for silver recovery and REACH substance evaluations force parallel reformulation tracks, stretching quality assurance resources.
Report Scope
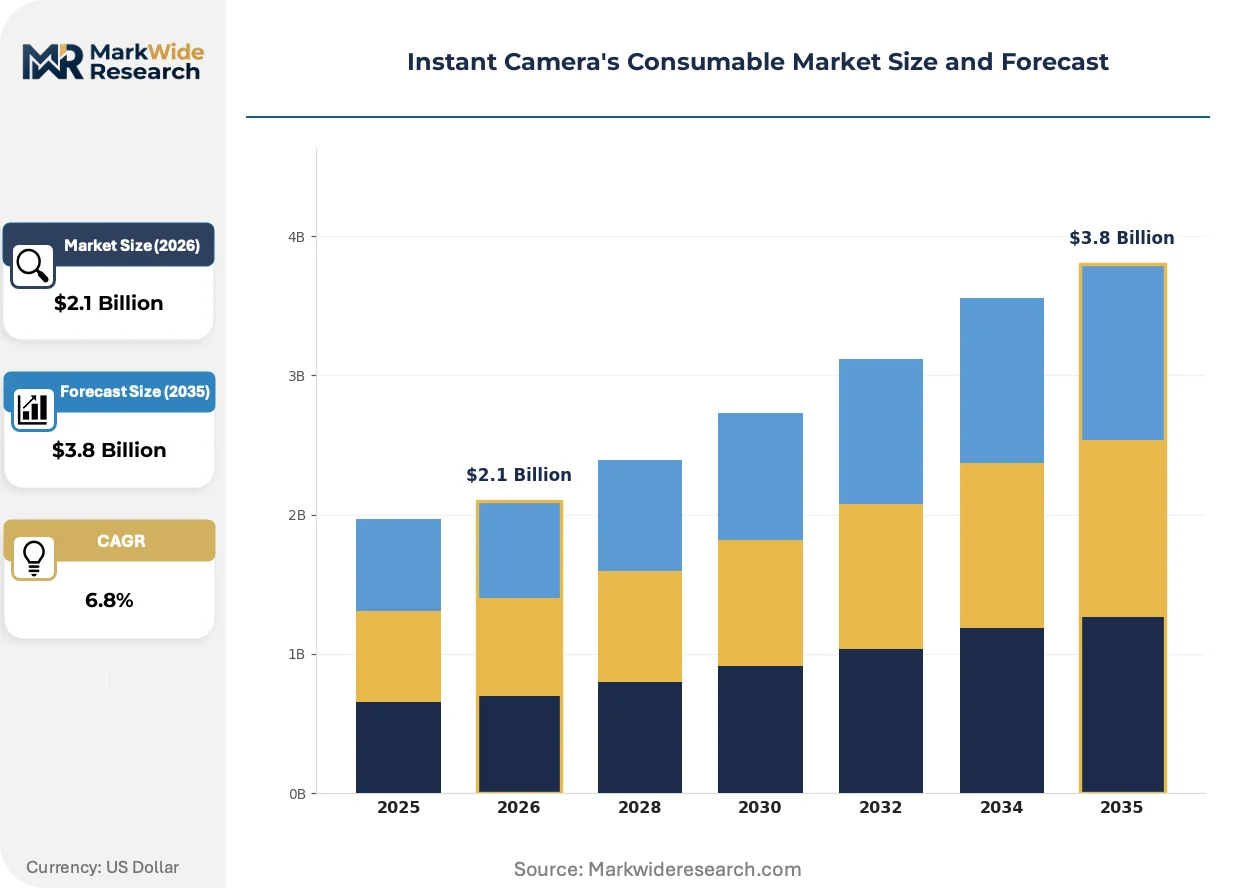
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Camera's Consumable Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Film, Paper, Batteries, Filters Application: Personal Use, Events, Professional Photography, Art Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale Packaging Type: Bulk Packs, Single Packs, Eco-Friendly Packs, Collector Editions |
| Companies Covered | Fujifilm Holdings Corporation, Polaroid Corporation, Lomographische AG, Leica Camera AG, Kodak Alaris, HP Inc., MiNT Camera, Canon Inc., Impossible Project, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Camera's Consumable Market Trends and Innovations
Instant consumable technology is fragmenting across two competing architectures while regulatory chemistry mandates and professional procurement patterns reshape competitive positioning. These intersecting forces determine which suppliers capture premium positioning versus commodity exposure.
Dye-diffusion thermal transfer emulsion technology is bifurcating the professional segment from consumer tiers. Wedding photographers and commercial studios specify ISO 800 cartridges with enhanced color stability, paying sustained premiums for archival-grade output. This split enables Fujifilm and Polaroid to maintain distinct product lines rather than converging on lowest-common-denominator formulations.
REACH substance restrictions on phthalate plasticizers and developer chemistry alternatives are forcing cartridge housing redesigns across European supply chains. ECHA evaluation timelines now determine product launch windows, with compliant formulations reaching retail shelves 8-14 months ahead of laggard competitors. German and French distributors are prioritizing suppliers with advance registration dossiers.
Event planners and photography studios are consolidating instant film procurement through direct manufacturer relationships, bypassing traditional wholesale distributors. This channel compression concentrates volume among larger professional accounts while squeezing margin for intermediaries. Japan and South Korea exhibit the most advanced direct-procurement penetration, with North American studios rapidly adopting the same model.
Instant Camera's Consumable Market Segmentation
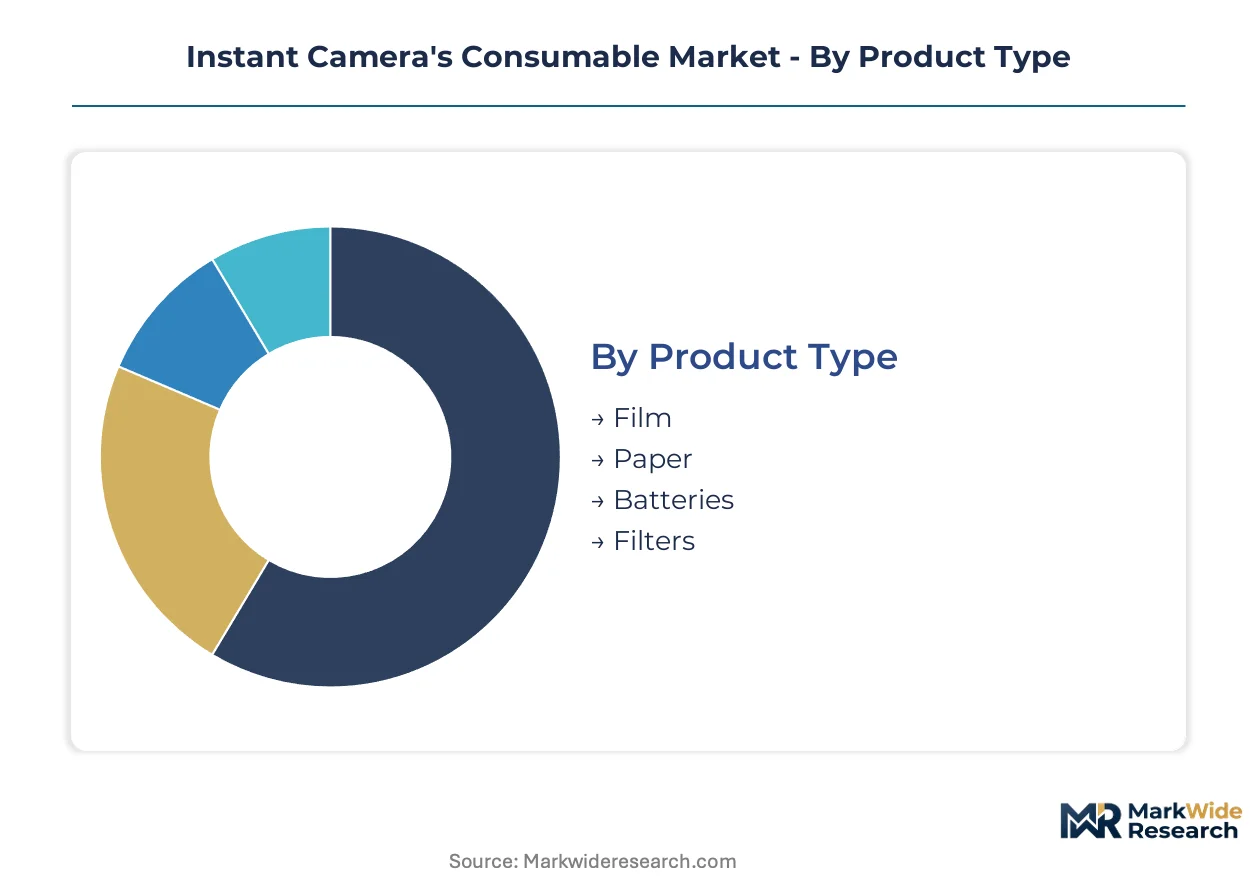
Instant camera consumables fragment across four distinct dimensions that determine pricing power, channel access, and regulatory exposure. Each segmentation layer reveals how suppliers capture margin through format specialization, end-use targeting, and packaging differentiation.
Product Type:
Film cartridges dominate domestic consumption in Japan, while paper and battery formats show stronger export-led growth into North American and European channels.
- Film:Chemically treated photographic emulsion layered with developer pods, typically ISO 800 sensitivity. Wedding studios in Japan and South Korea specify archival-grade formulations for client proofing workflows, paying sustained premiums for color stability.
- Paper:Thermal receipt-grade substrate engineered for zinc-oxide printing architectures. Budget camera manufacturers in China are displacing dye-diffusion volumes at the entry price tier through lower per-shot costs.
- Batteries:Lithium-ion power cells integrated into cartridge housings for compact camera designs.
- Filters:Optical lens attachments for color correction and special effects.
Film holds the largest share; momentum sits with paper formats gaining traction in cost-sensitive segments.
Application:
Professional use commands the steepest per-unit premiums, while personal consumption drives volume scale across mass retail channels.
- Personal Use:Casual photography for memory preservation and social sharing. Teenage consumers in Tokyo and Osaka sustain repeat purchase frequency through character-branded cartridge collaborations.
- Events:Wedding receptions, corporate gatherings, and milestone celebrations. Event planners in California and New York are consolidating procurement through direct manufacturer relationships, bypassing wholesale intermediaries.
- Professional Photography:Commercial studios and portrait specialists. Archival-grade emulsion specifications from German and French distributors prioritize suppliers with advance REACH registration dossiers.
- Art:Limited-edition collaborations and experimental formats. Gallery installations in London and Milan extract scarcity premiums from collector edition packaging.
Personal use generates the highest absolute volume; professional applications are climbing the fastest as studios formalize instant proofing workflows.
Distribution Channel:
Channel strategy bifurcates between convenience-driven mass retail and relationship-based professional supply.
- Online Retail:Direct-to-consumer platforms and marketplace listings. Subscription cartridge services from Osaka-based distributors are locking in recurring revenue from hobbyist collectors.
- Specialty Stores:Camera shops and photography equipment retailers. Staff expertise in Berlin and Paris locations drives upselling toward premium emulsion grades.
- Supermarkets:Mass-market shelf placement for impulse purchases. Seasonal promotional cycles in Tokyo convenience chains spike cartridge sales during holiday periods.
- Wholesale:Bulk supply to event agencies and institutional buyers. Margin compression is accelerating as professional accounts migrate toward direct manufacturer procurement.
Online retail commands expanding share; specialty stores retain pricing power through technical consultation.
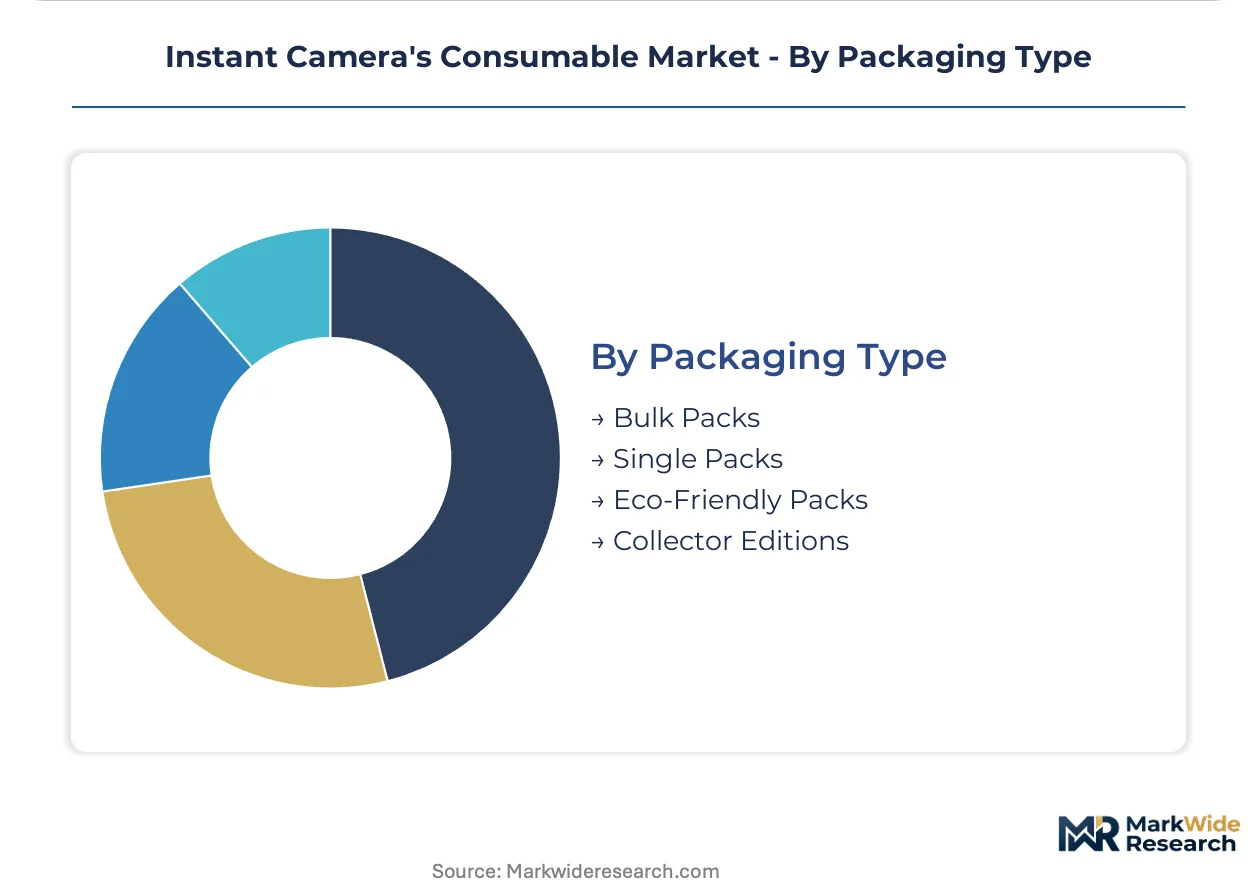
Packaging Type:
Packaging differentiation separates commodity volume plays from margin extraction through scarcity engineering.
- Bulk Packs:Multi-cartridge configurations for high-volume users. Wedding photography studios in Seoul and Los Angeles negotiate annual supply contracts against per-unit discounts.
- Single Packs:Individual cartridge sales for trial and occasional use. Airport retail locations in Frankfurt and Amsterdam capture tourist impulse purchases at premium markups.
- Eco-Friendly Packs:Reduced plastic housings and recyclable materials. EU REACH compliance on phthalate restrictions is accelerating adoption among German distributors seeking ISO 14001 certification alignment.
- Collector Editions:Artist collaborations and limited-release designs. Fashion label partnerships from Tokyo-based suppliers command 40-60% per-unit premiums over standard cartridges.
Bulk packs anchor volume; collector editions are gaining share fastest through scarcity-driven demand engineering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH chemical disclosure mandates and Japan's tangible media preference are reshaping formulation requirements and procurement patterns across key national markets.
Japan
Wedding photographers in Tokyo and Osaka sustain premium cartridge volumes through archival-grade emulsion specifications. METI standards on chemical substance management align with domestic manufacturer compliance frameworks. Fujifilm's domestic production base in Kanagawa Prefecture anchors captive supply from raw silver halide through finished cartridge.
Germany
Professional studios in Berlin and Munich prioritize suppliers with advance ECHA registration dossiers for phthalate-free cartridge housings. The EU F-Gas Regulation constrains thermal printer refrigerant choices in instant photo kiosks. Chemical formulation expertise concentrates in the Rhine-Ruhr industrial corridor, where compliance-first suppliers gain retail shelf priority.
United States
Event planners in California and New York are consolidating procurement through direct manufacturer relationships, bypassing wholesale intermediaries. EPA hazardous waste rules govern silver recovery from spent film processing in commercial darkrooms. Los Angeles-based wedding photography studios negotiate annual supply contracts against per-unit discounts for bulk cartridge configurations.
South Korea
Seoul's commercial photography sector drives demand for ISO 800 cartridges with enhanced color stability for client proofing workflows. MFDS chemical safety evaluations parallel REACH substance restrictions on developer pod chemistry. Direct-procurement penetration from Busan-based distributors exceeds North American adoption rates, locking in recurring revenue from professional accounts.
United Kingdom
Gallery installations in London and Manchester extract scarcity premiums from collector edition packaging collaborations with fashion labels. The UK's post-Brexit chemical regulatory framework maintains alignment with REACH substance restrictions through retained EU law. Specialty camera retailers in the Southeast region leverage staff expertise to upsell toward premium emulsion grades.
Instant Camera's Consumable Market Competitive Landscape
Player mix skews toward vertically integrated chemical conglomerates with captive emulsion synthesis capabilities. The market structure concentrates around three dominant suppliers controlling raw silver halide through finished cartridge production. Strategic archetypes include heritage brand licensors, captive chemical synthesizers, and boutique format specialists. Competitive moves center on proprietary chemistry lock-in and direct-to-professional channel compression.
Within the captive chemical synthesis tier, Fujifilm Holdings Corporation and Polaroid Corporation exemplify divergent approaches to supply chain control. Fujifilm leverages upstream integration from raw silver halide crystal growth through developer pod formulation. Polaroid anchors its position through proprietary i-Type film chemistry that blocks third-party cartridge compatibility. Kodak Alaris occupies a heritage-brand position competing on professional-portra film formulations and recognition among legacy photographers.
| Leading Market Players |
|---|
| Fujifilm Holdings Corporation |
| Polaroid Corporation |
| Lomographische AG |
| Leica Camera AG |
| Kodak Alaris |
| HP Inc. |
| MiNT Camera |
| Canon Inc. |
| Impossible Project |
| Others |
Pricing and Supply Chain Analysis
Captive emulsion synthesis capacity at Fujifilm's Kanagawa facility anchors supply-side scale economies that simultaneously compress competitor input costs and establish price floors for archival-grade film tiers. REACH compliance investments across European formulation lines feed back into supplier selection, with certified producers commanding shelf-space premiums that uncertified rivals cannot match.
Pricing Analysis
Certification level creates the primary spread between premium archival-grade cartridges and commodity thermal paper alternatives. Three-tier pricing structure across professional, enthusiast, and entry-level segments reflects ISO 14001 environmental credentials, volume contract scale, and emulsion chemistry complexity. Pricing pressure stems from zinc-oxide paper substitution in budget camera tiers. Event planners and wedding studios show lowest price sensitivity, while teenage casual users in Tokyo convenience chains exhibit highest elasticity.
Supply Chain Analysis
Inventory lead times for silver halide raw materials stretch 8-14 months ahead of ECHA registration dossier deadlines, forcing parallel formulation tracks. Supply concentrates in Japan, Germany, and South Korea for emulsion synthesis, cartridge assembly, and chemical precursor production respectively. The chain draws from silver mining concentrates, petrochemical-derived plasticizers, and lithium carbonate for integrated battery formats. Single-source vulnerability concentrates in specialized developer pod chemistry. Distribution runs through direct manufacturer relationships for professional accounts and specialty retail for enthusiast segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized knowledge of silver halide crystal growth and developer pod formulation concentrates among retiring chemists, constraining R&D pipeline velocity and consolidating advantage among incumbent chemical conglomerates with captive talent development programs.
For Market Incumbents: Compound backward integration into raw silver halide synthesis to defend against input price shocks from the three specialized chemical suppliers currently dominating emulsion feedstock. Prioritize ISO 14001 certification acceleration ahead of European retail baseline requirements. Channel control through direct-to-professional procurement relationships in Seoul and Los Angeles locks in recurring revenue against distributor margin compression. For New Entrants and Emerging Players: Anchor in collector edition packaging collaborations where 40-60% per-unit premiums offset volume scale disadvantages against vertically integrated incumbents. Target art gallery installations and fashion label partnerships in London and Milan as the most penetrable white-space segment. Pursue subscription cartridge services through Osaka-based distributor relationships as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors heritage brand licensors with dormant chemical synthesis assets that can be reactivated against REACH-driven formulation turnover. Long-term viability hinges on whether dye-diffusion thermal transfer retains professional segment loyalty against zinc-oxide paper cost compression. Acquisition target archetype: boutique format specialists with established artist collaboration pipelines. Watch ECHA alternative substance approval timelines as the critical inflection signal for compliant formulation first-mover advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver Halide Synthesis | Fujifilm's Kanagawa captive supply chain insulates margins from raw material price volatility. |
| REACH-Compliant Formulation Redesign | ECHA registration dossiers determine 8-14 month retail shelf priority windows in German and French channels. |
| Direct-to-Professional Procurement Channels | Los Angeles wedding studios bypass wholesale intermediaries through annual supply contract negotiations. |
| Collector Edition Artist Collaborations | Tokyo fashion label partnerships extract scarcity premiums from limited-release cartridge designs. |
| Battery-Integrated Cartridge Development | Lithium-ion embedding differentiates compact camera formats against zinc-oxide thermal paper alternatives. |
Research Methodology
Initial hypotheses were tested against primary input from emulsion chemistry R&D directors, wedding photography studio procurement leads, European specialty retail buyers, and instant camera equipment distributors, then refined through secondary validation against ECHA substance registration databases, METI chemical safety filings, EPA hazardous waste compliance records, and customs trade flow data. Bottom-up cartridge volume estimates from professional studio survey responses were triangulated against top-down market value reconstruction from manufacturer revenue disclosures.
Variance decomposition across the projection horizon isolates volume drivers by product type, application tier, distribution channel, and regional regulatory cluster. CAGRs were derived from segment-level growth rate reconciliation against aggregate market trajectory. Forecast inputs incorporated REACH alternative substance approval timelines, silver halide supply concentration risk factors, and channel migration patterns from wholesale toward direct procurement.
Decision-makers should treat outputs as directional under sustained professional photography adoption and stable silver halide feedstock availability assumptions; material deviation would warrant model refresh. Forecasts embody these base conditions alongside ECHA evaluation pace and thermal paper substitution rates. Revision becomes warranted when zinc-oxide printing architecture penetration crosses professional segment acceptance thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Dive Computer Market
Consumer Electronics
Smart Audio Devices Market
Consumer Electronics
Headsets for PC Market
Consumer Electronics
Kindle E-Reader Accessories Market
Consumer Electronics
Consumer Electronics Repair and Maintenance Market
Consumer Electronics
China Refurbished Smartphone Market
Consumer Electronics
Pool Speakers Market
Consumer Electronics
Pillow Holder for Tablets Market
Consumer Electronics
Handheld Device Accessories Market
Consumer Electronics
Zipline Kits Market
Consumer Electronics
Wet Wipes Market
Consumer Electronics
Consumer Electronics Retail Market
Consumer Electronics
Vape Cartridge Market
Consumer Electronics
China Massage Equipment Market
Consumer Electronics
United States Soundbar Market
Consumer Electronics
Gaming Laptop Market