
 United States Smart TV Market | 2026-2036
United States Smart TV Market Size, Share, and Industry Trends Forecast 2026-2036
United States Smart TV Market Outlook
Fragmentation across streaming-first households is repositioning purchase authority from traditional retail channels toward platform-direct and OEM-native ecosystems. Samsung Electronics leverages its captive semiconductor supply chain to sustain margin control across QLED and Mini-LED lineups. LG Electronics anchors its competitive stance through OLED panel specialization and content partnership integration.
A smart television integrates internet connectivity, embedded operating systems, and application platforms into a display device, typically featuring 4K or 8K resolution panels with HDR processing and voice-controlled interfaces for content streaming and home automation. LED displays occupy the highest unit volume tier due to accessible price positioning, while OLED and Mini-LED segments capture disproportionate margin pools from residential buyers seeking contrast performance and localized dimming precision. Wi-Fi connectivity dominates installation profiles, though Ethernet retains share in commercial and hospitality deployments where bandwidth stability governs content delivery quality.
FCC regulations governing spectrum allocation and device electromagnetic compatibility shape hardware certification requirements for all manufacturers selling into the United States. Energy Star standards administered by the EPA influence panel efficiency targets and standby power thresholds, directly affecting product design cycles and cost structures. Stakeholders must monitor ATSC 3.0 rollout velocity and state-level right-to-repair legislation as these forces will determine firmware update obligations and aftermarket service economics.
Market Dynamics
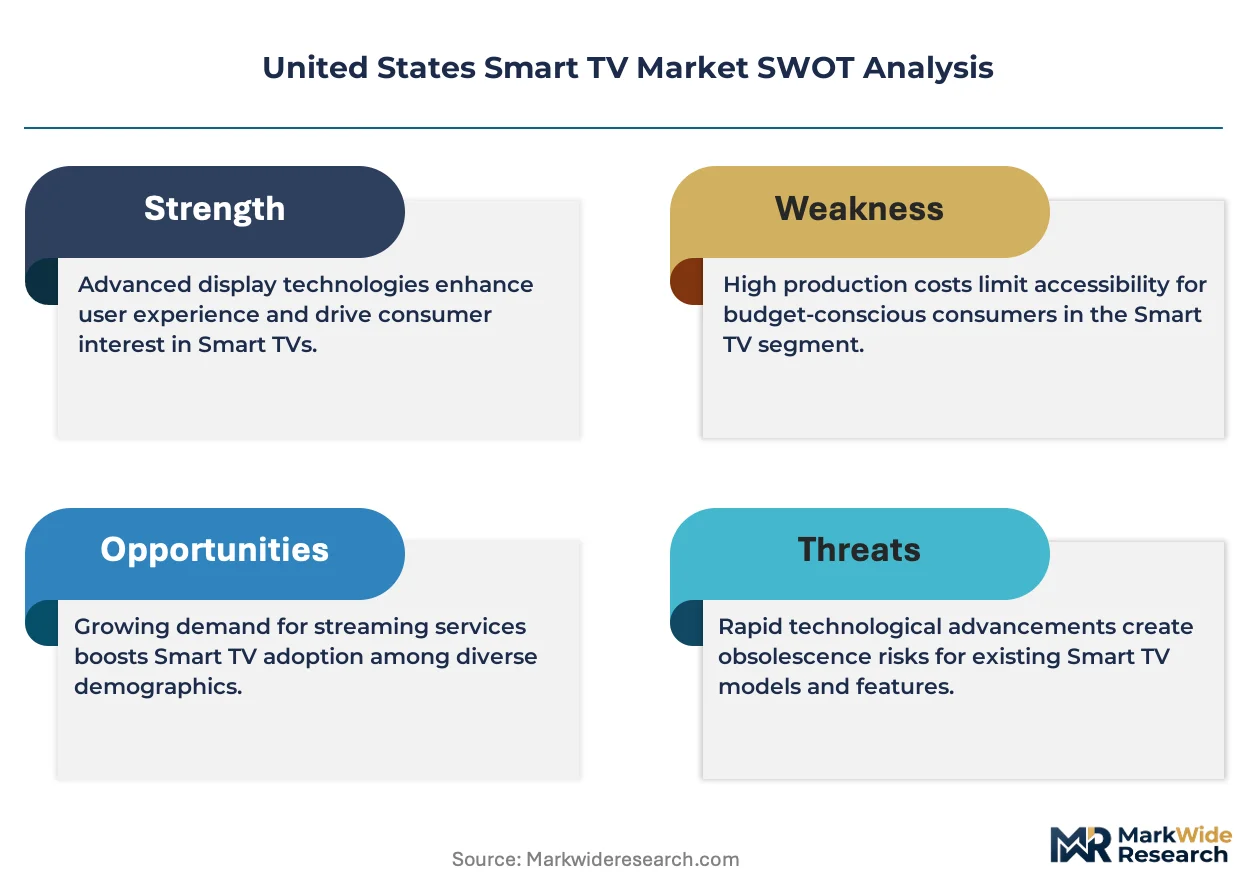
ATSC 3.0 broadcast standard deployment is rewriting connectivity requirements across the United States Smart TV Market, forcing manufacturers to redesign tuner modules and antenna architectures while state-level right-to-repair legislation creates parallel firmware obligations.
Growth Catalysts
- FCC Broadband Equity Access and Deployment Program:Fiber-to-the-home infrastructure subsidies in California and Texas metro corridors accelerate residential refresh cycles for 4K and 8K panel upgrades.
- Streaming platform bundling:Residential buyers concentrate purchase authority through platform-direct ecosystems, shifting volume toward OEM-native operating systems with integrated content partnerships.
- Mini-LED backlighting:Precision localized dimming technology captures disproportionate margin pools from contrast-sensitive buyers in premium residential segments.
Market Restraints
- Panel input cost volatility:Glass substrate and driver IC pricing fluctuations compress assembly margins for LED and QLED lineups during supply tightness.
- Semiconductor supply concentration:Captive foundry capacity at Korean and Taiwanese integrated manufacturers creates allocation risk for SoC and timing controller procurement.
- Energy Star standby power thresholds:EPA efficiency mandates extend product design cycles and raise certification costs for entry-tier models.
Strategic Opportunities
- Hospitality vertical underpenetration:Commercial deployment of smart displays with Ethernet-backhauled content management systems remains below saturation in Texas and Florida resort corridors.
- Voice assistant convergence:Integration of far-field microphone arrays with home automation protocols creates new attach-rate potential in California connected-home clusters.
- State right-to-repair tailwinds:Minnesota and California repair-access legislation generates aftermarket service revenue streams independent of OEM control.
Industry Challenges
- Firmware engineering talent scarcity:Embedded Linux and real-time OS specialization shortages delay ATSC 3.0 tuner integration timelines.
- HDMI 2.1 certification backlog:Compliance testing queue congestion at authorized test centers extends product launch windows for 8K 120Hz models.
- Legacy hospitality CMS integration:Proprietary content management protocols in installed commercial bases create friction for smart TV platform swaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Smart TV Market |
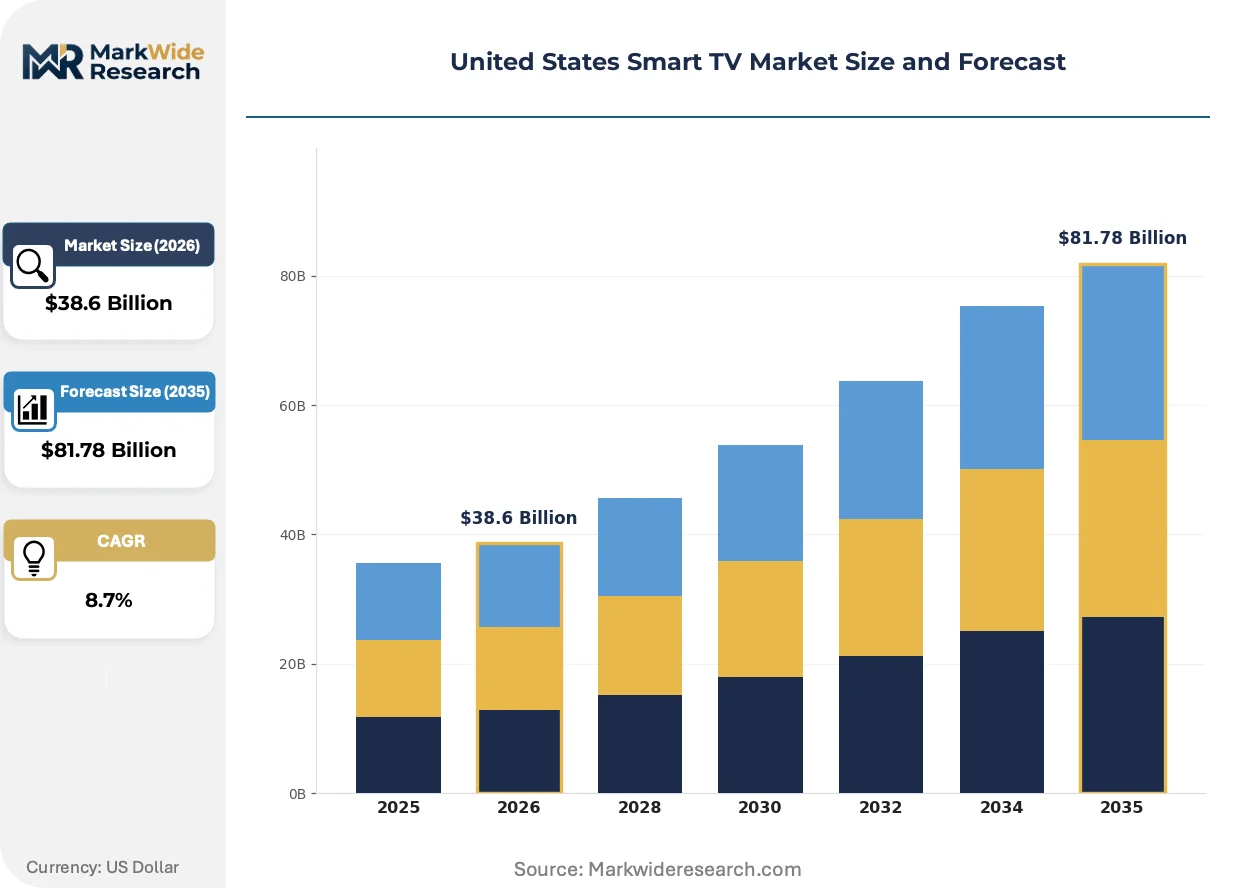
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, QLED, Mini-LED Connectivity: Wi-Fi, Ethernet, Bluetooth, HDMI End User: Residential, Commercial, Educational, Hospitality Price Tier: Economy, Mid-range, Premium, Luxury |
| Companies Covered | Hisense, Vizio, Samsung Electronics, Panasonic Holdings Corporation, Sharp Corporation, LG Electronics, Sony Group Corporation, Apple Inc., TCL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Smart TV Market Strategic Shifts
Display technology evolution and regulatory mandates are compressing product lifecycles while redistributing value capture across semiconductor, panel, and content layers.
Mini-LED backlighting with thousands of dimming zones is rewriting contrast performance expectations in the United States Smart TV Market. Residential buyers in premium segments adopt these sets at three-year replacement intervals, compressing the traditional five-to-seven-year television ownership cycle and forcing OLED specialists to accelerate manufacturing yield improvements.
EPA Energy Star Version 8.1 efficiency standards impose stricter active-mode power limits on panels above 65 inches. Manufacturers respond by redesigning power supply architectures and backlight driving schemes, with California and New York retail channels most affected due to state-level appliance efficiency regulations that reference federal benchmarks.
Platform-direct purchasing through OEM-native app stores displaces traditional retail bundling in the United States Smart TV Market. Streaming service subscription attach at point of activation generates recurring revenue that subsidizes hardware pricing, with this behavior most visible in Texas and Florida metro areas where fiber deployment enables 4K streaming without buffering friction.
United States Smart TV Market Segmentation
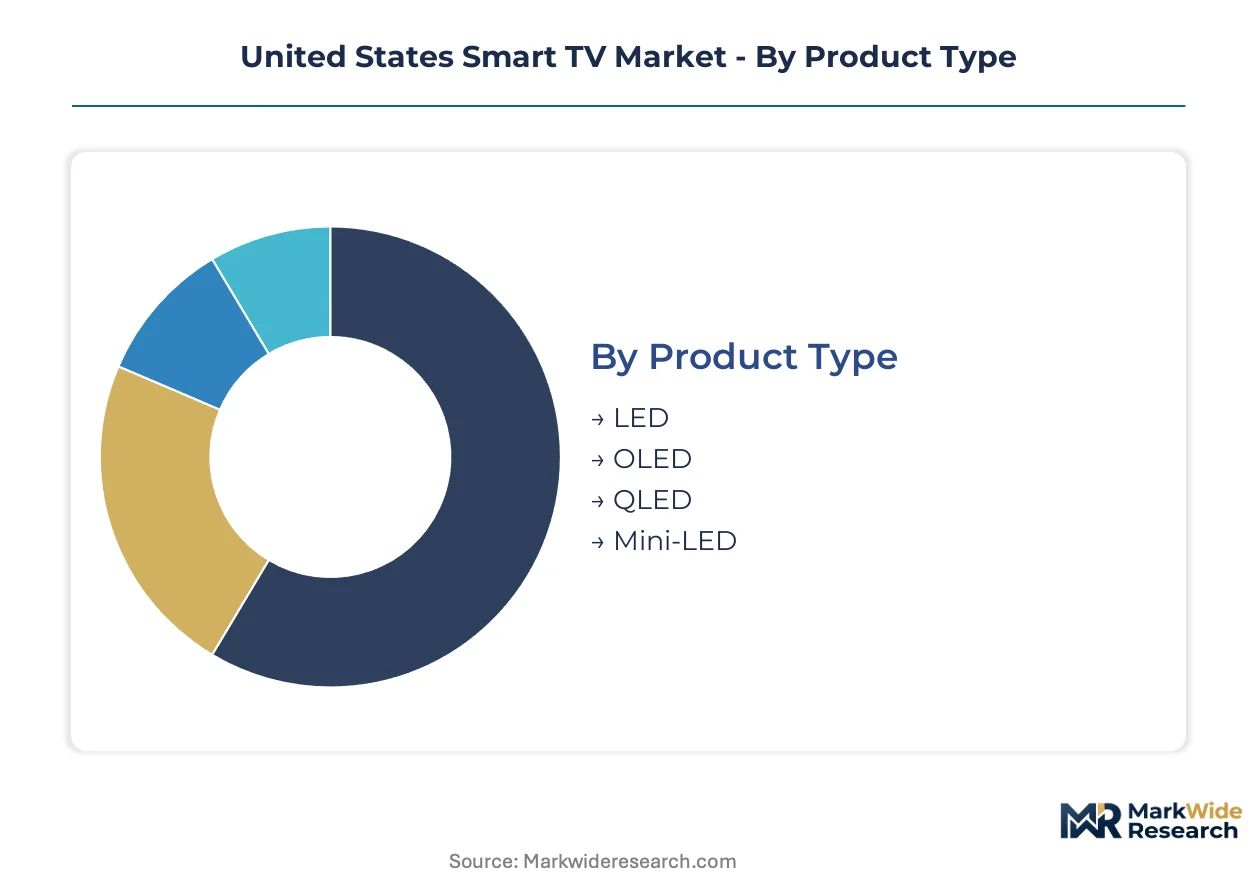
Smart TV segmentation reveals how capital deployment, connectivity infrastructure, and buyer sophistication stratify demand across the United States. Each dimension exposes distinct margin structures and refresh cycle dynamics that manufacturers must navigate.
Product Type:
Capital intensity varies sharply across display technologies, with OLED and Mini-LED fabrication requiring specialized equipment and cleanroom investment that LED backplane assembly avoids.
- LED:Edge-lit and direct-lit LCD architectures dominate unit economics through mature supply chains and standardized driver IC procurement. California and Texas residential buyers refresh these sets at compressed intervals as fiber-to-the-home deployment enables 4K streaming without buffering constraints.
- OLED:Self-emissive organic compound deposition demands vacuum thermal evaporation equipment and pixel-level burn-in mitigation engineering. Premium residential segments in New York and Los Angeles metro corridors absorb these sets despite three-year replacement cycles driven by static image retention risks.
- QLED:Quantum dot film integration enhances color gamut through photoluminescent nanoparticle layers.
- Mini-LED:Thousands of localized dimming zones deliver contrast performance approaching OLED with higher peak luminance.
LED absorbs the bulk of installed capacity; Mini-LED is expanding most quickly.
Connectivity:
Installation environment dictates hardware cost layering, with commercial deployments demanding redundant physical interfaces that residential Wi-Fi-centric designs eliminate.
- Wi-Fi:Dual-band and Wi-Fi 6E modules enable cord-free streaming across residential installations. Texas and Florida fiber corridors concentrate demand where 4K HDR bitrates exceed 25 Mbps and mesh network coverage eliminates dead zones.
- Ethernet:Gigabit RJ45 ports guarantee bandwidth stability for hospitality CMS backhauls and commercial digital signage. Florida resort corridors and Texas convention centers require these interfaces where concurrent 4K streams demand deterministic latency.
- Bluetooth:Low-energy protocols support peripheral pairing for soundbars and remote controls.
- HDMI:2.1 specification ports handle 8K 120Hz and variable refresh rate signaling for gaming applications.
Wi-Fi dominates residential attach rates; Ethernet retains commercial pricing premiums.
End User:
Procurement authority concentrates differently across verticals, with hospitality buyers negotiating fleet pricing through GPOs while residential purchases fragment across platform-direct and retail channels.
- Residential:Streaming-first households drive volume through OEM-native operating systems with integrated content partnerships. California and Texas metro buyers concentrate purchase authority where fiber-to-the-home deployment accelerates 4K and 8K panel upgrades.
- Commercial:Corporate campuses and retail environments deploy smart displays for internal communications and customer-facing signage. Minnesota and Illinois office corridors absorb these units where Ethernet-backhauled content management systems require deterministic bandwidth.
- Educational:K-12 and university procurement cycles refresh classroom displays through E-Rate funding programs.
- Hospitality:Hotel and resort operators underinvest in smart TV deployment relative to streaming device provisioning. Texas and Florida resort corridors present expansion headroom where proprietary CMS integration friction has stalled platform swaps.
Residential absorbs the bulk of unit volume; hospitality presents the steepest expansion trajectory.
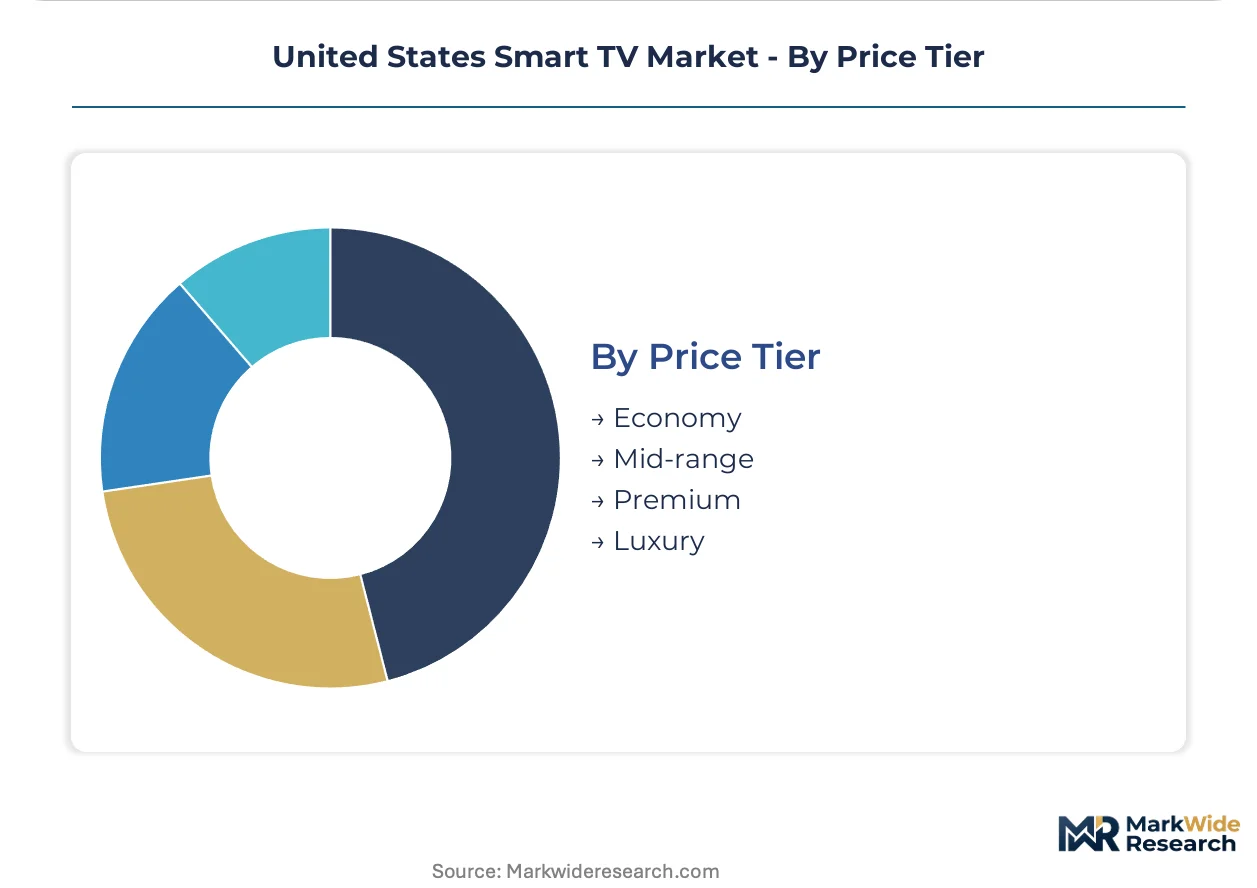
Price Tier:
Margin extraction stratifies across certification thresholds and panel performance specifications, with luxury tiers commanding hand-assembly and concierge delivery economics.
- Premium:65-inch and larger panels with full-array local dimming and advanced HDR processing capture disproportionate margin pools. California and New York buyers concentrate here where Energy Star Version 8.1 efficiency regulations filter entry-tier competition from retail channels.
- Luxury:77-inch and 83-inch OLED and Mini-LED sets with custom calibration and white-glove installation services. Los Angeles and Manhattan residential clusters absorb these units where home theater integration demands professional ISF certification.
- Economy:43-inch to 55-inch LED sets with basic smart platforms and limited app ecosystems.
- Mid-range:55-inch to 65-inch QLED and entry Mini-LED offerings balance performance and accessibility.
Premium captures the bulk of profit contribution; luxury is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential demand concentrates in coastal and Sun Belt metro corridors where fiber infrastructure enables 4K streaming without buffering friction. FCC broadband subsidies and state-level efficiency regulations reshape procurement patterns across distinct sub-regional clusters.
California
Los Angeles and San Francisco Bay Area buyers drive premium-tier volume through platform-direct purchasing and integrated content ecosystems. California Energy Commission appliance efficiency standards filter entry-tier competition from retail channels. Silicon Valley connected-home clusters accelerate voice assistant convergence and home automation protocol integration.
Texas
Dallas-Fort Worth and Houston metro corridors absorb disproportionate Mini-LED and QLED volume as fiber-to-the-home deployment accelerates refresh cycles. FCC Broadband Equity Access and Deployment Program subsidies target underserved census tracts in rural counties. Austin and San Antonio hospitality corridors present underpenetrated commercial deployment headroom for Ethernet-backhauled content management systems.
New York
Manhattan and Brooklyn residential clusters absorb luxury-tier OLED sets despite compressed replacement intervals driven by static image retention risks. New York State appliance efficiency regulations reference federal Energy Star benchmarks with additional standby power constraints. Rochester and Buffalo commercial corridors deploy smart displays for corporate campus internal communications and customer-facing signage.
Florida
Miami and Orlando resort corridors underinvest in smart TV deployment relative to streaming device provisioning, creating hospitality vertical expansion potential. Florida state procurement regulations govern E-Rate funded educational display refresh cycles in K-12 districts. Tampa and Jacksonville fiber deployment enables platform-direct purchasing behavior mirroring Texas metro patterns.
Illinois
Chicago metro commercial buyers concentrate procurement of Ethernet-equipped displays for deterministic bandwidth in office and retail environments. Illinois state right-to-repair legislation generates aftermarket service revenue streams independent of OEM control. Peoria and Springfield educational institutions refresh classroom displays through federal E-Rate funding programs with extended procurement cycles.
United States Smart TV Market Competitive Environment
Korean and Japanese producers anchor the premium display tier; Chinese fabricators hold volume positioning through cost-optimized LED assembly. The vendor base stratifies across three structural tiers: vertically integrated panel manufacturers with captive semiconductor supply, platform-native specialists with embedded operating system ecosystems, and contract-assembled value brands leveraging open-source smart platforms. Dominant competitive moves include backward integration into driver IC and timing controller procurement, plus strategic content partnership bundling at point of activation.
Within the integrated-manufacturer tier, Samsung Electronics and LG Electronics exemplify divergent technology specialization strategies. Samsung Electronics leverages captive semiconductor foundry capacity to sustain margin control across QLED and Mini-LED lineups, while LG Electronics anchors positioning through OLED panel specialization and content partnership integration. TCL represents the scale-driven archetype, occupying volume positioning through cost-optimized assembly and platform licensing rather than captive component supply.
| Leading Market Players |
|---|
| Hisense |
| Vizio |
| Samsung Electronics |
| Panasonic Holdings Corporation |
| Sharp Corporation |
| LG Electronics |
| Sony Group Corporation |
| Apple Inc. |
| TCL |
| Others |
Value Chain & Pricing Dynamics
Residential streaming-first households demanding 4K HDR panels with ATSC 3.0 tuners are forcing assembly lines to absorb glass substrate and driver IC volatility while compressing entry-tier margins.
Pricing Analysis
Volume concentrates in LED sets where three-tier pricing structure across premium, standard, and economy levels filters buyers by certification grade and after-sales service bundling. Price differentiation stems from Energy Star Version 8.1 compliance costs and brand premium capture in California retail channels. Pricing pressure stems from panel input cost volatility compressing assembly margins during supply tightness. Economy-tier buyers exhibit highest price sensitivity; luxury-tier buyers absorb custom calibration and white-glove delivery premiums.
Supply Chain Analysis
Trans-Pacific freight rate fluctuations and port congestion at Long Beach and Savannah shape landed cost structures for Korean and Taiwanese component imports. Panel fabrication draws from South Korea, Taiwan, and China for glass substrates, driver ICs, and timing controllers. Raw material dependencies include photoluminescent quantum dot films, organic OLED compounds, and Mini-LED backlighting arrays. Single-source vulnerability concentrates in captive foundry capacity for SoC procurement. Distribution runs through big-box retail chains, platform-direct OEM storefronts, and hospitality GPO procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Smart TV Market sits in a technology-transition phase as Mini-LED localized dimming displaces edge-lit LED dominance in premium residential segments.
For Market Incumbents: Hedge against OLED burn-in perception risks by accelerating Mini-LED yield improvements and securing captive semiconductor allocation through Korean foundry partnerships. Deepen backward integration into driver IC procurement to defend margin control when glass substrate pricing tightens. For New Entrants and Emerging Players: Far-field microphone array integration with home automation protocols offers a technology-first wedge into California connected-home clusters. Target hospitality verticals in Texas and Florida resort corridors where proprietary CMS friction has stalled incumbent platform swaps. Pursue white-label Ethernet-equipped deployments for commercial digital signage through regional AV integrators. For Investors and Strategic Acquirers: The window for entry favors vertically integrated panel manufacturers with captive semiconductor supply and embedded OS ecosystems. Long-term viability rests on ATSC 3.0 tuner integration capabilities and content partnership depth. Watch Minnesota and California right-to-repair enforcement velocity as the signal for aftermarket service revenue inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ATSC 3.0 Tuner Integration | FCC broadcast standard compliance secures retail channel access in California and Texas metro corridors. |
| Mini-LED Backlighting Scale-Up | Thousands of dimming zones capture premium residential margin pools from contrast-sensitive buyers. |
| Platform-Direct Content Partnership | Streaming subscription attach at activation subsidizes hardware pricing for OEM-native ecosystems. |
| Voice Assistant Protocol Convergence | Far-field microphone arrays penetrate California connected-home clusters with home automation integration. |
| Hospitality CMS Integration | Ethernet-backhauled content management systems unlock underpenetrated Texas and Florida resort verticals. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with display panel procurement managers, hospitality technology directors, retail category buyers, and FCC regulatory affairs specialists provided operational validation. Secondary sources included EPA Energy Star certification databases, SEC 10-K filings from listed electronics manufacturers, and FCC equipment authorization records. Bottom-up unit shipment estimates triangulated against top-down consumer electronics spending benchmarks.
Segmentation-level modeling tracked display technology, connectivity interface, end-user vertical, and price tier across the analysis window. CAGRs derived from logistic adoption curves fitted to broadband infrastructure deployment timelines and streaming platform penetration rates. Forecast inputs incorporated ATSC 3.0 rollout velocity assumptions and state-level right-to-repair legislative progression.
Several conditions sit outside the modeled scope, including geopolitical trade policy shifts affecting semiconductor tariffs and unanticipated broadcast standard regulatory delays. Forecasts reflect documented assumptions about fiber-to-the-home deployment cadence and streaming service bundling economics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Portable Media Player Market
Consumer Electronics
Global White Noise Machines Market
Consumer Electronics
Keycap Market
Consumer Electronics
Middle East and Africa Mobile Phone Accessories Market
Consumer Electronics
Smart DJ Controller Market
Consumer Electronics
Waterproof Bathroom TV Market
Consumer Electronics
DVD Remote Controls Market
Consumer Electronics
Digital Cloud Picture Frame Market
Consumer Electronics
Japan Gaming Peripherals Market
Consumer Electronics
Global Bluetooth Mono Earpieces Market
Consumer Electronics
FMCG Market
Consumer Electronics
Waterproof Headphones Market
Consumer Electronics
Asia-Pacific Mobile Phone Accessories Market
Consumer Electronics
Russia Gaming Gadgets Market
Consumer Electronics
UAE Consumer Electronics Market
Consumer Electronics
Vape Market