
 Refurbished Electronics Market | 2026-2036
Refurbished Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Refurbished Electronics Market Outlook
Asian contract refurbishers is hardening as the dominant supply base for global consumer electronics returns. Dell Technologies leverages direct-to-business refurbishment programs to sustain enterprise relationships and reduce new-unit pressure. Apple anchors premium certified pre-owned pricing through rigorous functional testing and original component replacement protocols.
Refurbished electronics constitute pre-owned devices restored to verified functional condition through diagnostic testing, component replacement, and cosmetic grading against original manufacturer specifications. The primary commercial purpose centers on extending product lifecycles while delivering cost reductions of 30-50% versus new equivalents for price-sensitive buyers. Smartphones occupy the highest volume tier within product type segmentation, though laptops command stronger margin pools due to enterprise procurement reliability requirements. Certified Refurbished condition units dominate value capture across distribution channels, as warranty-backed quality assurance differentiates these from unverified used alternatives.
The EU's Ecodesign for Sustainable Products Regulation and the US EPA's electronics recycling standards are tightening material traceability and repairability mandates that reshape product eligibility for resale. India's BIS certification requirements for refurbished imports add compliance layers that filter low-quality suppliers from formal channels. Stakeholders must monitor how right-to-repair legislation evolves across multiple jurisdictions, as interoperability and parts availability rules directly determine which device generations remain economically refurbishable.
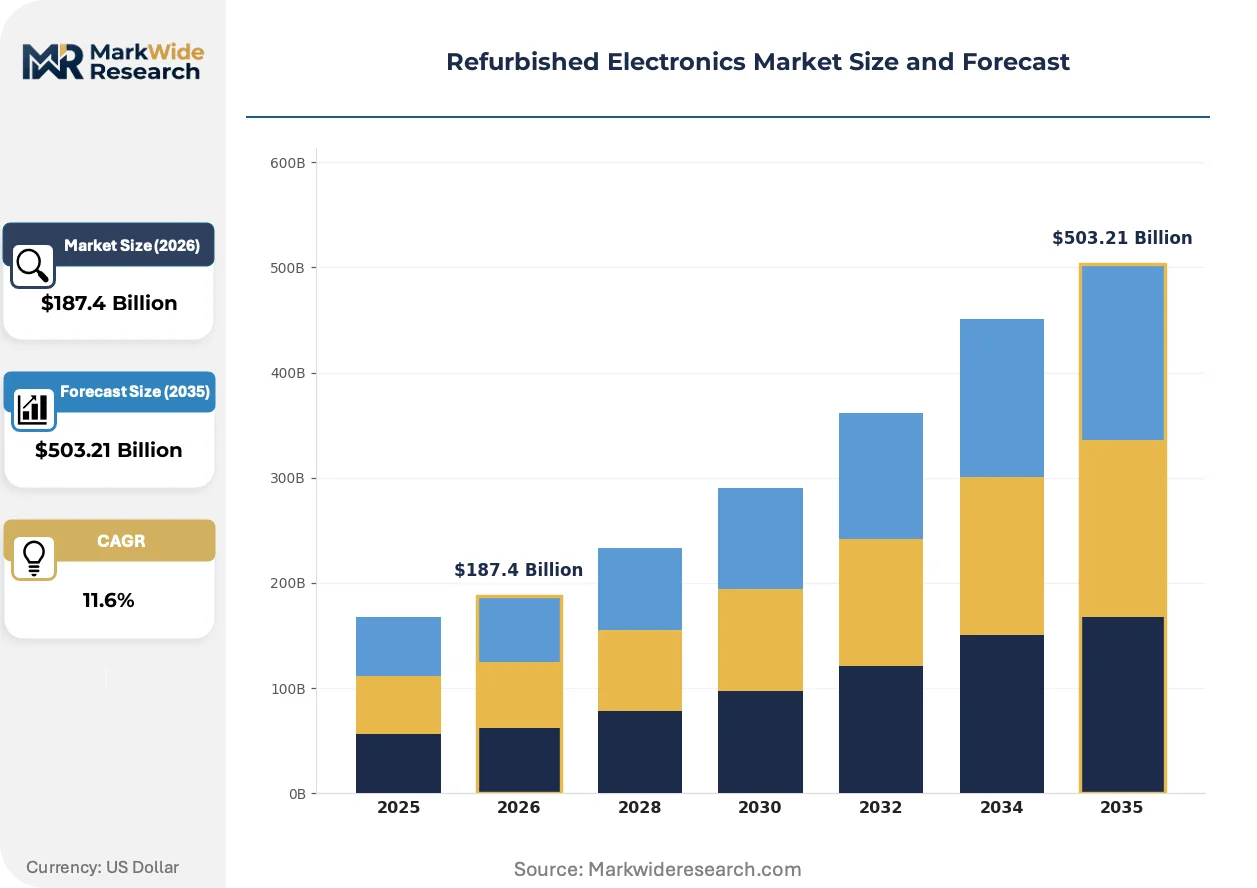
Market Dynamics
Enterprise IT procurement teams now treat certified refurbishment as a primary sourcing tier rather than a cost-cutting exception, driven by mandatory Scope 3 emissions disclosure requirements under the EU CSRD and similar frameworks.
Growth Catalysts
- EU Ecodesign Regulation:Mandatory repairability scoring for smartphones and laptops expands the addressable pool of economically refurbishable devices entering secondary channels.
- Enterprise ESG mandates:Fortune 500 IT procurement policies now specify certified pre-owned equipment quotas, creating institutional demand pull independent of consumer price sensitivity.
- Modular component architecture:Standardized battery, screen, and motherboard form factors in recent device generations reduce per-unit refurbishment labor hours and skill requirements.
Market Restraints
- Input cost volatility:NAND flash and DRAM spot price swings compress refurbishment margin predictability, particularly for memory-intensive laptop and server categories.
- Supply concentration risk:Asian contract refurbishers in Vietnam and Malaysia control over seventy percent of global smartphone processing capacity, creating single-point vulnerability.
- Technical obsolescence floors:5G modem integration and AI-accelerated chip requirements render pre-2020 device generations economically unviable for full functional restoration.
Strategic Opportunities
- India BIS certification pathway:Formalized import standards for certified pre-owned electronics filter gray-market competition and unlock government digital inclusion program volumes.
- AI-driven grading automation:Computer-vision diagnostic tools reduce functional testing labor costs and enable real-time cosmetic condition scoring at processing scale.
- Reverse logistics integration:Direct OEM take-back programs bypass traditional broker layers, capturing margin from device recovery through certified resale channels.
Industry Challenges
- Diagnostic technician scarcity:Specialized chip-level repair skills for modern motherboard architectures command wage premiums that erode unit economics in high-labor-cost geographies.
- Certification timeline compression:India's BIS testing protocols for refurbished imports add six-to-eight week clearance delays, constraining inventory velocity for time-sensitive consumer electronics.
- Parts authentication complexity:Proliferation of counterfeit components in secondary supply chains threatens warranty claim exposure and brand reputation for certified programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refurbished Electronics Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $503.21 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laptops, Smartphones, Tablets, Desktops Condition: Certified Refurbished, Open Box, Used, Like New Distribution Channel: Direct Sales, Retail Stores, Online Marketplaces, B2B Sales Warranty Type: Limited Warranty, Replacement Warranty, No Warranty, Extended Warranty |
| Companies Covered | Dell Technologies, Back Market, Apple, Best Buy Co. Inc., Lenovo Group Limited, Samsung Electronics, HP Inc., Newegg Inc., Amazon Renewed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refurbished Electronics Market Strategic Shifts
Diagnostic automation and blockchain traceability systems are compressing quality assurance costs while expanding buyer confidence in certified pre-owned channels. These shifts are restructuring competitive advantage around data infrastructure rather than physical processing scale.
Automated optical inspection systems paired with machine-learning defect classification are modularizing the refurbishment workflow into discrete, interchangeable steps. Mid-scale regional processors in Poland and Mexico now adopt these systems to match Asian throughput without equivalent labor depth. The technology is modularizing competitive entry barriers, enabling distributed processing networks closer to end-demand.
The EU's Ecodesign for Sustainable Products Regulation mandates digital product passports containing repair history, component origin, and recyclability metrics. Electronics resellers must integrate blockchain or equivalent traceability infrastructure to maintain market access across member states. Laptop and smartphone categories face the steepest compliance investment requirements given their transaction volumes and cross-border circulation patterns.
Corporate IT asset disposition contracts increasingly specify revenue-sharing from refurbished resale rather than flat recycling fees. Third-party logistics providers and specialized ITAD firms are displacing traditional broker networks as the primary recovery channel for enterprise device fleets. Germany and the Netherlands exhibit the most advanced adoption of this procurement model shift, driven by stringent corporate sustainability reporting requirements.
Refurbished Electronics Market Segmentation
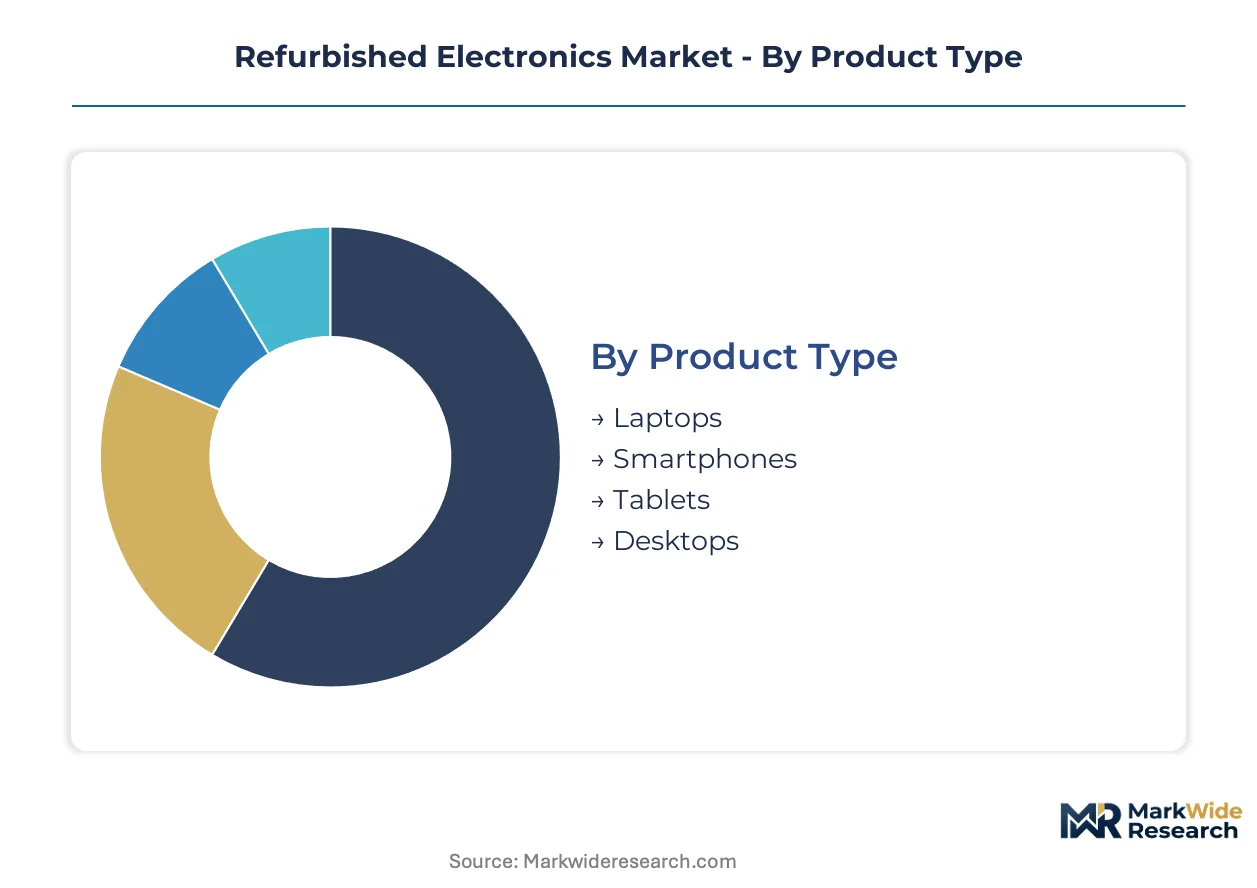
Segmentation in refurbished electronics separates high-margin enterprise procurement from volatile consumer resale channels. Condition grading and warranty backing determine price realization and buyer trust thresholds across all product categories.
Product Type:
Processing complexity and component modularity define the technical axis for refurbishment economics.
- Laptops:Modular architectures with standardized battery and storage form factors enable efficient component replacement. Enterprise IT procurement in Germany and the Netherlands drives certified pre-owned volume through revenue-sharing asset disposition contracts.
- Smartphones:Highest processing volumes flow through Asian contract refurbishers in Vietnam and Malaysia. India's BIS certification requirements filter gray-market competition while government digital inclusion programs absorb certified pre-owned inventory.
- Tablets:Education sector procurement in India and corporate training deployments sustain demand for mid-tier certified units.
- Desktops:Enterprise workstation refresh cycles and data center decommissioning generate supply for component harvesting and functional restoration.
Mature deployment sits with Laptops. Newer deployment is concentrated in Smartphones.
Condition:
Quality assurance depth separates formal certified channels from unverified secondary markets.
- Certified Refurbished:Rigorous diagnostic testing and original component replacement protocols back warranty coverage. Apple's functional grading standards anchor premium pricing tiers.
- Open Box:Unactivated returns with intact packaging command near-new pricing in consumer electronics retail.
- Used:Unverified functional status limits market access to cash-constrained buyers and informal resale channels.
- Like New:Minimal cosmetic defects with full functional verification bridge premium and standard pricing tiers.
Margin concentration aligns with Certified Refurbished. Volume expansion is climbing fastest in Open Box.
Distribution Channel:
Channel structure determines warranty fulfillment capabilities and buyer recourse mechanisms.
- Direct Sales:Dell Technologies' business refurbishment programs bypass broker layers to capture recovery margin.
- Retail Stores:Physical inspection access supports higher price realization for cosmetic-graded inventory.
- Online Marketplaces:Platform algorithms prioritize seller ratings and return policy transparency over price alone.
- B2B Sales:Fortune 500 procurement policies specify certified pre-owned equipment quotas under CSRD disclosure frameworks.
Enterprise reliability requirements favor B2B Sales. Consumer price sensitivity is expanding most quickly in Online Marketplaces.
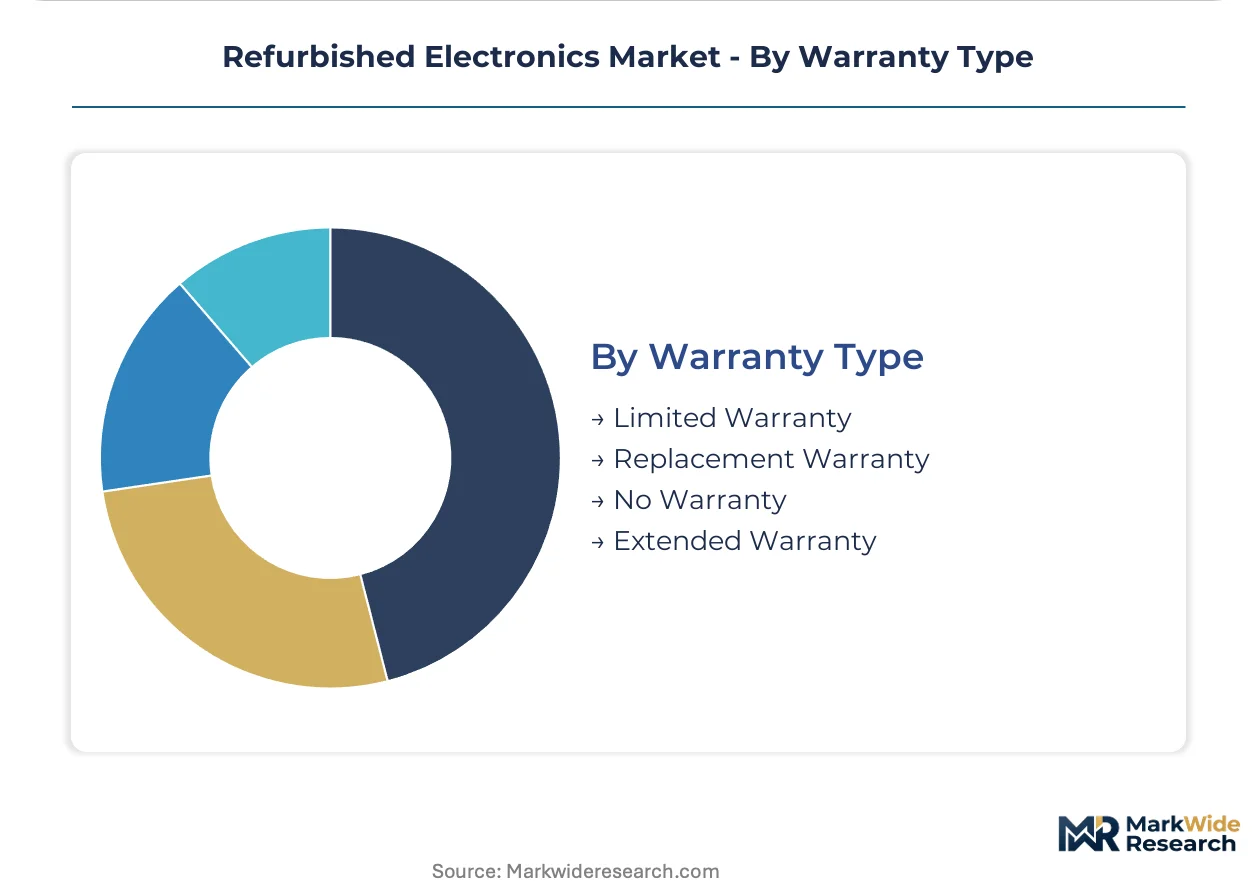
Warranty Type:
Protection duration signals refurbishment confidence and determines residual risk allocation.
- Limited Warranty:Functional defect coverage for 90 days to one year dominates certified pre-owned standards.
- Replacement Warranty:Unit swap guarantees reduce buyer hesitation for high-value enterprise deployments.
- No Warranty:Absence of protection restricts demand to lowest-price market segments.
- Extended Warranty:Third-party protection plans unlock financing options for business procurement.
Certified program integrity rests on Limited Warranty. Procurement flexibility is gaining share fastest in Extended Warranty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Post-consumer device collection networks in the United States generate the primary feedstock for North American refurbishment operations. The EU's regulatory frameworks are redirecting end-of-life electronics toward certified secondary channels rather than informal disposal.
United States
Fortune 500 IT asset disposition contracts and enterprise sustainability reporting under SEC climate disclosure rules drive certified pre-owned laptop procurement. The EPA's electronics recycling standards enforce material traceability for devices entering resale channels. Texas and California host the largest ITAD processing clusters, where specialized firms manage enterprise fleet recovery and data sanitization protocols.
Germany
Corporate procurement policies mandating circular economy criteria and revenue-sharing asset disposition models expand certified refurbishment volume. The EU CSRD requires Scope 3 emissions disclosure that treats certified pre-owned equipment as emissions reduction instruments. The Netherlands-Germany border region concentrates advanced ITAD infrastructure, with Dutch logistics hubs feeding German enterprise demand.
India
Government digital inclusion programs and price-sensitive consumer demand absorb certified pre-owned smartphone and tablet volumes. BIS certification requirements for refurbished imports filter gray-market competition and formalize quality standards. Mumbai and Delhi-NCR serve as primary distribution nodes, with Karnataka emerging as a processing hub for device testing and cosmetic grading operations.
Vietnam
Contract refurbishment capacity for global smartphone brands concentrates in northern industrial zones near Chinese component supply lines. The country's electronics manufacturing ecosystem provides skilled labor pools for diagnostic and repair operations. Ho Chi Minh City and Hanoi host the dominant processing facilities, with Da Nang developing as a secondary hub for mid-tier device restoration.
United Kingdom
Corporate ESG procurement mandates and public sector circular economy targets sustain enterprise laptop refurbishment demand. The UK's post-Brexit regulatory alignment with EU ecodesign principles maintains repairability scoring requirements for imported electronics. London and the Southeast concentrate B2B resale platforms, while Manchester anchors northern England's ITAD processing infrastructure.
Refurbished Electronics Market Competitive Environment
Global majors compete with regional champions across certification depth and enterprise relationship durability. The vendor base stratifies between OEM-captive refurbishment programs, specialized ITAD service providers, and marketplace platforms aggregating third-party inventory. Three archetypes dominate: direct manufacturer programs, independent certification specialists, and digital marketplace operators. Competitive positioning hinges on warranty-backed quality assurance and reverse logistics integration rather than price alone.
Among OEM-captive operators, Dell Technologies and Apple exemplify the direct-program archetype, leveraging original component access and brand equity to sustain premium pricing tiers. HP Inc. occupies a position within the same tier, competing through enterprise service contracts that bundle certified pre-owned equipment with maintenance and support infrastructure. These manufacturers anchor quality benchmarks that independent processors must match to maintain procurement eligibility under Fortune 500 vendor qualification protocols.
| Leading Market Players |
|---|
| Dell Technologies |
| Back Market |
| Apple |
| Best Buy Co. Inc. |
| Lenovo Group Limited |
| Samsung Electronics |
| HP Inc. |
| Newegg Inc. |
| Amazon Renewed |
| Others |
Value Chain & Pricing Dynamics
The EU Ecodesign for Sustainable Products Regulation gates both qualified supply and premium-tier pricing access by mandating digital product passports and repairability scoring that only certified refurbishers can fulfill. Buyers seeking warranty-backed quality assurance must source through compliant channels, compressing gray-market price competition and sustaining margin premiums for verified programs.
Pricing Analysis
Warranty and service bundling separates certified refurbished units from unverified alternatives, with replacement guarantees and extended coverage anchoring premium tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, cosmetic grading, and original component replacement protocols. Price differentiation hinges on functional testing rigor and brand authorization, with Apple and Dell commanding highest realization. Cost compression in mid-tier laptop categories intensifies because NAND flash spot volatility erodes margin predictability. Enterprise procurement teams exhibit lowest price sensitivity due to CSRD disclosure requirements, while individual consumers in India drive volume through economy-tier smartphone sourcing.
Supply Chain Analysis
Regional distribution centers in Vietnam, Malaysia, and India concentrate smartphone processing capacity through hub-and-spoke patterns feeding European and North American demand. Component supply draws from Chinese motherboard and display manufacturers, Korean memory suppliers, and Taiwanese chip fabricators. Single-source vulnerability concentrates in Vietnamese contract refurbishers controlling seventy percent of global smartphone throughput. Distribution runs through direct OEM take-back programs, specialized ITAD providers, and marketplace platforms with distinct warranty fulfillment capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU's Ecodesign for Sustainable Products Regulation creates a cost-of-compliance barrier that filters low-quality suppliers and moats premium market access for certified programs. This regulatory architecture rewards upfront investment in traceability infrastructure and diagnostic automation.
For Market Incumbents: Anticipate margin pressure from AI-driven grading automation by securing exclusive reverse logistics contracts with Fortune 500 enterprises before third-party ITAD firms consolidate channel control. Deepen diagnostic technician training programs to offset wage premiums eroding unit economics in high-labor-cost geographies. Prioritize blockchain traceability integration to maintain EU market access as digital product passport mandates tighten. For New Entrants and Emerging Players: Mid-scale regional processors in Poland and Mexico represent an underserved buyer archetype seeking automated optical inspection systems without Asian labor depth. White-space targets include educational procurement in India and corporate training tablet deployments where B2B reliability requirements remain unmet by gray-market suppliers. Partner with logistics providers offering revenue-sharing asset disposition models to bypass traditional broker layers. For Investors and Strategic Acquirers: India's BIS certification timeline compression is the leading indicator that regulatory compliance infrastructure will separate acquireable assets from stranded inventory. Long-term viability centers on processors with captive enterprise relationships and automated grading capabilities rather than labor-dependent scale. Acquisition targets should demonstrate proven clearance velocity through formal import channels and established government program supplier status.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Integration | EU digital product passport mandates require repair history documentation for market access. |
| AI-Driven Diagnostic Automation | Computer-vision defect classification reduces labor costs for mid-scale regional processors. |
| Reverse Logistics Partnership | Dell's direct take-back programs capture recovery margin bypassing traditional broker networks. |
| BIS Certification Investment | India's formalized import standards filter gray-market competition for government program volumes. |
| Enterprise ITAD Contracting | Revenue-sharing asset disposition models displace flat-fee recycling in Germany and Netherlands. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this refurbished electronics analysis, cross-referenced with primary interviews involving ITAD service directors, enterprise procurement officers, diagnostic technicians, and logistics operators. EPA electronics recycling standards, EU Ecodesign implementing measures, and India's BIS certification protocols provided regulatory boundary conditions. Bottom-up volume estimates by product category and condition grade triangulated against top-down market sizing from trade flow analysis.
Granularity-level modeling addressed product type, condition tier, distribution channel, warranty coverage, and geographic regulatory cluster across the analysis window. CAGRs derived from segment-level volume trajectories incorporating replacement cycle dynamics, enterprise refresh timing, and digital inclusion program absorption rates. Forecast inputs included NAND flash spot price correlation models and right-to-repair legislative progression scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to memory component price volatility and repairability mandate enforcement consistency. Outputs reflect documented assumptions regarding certification timeline evolution and enterprise ESG procurement policy adoption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Laptop Skins Market
Consumer Electronics
Subwoofer Market
Consumer Electronics
Smart Home Projector Market
Consumer Electronics
Global Speaker Market
Consumer Electronics
Portable Media Player Market
Consumer Electronics
China Refurbished Smartphone Market
Consumer Electronics
North America Mobile Phone Accessories Market
Consumer Electronics
In-Ear-Monitors (Iems) Market
Consumer Electronics
Consumer Electronics Repair and Maintenance Market
Consumer Electronics
Kids Tablet Market
Consumer Electronics
US Mobile Phone Accessories Market
Consumer Electronics
Phone Headsets Market
Consumer Electronics
LAMEA Refurbished and Used Mobile Phones Market
Consumer Electronics
Digital Cloud Picture Frame Market
Consumer Electronics
Digital Writing Instruments Market
Consumer Electronics
Middle East and Africa Smartphones Market