
 Earbuds Market | 2026-2036
Earbuds Market Size, Share, and Industry Trends Forecast 2026-2036
Earbuds Market Intelligence
Contract manufacturing reliance is shifting toward hybrid in-house and outsourced production as brands seek supply chain resilience. Apple sustains premium positioning through proprietary silicon and ecosystem integration. Samsung leverages vertical component manufacturing to control cost curves across price tiers. Anker competes aggressively in budget and mid-range segments through direct-to-consumer channel efficiency.
Earbuds are compact electroacoustic transducers designed for personal audio reproduction, typically incorporating dynamic or balanced armature drivers with frequency responses spanning 20 Hz to 20 kHz, and are engineered for portable music consumption, voice communication, and immersive content experiences. True wireless configurations dominate volume shipments while premium tiers capture disproportionate margin pools. Bluetooth connectivity anchors the mass market, though USB-C and NFC variants occupy growing niches in professional and enterprise deployments.
FCC certification mandates govern RF emissions and wireless interoperability for US-bound products, while CE marking and RoHS compliance govern European market access and material restrictions. China's MIIT enforces radio transmission standards that domestic and foreign manufacturers must satisfy for commercial distribution. Stakeholders must monitor evolving interoperability mandates and battery safety regulations as jurisdictions tighten circular economy requirements.
Market Dynamics
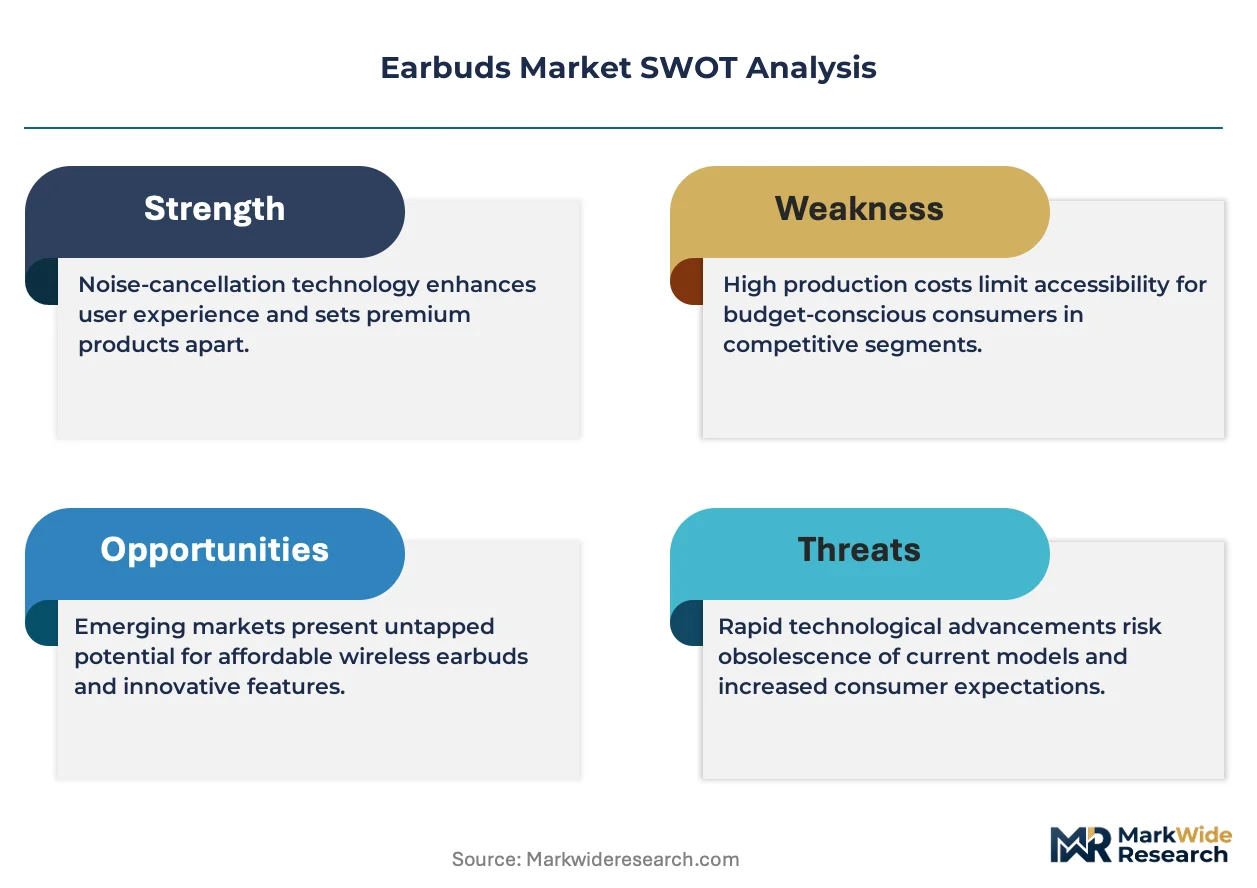
Bluetooth Low Energy Audio is compressing legacy codec architectures across flagship and mid-tier product lines, forcing component suppliers to retool driver and DSP portfolios while fitness-integrated use cases pull demand toward workout-optimized form factors.
Growth Catalysts
- MIIT Radio Transmission Standards:China's enforcement of unified wireless certification accelerates domestic brand consolidation and reduces interoperability friction for cross-border shipments.
- Fitness-Integrated Audio:Workout-optimized earbuds with biometric sensing and sweat-resistant IP ratings capture the fastest-expanding buyer segment as gym and outdoor exercise audio becomes non-discretionary.
- Hybrid Manufacturing Models:Brands blending in-house assembly with contract manufacturing build supply chain resilience against single-source concentration risks.
Market Restraints
- Lithium-Ion Cell Volatility:Battery raw material price swings and constrained cathode supply concentrate cost pressure in compact form factors where cell volume is fixed.
- Shenzhen-Shenzhen Component Sourcing:Driver, PCB, and antenna module supply clusters within China's Pearl River Delta create geographic concentration exposure for non-domestic brands.
- Codec Licensing Architecture:Proprietary audio encoding stacks from Qualcomm and Sony impose royalty burdens that compress margins at sub-premium price tiers.
Strategic Opportunities
- India PLI Scheme for Electronics:Production-linked incentives for mobile phone and component manufacturing attract earbud assembly relocation from coastal China to Tamil Nadu and Uttar Pradesh.
- Hearing Health Integration:FDA OTC hearing aid regulations enable earbuds with adaptive amplification to serve mild-to-moderate hearing loss without clinical fitting.
- Direct-to-Consumer Channel Optimization:Amazon storefront analytics and TikTok Shop live commerce compress customer acquisition costs for mid-market brands bypassing traditional retail.
Industry Challenges
- FCC Certification Timelines:RF emissions testing and SAR documentation for US-bound products extend launch windows by 8-14 weeks, compressing seasonal product cycles.
- Acoustic Engineering Talent Scarcity:Miniaturized driver tuning and ANC algorithm development require specialized electroacoustic expertise concentrated in Denmark, Japan, and California.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earbuds Market |
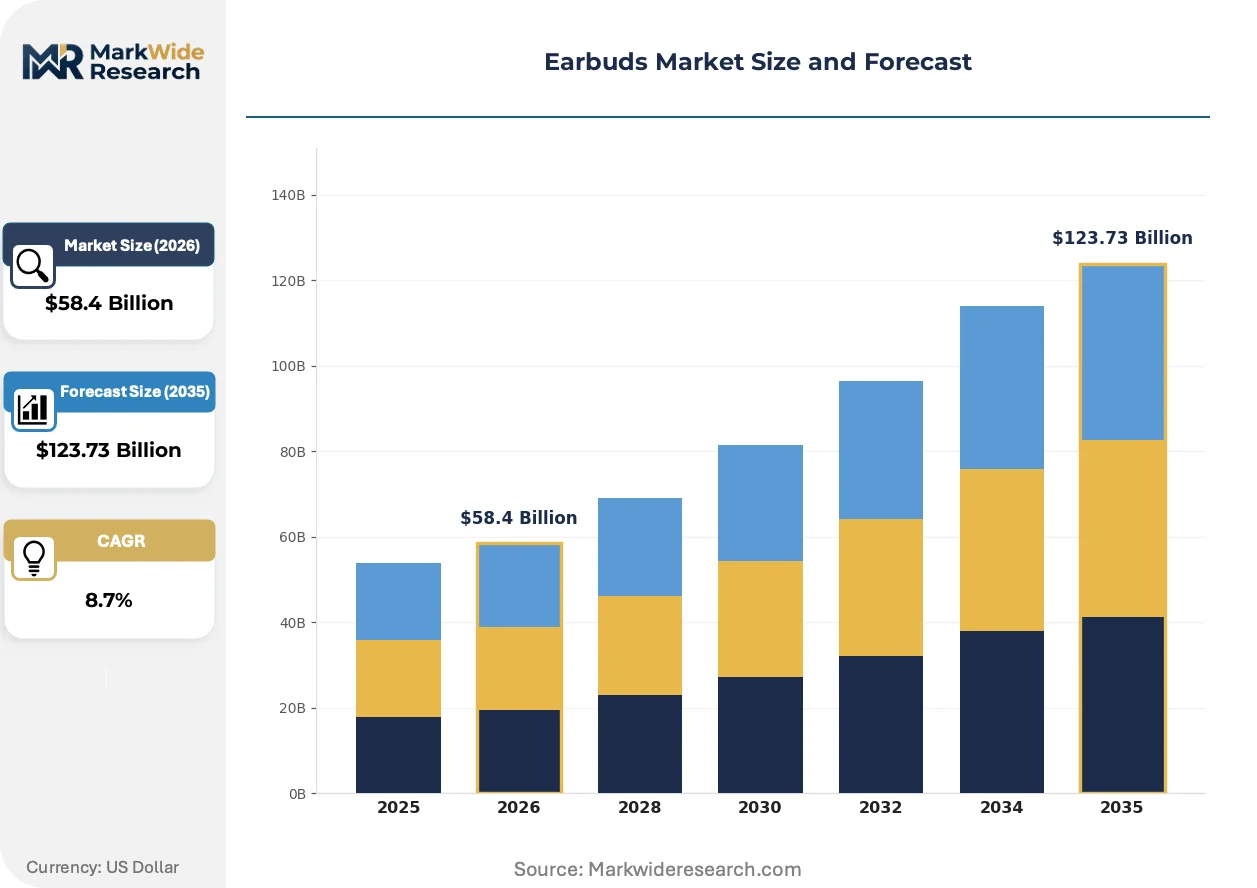
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $123.73 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: True Wireless, Over-Ear, In-Ear, On-Ear Connectivity: Bluetooth, Wired, NFC, USB-C End User: Consumers, Gamers, Professionals, Athletes Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Sennheiser, Samsung, Sony, Technics, Anker, Bose, JBL, Shokz, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earbuds Market Strategic Shifts & Innovations
Codec standardization and biometric sensor fusion are restructuring how earbuds differentiate, with software-defined audio experiences displacing hardware-centric positioning across price tiers.
LC3plus and Auracast broadcast audio is expanding into public venue and fitness center deployments, enabling multi-listener streaming without pairwise pairing. Transit authorities in Seoul and London pilot Auracast-enabled PA systems, while gym chains adopt broadcast modes for instructor-led classes. This compression of legacy Bluetooth pairing workflows opens subscription revenue models for venue-managed audio services.
EU Battery Regulation mandates removable cell design and recycled content thresholds for portable electronics entering European markets after 2027. Manufacturers must redesign unibody enclosures to accommodate user-replaceable batteries without compromising IP ratings. Premium tier products face the steepest compliance costs as metal-and-resin construction complicates disassembly.
Subscription bundling of lossless streaming with hardware purchases reconfigures customer lifetime value calculations. Tidal and Apple Music integrate tiered audio quality with device firmware, locking buyers into ecosystem content libraries. This shift from transactional hardware sales to recurring service attachment is most visible in North American and Western European markets where streaming penetration exceeds 70 percent.
Earbuds Market Segmentation
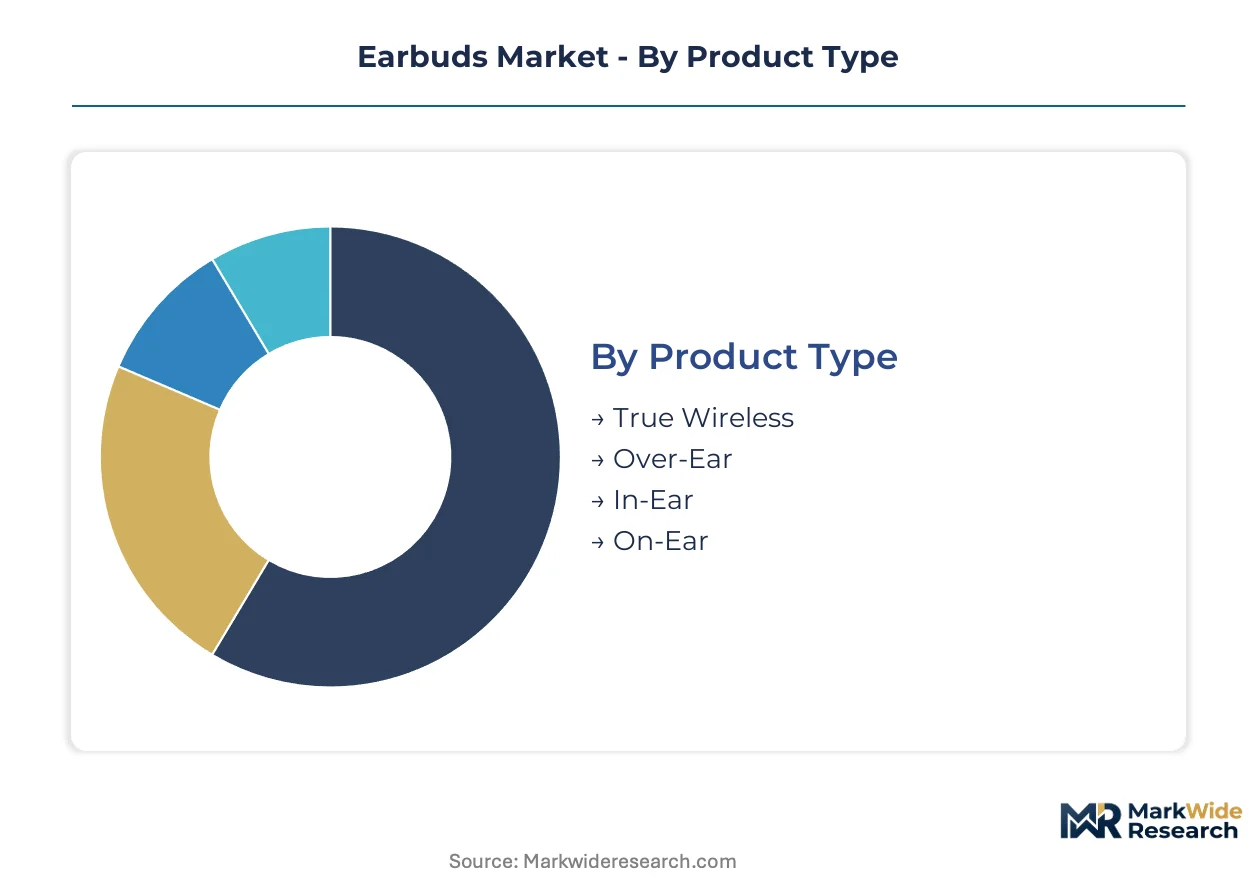
Earbud segmentation determines which engineering tradeoffs—driver architecture, power budgets, acoustic isolation—align with specific use intensities and connectivity environments. Manufacturers configure BOM stacks and certification pathways differently across these boundaries.
Product Type:
Standalone true wireless configurations dominate shipment volumes while tethered and over-ear variants serve embedded professional systems with fixed installation requirements.
- True Wireless:Completely cable-free implementations with independent left/right buds, Bluetooth 5.3+ SoCs, and charging case power management. Demand concentrates in China and India where domestic brands exploit Shenzhen component clusters to compress BOM costs while MIIT certification accelerates domestic distribution.
- In-Ear:Canal-sealing designs with silicone or foam tips providing passive isolation down to 15-25 dB, common in commuter and gym environments. Athletes and fitness centers in Seoul and London drive replacement cycles through sweat-corrosion and biometric sensor integration.
- Over-Ear:Circumaural enclosures with 40-50 mm dynamic drivers and extended battery capacities for studio monitoring and long-haul travel. Post-production facilities in California and Copenhagen sustain niche demand despite bulk constraints.
- On-Ear:Supra-aural pads resting against the outer ear, balancing portability with driver size for mid-tier consumer segments. European retailers favor these for CE-marked youth volume given pressure-limiting compliance advantages.
True Wireless leads volumes today; In-Ear is gaining share fastest through fitness-integrated biometric expansion.
Connectivity:
Wireless protocols command consumer preference while wired and alternate interfaces persist in latency-sensitive and enterprise-locked deployments.
- Bluetooth:Dominant RF implementation spanning SBC, AAC, aptX, and LC3 codec stacks with 10-meter nominal range. FCC Part 15 certification timelines in the US and MIIT radio transmission standards in China create divergent pre-market testing burdens for multi-territory launches.
- Wired:3.5 mm TRRS or USB-C DAC-dependent connections eliminating battery dependency and latency for gaming and broadcast monitoring. Professional audio engineers in Japan and Germany specify these for METI and KBA workplace compliance in transportation control rooms.
- NFC:Tap-to-pair functionality and payment token storage in hybrid wearable configurations. Transit authorities in London and Seoul pilot Auracast-adjacent NFC pairing for accessibility-focused passenger services.
- USB-C:Digital audio with integrated DAC/amplification and charging convergence, growing in enterprise fleet deployments requiring standardized cable ecosystems. IT procurement in North American financial services favors these for HIPAA-aligned device management.
Bluetooth dominates installed base; USB-C is climbing fastest through enterprise standardization mandates.
End User:
User intensity and environmental exposure separate consumer casual use from performance-optimized professional and athletic segments.
- Consumers:General-purpose listeners prioritizing convenience, brand aesthetics, and streaming service integration. Replacement cycles accelerate in India through PLI-scheme price compression and Amazon-TikTok direct-to-consumer channel efficiency.
- Athletes:IPX4-IPX7 rated designs with earhook or wingtip retention, heart rate sensing, and offline storage for phone-free training. Gym chains in Seoul and London adopt broadcast-enabled models for instructor-led class synchronization.
- Gamers:Sub-20 ms latency requirements, spatial audio processing, and boom microphone attachments for team communication. Esports venues in South Korea and California drive demand for 2.4 GHz dongle variants alongside Bluetooth.
- Professionals:ANC prioritization, multi-point pairing, and call-quality beamforming for open-office and remote work. FDA OTC hearing aid regulations in the US enable adaptive amplification features for mild-to-moderate hearing loss without clinical fitting.
Consumers anchor shipment volumes; Athletes show steepest expansion trajectory through biometric sensor fusion.
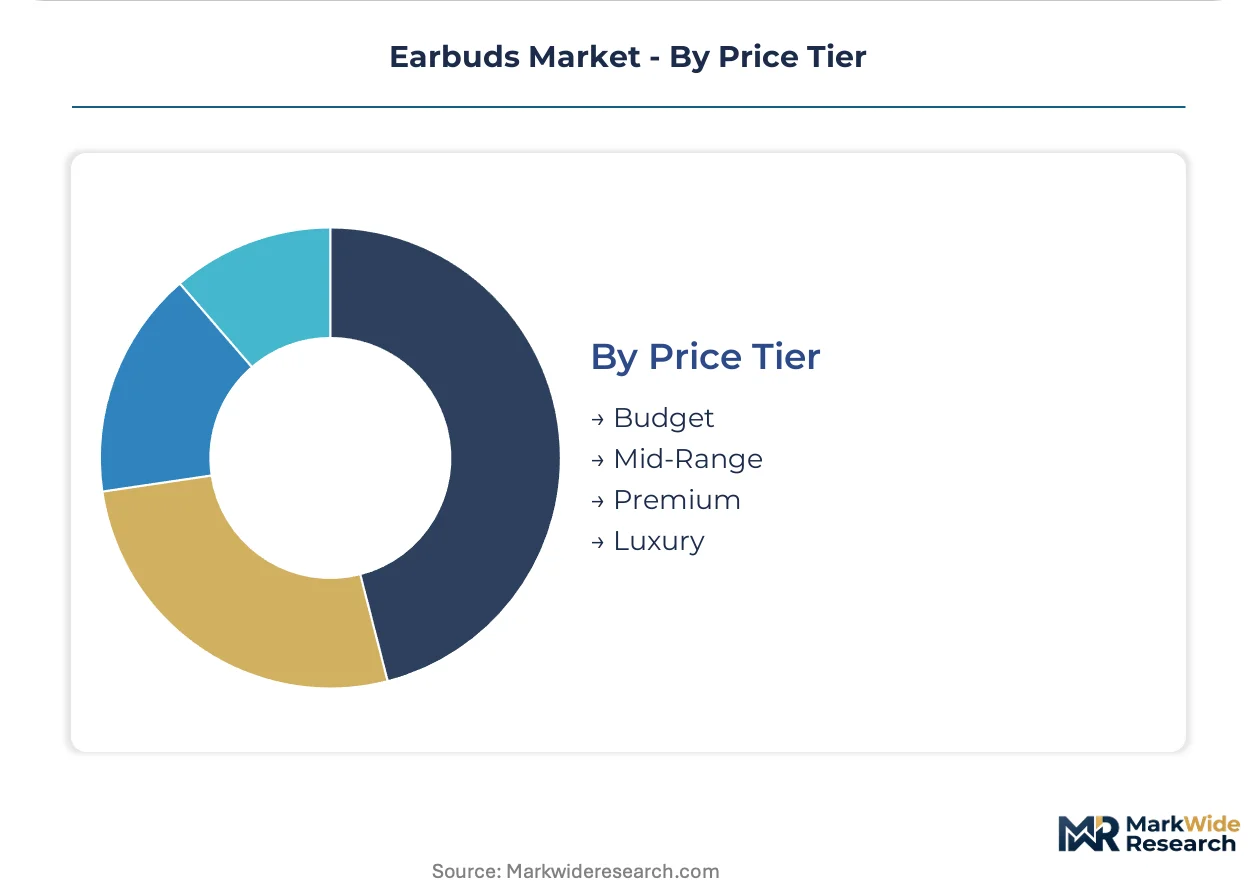
Price Tier:
Component grade and certification depth stratify manufacturing location, margin structure, and channel access across economic boundaries.
- Premium:Custom silicon, multi-driver hybrids, and adaptive ANC with personalized spatial audio. Apple's proprietary H-series chips and Samsung's vertical component manufacturing define this tier through ecosystem lock-in and controlled cost curves.
- Budget:Single dynamic drivers, basic Bluetooth 5.0, and Shenzhen-sourced PCBs with minimal acoustic tuning. Anker's direct-to-consumer efficiency and domestic Chinese brands exploit this tier through platform ecosystem volume.
- Mid-Range:Hybrid driver configurations, entry ANC, and balanced codec support for quality-conscious mainstream buyers. Indian PLI scheme assembly relocation to Tamil Nadu and Uttar Pradesh concentrates new entrant activity here.
- Luxury:Precious metal finishes, concierge service bundling, and limited artisan production for status signaling. European markets sustain this tier through CSRD-aligned circular economy marketing and repair-service subscriptions.
Budget tier captures unit leadership; Premium is expanding most quickly through subscription-streaming hardware bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pearl River Delta anchors global earbud manufacturing, with Shenzhen's component clusters supplying driver modules, PCBs, and antenna systems to brands worldwide. Demand concentrates in China, where domestic brands exploit platform ecosystem lock-in and MIIT certification pathways to compress distribution cycles. Secondary markets in India, South Korea, the United States, and Germany each exhibit distinct regulatory and procurement patterns.
China
Fitness-integrated audio and Bluetooth Low Energy Audio codec adoption drive replacement cycles among urban consumers. MIIT enforces unified radio transmission standards that accelerate domestic brand consolidation while streamlining cross-border interoperability testing. Shenzhen's component ecosystem supplies driver, PCB, and battery cell modules to both domestic and foreign brands seeking compressed BOM costs.
India
PLI scheme incentives for mobile phone and component manufacturing attract earbud assembly relocation from coastal China to Tamil Nadu and Uttar Pradesh. BIS certification mandates govern safety and interoperability for commercial distribution, with testing timelines compressing as accredited labs expand capacity. Amazon and TikTok Shop direct-to-consumer channels accelerate replacement cycles through price-compressed mid-tier offerings.
South Korea
Gaming and esports venues in Seoul drive demand for sub-20 ms latency configurations and spatial audio processing. MFDS regulations govern biometric sensor accuracy claims for fitness-integrated models with heart rate monitoring. Busan-Ulsan industrial corridors host contract manufacturers serving both domestic brands and export-oriented assembly for North American markets.
United States
FDA OTC hearing aid regulations enable earbuds with adaptive amplification to serve mild-to-moderate hearing loss without clinical fitting, expanding addressable demand beyond traditional audio consumers. FCC Part 15 certification timelines extend launch windows by 8-14 weeks, compressing seasonal product cycles for holiday-bound shipments. California and Massachusetts concentrate acoustic engineering talent for ANC algorithm development.
Germany
CE marking and RoHS compliance govern European market access, with EU Battery Regulation mandates for removable cell design and recycled content thresholds taking effect after 2027. KBA workplace compliance specifications in transportation control rooms sustain niche demand for wired USB-C configurations with integrated DAC/amplification. Bavaria and Baden-Württemberg host precision driver tuning facilities serving premium-tier brands.
Earbuds Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue fitness-integrated and hearing-health adjacent spaces. The vendor base stratifies across proprietary silicon owners, vertical component manufacturers, and direct-to-consumer efficiency players. Three archetypes dominate: ecosystem-locked premium brands, Shenzhen-sourced volume competitors, and hybrid manufacturing specialists. Consolidation pressure manifests through strategic partnerships for codec licensing and capacity expansion into India PLI-subsidized assembly zones.
Among ecosystem-locked premium-tier vendors, Apple and Samsung exemplify proprietary silicon strategies that control cost curves and deepen user retention through hardware-software integration. Sony occupies a position within the codec licensing and acoustic engineering tier, leveraging specialized expertise in miniaturized driver tuning. Anker represents direct-to-consumer efficiency archetypes, compressing customer acquisition costs through Amazon storefront analytics and platform-native distribution.
| Leading Market Players |
|---|
| Sennheiser |
| Samsung |
| Sony |
| Technics |
| Anker |
| Bose |
| JBL |
| Shokz |
| Apple |
| Others |
Cost & Logistics Intelligence
Premium-to-budget tier divergence in driver architecture and certification depth manifests simultaneously in pricing power and supply chain geography. Apple's proprietary silicon and Samsung's vertical component manufacturing sustain margin capture at the premium end, while Shenzhen-sourced single-driver configurations compress landed costs for volume brands serving price-sensitive Indian and Southeast Asian consumers through direct-to-consumer channels.
Pricing Analysis
Input-cost pass-through from lithium-ion cathode volatility and Bluetooth codec licensing royalties intensifies margin pressure at sub-premium price points. Three-tier pricing structure across premium, standard, and economy levels separates custom silicon multi-driver hybrids from entry ANC configurations and basic Bluetooth 5.0 implementations. Pricing softness reflects constrained battery raw material supply and Qualcomm royalty burdens that brands cannot fully absorb below mid-range thresholds. Athletes and fitness-integrated buyers show least price sensitivity; budget-tier consumers in India exhibit highest elasticity, accelerating replacement cycles only when PLI-scheme assembly compresses retail tags.
Supply Chain Analysis
Logistics and freight cost optimization increasingly shapes assembly location decisions as brands diversify beyond Pearl River Delta concentration. Component manufacturing clusters in China, South Korea, and Vietnam feed driver modules, PCBs, and antenna systems to final assembly operations. Battery cell supply draws from cylindrical and pouch cell production anchored in China and South Korea, creating single-source vulnerability for non-vertically integrated brands. Distribution runs through Amazon storefronts and TikTok Shop live commerce for mid-market entrants, while premium tiers maintain controlled retail partnerships for experiential positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on Bluetooth Low Energy Audio codec adoption compressing legacy royalty burdens while fitness-integrated biometric tiers command sustained premium pricing.
For Market Incumbents: Anticipate codec standardization disrupting proprietary differentiation advantages by accelerating LC3plus and Auracast firmware deployment across product lines. Defend position through backward integration into driver module production and captive battery cell sourcing that insulates against cathode price swings. Prioritize MIIT certification pathway optimization to maintain velocity in Chinese domestic distribution against consolidating local competitors.
For New Entrants and Emerging Players: Amazon and TikTok Shop analytics partnerships offer the most penetrable channel infrastructure for mid-range positioning without legacy retail margin sacrifices. Target hearing-health adjacent segments where FDA OTC regulations enable adaptive amplification features without clinical fitting infrastructure. White-space exists in gym chain broadcast-enabled bulk procurement and Auracast venue deployment partnerships that incumbent audio brands have underdeveloped.
For Investors and Strategic Acquirers: Consolidation pressure builds where acoustic engineering talent scarcity concentrates miniaturized ANC algorithm development in Denmark, Japan, and California. Long-term viability favors targets with hybrid manufacturing footprints spanning Shenzhen component access and India PLI-subsidized assembly capacity. Watch FDA OTC hearing aid enrollment trajectories and EU Battery Regulation compliance readiness as inflection signals for premium-tier margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Bluetooth LE Audio Firmware Migration | LC3plus codec adoption reduces Qualcomm royalty exposure while enabling Auracast broadcast revenue models. |
| India PLI Assembly Relocation | Tamil Nadu and Uttar Pradesh manufacturing subsidies compress landed costs for mid-tier export volumes. |
| Hearing Health Feature Integration | FDA OTC regulations expand addressable demand beyond traditional audio consumers into mild-to-moderate loss segments. |
| Hybrid Manufacturing Model Deployment | Blended in-house and contract assembly builds resilience against Shenzhen-Shenzhen geographic concentration exposure. |
| Direct-to-Consumer Channel Optimization | Amazon storefront analytics and TikTok Shop live commerce reduce customer acquisition costs versus traditional retail. |
Research Approach
Multiple input streams — executive interviews with earbud brand product managers and supply chain directors, regulatory filing analysis from FCC and MIIT databases, and customs trade records from China and India — were reconciled through bottom-up shipment modeling and top-down market sizing validation. Primary fieldwork engaged acoustic engineering leads in Copenhagen and California, contract manufacturing procurement heads in Shenzhen and Busan, and fitness center operators in Seoul and London piloting Auracast deployments. Secondary sources encompassed Bluetooth SIG specification releases, EU Battery Regulation draft impact assessments, and PLI scheme beneficiary disclosures from Indian electronics manufacturing zones.
Data-stream reconciliation across product type, connectivity protocol, end-user intensity, and price tier segmentation anchored volume and value projections throughout the forecast period. CAGRs derived from replacement cycle analysis by user archetype, codec adoption curve modeling, and geographic penetration rate differentials. Industry-specific inputs included biometric sensor fusion adoption trajectories in athletic segments and FDA OTC hearing aid regulatory enrollment assumptions for professional-tier demand expansion.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion raw material supply disruptions, MIIT certification timeline shifts, and EU Battery Regulation removable cell design compliance deadlines. Forecasts reflect documented assumptions about Bluetooth LE Audio penetration rates and India PLI capacity buildout schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Camera Case Market
Consumer Electronics
Smart Connected Speaker Market
Consumer Electronics
Consumer Electronic Biometrics Market
Consumer Electronics
Digital Accessories Market
Consumer Electronics
Smart Headphones Market
Consumer Electronics
Gaming Keyboard Market
Consumer Electronics
Middle East and Africa Mobile Phone Accessories Market
Consumer Electronics
Smart Television and Set-Top Box Market
Consumer Electronics
TV Mirror Market
Consumer Electronics
Bluetooth Speakers Market
Consumer Electronics
Ergonomic Mouse Market
Consumer Electronics
Gaming Mouse Market
Consumer Electronics
Waterproof Bathroom TV Market
Consumer Electronics
Electronics Accessories Market
Consumer Electronics
Global Office and Contact Center Headset Market
Consumer Electronics
Vape Cartridge Market