
 Europe Mobile Phone Accessories Market | 2026-2036
Europe Mobile Phone Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mobile Phone Accessories Market Foresight
Enterprise mobility management is expanding across European corporations deploying standardized smartphone fleets for field staff and logistics workers. Samsung Electronics Co., Ltd. dominates B2B channel partnerships with enterprise-grade protective solutions and Knox-integrated accessories. Sennheiser Electronic GmbH & Co. KG specializes in premium audio peripherals targeting hybrid work environments with broadcast-quality headsets. Xiaomi Corporation competes aggressively on price in Eastern European online retail, leveraging direct-to-consumer logistics to undercut traditional electronics stores.
Europe mobile phone accessories comprise add-on components—protective enclosures, power delivery devices, audio transducers, and display films—engineered to extend device functionality, durability, or user ergonomics, typically conforming to USB Power Delivery 3.0 or Qi wireless charging protocols for interoperability across Android and iOS ecosystems. Cases and screen protectors constitute the largest volume segment, though margin pools concentrate in headphones where active noise cancellation and LDAC codec support command price premiums. Chargers represent the fastest-growing structural category as GaN semiconductor adoption enables higher wattage in smaller form factors, while silicone materials displace conventional plastics under Ecodesign pressure for reduced petroleum feedstock dependence.
REACH chemicals regulation and the EU Green Deal's circular economy action plan constrain material choices, compelling suppliers to document substance safety and design for disassembly across accessory portfolios. EMA and national market surveillance authorities in Germany, France, and Italy enforce CE marking conformity for electronic accessories, creating compliance differentiation between established distributors and gray-market imports. Stakeholders must monitor upcoming battery passport requirements and right-to-repair mandates that will reshape spare parts availability and aftermarket pricing structures.
Market Dynamics
GaN semiconductor adoption in charging hardware is compressing form factors while elevating power density, forcing incumbent suppliers to retool manufacturing lines or cede premium positioning to specialized power electronics firms.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Mandates for recycled content and modular repairability are creating compliant product lines that command shelf space at major German electronics retailers.
- Enterprise fleet standardization:Logistics and field service corporations across France and the Netherlands are deploying uniform device programs with bulk accessory procurement.
- Qi2 magnetic alignment:The Wireless Power Consortium's updated protocol is automating accessory pairing and reducing returns from charging misalignment.
Market Restraints
- Silicone feedstock volatility:Petrochemical-derived silicone prices fluctuate with natural gas benchmarks, squeezing margin on Ecodesign-compliant cases.
- Assembly concentration in Southeast Asia:Final manufacturing of precision connectors and GaN modules remains concentrated outside Europe, exposing lead times to maritime disruption.
- REACH substance documentation:ECHA's expanded SVHC candidate list requires costly third-party testing for phthalates and flame retardants in cable sheathing.
Strategic Opportunities
- Battery passport preparation:The EU's upcoming battery regulation creates first-mover advantage for accessory firms building digital product passports and disassembly documentation systems.
- Eastern European e-commerce penetration:Poland and Romania show underdeveloped accessory attachment rates relative to smartphone ownership, favoring direct-to-consumer logistics investments.
- Right-to-repair alignment:Modular charging cable designs with replaceable connector heads anticipate French and German repair index scoring requirements.
Industry Challenges
- GaN design talent scarcity:Power electronics engineers capable of thermal management in sub-30W chargers command premium compensation, constraining in-house R&D scaling.
- CE marking surveillance intensity:German and Italian market authorities are conducting unannounced port inspections for electromagnetic compatibility violations, extending certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mobile Phone Accessories Market |
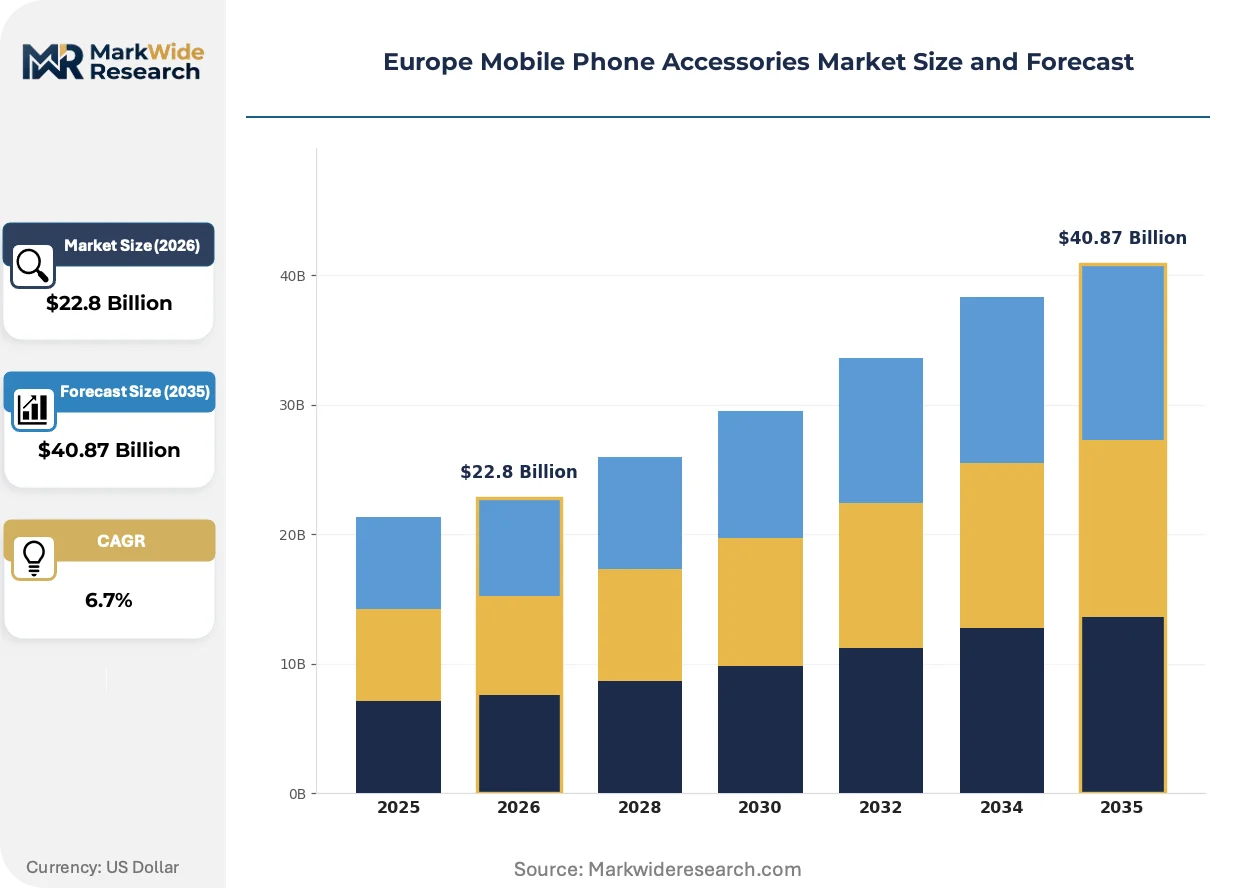
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $40.87 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cases, Screen Protectors, Chargers, Headphones Material: Silicone, Plastic, Leather, Tempered Glass Distribution Channel: Online Retail, Electronics Stores, Supermarkets, Specialty Shops Customer Type: Individual Consumers, Corporates, Educational Institutions, Resellers |
| Companies Covered | Belkin International, Inc., Bose Corporation, Apple Inc., Panasonic Corporation, Xiaomi Corporation, Samsung Electronics Co., Ltd., Sennheiser Electronic GmbH & Co. KG, Amazon Inc., Sony Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mobile Phone Accessories Market Shifts & Advancements
Accessory functionality is converging with device management software, creating hardware that reports usage telemetry and enables remote configuration by enterprise IT departments.
Gallium nitride power circuitry is automating thermal regulation in multi-port chargers, allowing simultaneous laptop and smartphone charging without heat-induced throttling. Enterprise procurement teams in Scandinavian markets are specifying GaN-based solutions for desk hoteling environments. The technology is automating the displacement of legacy silicon-based adapters in premium channel positioning.
France's repairability index mandates are compelling accessory designers to publish disassembly scores and spare parts availability timelines. Manufacturers must now engineer click-fit connectors rather than adhesive bonds. Headphone and charging dock categories face the steepest redesign costs to achieve index compliance.
Corporate buyers are consolidating accessory procurement through mobility management platforms that bundle device enrollment with standardized case and charging deployments. Traditional electronics distributors in Germany are losing direct relationships with large fleet operators. The shift is most visible among logistics firms operating across Benelux corridors.
Europe Mobile Phone Accessories Market Segmentation
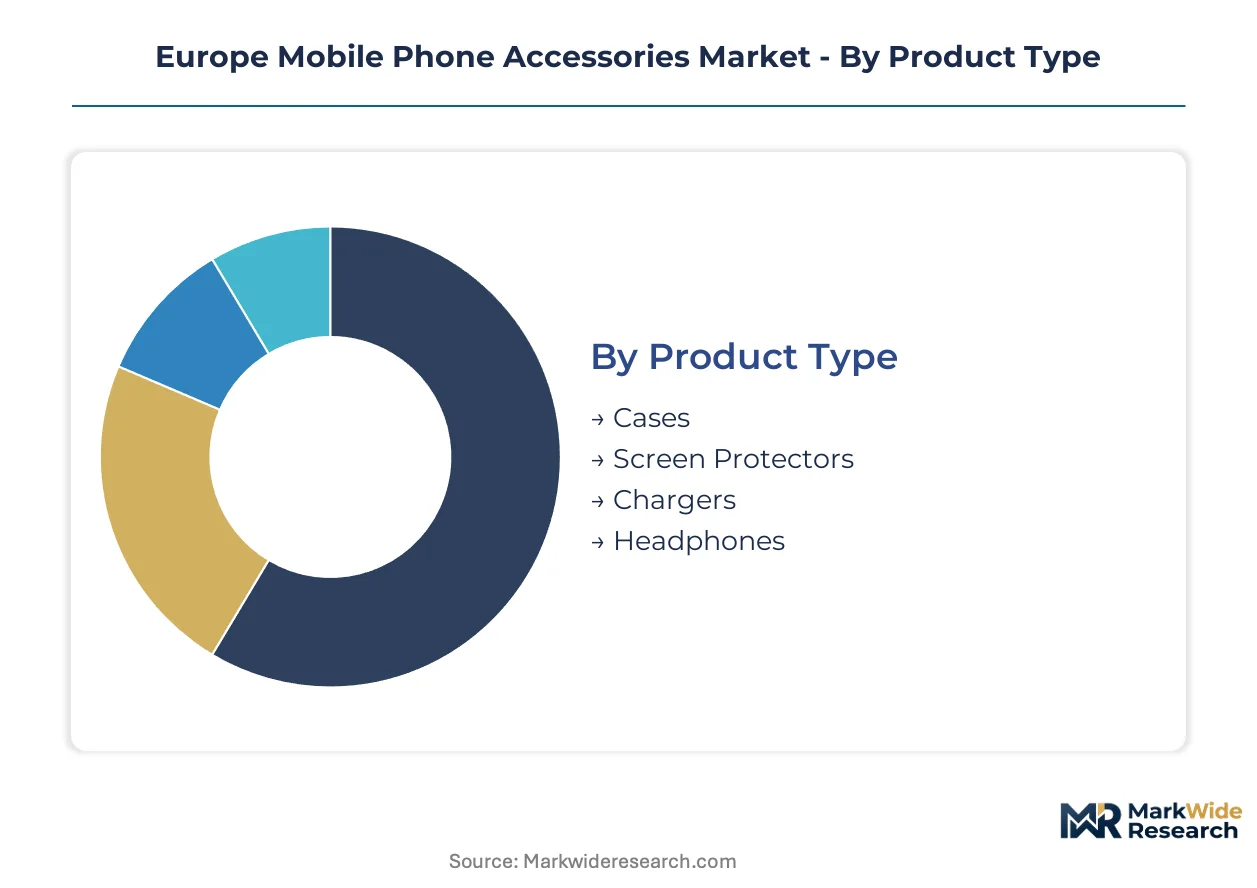
Segmentation reveals how capital deployment, regulatory exposure, and channel economics vary across accessory categories. Manufacturers must align production scale and certification investments with the structural characteristics of each segment cluster.
Product Type:
Chargers demand the highest upfront capital for GaN semiconductor fabrication and thermal engineering facilities, while cases require lower tooling investment but higher material compliance documentation.
- Cases:Protective enclosures molded from silicone, TPU, or polycarbonate composites with precision cutouts for camera modules and charging ports. German consumer electronics retailers stock the deepest inventories here, driven by Ecodesign mandates pushing suppliers toward recycled feedstocks and modular repairability scores.
- Chargers:Power delivery devices incorporating GaN or silicon carbide semiconductors to achieve higher wattage densities in compact form factors. Enterprise fleet managers in France and the Netherlands specify these for standardized device deployments, prioritizing USB Power Delivery 3.0 and Qi2 magnetic alignment protocols.
- Screen Protectors:Tempered glass or PET film laminates engineered for hardness ratings and oleophobic coatings.
- Headphones:Audio peripherals spanning true wireless earbuds to broadcast-quality over-ear headsets with active noise cancellation.
Cases absorb the bulk of installed capacity; chargers are expanding most quickly.
Material:
Material selection determines REACH documentation burden and Ecodesign compliance trajectory, with petroleum-derived inputs facing the steepest substitution pressure.
- Silicone:Elastomer compounds offering shock absorption and grip texture, increasingly sourced from post-industrial recycled streams to satisfy EU Green Deal circular economy requirements. Feedstock price volatility tied to natural gas benchmarks squeezes margin on Ecodesign-compliant product lines.
- Plastic:ABS and polycarbonate resins still dominant in budget-tier manufacturing but losing shelf space at major German electronics retailers under modular repairability mandates.
- Leather:Natural and synthetic hide materials positioned in premium channel tiers with higher margin pools but smaller volume footprints.
- Tempered Glass:Chemically strengthened aluminosilicate substrates for screen protection with hardness ratings and shatter-resistant properties.
Silicone commands the deepest supplier relationships; tempered glass is climbing the fastest on replacement cycle acceleration.
Distribution Channel:
Channel economics split between high-touch retail requiring inventory carrying costs and direct-to-consumer logistics demanding last-mile optimization.
- Online Retail:E-commerce platforms and direct-to-consumer storefronts capturing growing share through price transparency and subscription replenishment models. Xiaomi leverages this channel aggressively in Poland and Romania where traditional electronics retail density remains underdeveloped.
- Electronics Stores:Brick-and-mortar specialists like MediaMarkt Saturn holding privileged positions for premium accessory launches and enterprise procurement relationships.
- Supermarkets:Mass merchandisers stocking impulse-purchase accessories with limited SKU depth and compressed margins.
- Specialty Shops:Carrier-branded stores and independent mobile repair operators focusing on immediate-need replacement and installation services.
Electronics stores anchor the highest-value transactions; online retail is gaining share fastest on logistics network maturation.
Customer Type:
Procurement sophistication varies sharply between individual price sensitivity and corporate standardization requirements with negotiated volume terms.
- Corporates:Enterprise mobility programs deploying standardized device fleets with bulk accessory procurement through mobility management platforms. Logistics and field service corporations across Benelux corridors are consolidating supplier relationships away from traditional electronics distributors.
- Individual Consumers:Fragmented demand driven by device replacement cycles, aesthetic preferences, and price-tier segmentation across premium, standard, and economy levels.
- Educational Institutions:Bulk purchasing for student device programs with durability and warranty requirements distinct from consumer markets.
- Resellers:Gray-market and authorized distributors navigating CE marking conformity and ECHA substance documentation requirements for cross-border trade.
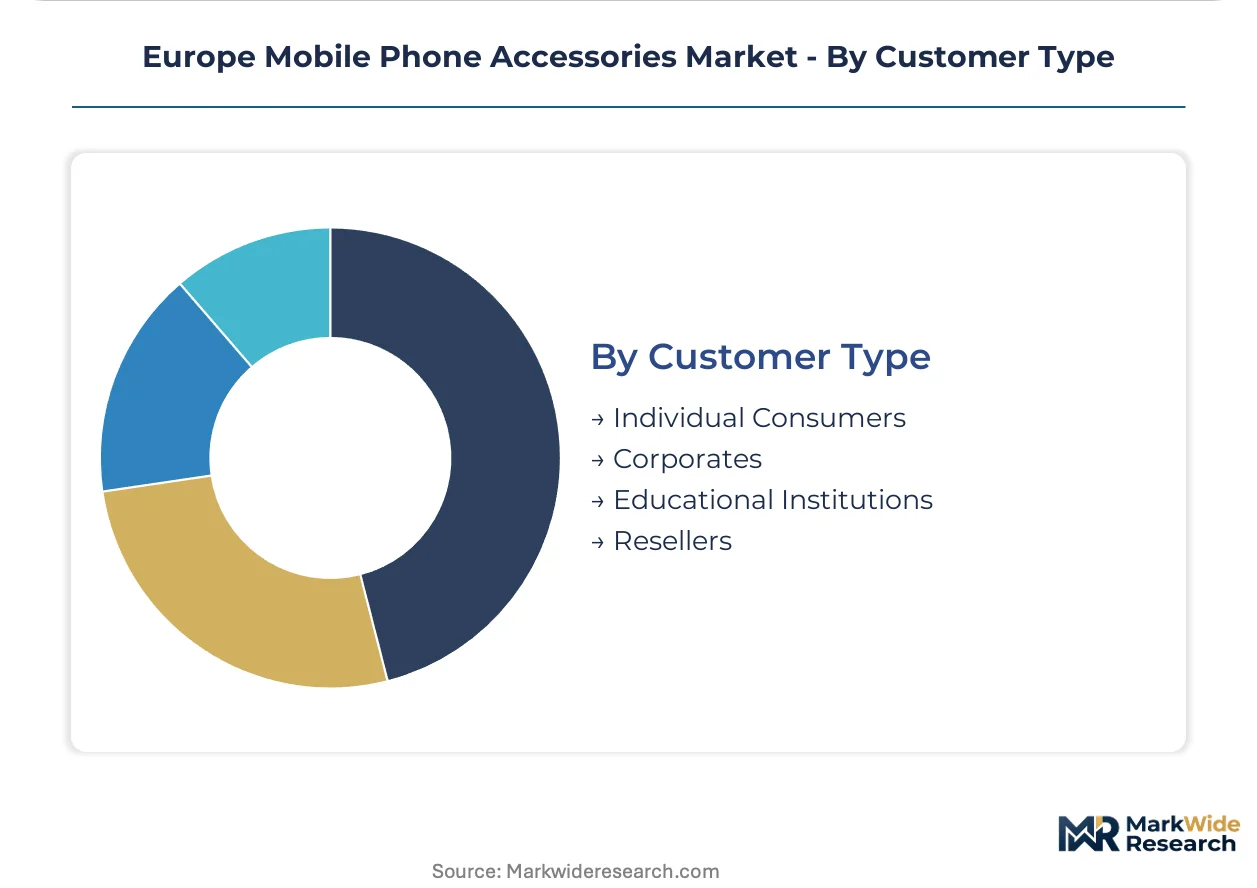
Individual consumers represent the deepest volume base; corporates are expanding most quickly on fleet standardization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Accessory production concentrates in Southeast Asian assembly hubs, while European consumption patterns diverge sharply across national regulatory and retail environments. The region's largest economies are pulling demand in distinct directions based on fleet standardization maturity and circular economy enforcement intensity.
Germany
Enterprise mobility programs at logistics firms and automotive suppliers are driving bulk procurement of GaN chargers and modular cases. The country's national market surveillance authority conducts unannounced port inspections for CE marking violations, tightening compliance timelines for importers. Berlin and Munich host dense electronics retail networks where Ecodesign-compliant products command preferential shelf placement.
France
Repairability index mandates are forcing accessory designers toward click-fit connectors and published disassembly scores. The national pharmaceutical and environmental regulator ANSM enforces extended producer responsibility frameworks alongside REACH substance documentation. Lyon and Paris clusters see active redesign of headphone and charging dock categories to achieve index compliance.
Netherlands
Field service corporations operating across Benelux corridors are consolidating supplier relationships through mobility management platforms. The Dutch national market authority aligns with EMA surveillance protocols for electromagnetic compatibility enforcement. Rotterdam's logistics hub supports direct-to-consumer fulfillment networks serving underpenetrated Eastern European markets.
Poland
Smartphone ownership rates outpace accessory attachment rates, creating whitespace for online retail expansion. The country's national standards body implements EU Ecodesign directives with phased compliance windows for recycled content claims. Warsaw and Krakow e-commerce logistics networks are maturing rapidly, attracting direct-to-consumer investments from Asian manufacturers.
Italy
Specialty retail channels in Milan and Rome maintain strong positions for premium audio peripherals and protective solutions. Italian market surveillance authorities coordinate with German and French counterparts on gray-market import interdiction. Southern regions show lagging enterprise fleet standardization compared to Northern industrial corridors.
Europe Mobile Phone Accessories Market Competitive Landscape
Top-tier vendors anchor premium-channel positioning, while mid-tier specialists compete on Ecodesign compliance speed and direct-to-consumer logistics reach. The vendor base stratifies across three distinct tiers: multinational electronics conglomerates with captive accessory portfolios, specialized power electronics and audio firms, and price-focused direct-to-consumer platforms. Two dominant competitive moves are reshaping positioning: backward integration into GaN semiconductor sourcing and strategic partnerships with enterprise mobility management platforms.
Within the multinational conglomerate tier, Samsung Electronics Co., Ltd. and Apple Inc. occupy positions defined by ecosystem lock-in and retail channel control. Sennheiser Electronic GmbH & Co. KG exemplifies the specialized audio archetype, anchoring premium positioning in broadcast-quality peripherals. Xiaomi Corporation represents the direct-to-consumer platform model, leveraging logistics infrastructure to undercut traditional retail in price-sensitive Eastern European markets.
| Leading Market Players |
|---|
| Belkin International, Inc. |
| Bose Corporation |
| Apple Inc. |
| Panasonic Corporation |
| Xiaomi Corporation |
| Samsung Electronics Co., Ltd. |
| Sennheiser Electronic GmbH & Co. KG |
| Amazon Inc. |
| Sony Corporation |
| Others |
Supply & Pricing Matrix
Enterprise fleet managers consolidating procurement across Benelux logistics corridors command volume-based contract structures that compress unit economics for standard protective cases and GaN charging hardware. Their negotiated tier pricing feeds upstream into supplier choices favoring Southeast Asian assembly with modular component sourcing to preserve margin.
Pricing Analysis
Cost-down pressure on mid-tier accessories accelerates because REACH documentation requirements and silicone feedstock volatility squeeze converter margins. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked GaN chargers with thermal engineering certification from uncertified gray-market alternatives. Price differentiation hinges on Ecodesign compliance documentation and after-sales warranty bundling. Individual consumers in Eastern European online channels exhibit highest price sensitivity; enterprise procurement teams in Germany and France prioritize protocol interoperability over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke fulfillment networks serving electronics retailers and direct-to-consumer platforms. Final assembly concentrates in Vietnam, China, and Malaysia for precision connectors and GaN semiconductor modules. Raw material dependencies span petrochemical-derived silicone, rare earth elements for magnet arrays, and copper for cable conductors. Single-source vulnerability in GaN wafer fabrication exposes lead times to maritime disruption. Distribution runs through specialized electronics distributors in Germany and carrier-branded retail in Southern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Ecodesign for Sustainable Products Regulation erects a compliance moat favoring incumbent suppliers with documented recycled content chains and modular repairability scores. First-movers capturing shelf space at German electronics retailers secure defensible positioning against gray-market entrants lacking certification infrastructure.
For Market Incumbents: Extend backward integration into post-industrial silicone recycling streams to secure Ecodesign-compliant feedstock pricing. Anchor channel control through exclusive enterprise mobility platform partnerships before logistics corporations consolidate supplier panels. Threat substitution from direct-to-consumer Asian platforms intensifies margin pressure in Eastern European price tiers.
For New Entrants and Emerging Players: Direct-to-consumer logistics investments in Poland and Romania bypass traditional electronics retail density gaps. White-space concentrates in battery passport preparation services and disassembly documentation systems ahead of EU battery regulation implementation. Go-to-market through subscription replenishment models for enterprise fleet accessory refresh cycles captures recurring revenue without retail slotting fee burdens.
For Investors and Strategic Acquirers: The window for entry favors specialized power electronics firms with GaN thermal engineering capabilities and established CE marking pathways. Long-term viability centers on acquisition targets combining Ecodesign compliance speed with direct-to-consumer logistics infrastructure. Signal to watch: French and German repair index scoring publication timelines that will reshape aftermarket pricing structures and spare parts availability economics.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Backward Integration | Captive wafer sourcing insulates margin from power electronics talent scarcity and supply concentration. |
| Battery Passport System Development | Digital product passport infrastructure anticipates EU battery regulation and commands enterprise procurement preference. |
| Enterprise Mobility Platform Partnership | Integration with fleet management software bundles hardware procurement with device enrollment telemetry. |
| Eastern European E-commerce Expansion | Direct-to-consumer logistics in Poland and Romania exploits underdeveloped accessory attachment rates relative to smartphone ownership. |
| Modular Repairability Redesign | Click-fit connector engineering achieves French repairability index compliance and extends product lifecycle revenue. |
Research Methodology
Document review covered EU regulatory filings, ECHA substance documentation databases, and enterprise mobility platform technical specifications, complemented by interviews with accessory category managers at German electronics retailers, procurement leads at Benelux logistics corporations, GaN power electronics engineers, and Ecodesign compliance officers. Secondary validation drew from customs trade data, REACH SVHC candidate list updates, and Wireless Power Consortium protocol documentation. Bottom-up demand modeling triangulated against top-down market sizing across product type, material, distribution channel, and customer type segmentation.
Cross-reference between historical shipment patterns and expert panel input anchored volume projections across the modeling period. Segmentation dimensions modeled include product category, material compliance tier, distribution channel economics, and procurement sophistication level. CAGRs derived from trajectory fitting to documented enterprise fleet standardization trends and Ecodesign mandate phase-in schedules. Industry-specific inputs incorporated GaN adoption curves, silicone feedstock price indices, and repairability index scoring implementation timelines.
The model holds under sustained EU regulatory enforcement intensity and stable maritime logistics capacity; deviation in REACH substance list expansion velocity or Southeast Asian assembly disruption would shift volume and value outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Electronic Products Rental Market
Consumer Electronics
Baby Monitor Market
Consumer Electronics
North America Wireless Anc Headphone Market
Consumer Electronics
Gaming Mouse & Keyboards Market
Consumer Electronics
Global Smart Earbuds Market
Consumer Electronics
Foldable Phone Market
Consumer Electronics
Smart Mirror TV Market
Consumer Electronics
Gaming Keyboard Market
Consumer Electronics
Consumer Electronic Accessories Market
Consumer Electronics
Waterproof Headphones Market
Consumer Electronics
Electronics Accessories Market
Consumer Electronics
Silicone Sex Doll Market
Consumer Electronics
Streaming Devices Market
Consumer Electronics
Gaming Computer Market
Consumer Electronics
Global Wireless Headphones Market
Consumer Electronics
GCC Soundbar Market