
 Asia-Pacific Gene Synthesis Market | 2026-2036
Asia-Pacific Gene Synthesis Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Gene Synthesis Market Outlook
Academic institutes is collapsing as the dominant buyer archetype as pharmaceutical companies and biotech firms accelerate in-house gene synthesis programs. GenScript Biotech Corporation leverages its integrated service platform across research through commercial-scale production. Twist Bioscience Corporation differentiates through silicon-based DNA synthesis technology that reduces cost per base. Thermo Fisher Scientific anchors regional distribution through its established life sciences infrastructure across East Asian metropolitan hubs.
Gene synthesis denotes the de novo construction of DNA sequences through chemical or enzymatic methods, typically producing double-stranded DNA fragments ranging from hundreds to thousands of base pairs for protein expression, pathway engineering, or therapeutic vector construction. Oligonucleotide synthesis underpins most commercial workflows, while Gibson Assembly gains traction for seamless multi-fragment cloning in complex metabolic engineering projects. Synthetic genes command premium positioning due to validation requirements and codon optimization services, whereas gene fragments serve high-volume research screening applications with faster turnaround expectations.
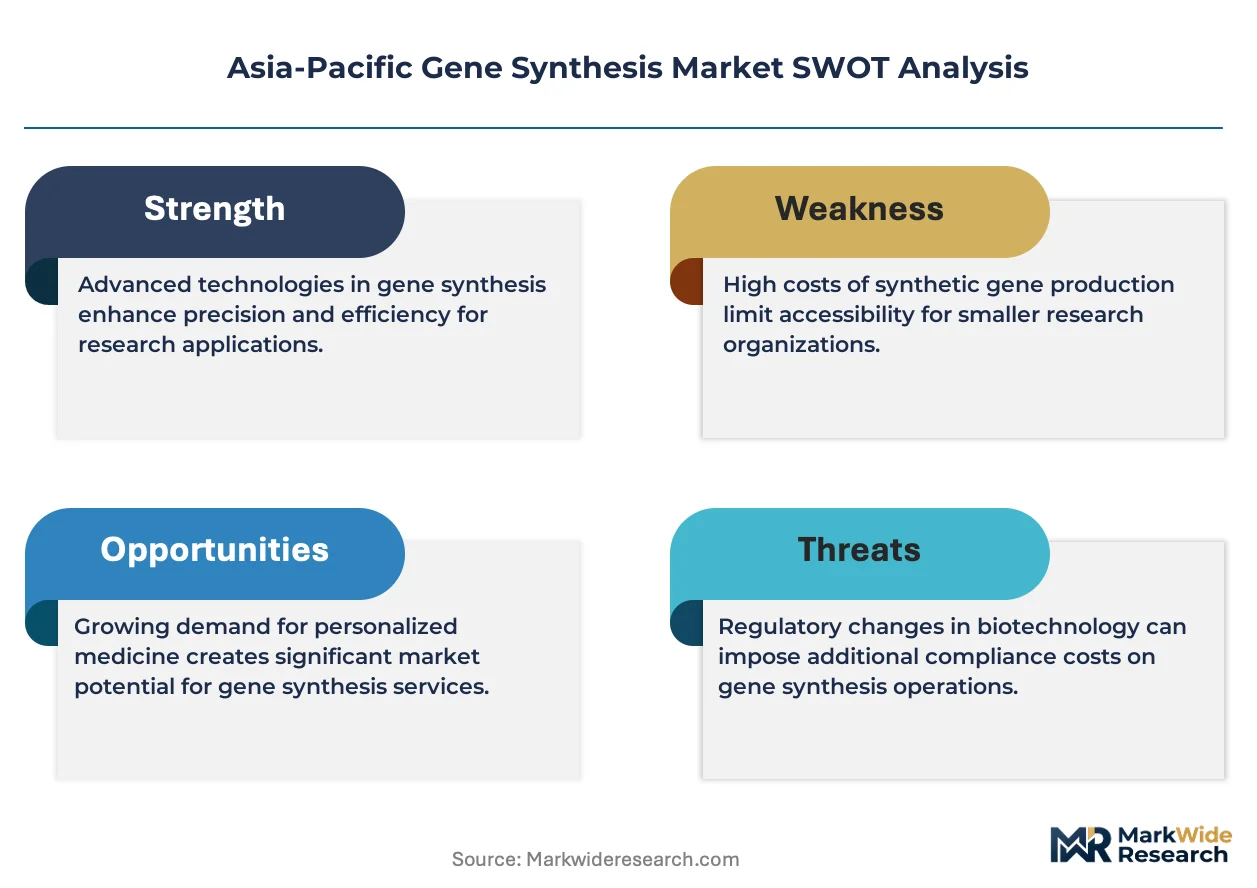
China's NMPA and Japan's PMDA impose divergent quality documentation standards on imported synthetic DNA, creating compliance segmentation across national boundaries. India's CDSCO and Australia's TGA maintain distinct biosecurity screening protocols for gene constructs, affecting cross-border service logistics. South Korea's MFDS actively incorporates synthetic biology products into its regenerative medicine evaluation frameworks. Stakeholders must assess which regulatory pathway—pharmaceutical, agricultural, or research-use—delivers the fastest validation timeline for their specific construct category.
Market Dynamics
China's NMPA biologics approval streamlining is compressing gene synthesis validation timelines from 18 months to under 9 months, triggering a cascade of capacity investments across the eastern biotech corridor.
Growth Catalysts
- Regulatory Acceleration:NMPA's optimized IND review pathways for cell and gene therapies are expanding synthetic DNA procurement volumes from CMOs serving clinical-stage developers.
- Academic-Industrial Consortia:Shanghai-Suzhou corridor institutions are pooling sequencing infrastructure with commercial gene synthesis providers, reducing per-project validation overhead.
- Silicon-Based Synthesis:Semiconductor-derived DNA production platforms are cutting reagent consumption and enabling parallel synthesis of variant libraries for CRISPR screening applications.
Market Restraints
- Phosphoramidite Supply Concentration:Three Japanese chemical manufacturers control 70% of ultra-high-purity phosphoramidite precursors, exposing synthesis providers to input cost volatility and allocation risk.
- Cross-Border Biosecurity Friction:Australia's TGA and India's CDSCO maintain non-harmonized gene construct screening protocols, fragmenting regional service logistics and extending customs clearance timelines.
- Enzymatic Synthesis Substitution:Terminal deoxynucleotidyl transferase-based methods are displacing phosphoramidite chemistry for fragments under 200 base pairs, eroding margins in high-volume screening segments.
Strategic Opportunities
- South Korean Regenerative Medicine:MFDS incorporation of synthetic biology constructs into cell therapy evaluation frameworks is opening dedicated procurement channels for GMP-grade gene synthesis.
- Agricultural Biotechnology:Gene stacking for climate-resilient rice varieties is driving demand for multi-gene pathway assembly services from national agricultural research institutes.
- Cloud-Connected Ordering Platforms:API-integrated procurement systems are displacing email-based quotation workflows, enabling real-time design validation and automated codon optimization.
Industry Challenges
- Bioinformatics Talent Scarcity:Shortages of computational biologists proficient in automated sequence validation and error correction are constraining quality assurance throughput at mid-scale providers.
- GMP Certification Timelines:ISO 13485 and NMPA GMP dual certification for clinical-grade synthetic DNA requires 14-18 months, delaying market entry for new production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Gene Synthesis Market |
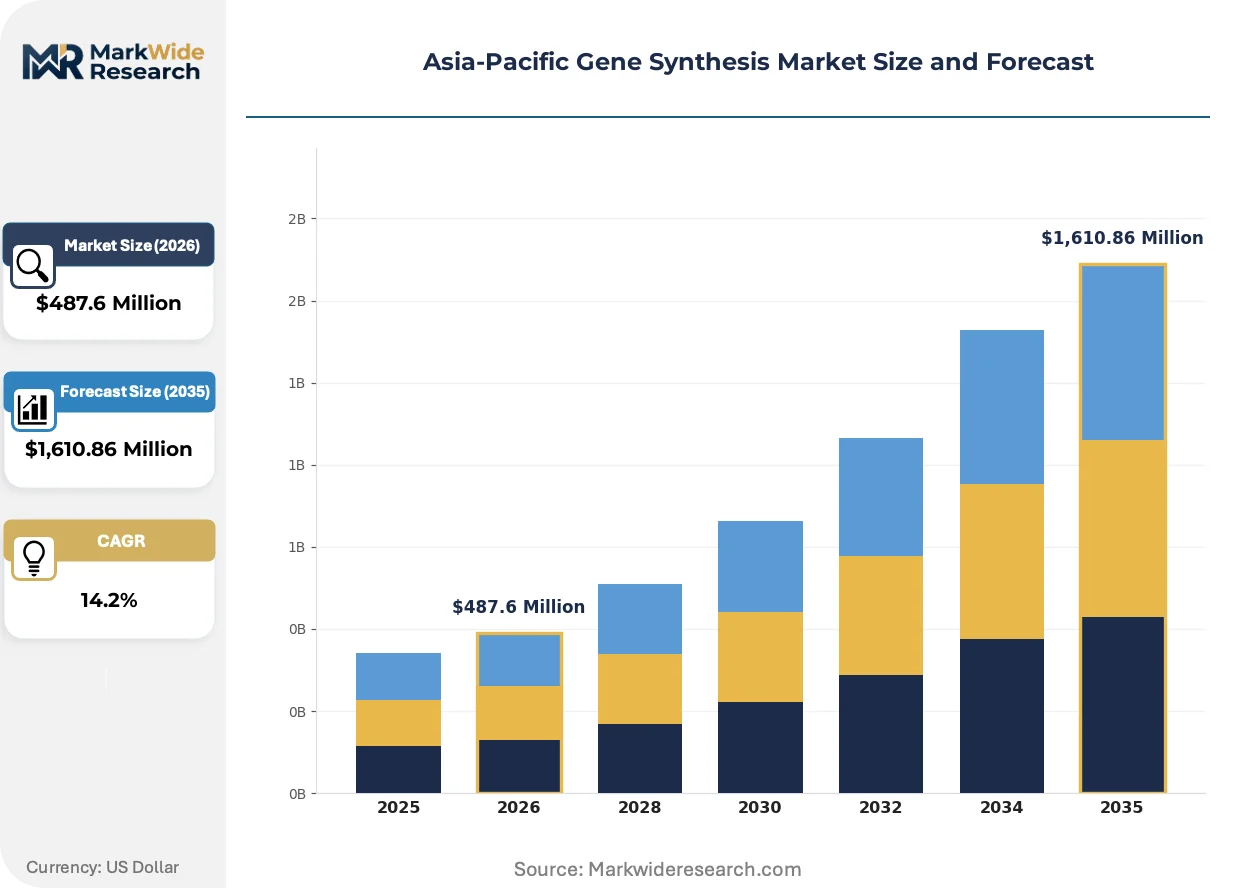
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Fragments, Genes, Gene Constructs, Synthetic Genes Technology: PCR-based, Oligonucleotide Synthesis, Gibson Assembly, Ligation Application: Research, Therapeutics, Agriculture, Diagnostics End User: Pharmaceutical Companies, Academic Institutes, Biotech Firms, Contract Research Organizations |
| Companies Covered | GenScript Biotech Corporation, Thermo Fisher Scientific, Twist Bioscience Corporation, Integrated DNA Technologies, Boster Biological Technology, MACROGEN CO., LTD., Bioneer Pacific, OriGene Technologies, Brooks Automation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Gene Synthesis Market Strategic Shifts
Gene synthesis workflows are fragmenting into specialized tiers as pharmaceutical developers demand clinical-grade documentation while research screening prioritizes speed over validation depth.
Enzymatic DNA synthesis is bifurcating market positioning between ultra-long fragment production and high-throughput variant library generation. Agricultural biotechnology institutes are adopting enzymatic methods for pathway assembly projects exceeding 10 kilobases. This technology is bifurcating the competitive landscape into phosphoramidite-dominated short-fragment specialists and enzymatic-platform players controlling the long-fragment premium tier.
South Korea's MFDS has issued guidance integrating synthetic gene constructs into regenerative medicine product evaluation frameworks. This policy shift is mandating GMP-grade documentation for gene synthesis inputs previously classified as research-use-only. Cell therapy developers in Seoul and Songdo are responding by qualifying dedicated synthetic DNA suppliers under the new pathway.
Consolidated procurement through centralized biotech park purchasing offices is displacing direct vendor relationships for academic consortia. The eastern China biotech corridor's shared service centers are aggregating gene synthesis demand from 40+ institutes, extracting volume pricing and standardized SLAs. This concentration is most visible in Suzhou Industrial Park, where procurement committees now manage annual synthetic DNA contracts exceeding institutional individual purchasing thresholds.
Asia-Pacific Gene Synthesis Market Segmentation
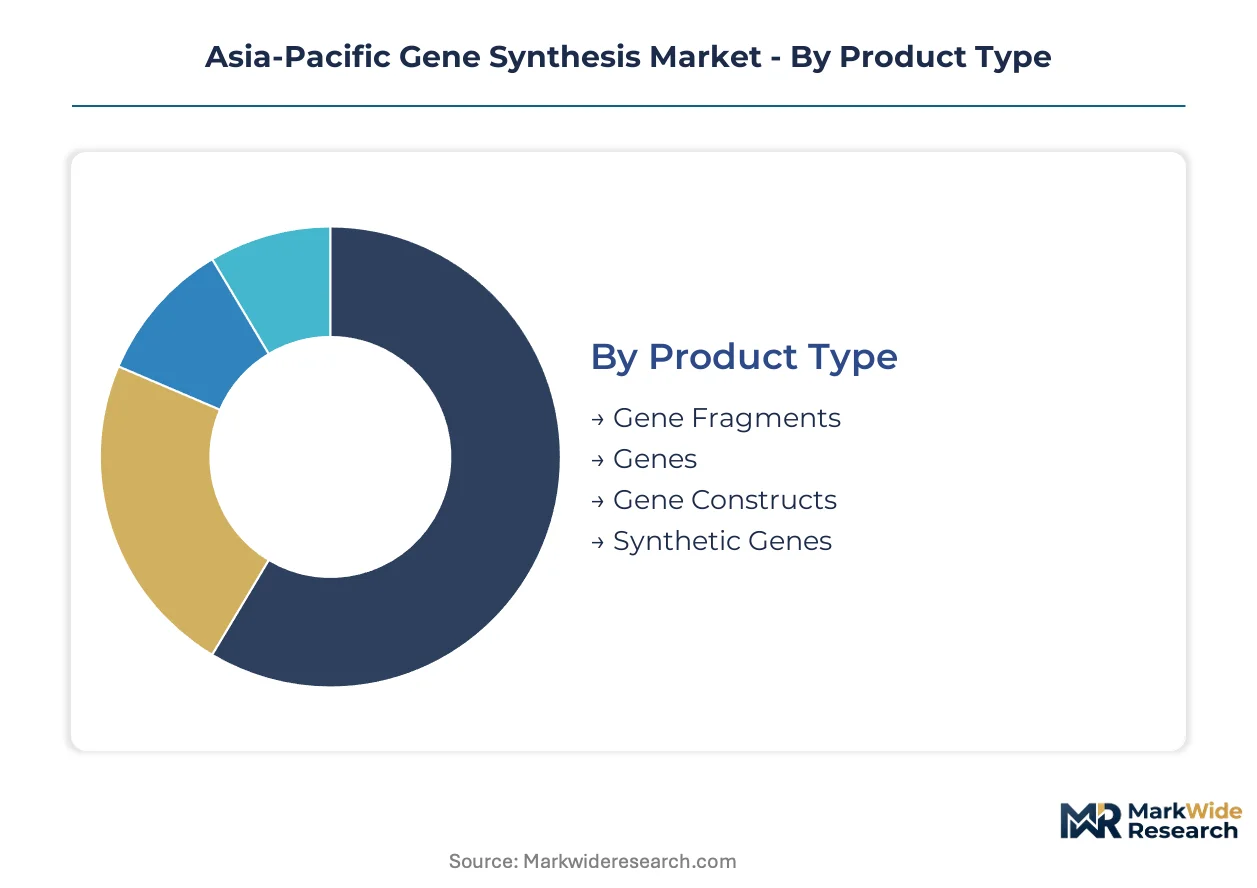
Gene synthesis procurement patterns across Asia-Pacific diverge sharply by product complexity and regulatory pathway. Segmentation reveals how clinical-grade documentation requirements reshape supplier selection while research screening prioritizes turnaround speed over validation depth.
Product Type:
Domestic consumption concentrates in shorter fragments for CRISPR screening across Chinese and South Korean academic clusters, while export-oriented synthetic gene production serves multinational pharmaceutical developers requiring NMPA-aligned documentation.
- Synthetic Genes:Full-length coding sequences with codon optimization and regulatory-compliant documentation. Demand clusters in Shanghai-Suzhou corridor cell therapy developers navigating MFDS and NMPA dual-pathway submissions.
- Genes:Standardized expression cassettes for protein production workflows. Japanese pharmaceutical companies source these through PMDA-registered suppliers for biologics manufacturing support.
- Gene Fragments:Uncloned DNA segments under 500 base pairs for assembly workflows. High-volume procurement from Australian agricultural institutes drives regional pricing benchmarks.
- Gene Constructs:Multi-component assemblies incorporating promoters, terminators, and selection markers. Indian CDSCO screening protocols create customs friction for cross-border shipments.
Synthetic genes hold the largest share; momentum sits with gene fragments as enzymatic synthesis displaces phosphoramidite methods below 200 base pairs.
Technology:
Cost stratification separates semiconductor-enabled platforms commanding premium positioning from chemistry-dependent methods competing on per-base economics in high-throughput screening.
- Oligonucleotide Synthesis:Phosphoramidite chemistry remains the backbone of commercial production. Japanese chemical manufacturers control precursor supply, exposing providers to allocation risk during demand surges.
- Gibson Assembly:Seamless multi-fragment cloning enables complex metabolic engineering without restriction sites. Agricultural biotechnology institutes in China adopt this for pathway assembly exceeding 10 kilobases.
- PCR-based:Amplification-dependent methods for template-derived sequence production. Cost-competitive for variant library generation where error rates permit iterative screening.
- Ligation:Enzymatic joining of pre-synthesized fragments. Declining share as Gibson methods reduce scar sequences in multi-gene stacking applications.
Oligonucleotide synthesis dominates current revenue; Gibson Assembly is climbing the fastest as agricultural and cell therapy applications demand seamless cloning.
Application:
Volume concentration varies by validation tier—research screening tolerates higher error rates while therapeutic applications mandate ISO 13485-aligned production records.
- Research:Exploratory applications across genomics and molecular biology. Academic consortia in Suzhou Industrial Park aggregate demand through shared procurement offices.
- Therapeutics:Clinical-grade synthetic DNA for cell and gene therapy vectors. NMPA streamlining of IND reviews compresses procurement cycles from 18 months to under 9 months.
- Agriculture:Climate-resilient crop development through multi-gene pathway engineering. Australian TGA biosecurity screening extends logistics timelines for imported constructs.
- Diagnostics:Synthetic controls and reference materials for assay validation. South Korean MFDS integration of synthetic biology into regenerative medicine frameworks opens dedicated procurement channels.
Research commands the greatest volume; therapeutics delivers the steepest expansion trajectory as regulatory acceleration triggers capacity investments.
End User:
Procurement centralization is displacing direct vendor relationships as biotech parks aggregate demand from clustered institutes and CROs.
- Biotech Firms:Venture-backed developers outsourcing synthetic DNA for pipeline acceleration. Eastern China corridor firms expand in-house programs as NMPA pathways mature.
- Academic Institutes:Traditional anchor of gene synthesis consumption. Consolidated purchasing through shared service centers now extracts volume pricing from 40+ Suzhou institutions.
- Pharmaceutical Companies:Multinational developers requiring GMP-grade documentation for commercial manufacturing. Dual ISO 13485 and NMPA certification requirements delay supplier qualification.
- Contract Research Organizations:Service providers bridging design and production for sponsor firms. CRO clusters in Shanghai anchor regional consumption through integrated service platforms.
Academic institutes retain the largest installed base; biotech firms are gaining share fastest as venture funding flows toward synthetic biology-enabled therapeutics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Suzhou high-speed rail corridor underwrites China's dominance in Asia-Pacific gene synthesis, compressing logistics timelines between biotech clusters and enabling same-day sample transport for validation workflows.
China
Cell therapy developers in Shanghai and Suzhou drive synthetic DNA procurement volumes as NMPA streamlines IND reviews. The regulator's optimized biologics pathways cut validation timelines from 18 months to under 9 months. Shared service centers in Suzhou Industrial Park now aggregate demand from 40+ institutes, extracting standardized SLAs through consolidated procurement.
Japan
PMDA-registered suppliers serve pharmaceutical manufacturers requiring ISO 13485-aligned documentation for biologics manufacturing support. METI coordinates academic-industrial consortia advancing enzymatic synthesis platforms. Tokyo-Yokohama biotech clusters anchor premium-tier synthetic gene production for export markets.
South Korea
MFDS integration of synthetic biology into regenerative medicine frameworks mandates GMP-grade documentation for gene synthesis inputs. Cell therapy developers in Seoul and Songdo qualify dedicated suppliers under the new pathway. Government-funded bioclusters in Daejeon-Sejong support domestic enzymatic synthesis R&D.
India
CDSCO screening protocols create customs friction for imported gene constructs, fragmenting cross-border service logistics. Contract research organizations in Hyderabad and Bangalore expand in-house phosphoramidite capacity to bypass import delays. National agricultural institutes drive gene fragment demand for climate-resilient crop development.
Australia
TGA biosecurity screening extends clearance timelines for synthetic DNA shipments, compressing margins on time-sensitive research projects. Agricultural biotechnology institutes in Queensland and New South Wales adopt enzymatic methods for multi-gene pathway assembly exceeding 10 kilobases. Domestic providers leverage this regulatory gap to capture institutional procurement.
Asia-Pacific Gene Synthesis Market Competitive Environment
Listed leaders compete with private specialists across documentation tiers, with public companies dominating GMP-certified production and venture-backed firms capturing research-screening volumes. The vendor base stratifies into three tiers: integrated platform providers, silicon-based technology specialists, and regional chemistry-dependent producers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as dual ISO 13485 and NMPA certification requirements delay new facility qualification.
Among integrated platform providers, GenScript Biotech Corporation exemplifies the full-service archetype spanning research through commercial-scale production. Twist Bioscience Corporation occupies a position on the silicon-based technology vector, while Thermo Fisher Scientific anchors the distribution infrastructure tier across East Asian metropolitan hubs. These three entities represent distinct strategic postures within the regional competitive structure.
| Leading Market Players |
|---|
| GenScript Biotech Corporation |
| Thermo Fisher Scientific |
| Twist Bioscience Corporation |
| Integrated DNA Technologies |
| Boster Biological Technology |
| MACROGEN CO., LTD. |
| Bioneer Pacific |
| OriGene Technologies |
| Brooks Automation |
| Others |
Value Chain & Pricing Dynamics
Nine-month validation timelines under NMPA's streamlined biologics pathway compress procurement cycles and concentrate pricing power among GMP-certified providers serving Shanghai-Suzhou corridor cell therapy developers. This lead-time compression rewards vertically integrated suppliers while fragmenting research-grade pricing across enzymatic-platform entrants.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification status and NMPA GMP alignment. Premium tiers attach to clinical-grade synthetic genes with full validation documentation; economy tiers serve CRISPR screening fragments where enzymatic synthesis displaces phosphoramidite methods below 200 base pairs. Pricing pressure stems from enzymatic-platform entrants eroding margins in high-volume research segments. Academic consortia exhibit highest price sensitivity; pharmaceutical manufacturers prioritize documentation depth over per-base cost.
Supply Chain Analysis
Japanese chemical manufacturers' control over ultra-high-purity phosphoramidite precursors exposes synthesis providers to allocation risk during demand surges. Production concentrates in China, Japan, and South Korea, with raw material dependencies spanning phosphoramidite reagents, semiconductor-grade silicon substrates, and terminal deoxynucleotidyl transferase enzymes. Single-source vulnerability in precursor supply creates structural exposure to input cost volatility. Distribution runs through biotech park shared service centers aggregating demand from clustered academic institutes and CROs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement offices in Suzhou Industrial Park and similar biotech corridors, extracting volume pricing from 40-plus institutions and displacing direct vendor relationships.
For Market Incumbents: Shield GMP-certified production capacity from enzymatic-platform substitution by accelerating dual ISO 13485 and NMPA certification timelines. Prioritize backward integration into phosphoramidite precursor supply through offtake agreements with Japanese chemical manufacturers. Defensive positioning rests on clinical-grade documentation depth that research-platform entrants cannot replicate. For New Entrants and Emerging Players: NMPA GMP fast-track qualification for cell therapy suppliers opens white-space entry in South Korean regenerative medicine procurement channels under MFDS guidance. Target agricultural biotechnology institutes in Australia and India adopting enzymatic methods for multi-gene pathway assembly exceeding 10 kilobases. Cloud-connected API-integrated ordering platforms enable automated codon optimization as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational life sciences conglomerates divesting non-core gene synthesis divisions amid portfolio rationalization. Long-term viability favors enzymatic-platform specialists with demonstrated 10-kilobase-plus fragment capability and agricultural biotechnology customer concentration. Watch enzymatic synthesis cost-parity thresholds with phosphoramidite chemistry as inflection indicator for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Fast-Track | ISO 13485 and NMPA GMP alignment compresses supplier qualification timelines for clinical-grade synthetic DNA. |
| Phosphoramidite Supply Security | Long-term offtake agreements with Japanese precursor manufacturers mitigate allocation risk during demand surges. |
| Enzymatic Platform Scale-Up | 10-kilobase-plus fragment production capability captures agricultural biotechnology pathway assembly demand. |
| Cloud-Connected Procurement Integration | API-enabled ordering platforms displace email-based workflows with real-time design validation. |
| Biotech Park Service Center Partnership | Shared procurement office aggregation extracts volume pricing from 40-plus institutional customers. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with gene synthesis procurement directors, regulatory affairs leads at NMPA and MFDS, CRO operations managers, and agricultural biotechnology institute heads; and secondary validation through NMPA biologics filings, MFDS regenerative medicine guidance documents, phosphoramidite trade flow data, and biotech park procurement committee records. Bottom-up segment sizing triangulated against top-down market boundary analysis.
Across the projection horizon, the analytical framework modeled gene synthesis demand by product complexity tier, regulatory pathway, and end-user concentration pattern. CAGRs derived from segment-level growth rate blending weighted by procurement volume concentration in Shanghai-Suzhou corridor and enzymatic-platform adoption curves in agricultural applications. Forecast inputs incorporated NMPA IND review timeline compression and MFDS synthetic biology integration policy shifts.
Decision-makers should treat outputs as directional under assumptions of sustained NMPA regulatory acceleration and phosphoramidite supply stability; material deviation in enzymatic synthesis cost-parity timing or biosecurity screening protocol harmonization would warrant model refresh. Revision becomes warranted when enzymatic-platform fragment pricing crosses below phosphoramidite economics in sub-200-base-pair segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Biology
Difficult-To-Express Proteins Market
Synthetic Biology
Gene Synthesis (Research Use) Market
Synthetic Biology
Synthetic Stem Cells Market
Synthetic Biology
Synthetic Hormones Market
Synthetic Biology
Transient Protein Expression Market
Synthetic Biology
Mutation Generation Systems Market
Synthetic Biology
Global Cell-Free Protein Expression Market
Synthetic Biology
DNA Synthesizer Market
Synthetic Biology
Synthetic Genomics Market