
 Synthetic Hormones Market | 2026-2036
Synthetic Hormones Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Hormones Market Intelligence
Manufacturing capacity for complex biologic-based hormones is shifting towards specialized contract development and manufacturing organizations. This strategic move allows major pharmaceutical firms to focus on core R&D and commercialization. Pfizer leverages its extensive pipeline for oncology-related hormonal therapies. Novo Nordisk dominates the metabolic diseases space with its portfolio of synthetic insulins and GLP-1 agonists.
Synthetic hormones are laboratory-manufactured molecules designed to replicate the function of endogenous hormones. Produced via chemical synthesis or recombinant DNA technology, they are used to treat deficiencies or modulate physiological processes. Thyroid hormones and corticosteroids constitute large, established product segments within the market. In contrast, advanced delivery modes like injectables and transdermal patches for therapies in oncology and reproductive health represent the fastest-growing areas.
The U.S. FDA and the European Medicines Agency (EMA) mandate extensive clinical trials to prove bioequivalence and safety for new synthetic hormone products. These stringent approval processes, along with similar standards from Japan's PMDA, govern market access and influence development timelines. Future success for manufacturers depends on managing a portfolio that balances innovation in new therapies with lifecycle management of established products.
Market Dynamics
The market's central dynamic is the division between high-volume, commoditized segments like thyroid hormones and the high-growth, technically complex field of biologic-based hormones. This creates a bifurcated structure, demanding different manufacturing capabilities, R&D investments, and commercial strategies.
Growth Catalysts
- Recombinant DNA Technology:The application of this technology enables the production of complex protein-based hormones, such as GLP-1 agonists and synthetic insulins, expanding treatment paradigms for metabolic diseases and certain cancers.
- Aging Demographics:Growing elderly populations in developed economies, including Germany and the United States, increase the prevalence of endocrine disorders and menopause-related conditions, driving steady demand for hormone replacement therapies.
- Advanced Delivery Systems:Development of patient-centric delivery modes like long-acting injectables, transdermal patches, and subcutaneous implants improves therapeutic adherence and efficacy, particularly in chronic disease management.
Market Restraints
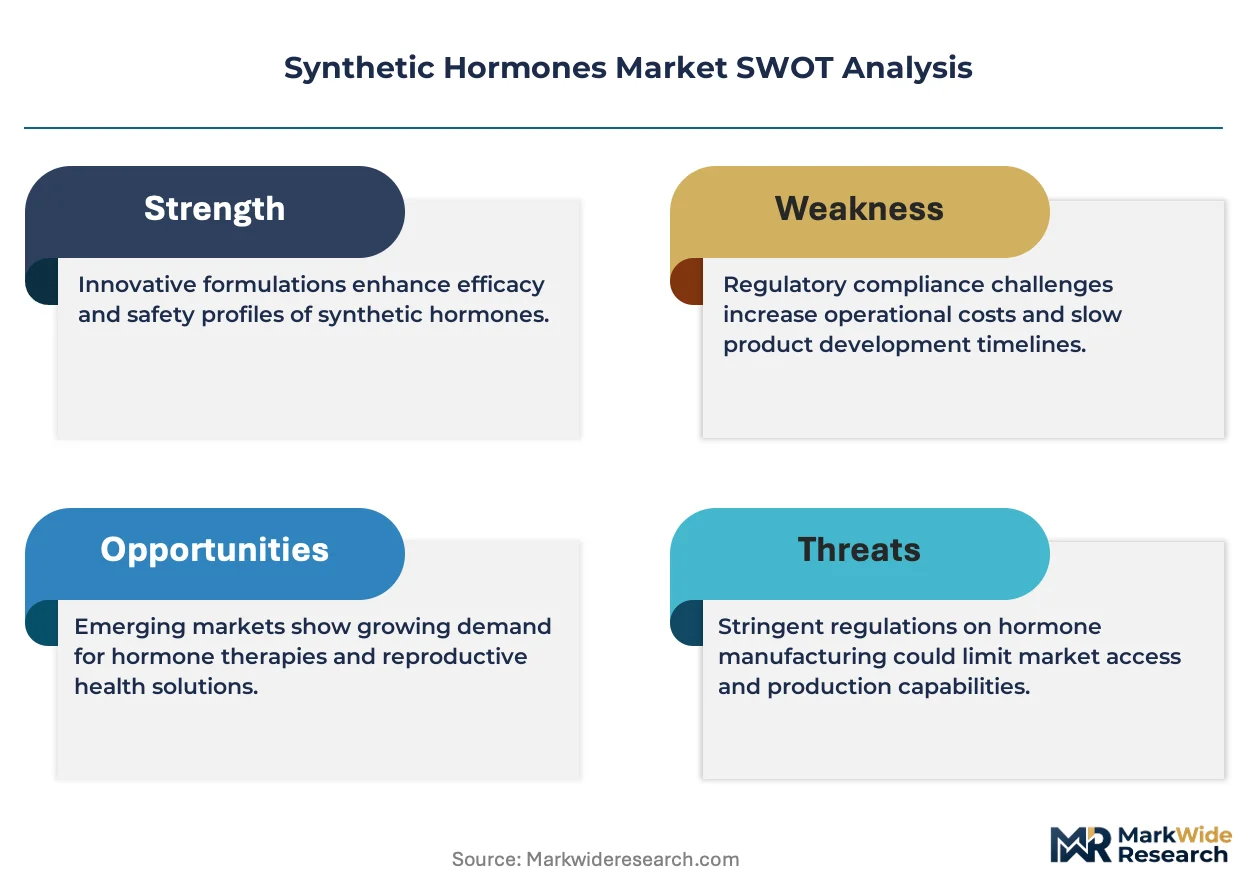
- Stringent Regulatory Hurdles:Extensive and costly clinical trials mandated by agencies like the U.S. FDA, EMA, and Japan's PMDA to prove safety and bioequivalence create high barriers to entry and lengthen development timelines.
- High Manufacturing Complexity:The production of biologic hormones requires significant capital investment in specialized facilities and bioprocessing expertise, constraining supply and elevating production costs compared to chemically synthesized molecules.
- Intellectual Property Risks:The complex patent landscape for biologics and the looming threat of biosimilar competition following patent expiration create investment uncertainty for originator drug developers.
Strategic Opportunities
- Emerging Market Expansion:Untapped patient populations in regions like Latin America and Southeast Asia, where healthcare spending and awareness of endocrine conditions are rising, offer significant growth potential for established hormone therapies.
- Personalized Hormone Therapies:Integrating genomic and biomarker data to tailor hormone treatments, especially in oncology and reproductive health, presents a frontier for developing highly effective, targeted therapies.
- Biosimilar Development:The expiration of patents for major biologic hormones, including certain insulins and growth factors, creates a substantial commercial opportunity for companies to produce and market lower-cost biosimilar versions.
Industry Challenges
- Outsourced Supply Chain Management:The strategic shift towards using contract manufacturing organizations for complex biologics introduces challenges in quality assurance, technology transfer, and supply chain visibility.
- Specialized Talent Scarcity:A shortage of experts in areas like bioprocess engineering, protein chemistry, and regulatory affairs for biologics can impede product development and manufacturing scale-up.
- Portfolio Balancing Act:Manufacturers face the operational challenge of allocating resources between investing in innovative, high-risk biologic pipelines and managing the lifecycle of mature, lower-margin synthetic hormone products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Hormones Market |
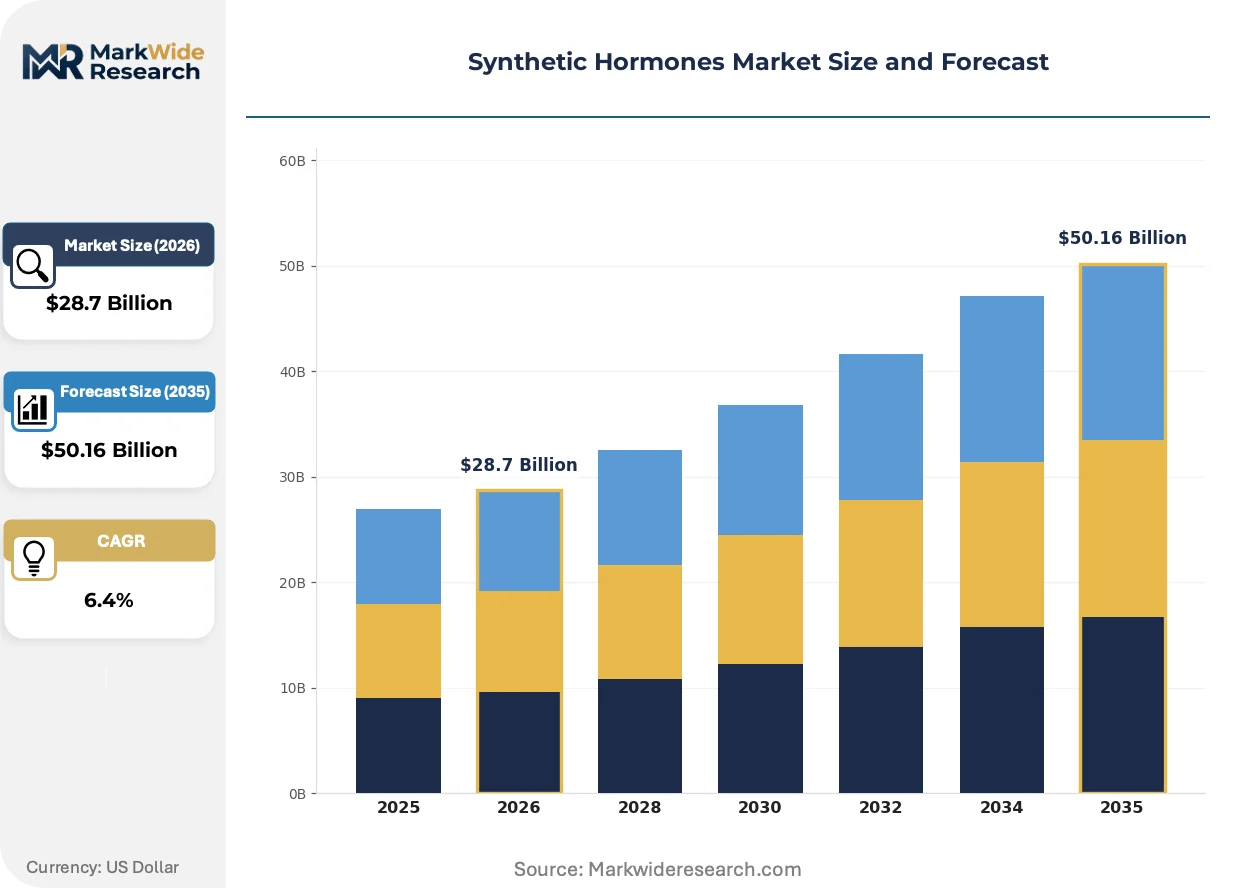
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Estrogens, Progestins, Androgens, Corticosteroids, Thyroid Hormones Therapy Area: Endocrine Disorders, Reproductive Health, Dermatology, Oncology, Metabolic Diseases End User: Pharmacies, Diagnostic Centers, Medical Clinics, Research Institutions, Specialists Delivery Mode: Oral, Injectable, Transdermal, Implantable, Nasal Spray |
| Companies Covered | Johnson & Johnson, Roche, Pfizer Inc., Sanofi SA, Merck & Co., Inc., Novo Nordisk A/S, Eli Lilly, AbbVie Inc., AstraZeneca PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Hormones Market Strategic Shifts & Innovations
Precision and patient convenience are actively reshaping the market. The industry is pivoting from one-size-fits-all treatments toward highly targeted therapies and self-administered formulations that improve quality of life and treatment outcomes for chronic conditions.
Recombinant DNA technology allows for the production of highly specific biologic hormones that are identical to those found in the human body. Pharmaceutical innovators in the metabolic disease and oncology sectors are rapidly adopting this production method for their pipelines. This bio-manufacturing process is overtaking traditional chemical synthesis for complex therapies, as it enables the creation of molecules with superior efficacy and safety profiles.
The European Medicines Agency's established pathway for biosimilar approval provides a clear and predictable regulatory framework for market entry. This policy stimulates price competition by enabling manufacturers to launch follow-on versions of off-patent biologics with a focused, but still rigorous, data package. Hormone categories like synthetic insulins and somatropin are most affected, compelling originators to innovate on next-generation products to protect market share.
A prominent behavioral shift involves patient preference for self-administered, long-acting hormone formulations over therapies requiring frequent clinical visits. This trend disrupts traditional distribution, favoring products like auto-injector pens and transdermal patches that are dispensed through retail pharmacy channels. This demand for greater autonomy in treatment management is most visible in the United States and Europe for chronic conditions like diabetes and osteoporosis.
Synthetic Hormones Market Segmentation
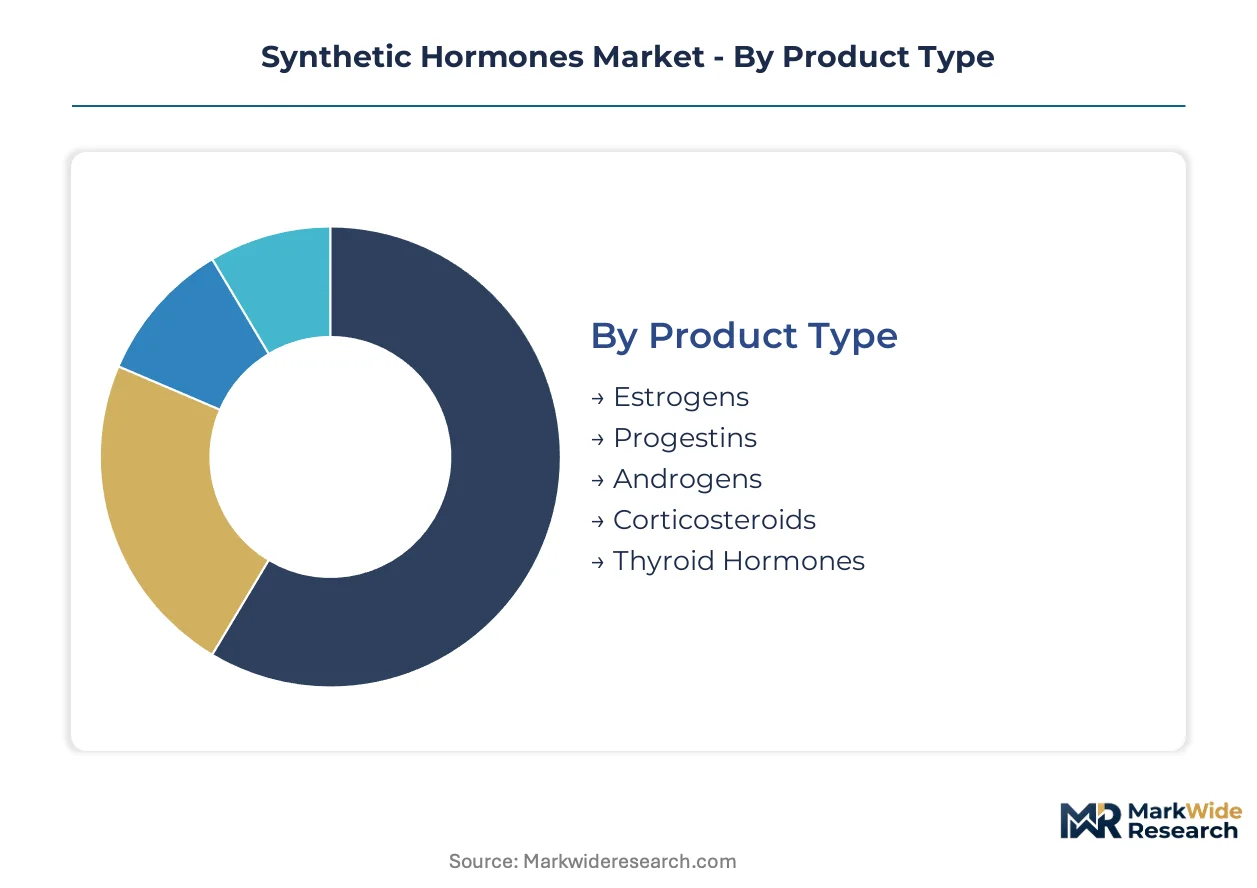
The synthetic hormones market exhibits diverse segmentation, reflecting varied product characteristics, therapeutic applications, and patient needs. Understanding these distinct segments allows manufacturers to tailor their product development, commercial strategies, and market access initiatives effectively.
Product Type:
The market for synthetic hormones splits between high-volume, established products and more specialized, often higher-value, therapeutic agents.
- Estrogens:These steroid hormones are primarily used in hormone replacement therapy for menopause symptoms and contraception, often delivered via oral tablets or transdermal patches. Demand concentrates in developed economies with aging female populations, particularly in the United States and Germany.
- Progestins:Synthetic progestogens find application in contraception, hormone replacement therapy, and the treatment of gynecological disorders like endometriosis.
- Androgens:These hormones, including testosterone, treat male hypogonadism and certain wasting syndromes, with demand growing among aging male populations.
- Corticosteroids:A broad class of steroid hormones, corticosteroids reduce inflammation and suppress the immune system, used in conditions ranging from asthma to autoimmune diseases.
- Thyroid Hormones:Primarily levothyroxine, these synthetic hormones treat hypothyroidism, representing a high-volume, foundational segment with widespread patient use. This segment is globally available.
Mature deployment sits with Thyroid Hormones. Newer deployment is concentrated in Estrogens.
Therapy Area:
Therapy areas define the specific medical conditions synthetic hormones address, ranging from chronic metabolic conditions to life-threatening cancers.
- Metabolic Diseases:This segment includes conditions like diabetes, where synthetic insulins and GLP-1 agonists are critical for glucose regulation, expanding treatment paradigms. Demand is accelerating globally due to rising prevalence of diabetes, particularly in regions like North America and Europe.
- Oncology:Hormonal therapies for cancers, such as prostate and breast cancer, utilize synthetic hormones to block or stimulate hormone receptors, offering targeted treatment options. Pfizer leverages its extensive pipeline for oncology-related hormonal therapies.
- Endocrine Disorders:This broad category encompasses conditions like growth hormone deficiency, adrenal insufficiency, and pituitary disorders, requiring precise hormone replacement.
- Reproductive Health:Synthetic hormones are central to fertility treatments, contraception, and managing conditions like polycystic ovary syndrome.
- Dermatology:Hormonal treatments address certain skin conditions, including acne and hirsutism, often involving topical or systemic hormone modulation.
Therapy areas like Endocrine Disorders drive significant patient volume, while Oncology focuses on specialized treatment needs.
End User:
The end-user landscape reflects where patients access and receive synthetic hormone therapies, influencing distribution channels and product formulations.
- Pharmacies:Retail and hospital pharmacies serve as primary dispensing points for a wide array of synthetic hormone prescriptions, including self-administered medications. This channel supports broad patient access for chronic conditions in countries like the United States.
- Specialists:Endocrinologists, oncologists, and reproductive health specialists directly prescribe and often administer complex hormone therapies, particularly biologics. These physicians manage intricate dosing regimens.
- Diagnostic Centers:These facilities conduct hormone level testing, which informs the diagnosis and monitoring of hormone deficiencies or excesses, guiding therapeutic decisions.
- Medical Clinics:General practitioners and family medicine clinics manage common hormone-related conditions and prescribe standard synthetic hormone treatments.
- Research Institutions:Academic and private research bodies utilize synthetic hormones for drug discovery, clinical trials, and understanding physiological processes.
Demand for hormone therapies through Pharmacies supports broad access, whereas Specialists engagements focus on complex patient management.
Delivery Mode:
Delivery modes represent the methods by which synthetic hormones are administered, with innovation focusing on improving patient compliance and therapeutic efficacy.
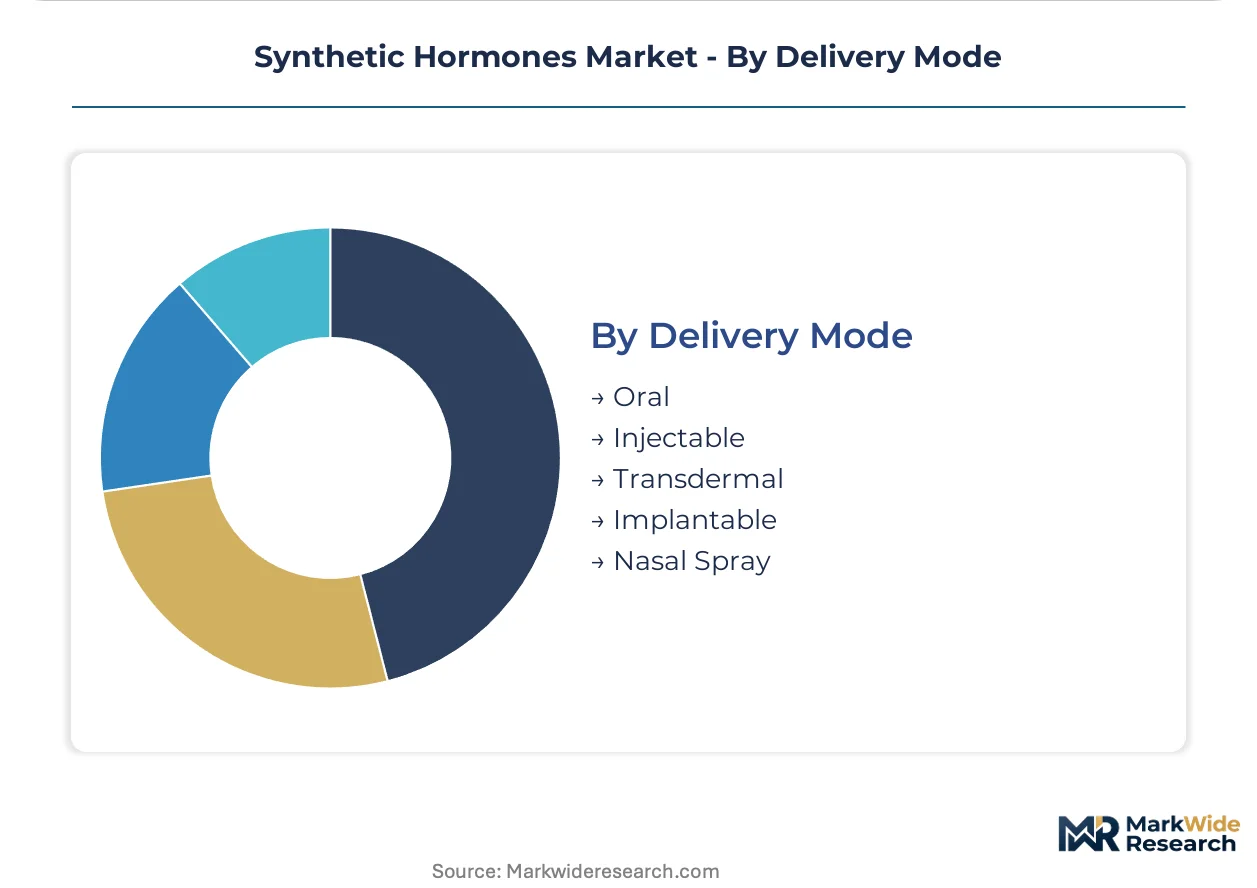
- Injectable:This mode includes traditional injections and advanced long-acting injectables, crucial for protein-based hormones like insulin and GLP-1 agonists, improving adherence. These formulations are critical for chronic disease management, particularly in Europe and the United States.
- Implantable:Subcutaneous implants offer sustained hormone release over extended periods, providing consistent dosing and enhancing patient convenience, especially in contraception and hormone replacement. These systems improve patient compliance.
- Oral:Traditional oral tablets and capsules remain a common and convenient delivery method for many synthetic hormones, particularly for established, small-molecule products.
- Transdermal:Patches and gels deliver hormones through the skin, bypassing first-pass metabolism and offering a non-invasive option for therapies like estrogen replacement.
- Nasal Spray:This delivery route provides rapid absorption for certain hormones, offering an alternative for patients who prefer not to use injections or oral medications.
Established delivery through Oral methods remains foundational, while Injectable delivery modes offer enhanced patient adherence and therapeutic outcomes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors significant innovation and production capacity for synthetic hormones. Developed economies, particularly in Europe and Asia, also drive substantial demand for advanced hormone therapies. These regions possess the necessary healthcare infrastructure and regulatory frameworks to support complex pharmaceutical markets.
United States
Demand for hormone replacement therapies and oncology treatments drives the market in the United States. The U.S. FDA mandates extensive clinical trials, influencing product development timelines. Biotech clusters in Boston and the San Francisco Bay Area lead research and manufacturing for novel biologic hormones.
Germany
Germany's aging demographics and high prevalence of metabolic diseases generate steady demand for synthetic hormones. The European Medicines Agency (EMA) sets rigorous approval standards for new pharmaceutical products within the country. Pharmaceutical manufacturing and R&D activities concentrate in regions like Bavaria and North Rhine-Westphalia.
Japan
Japan exhibits high demand for endocrine disorder treatments and a strong focus on personalized medicine approaches. The PMDA's stringent approval processes govern market access for synthetic hormone products. Major pharmaceutical R&D and manufacturing hubs are located in the Tokyo metropolitan area.
China
China's rising chronic disease burden and expanding healthcare access contribute significantly to the synthetic hormones market. The NMPA regulates the development and commercialization of pharmaceutical products across the country. Biopharmaceutical development is rapidly advancing in cities like Shanghai and Beijing.
India
India presents a growing patient population for hormone therapies and serves as a significant hub for biosimilar manufacturing. The CDSCO oversees pharmaceutical product approvals and quality standards. Pharmaceutical production facilities are concentrated in states such as Telangana and Maharashtra.
Synthetic Hormones Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized biologic-based hormone therapies. The market structure exhibits a dual nature, with high-volume commoditized segments coexisting with technically complex, high-growth areas. Large diversified pharmaceutical firms, specialized biopharmaceutical companies, and biosimilar developers form the primary strategic archetypes. Portfolio diversification into advanced delivery systems and strategic acquisitions of novel technology platforms represent dominant competitive moves.
Within the specialized biologic-based hormone segment, Novo Nordisk A/S exemplifies leadership in metabolic diseases, particularly with its synthetic insulins and GLP-1 agonists. This company's focus underscores the value of proprietary biologic development for chronic conditions. Pfizer Inc. represents a diversified pharmaceutical firm leveraging an extensive pipeline for oncology-related hormonal therapies, demonstrating how established players integrate complex biologics into broader portfolios. Eli Lilly also occupies a significant position in the metabolic disease space, focusing on innovative diabetes treatments and contributing to the competitive dynamics of advanced hormone therapies. These companies anchor innovation and commercialization efforts in their respective therapeutic areas, driving advancements in patient care.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Roche |
| Pfizer Inc. |
| Sanofi SA |
| Merck & Co., Inc. |
| Novo Nordisk A/S |
| Eli Lilly |
| AbbVie Inc. |
| AstraZeneca PLC |
| Others |
Cost & Logistics Intelligence
The pronounced bifurcation between commoditized synthetic hormones and complex biologic-based therapies drives distinct pricing models and supply chain configurations. This structural split demands different capital investments and commercial strategies.
Pricing Analysis
After-sales patient support programs often bundle with premium biologic hormone therapies, while commoditized segments offer per-unit transactional pricing. A hybrid model applies, with value-based pricing for novel biologics and contract-based long-term agreements for established products. Regulatory approval tier and manufacturing complexity drive price differentiation. Pricing softness stems from biosimilar competition for off-patent biologics, impacting high-volume segments where government payers exhibit high price sensitivity.
Supply Chain Analysis
Domestic content mandates in regions like India and China are reshaping sourcing for basic synthetic hormone APIs, while complex biologic production concentrates in the United States and Europe. The supply chain relies on specialized raw materials, including recombinant DNA technology inputs and advanced cell culture media. Single-source vulnerability for proprietary biologics represents a structural risk. Distribution runs through retail pharmacies for high-volume products and specialized clinics for advanced therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The synthetic hormones market is fundamentally a cost-of-compliance story, where stringent regulatory hurdles from agencies like the U.S. FDA and EMA create a significant barrier-to-entry moat for compliant manufacturers. This regulatory environment favors players capable of extensive clinical trials.
For Market Incumbents: Anticipate biosimilar competition by accelerating R&D into next-generation long-acting biologics and advanced delivery systems. Incumbents should strengthen channel control for specialized therapies and invest in manufacturing capacity for complex protein-based hormones in key regions. Diversification into personalized hormone therapies can mitigate margin pressure from commoditized segments.
For New Entrants and Emerging Players: Price-point gaps between premium branded biologics and economy generics offer opportunities for new entrants. Focus on biosimilar development for off-patent synthetic insulins and growth factors, leveraging established regulatory pathways like the EMA's. Target underpenetrated emerging markets in Southeast Asia with cost-effective, high-volume hormone replacement therapies. Strategic partnerships with local healthcare providers facilitate market penetration.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized biopharmaceutical companies focused on complex biologic hormone development given their innovation and high regulatory barriers to entry. Acquisition targets should include firms possessing advanced long-acting delivery platforms or novel genomic-based hormone therapies. Long-term viability favors companies with robust patent portfolios and diversified pipelines. The signal to watch is successful Phase 3 clinical trial readouts for targeted oncology hormone treatments.
| Strategic Initiative | Industry Significance |
|---|---|
| Pipeline Diversification | Reduces reliance on single therapeutic areas and mitigates patent expiration risks. |
| Advanced Delivery System Investment | Improves patient compliance and expands market access for chronic conditions. |
| Contract Manufacturing Partnerships | Optimizes capital allocation and leverages specialized bioprocessing expertise. |
| Biosimilar Portfolio Expansion | Captures market share from off-patent biologics, stimulating price competition. |
| Genomic-Based Therapy R&D | Enables highly personalized treatments for specific patient populations. |
Research Approach
Document review covered FDA filings, EMA submissions, clinical trial registries, and pharmaceutical company annual reports, complemented by interviews with regulatory affairs leads, endocrinologists, and hospital procurement managers. This approach combined primary insights with secondary validation. Bottom-up and top-down triangulation ensured comprehensive data coverage across all market segments.
Historical market performance was cross-referenced with expert panel input to project future trends across the analysis window. Segmentation dimensions modeled included product type, therapy area, end-user, and delivery mode. Compound Annual Growth Rates were derived from a multi-variable regression analysis. Key forecast inputs included disease prevalence rates for metabolic conditions and regulatory approval timelines for novel biologics.
Inputs from public financial disclosures and regulatory databases were available through the study window; gaps in real-time pricing data for emerging markets introduce uncertainty bands. Forecasts reflect assumptions regarding future regulatory changes and technological advancements in drug delivery. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Biology
Gene Synthesis (Research Use) Market
Synthetic Biology
Synthetic Genomics Market
Synthetic Biology
Mutation Generation Systems Market
Synthetic Biology
Transient Protein Expression Market
Synthetic Biology
Global Cell-Free Protein Expression Market
Synthetic Biology
Synthetic Stem Cells Market
Synthetic Biology
DNA Synthesizer Market
Synthetic Biology
Asia-Pacific Gene Synthesis Market
Synthetic Biology
Difficult-To-Express Proteins Market