
 Synthetic Genomics Market | 2026-2036
Synthetic Genomics Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Genomics Market Analytics
The gap between premium gene synthesis services and commodity oligo production is broadening. Thermo Fisher Scientific leverages its integrated instrument-reagent workflow to dominate high-throughput research segments. Amyris sustains cost leadership in microbial strain engineering for industrial biotechnology applications. Twist Bioscience differentiates through silicon-based DNA synthesis platforms that compress turnaround times for complex constructs.
Synthetic genomics encompasses the design, assembly, and modification of genetic material using chemically synthesized DNA fragments with error rates below one per ten thousand base pairs, enabling programmable biological systems for therapeutic protein production and metabolic engineering. Gene editing tools command premium pricing due to CRISPR licensing complexity and guide RNA optimization requirements. Synthetic DNA segments anchor volume demand as declining per-base costs expand accessibility to smaller research institutions. Biotechnology applications lead value generation, while agricultural end users represent an emerging demand pool for trait-stacked crop development.
The FDA and EMA govern gene therapy investigational new drug pathways, with the FDA's Chemistry, Manufacturing, and Controls guidance dictating synthetic DNA purity thresholds for clinical-grade materials. The EPA oversees microbial containment standards for environmental release of engineered organisms in agricultural trials. Stakeholders must monitor evolving gene synthesis screening protocols under the Wassenaar Arrangement and national biosecurity frameworks that govern dual-use sequence orders.
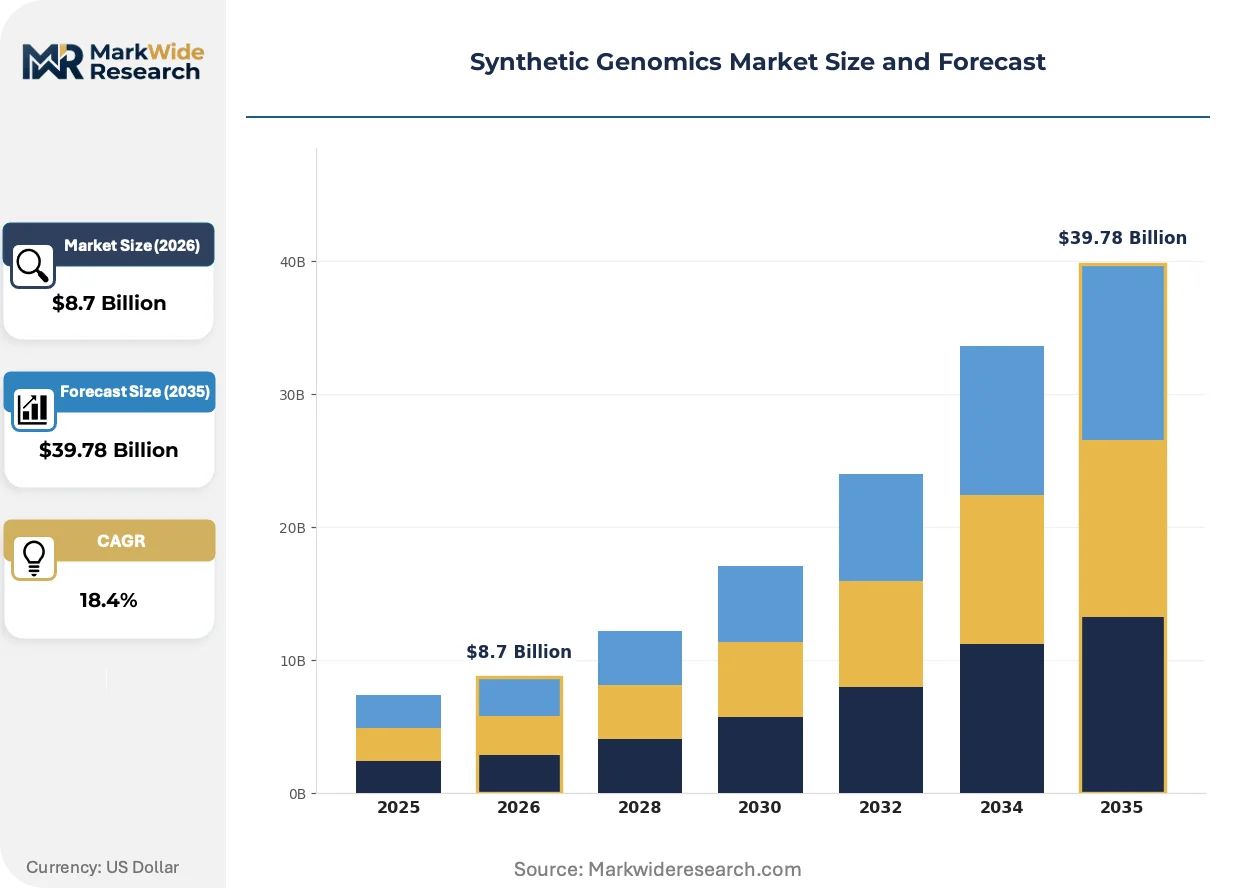
Market Dynamics
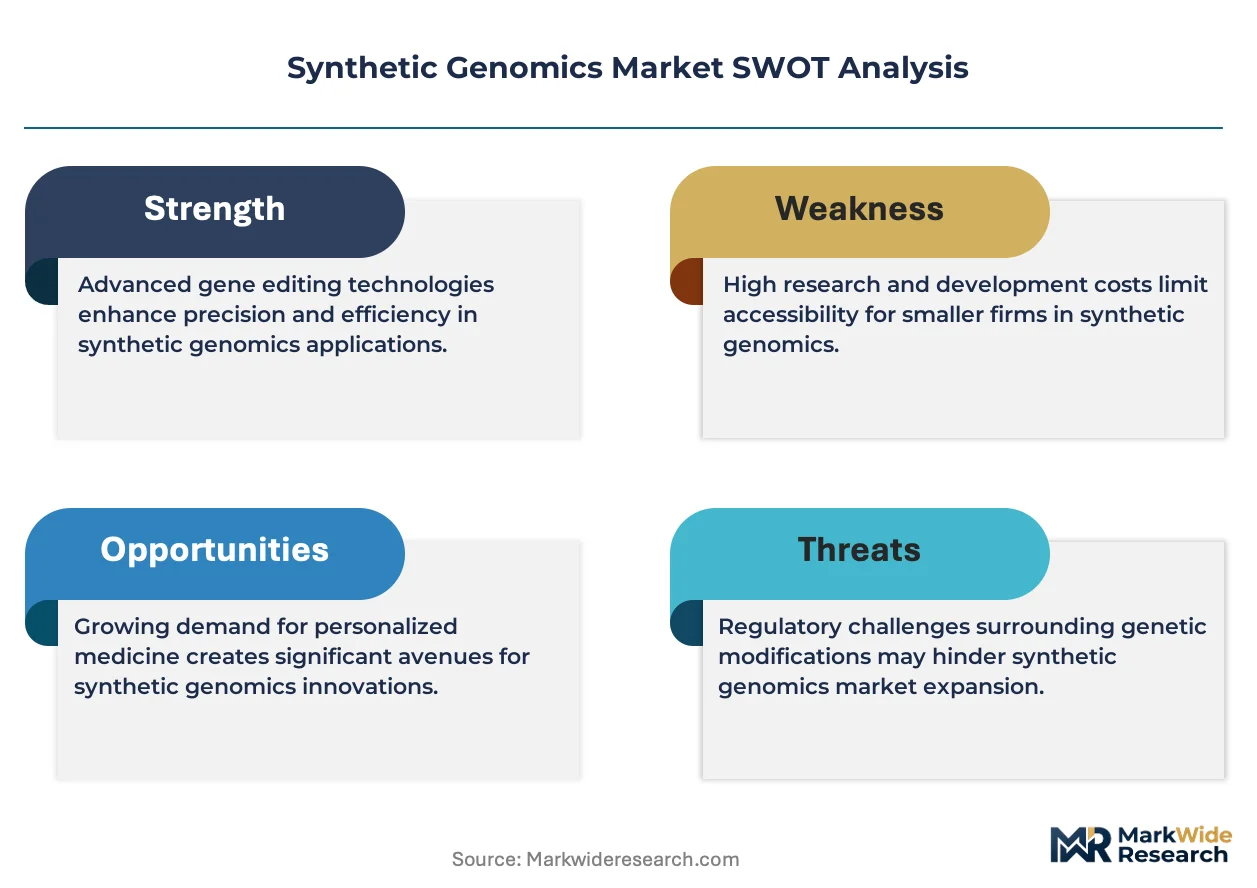
CRISPR licensing complexity and guide RNA optimization requirements are compressing margins for therapeutic developers while concentrating purchasing power among vertically integrated pharmaceutical conglomerates that can absorb regulatory compliance costs.
Growth Catalysts
- Gene therapy pipeline expansion:Pharmaceutical developers are scaling investigational new drug submissions for inherited disorders, creating sustained demand for clinical-grade synthetic DNA with purity thresholds exceeding 99.9 percent.
- EPA microbial containment standards:Clearer environmental release protocols for engineered organisms in agricultural trials are accelerating field testing timelines for trait-stacked crop programs.
- Boston-San Francisco biotech corridor concentration:Venture deployment into synthetic biology startups within these clusters is generating captive demand for local gene synthesis services and specialized reagent supply chains.
Market Restraints
- Phosphoramidite cost volatility:Raw material supply for solid-phase DNA synthesis fluctuates with specialty chemical feedstock pricing, compressing margins for commoditized oligo producers.
- Dual-use screening protocols:Wassenaar Arrangement compliance requirements and national biosecurity frameworks impose order-review delays on pathogenic sequence requests, extending fulfillment timelines.
- Error rate limitations in long constructs:Current enzymatic assembly methods struggle to maintain fidelity beyond 10,000 base pairs without costly verification steps, restricting accessible project scales for smaller research institutions.
Strategic Opportunities
- Industrial biotechnology strain engineering:Microbial production platforms for bio-based chemicals and sustainable materials represent underpenetrated demand beyond pharmaceutical applications.
- EU Green Deal bioeconomy incentives:Regulatory frameworks promoting renewable feedstock substitution are creating procurement mandates favoring engineered microbial production systems.
- AI-driven sequence optimization:Machine learning tools for codon optimization and pathway design are converging with automated synthesis platforms to compress development cycles for complex metabolic engineering projects.
Industry Challenges
- CRISPR licensing fragmentation:Multiple competing intellectual property estates create negotiation complexity for therapeutic developers seeking freedom to operate across guide RNA designs and delivery modalities.
- Specialized technician scarcity:Molecular biology automation and quality control for clinical-grade materials require hybrid skill sets combining synthetic chemistry expertise with regulatory documentation experience that outpaces training pipeline output.
- ISO 13485 certification timelines:Medical device quality management system implementation for synthetic DNA used in diagnostic applications extends commercialization pathways by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Genomics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic DNA, Synthetic RNA, Gene Editing Tools, Cloning Vectors Application: Biotechnology, Agriculture, Pharmaceuticals, Industrial Biotechnology End User: Research Institutions, Pharmaceutical Companies, Agrochemical Corporations, Contract Research Organizations Technology: CRISPR, Synthetic Biology Platforms, Gene Synthesis Technologies, Sequencing Solutions |
| Companies Covered | Thermo Fisher Scientific, Amyris, Ginkgo Bioworks, Oxford Nanopore Technologies, Synthetic Genomics, Twist Bioscience, Genscript, Integrated DNA Technologies, Illumina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Genomics Market Evolving Landscape
Silicon-based DNA synthesis platforms are compressing turnaround times while enzymatic methods challenge phosphoramidite chemistry on cost curves. Regulatory clarity on gene editing is reshaping clinical trial design. Procurement patterns are fragmenting as distributed research institutions gain access to previously enterprise-grade capabilities.
Enzymatic DNA synthesis is expanding into applications previously dominated by chemical phosphoramidite methods, particularly for sequences with complex secondary structures or modified bases. Mid-sized contract research organizations are adopting benchtop enzymatic systems to bypass centralized service provider queues. This technology is expanding into same-day synthesis workflows for iterative design-build-test cycles in metabolic engineering programs.
FDA Chemistry, Manufacturing, and Controls guidance is mandating synthetic DNA purity thresholds for clinical-grade materials that exceed research-grade specifications by an order of magnitude. Investigational new drug sponsors must now document endotoxin levels, residual solvent content, and sequence verification methodology to pre-IND submission standards. Cell and gene therapy developers in the United States are responding by qualifying dedicated supply chains with audit rights and change-control protocols.
Research institutions are unbundling after-sales service from instrument-reagent contracts, negotiating separate agreements for application support and maintenance. This pattern is displacing bundled enterprise agreements that previously locked buyers into single-vendor workflows. The shift is most visible among European academic consortia pursuing open-source automation platforms to reduce dependency on integrated proprietary systems.
Synthetic Genomics Market Segmentation
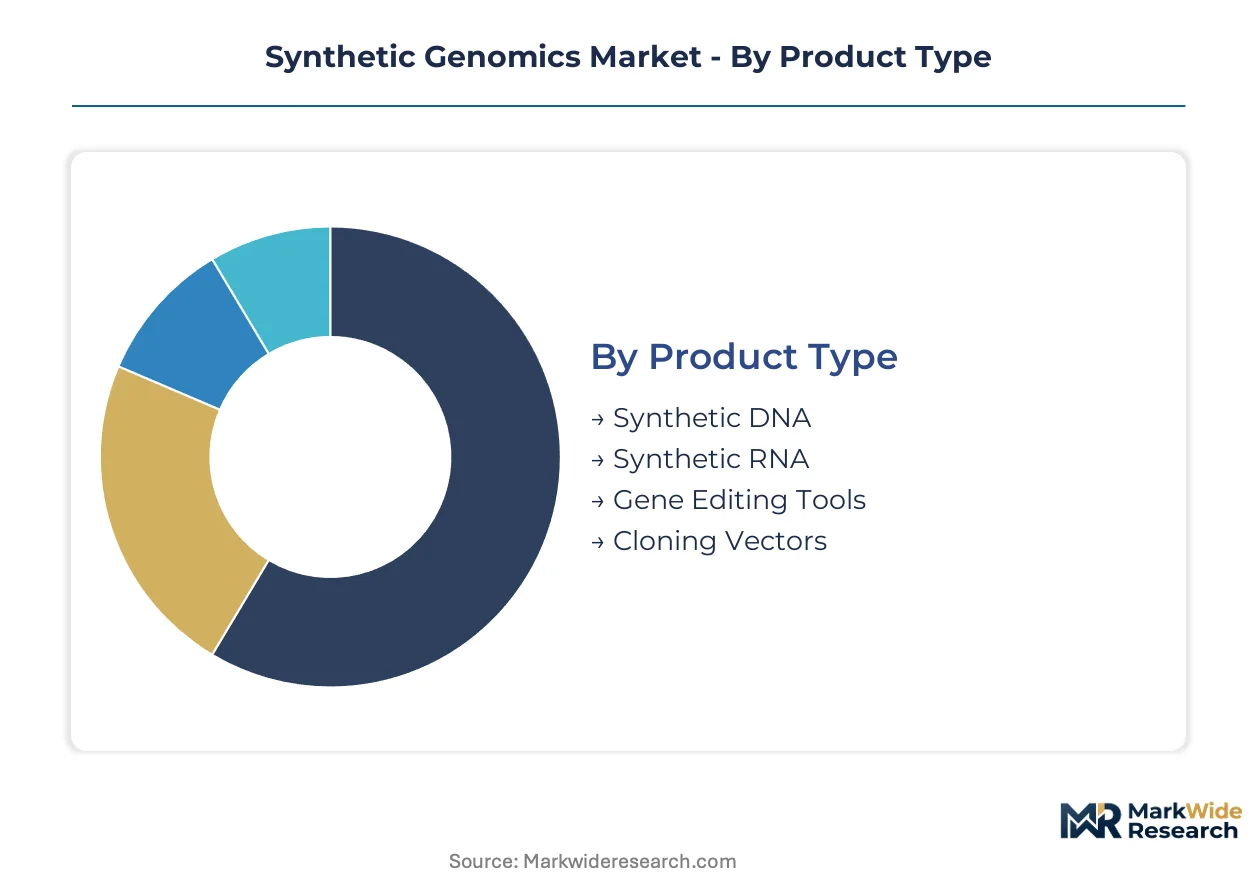
Synthetic genomics markets fragment across technology generations, with phosphoramidite chemistry facing displacement from enzymatic methods and silicon-based platforms. Upgrade cycles accelerate as research institutions unbundle legacy instrument-reagent contracts. Each segment carries distinct purity thresholds, regulatory pathways, and customer procurement patterns.
Product Type:
Replacement cycles favor modular synthesis platforms over fixed-capacity instruments, compressing obsolescence timelines from seven years to four.
- Synthetic DNA:Chemically synthesized oligonucleotides with error rates below one per ten thousand base pairs anchor volume demand. Research institutions in the United States biotech corridor drive consumption as declining per-base costs expand accessibility beyond pharmaceutical conglomerates.
- Gene Editing Tools:CRISPR-Cas systems and guide RNA reagents command premium pricing due to licensing complexity and optimization requirements. Therapeutic developers absorb these costs while smaller institutions face access barriers.
- Synthetic RNA:Modified nucleotide chemistries for mRNA therapeutics and vaccine applications require specialized manufacturing capabilities.
- Cloning Vectors:Plasmid backbones and viral delivery systems support gene therapy manufacturing workflows.
Volume placements concentrate in Synthetic DNA; the faster expansion belongs to Gene Editing Tools.
Application:
Cost tiers separate clinical-grade materials from research-grade specifications, with purity thresholds dictating pricing multiples.
- Biotechnology:Metabolic engineering and therapeutic protein production lead value generation through programmable biological systems. Strain engineering for bio-based chemicals creates procurement mandates under EU Green Deal frameworks.
- Pharmaceuticals:Gene therapy pipelines scale investigational new drug submissions for inherited disorders. FDA Chemistry, Manufacturing, and Controls guidance mandates synthetic DNA purity exceeding research-grade specifications by an order of magnitude.
- Industrial Biotechnology:Microbial production platforms for sustainable materials represent underpenetrated demand beyond pharmaceutical applications.
- Agriculture:Trait-stacked crop development programs accelerate field testing timelines under clarified EPA microbial containment standards.
Biotechnology captures the largest share of current placements; Pharmaceuticals is climbing the fastest as regulatory clarity reshapes clinical trial design.
End User:
Customer sophistication determines service tier access, with ISO 13485 certification requirements filtering smaller buyers from clinical-grade supply chains.
- Research Institutions:Distributed academic consortia negotiate unbundled service agreements, displacing bundled enterprise contracts. European clusters pursue open-source automation platforms to reduce dependency on integrated proprietary systems.
- Pharmaceutical Companies:Vertically integrated conglomerates absorb CRISPR licensing costs and regulatory compliance burdens. These buyers qualify dedicated supply chains with audit rights and change-control protocols.
- Contract Research Organizations:Mid-sized CROs adopt benchtop enzymatic synthesis systems to bypass centralized service provider queues.
- Agrochemical Corporations:Field trial sponsors navigate EPA environmental release protocols for engineered organisms.
Research Institutions dominate placement volumes; Contract Research Organizations are gaining share fastest through automation adoption.
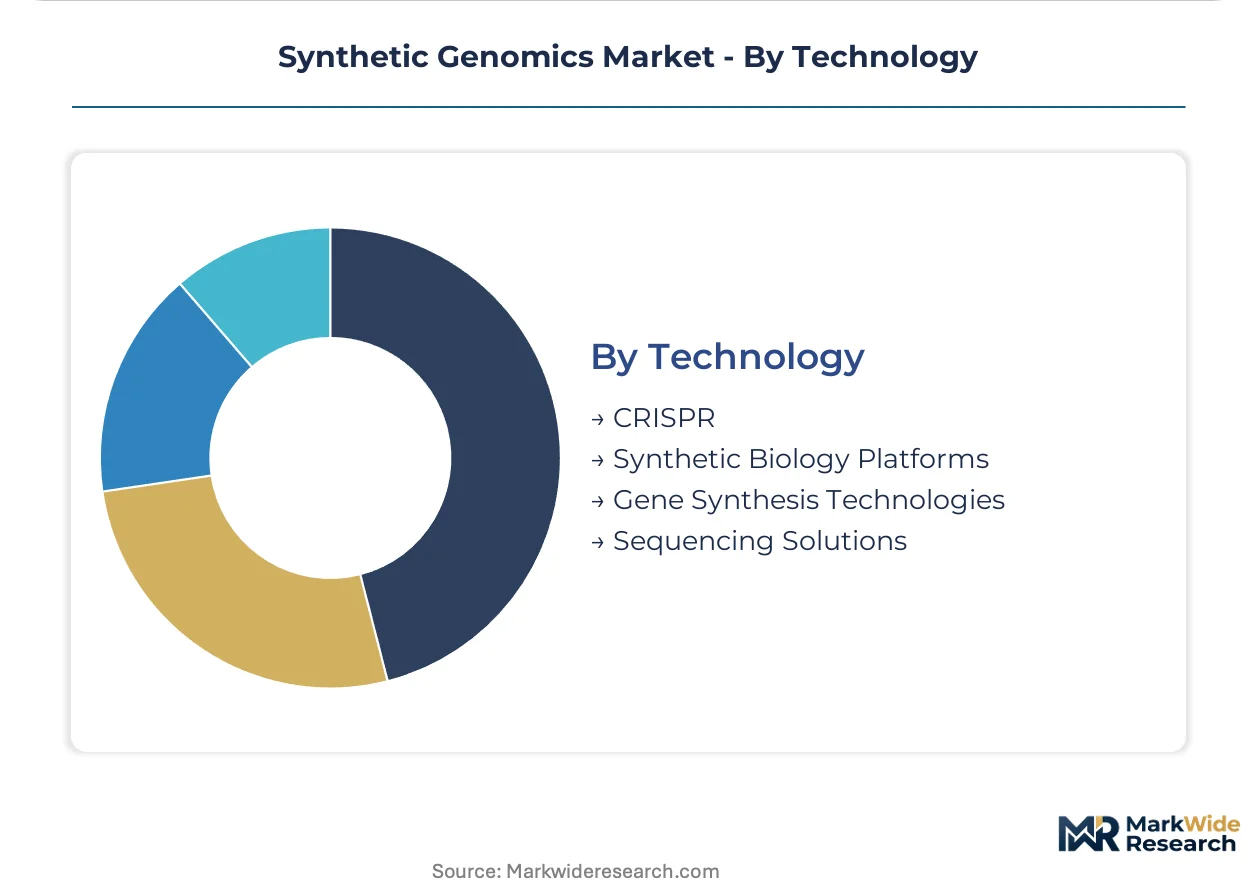
Technology:
Margin structures favor platforms combining hardware, consumables, and software over standalone reagent sales.
- Gene Synthesis Technologies:Silicon-based DNA synthesis platforms compress turnaround times for complex constructs. Solid-phase phosphoramidite chemistry faces cost pressure from enzymatic alternatives.
- CRISPR:Multiple competing intellectual property estates create negotiation complexity for therapeutic developers seeking freedom to operate. Licensing fragmentation concentrates purchasing power among buyers with legal resources.
- Synthetic Biology Platforms:Integrated design-build-test automation supports iterative metabolic engineering cycles.
- Sequencing Solutions:Verification workflows for long constructs require hybridization with synthesis platforms.
Gene Synthesis Technologies anchor current placements; CRISPR shows the steepest expansion trajectory as regulatory frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-San Francisco biotech corridor anchors synthetic genomics demand through concentrated venture deployment and specialized reagent supply chains. Pharmaceutical developers and research institutions within these clusters generate captive demand for clinical-grade synthetic DNA and gene editing tools. Regulatory clarity from the FDA is accelerating investigational new drug submissions across inherited disorder programs.
United States
Gene therapy pipeline expansion and CRISPR therapeutic development drive procurement of high-purity synthetic DNA. The FDA's Chemistry, Manufacturing, and Controls guidance mandates purity thresholds exceeding research-grade specifications by an order of magnitude. The Boston-San Francisco corridor concentrates venture-funded synthetic biology startups and specialized service providers.
Germany
Industrial biotechnology applications for bio-based chemicals and sustainable materials create procurement mandates under EU Green Deal frameworks. EMA regulatory pathways for gene therapy investigational new drugs are reshaping clinical trial design across European pharmaceutical developers. The Rhine-Ruhr and Munich clusters host metabolic engineering programs and automated synthesis platform deployments.
United Kingdom
Research institutions negotiate unbundled service agreements, displacing bundled enterprise contracts previously dominated by integrated vendors. MHRA alignment with FDA gene therapy guidance is streamlining investigational new drug pathways for synthetic DNA-based therapeutics. The Cambridge-London corridor concentrates CRISPR research programs and specialized reagent distribution networks.
China
Declining per-base synthesis costs are expanding accessibility to distributed research institutions beyond pharmaceutical conglomerates. NMPA regulatory frameworks for gene editing therapeutics are maturing, creating clarity for clinical-grade material sourcing. The Yangtze River Delta and Beijing-Tianjin-Hebei regions concentrate synthetic biology startups and domestic gene synthesis service providers.
Switzerland
Precision fermentation and microbial strain engineering programs drive demand for complex synthetic constructs and verification workflows. Swissmedic oversight of gene therapy manufacturing standards is dictating supply chain qualification requirements for clinical-grade materials. The Basel-Zurich corridor anchors pharmaceutical conglomerate R&D operations and specialized biotechnology service providers.
Synthetic Genomics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purity-grade and regulatory-certification dimensions. The market structures around three tiers: integrated instrument-reagent workflow providers, specialized gene synthesis service platforms, and commodity oligonucleotide producers. Strategic archetypes include vertically integrated pharmaceutical conglomerates with captive supply chains, silicon-based synthesis platform specialists, and enzymatic method challengers. Dominant competitive moves encompass supply chain qualification with audit rights and change-control protocols, plus automation platform deployments to compress turnaround times.
Within the integrated workflow tier, Thermo Fisher Scientific anchors instrument-reagent bundling strategies. Twist Bioscience and Ginkgo Bioworks occupy positions as platform-centric specialists, with the former exemplifying silicon-based synthesis acceleration and the latter representing design-build-test automation for metabolic engineering. These three entities collectively illustrate the competitive tension between hardware-software integration and specialized service models.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Amyris |
| Ginkgo Bioworks |
| Oxford Nanopore Technologies |
| Synthetic Genomics |
| Twist Bioscience |
| Genscript |
| Integrated DNA Technologies |
| Illumina |
| Others |
Value Network & Pricing Analysis
Phosphoramidite feedstock pricing volatility cascades through solid-phase DNA synthesis supply chains, compressing margins for commoditized oligo producers while concentrating pricing power among integrated instrument-reagent providers that absorb input cost swings through captive chemical manufacturing.
Pricing Analysis
Throughput-based pricing anchors gene synthesis contracts, with silicon-platform providers commanding premiums for same-day turnaround on complex constructs exceeding ten thousand base pairs. Pricing stratifies across clinical-grade, research-grade, and commodity-grade purity tiers, with FDA Chemistry, Manufacturing, and Controls certification adding order-of-magnitude multiples. Cost compression in phosphoramidite-based oligo production is intensifying because enzymatic synthesis challengers bypass specialty chemical feedstock dependencies. Contract research organizations exhibit highest price sensitivity, while vertically integrated pharmaceutical conglomerates prioritize supply security over unit economics.
Supply Chain Analysis
Refurbishment flows for synthesis instruments concentrate in the United States, Germany, and Switzerland, where specialized service providers extend platform lifecycles for research institutions seeking to defer capital replacement. Raw material dependencies center on phosphoramidite chemistries from specialty chemical producers, silicon wafers for semiconductor-based synthesis chips, and modified nucleotide building blocks for mRNA applications. Single-source vulnerability in phosphoramidite precursor manufacturing creates exposure to feedstock price shocks. Distribution runs through direct instrument-reagent contracts with pharmaceutical developers and unbundled service agreements with academic consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The synthetic genomics market functions as a cost-of-compliance arena where FDA Chemistry, Manufacturing, and Controls guidance erects barrier-to-entry moats favoring players with established clinical-grade certification infrastructure.
For Market Incumbents: Deepen backward integration into phosphoramidite precursor manufacturing to neutralize feedstock price volatility threatening commoditized oligo margins. Fortify ISO 13485-certified production capacity in the Boston-San Francisco corridor to capture gene therapy pipeline expansion demand. Enzymatic synthesis challengers threaten solid-phase chemistry incumbents; defend through same-day turnaround guarantees and locked-in reagent supply contracts. For New Entrants and Emerging Players: Contract research organizations represent the most penetrable channel partner type for benchtop enzymatic synthesis platforms, bypassing centralized service queues that constrain iterative metabolic engineering cycles. Target industrial biotechnology strain engineering programs in Germany's Rhine-Ruhr cluster, where EU Green Deal procurement mandates favor engineered microbial production systems. Pursue open-source automation partnerships with European academic consortia seeking to reduce proprietary system dependency. For Investors and Strategic Acquirers: Distressed-cycle entries favor platform-centric specialists with silicon-based synthesis capabilities in the United States, where venture deployment into synthetic biology startups generates captive demand for accelerated turnaround services. Long-term viability over the next decade hinges on regulatory certification moats rather than raw technology differentiation. Monitor EPA microbial containment standard clarifications as the inflection signal for agricultural trait-stacked crop program acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical-Grade Supply Chain Qualification | FDA Chemistry, Manufacturing, and Controls compliance mandates audit rights and change-control protocols for gene therapy sponsors. |
| Silicon-Based Synthesis Platform Deployment | Twist Bioscience's semiconductor manufacturing approach compresses turnaround times for complex constructs beyond ten thousand base pairs. |
| Enzymatic Method Manufacturing Scale-Up | Bypassing phosphoramidite chemistry reduces dependency on volatile specialty chemical feedstock pricing. |
| EU Green Deal Bioeconomy Alignment | Regulatory frameworks in Germany and Switzerland mandate renewable feedstock substitution favoring engineered microbial systems. |
| CRISPR Licensing Portfolio Consolidation | Fragmented intellectual property estates create negotiation complexity requiring legal resources concentrated among pharmaceutical conglomerates. |
Research Methodology
SEC 10-K filings, FDA Chemistry, Manufacturing, and Controls guidance documents, and EMA gene therapy investigational new drug submissions formed the secondary backbone for market sizing and regulatory pathway mapping. Primary interviews with gene therapy development executives, regulatory affairs leads at pharmaceutical sponsors, synthetic biology platform engineers, and contract research organization procurement managers validated demand assumptions and pricing dynamics. Bottom-up segment modeling triangulated against top-down venture deployment tracking across the Boston-San Francisco and Cambridge-London biotech corridors.
Historical trendline analysis of gene synthesis order volumes and purity-grade pricing trajectories informed projection frameworks across the analysis window. Segmentation dimensions encompassed product type, application vertical, end-user sophistication tier, and technology generation, with regulatory certification status serving as a cross-cutting price-elasticity modifier. CAGRs derived from weighted average of technology adoption curves and pipeline-stage gene therapy program counts. Forecast inputs included CRISPR therapeutic development timelines and EPA environmental release protocol evolution for agricultural applications.
Caveats apply where Wassenaar Arrangement screening protocol revisions or national biosecurity framework tightening could materially shift the outlook for pathogenic sequence order fulfillment timelines. Practitioners should monitor NMPA regulatory framework maturation in China and dual-use sequence screening automation advances for early signals of supply chain access restriction or relaxation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Biology
Mutation Generation Systems Market
Synthetic Biology
Asia-Pacific Gene Synthesis Market
Synthetic Biology
Transient Protein Expression Market
Synthetic Biology
Synthetic Hormones Market
Synthetic Biology
DNA Synthesizer Market
Synthetic Biology
Gene Synthesis (Research Use) Market
Synthetic Biology
Synthetic Stem Cells Market
Synthetic Biology
Global Cell-Free Protein Expression Market
Synthetic Biology
Difficult-To-Express Proteins Market